
 Pearlizers Market | 2026-2036
Pearlizers Market Size, Share, and Industry Trends Forecast 2026-2036
Pearlizers Market Analytics
Premium cosmetics brands are bifurcating from mass-market buyers as the dominant procurement archetype in pearlizers. Specialty formulators now command priority allocation from advanced material suppliers. BASF SE leverages its integrated pigment chemistry portfolio to serve tier-one personal care houses. Merck KGaA anchors high-performance effect pigment supply through proprietary substrate coating technology. Fujian Kuncai Fine Chemicals Co., Ltd. competes on manufacturing scale for domestic and export powder grades.
Pearlizers are nacreous pigments, typically mica substrates coated with titanium dioxide or iron oxide layers at controlled thicknesses, engineered to produce interference colors and luster effects in finished goods. These materials function primarily to impart visual depth, opacity modulation, and sensory differentiation in cosmetics, coatings, and thermoplastic applications. Liquid pearlizer formulations dominate volume consumption in cosmetics due to ease of cold-process incorporation, while powder grades command margin concentration in automotive and industrial coating segments where durability specifications are stringent. The plastics application channel represents the fastest-expanding structural opportunity as masterbatch compounders adopt pearlized effects for consumer electronics housings and premium packaging.
REACH registration requirements in Europe, FDA color additive regulations in the United States, and China's GB standards for cosmetic raw materials collectively govern pearlizer market access and compositional compliance. ECHA substance evaluation protocols are tightening trace metal thresholds in mica-derived pigments, forcing reformulation investments across supplier bases. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that constrains multi-region product registration strategies.
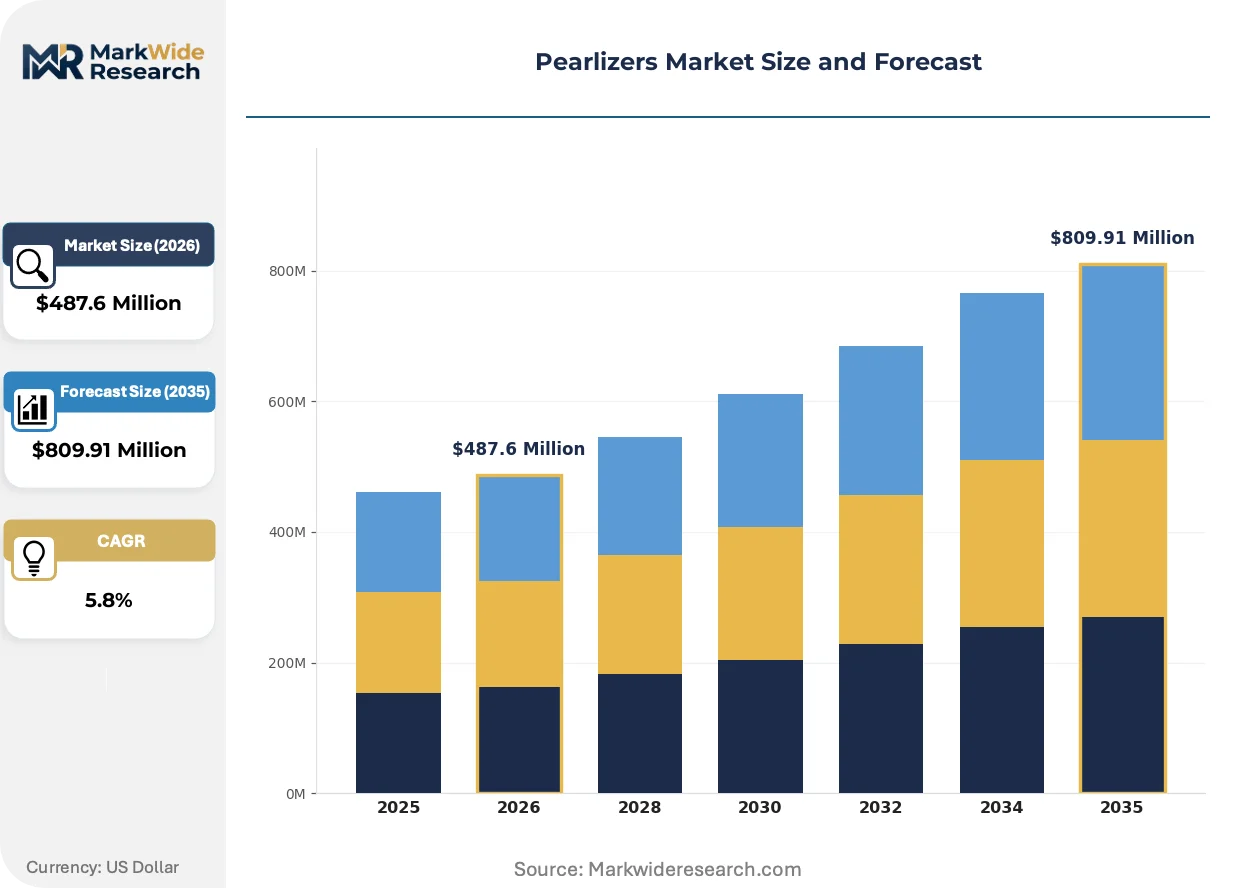
Market Dynamics
REACH substance evaluation protocols are tightening trace metal thresholds in mica-derived pigments, forcing reformulation investments and supplier consolidation across European pearlizer value chains.
Growth Catalysts
- Clean-beauty ingredient disclosure mandates:ECHA and FDA parallel enforcement drives specialty cosmetics formulators toward certified pearlizer grades with full supply chain transparency.
- China's domestic brand scaling:Local personal care houses in Shanghai and Guangzhou are expanding pearlized product portfolios for Asia-Pacific consumer electronics and premium packaging applications.
- Masterbatch compounder adoption:Thermoplastic processors are integrating interference pigments into consumer electronics housings, creating structural demand pull from compounders serving Apple and Samsung supply chains.
Market Restraints
- Mica supply concentration:Overreliance on Jharkhand and Madagascar artisanal mining creates ESG audit exposure and volume volatility for substrate-dependent pigment houses.
- Titanium dioxide cost pass-through:TiO2 price spikes from sulfate-process chloride-grade shortages compress margin structures for mid-tier pearlizer blenders.
- Iron oxide interference limitations:Narrower color gamut and lower luster coefficients restrict substitution potential against premium metal oxide systems in automotive coating specifications.
Strategic Opportunities
- India specialty chemical corridors:Gujarat and Maharashtra industrial zones offer tariff-advantaged export platforms for REACH-registered pearlizer production serving European cosmetics houses.
- Synthetic mica substrate convergence:Fluorphlogopite engineered crystals paired with atomic layer deposition enable heavy-metal-free formulations qualifying for clean-beauty premium tiers.
- Direct-to-formulator digital channels:Specialty chemical marketplaces bypass traditional distributor markups for mid-volume cosmetics laboratories seeking rapid sample-to-production scaling.
Industry Challenges
- Multi-jurisdiction registration timelines:Divergent GB standards, FDA color additive petitions, and REACH dossier updates create formulation lock-in risks for global product lines.
- Substrate coating equipment capex:Fluidized bed CVD systems for controlled TiO2 layer deposition require capital commitments that strain mid-cap pigment houses.
- Colorimetric batch consistency:Interference color tolerance tightening by automotive OEMs demands spectrophotometric QA infrastructure beyond legacy visual matching protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearlizers Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Solid Application: Cosmetics, Paints, Inks, Plastics End User: Manufacturers, Retailers, Distributors, Wholesalers Technology: Coating, Mixing, Formulating, Dispersion |
| Companies Covered | BASF SE, Clariant, Lubrizol, Sun Chemical Performance Pigments, Merck KGaA, Huaian Concord Cosmetics Product Co. Ltd. (Kolortek), Fujian Kuncai Fine Chemicals Co., Ltd., Ashland, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearlizers Market Evolving Landscape
Formulation science and regulatory chemistry are converging to redefine pearlizer performance benchmarks, with substrate engineering and compliance architecture now determining competitive access rather than commodity scale alone.
Fluorphlogopite synthetic mica is fragmenting traditional natural mica supply structures by eliminating heavy metal contamination risks while enabling tighter interference layer control. Specialty cosmetics formulators in France and South Korea are accelerating qualification programs for synthetic substrates. The technology is fragmenting procurement patterns as tier-one houses dual-source natural and synthetic grades to mitigate ESG audit exposure.
ECHA's 2024-2026 substance evaluation roadmap for mica-derived pigments is compressing allowable lead and arsenic thresholds by an order of magnitude. Pigment houses with Jharkhand supply dependencies face forced reformulation or captive mine investment. Automotive coating segments in Germany and premium skincare in Italy are most exposed, with BASF and Merck accelerating synthetic substrate capacity expansion.
Buyer concentration among specialty formulators is compressing distributor relevance as direct technical service relationships become the primary channel for complex color-matching support. Mid-volume cosmetics houses in São Paulo and Mexico City now bypass regional distributors for direct mill relationships. This pattern is most visible in Latin America where import tariff engineering favors consolidated procurement from European pigment houses.
Pearlizers Market Segmentation
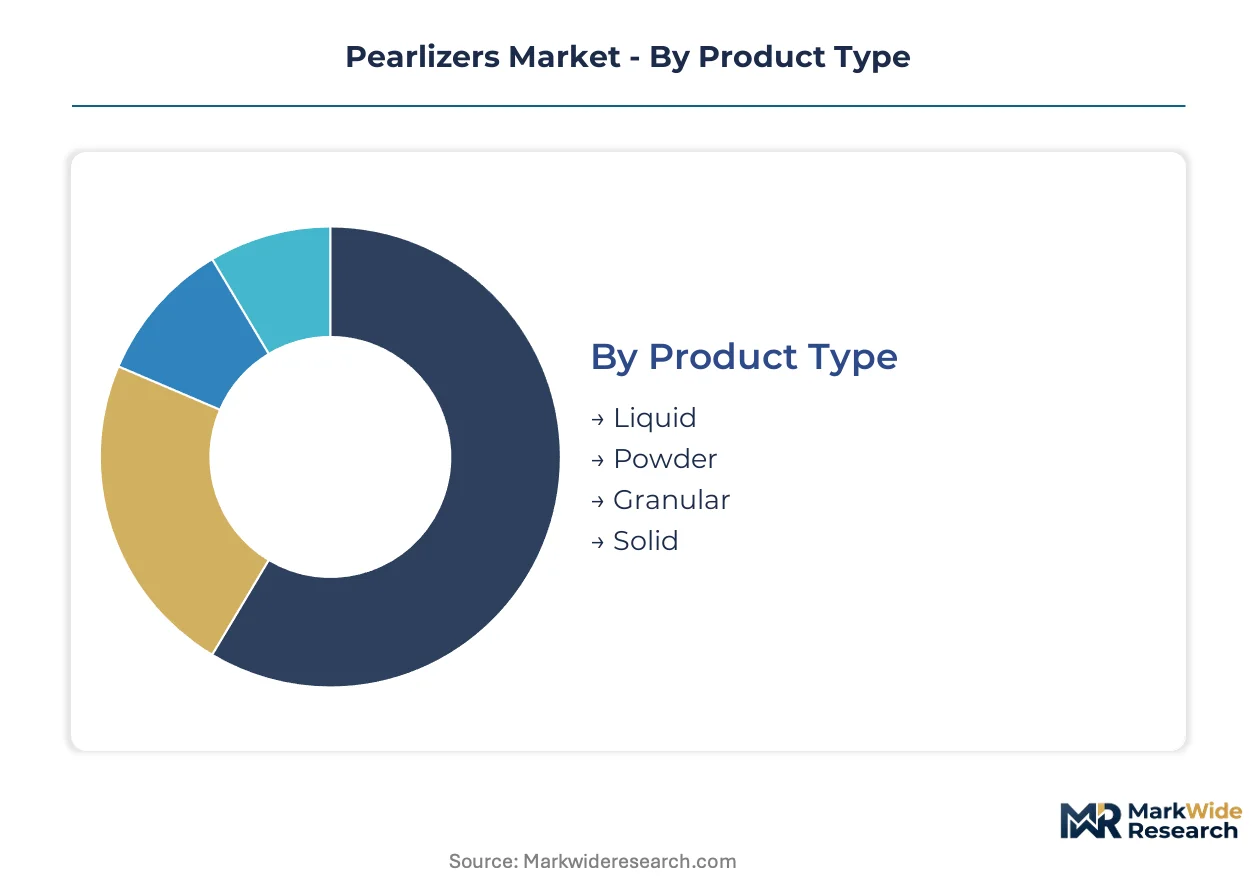
Pearlizer procurement patterns diverge sharply across physical form factors and end-use specifications. Formulators select product types based on process compatibility, while application segments dictate performance thresholds and regulatory compliance burdens.
Product Type:
Margin pools concentrate in powder grades where coating durability specifications command premium pricing, while liquid formulations dominate volume throughput in cosmetics manufacturing.
- Liquid:Cold-process emulsions enable direct incorporation into skincare and color cosmetic formulations without heat activation. Demand concentrates in Shanghai and Guangzhou personal care houses scaling pearlized product lines for Asia-Pacific consumers, though refrigerated logistics add cost complexity for long-haul distribution.
- Powder:Mica substrates with controlled TiO2 deposition thickness deliver interference colors and luster effects for automotive and industrial coatings. German automotive OEMs and Italian premium skincare manufacturers drive qualification programs, with ECHA trace metal thresholds forcing synthetic substrate adoption.
- Granular:Free-flowing agglomerates suit masterbatch compounders serving thermoplastic processors in consumer electronics supply chains.
- Solid:Compressed tablet forms address specialized pharmaceutical and food-grade applications requiring precise dosing control.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
Volume distribution tracks end-use durability requirements and colorimetric precision needs across industrial and consumer segments.
- Cosmetics:Specialty formulators in France and South Korea deploy interference pigments for sensory differentiation in high-end skincare and color cosmetics. REACH registration and clean-beauty disclosure mandates push procurement toward certified grades with full supply chain transparency.
- Plastics:Thermoplastic processors integrate pearlized effects into consumer electronics housings for Apple and Samsung supply chains. Masterbatch compounders represent the steepest expansion trajectory as interference pigments displace conventional colorants in premium packaging.
- Paints:Automotive coating specifications demand spectrophotometric batch consistency beyond legacy visual matching protocols.
- Inks:Narrower color gamut requirements in packaging graphics limit substitution potential against premium metal oxide systems.
Cosmetics commands the margin premium. Plastics is climbing the fastest.
End User:
Procurement authority is concentrating in manufacturers with direct technical service relationships, compressing traditional distributor relevance.
- Manufacturers:Tier-one personal care houses and automotive coating formulators in Germany, Italy, and France negotiate priority allocation through integrated pigment chemistry portfolios. Direct mill relationships bypass regional distributor markups for complex color-matching support.
- Distributors:Mid-volume cosmetics laboratories in São Paulo and Mexico City increasingly source through specialty chemical marketplaces for rapid sample-to-production scaling.
- Retailers:Private-label personal care brands in China domestic markets drive consolidated procurement from European pigment houses.
- Wholesalers:Import tariff engineering in Latin America favors consolidated volume aggregation for regional resale.
Manufacturers hold technical specification authority. Distributors are rotating up the share rankings.
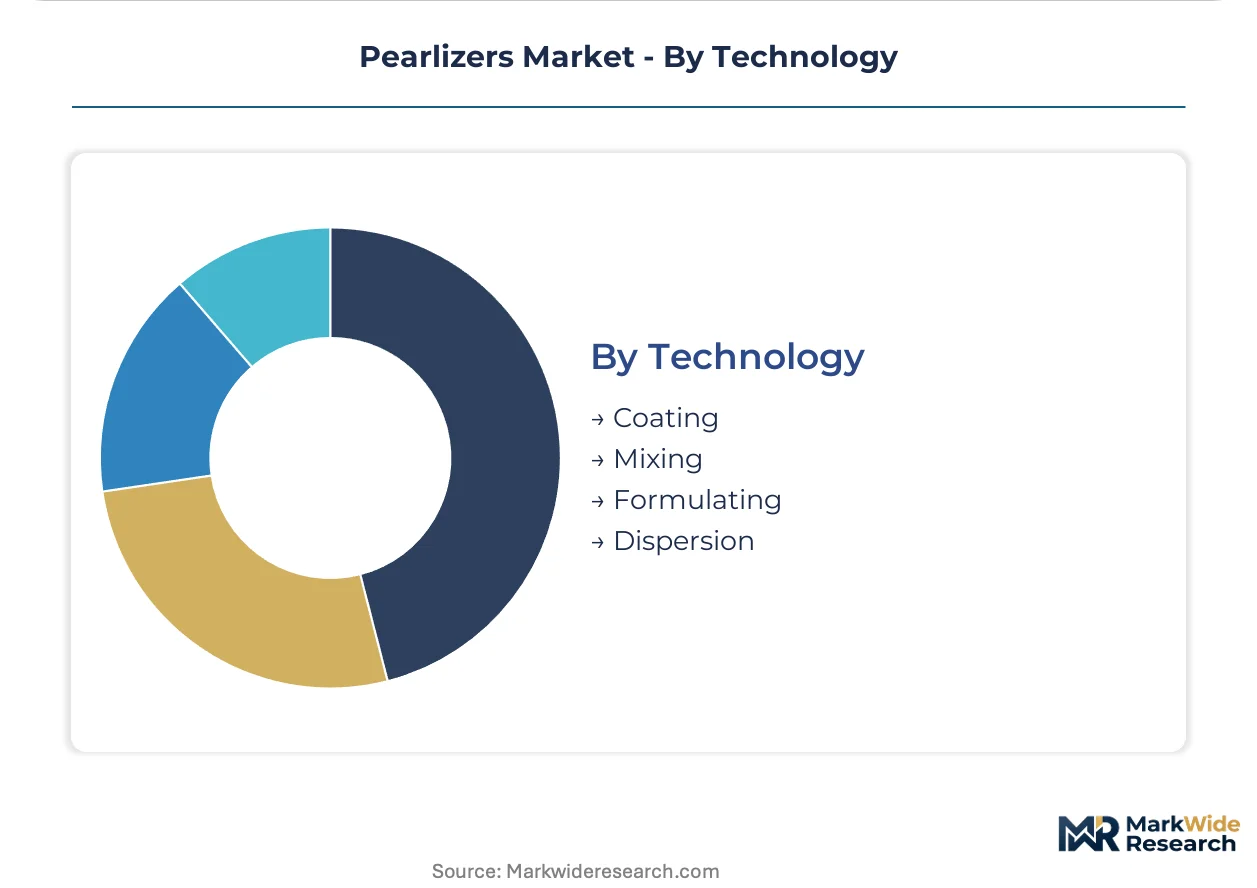
Technology:
Process control capabilities determine competitive access, with substrate coating precision now outweighing commodity blending scale.
- Coating:Fluidized bed CVD systems deposit controlled TiO2 layers on mica or fluorphlogopite substrates. Atomic layer deposition enables heavy-metal-free formulations qualifying for clean-beauty premium tiers.
- Dispersion:Particle size distribution control in liquid systems determines optical performance in finished cosmetics.
- Mixing:Standardized blending operations for commodity pearlizer grades face margin compression from TiO2 cost pass-through volatility.
- Formulating:End-use application engineering requires cross-functional expertise spanning pigment chemistry and finished goods processing.
Coating holds process technology barriers. Dispersion is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites European pearlizer distribution, while Shanghai Yangshan Port anchors Asia-Pacific import flows for mica substrate feedstocks.
China
Domestic cosmetics brands in Shanghai and Guangzhou scale pearlized product lines for consumer electronics packaging and premium skincare. GB standards for cosmetic raw materials tighten trace metal disclosure requirements. The Yangtze River Delta concentrates fluorphlogopite synthetic mica production capacity serving clean-beauty export markets.
Germany
Automotive OEMs in Stuttgart and Munich demand spectrophotometric batch consistency for interference pigments in exterior coatings. ECHA substance evaluation protocols compress allowable lead and arsenic thresholds in mica-derived pigments. The Rhine-Ruhr industrial corridor hosts fluidized bed CVD equipment clusters for controlled TiO2 layer deposition.
United States
FDA color additive regulations govern pearlizer market access for cosmetics and food-contact applications. Specialty formulators in New Jersey and California prioritize certified grades with full supply chain transparency. The Gulf Coast petrochemical corridor supplies sulfate-process TiO2 feedstocks facing price volatility from chloride-grade shortages.
India
Gujarat and Maharashtra industrial zones offer tariff-advantaged export platforms for REACH-registered pearlizer production. BIS standards for pigment quality create domestic compliance architecture. Ankleshwar and Vapi chemical corridors attract European cosmetics houses seeking alternative sourcing to Jharkhand mica dependencies.
South Korea
MFDS cosmetic ingredient regulations accelerate qualification programs for synthetic mica substrates in premium skincare. Seoul-based formulators deploy interference pigments for sensory differentiation in K-beauty export lines. The Incheon Free Economic Zone concentrates masterbatch compounding for consumer electronics supply chains.
Pearlizers Market Competitive Landscape
Listed leaders compete with private specialists across integrated pigment chemistry portfolios and substrate coating technology. The vendor base concentrates around three tiers: multinational chemical conglomerates with diversified effect pigment divisions, mid-cap specialists focused on mica-derived substrates, and regional powder-grade manufacturers serving domestic cosmetics houses. Strategic archetypes include integrated pigment houses leveraging backward control over TiO2 supply, synthetic substrate pioneers eliminating heavy metal contamination risks, and scale-driven compounders optimizing fluidized bed CVD throughput. Competitive moves center on synthetic mica capacity expansion and direct-to-formulator digital channel development.
Among Germany-based integrated chemical groups, BASF SE and Merck KGaA occupy positions spanning coating technology and proprietary substrate systems. Fujian Kuncai Fine Chemicals Co., Ltd. represents the scale-driven manufacturing archetype for powder-grade pearlizers. These three entities exemplify the competitive spectrum from high-performance effect pigments to volume-optimized export grades.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Lubrizol |
| Sun Chemical Performance Pigments |
| Merck KGaA |
| Huaian Concord Cosmetics Product Co. Ltd. (Kolortek) |
| Fujian Kuncai Fine Chemicals Co., Ltd. |
| Ashland |
| Croda International Plc |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day substrate lead times concentrate pricing power with integrated pigment houses controlling Jharkhand and Madagascar mica sourcing, while TiO2 cost pass-through volatility compresses margins for mid-tier blenders lacking backward integration into sulfate-process feedstocks. REACH-registered grades command premium spreads over standard powder grades as ECHA trace metal thresholds tighten, with specialty cosmetics formulators absorbing higher unit costs to secure certified supply chain transparency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with clean-beauty-certified synthetic mica substrates capturing widest spreads. Price differentiation hinges on REACH dossier completeness and spectrophotometric batch consistency guarantees. Cost compression in mid-tier powder grades is intensifying because chloride-grade TiO2 shortages force sulfate-process substitution. Mass-market cosmetics houses in São Paulo exhibit highest price sensitivity, while German automotive OEMs prioritize colorimetric precision over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate among cosmetics formulators seeking formulation flexibility, while masterbatch compounders serving consumer electronics supply chains maintain strategic stockpiles of interference pigments to hedge against Jharkhand mining disruptions. Raw material sourcing draws from Madagascar and Jharkhand for natural mica substrates, China for fluorphlogopite synthetic crystals, and Gulf Coast petrochemical corridors for TiO2 feedstocks. Single-source vulnerability in artisanal mica mining creates ESG audit exposure for pigment houses. Distribution runs through Rotterdam's chemical logistics infrastructure for European REACH-registered grades and Shanghai Yangshan Port for Asia-Pacific import flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among specialty formulators with direct technical service relationships, fragmenting traditional distributor relevance as mid-volume cosmetics houses bypass regional markups for mill-direct procurement.
For Market Incumbents: Compound defensive positioning through captive synthetic mica capacity expansion in Gujarat and Maharashtra industrial zones, securing REACH-registered export platforms insulated from Jharkhand supply volatility. Deepen fluidized bed CVD coating capabilities to meet automotive OEM spectrophotometric tolerance tightening, while accelerating direct-to-formulator digital channels to compress distributor relevance further. For New Entrants and Emerging Players: Lead with synthetic fluorphlogopite substrate specialization targeting South Korean premium skincare formulators seeking heavy-metal-free clean-beauty qualification. The most penetrable white space sits in mid-volume Latin American cosmetics laboratories in Mexico City bypassing traditional distribution for rapid sample-to-production scaling through specialty chemical marketplaces. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core effect pigment divisions amid portfolio rationalization pressures. Long-term viability over the coming decade rests on synthetic substrate technology ownership and direct channel control. The signal to watch is ECHA substance evaluation protocol acceleration compressing natural mica qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Mica Capacity Expansion | Fluorphlogopite crystal growth eliminates heavy metal contamination risks for clean-beauty premium tiers. |
| Backward Integration into TiO2 Feedstocks | Sulfate-process chloride-grade supply security insulates margin structures from spot price volatility. |
| Direct-to-Formulator Digital Channel Development | Specialty chemical marketplaces bypass distributor markups for mid-volume cosmetics laboratory procurement. |
| REACH Dossier Investment | Full supply chain transparency certification unlocks priority allocation from tier-one European personal care houses. |
| Fluidized Bed CVD Equipment Deployment | Controlled TiO2 layer deposition precision meets German automotive OEM colorimetric batch consistency specifications. |
Research Methodology
Operator-level perspectives from plant managers at pigment manufacturing facilities, procurement leads at cosmetics OEMs, distribution channel partners in Rotterdam and Shanghai, and technical R&D directors anchored the qualitative base. Primary interview insights combined with customs and trade data, SEC filings from listed chemical conglomerates, ECHA substance evaluation protocols, and GB standards documentation for cosmetic raw materials. Bottom-up volume modeling across powder, liquid, granular, and solid product types triangulated with top-down value estimates derived from REACH-registered grade pricing spreads.
Sensitivity analysis tested forecast robustness across TiO2 price volatility scenarios, ECHA trace metal threshold acceleration timelines, and synthetic mica adoption curves. Segmentation dimensions modeled include physical form factor, application channel, end-user procurement archetype, and coating technology tier. CAGRs were derived from regression analysis of historical volume trajectories adjusted for structural demand shifts in masterbatch compounding and clean-beauty certification. Industry-specific inputs encompassed fluorphlogopite capacity buildout schedules and automotive OEM colorimetric tolerance evolution.
The analysis sits within stated boundaries; outcomes outside sustained ECHA regulatory enforcement or abrupt Jharkhand supply disruption would require recalibration. Forecasts reflect documented assumptions regarding synthetic substrate cost convergence timelines and specialty formulator buyer concentration trajectories. Revision becomes warranted when clean-beauty disclosure mandate adoption crosses critical mass thresholds in Asia-Pacific consumer markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Liquid Thickeners Market
Additives
Potassium Nitrate Market
Additives
Monocalcium Phosphate Market
Additives
Sorbitan Tristearate Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Crosslinking Agents Market
Additives
Plasticizer Alcohols Market
Additives
Silage Additives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Europe Fuel Additives Market
Additives
North America Fuel Additives Market
Additives
Calcium Stearate Market
Additives
Global Coalescing Agent Market
Additives
Impact Modifier Market
Additives
Feed Additives Market
Additives
Carboxymethylcellulose (CMC) Market