
 Aluminum Sulfide Market | 2026-2036
Aluminum Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Sulfide Market Analysis
Chinese inorganic chemical producers is realigning capacity toward higher-purity grades for electronics applications. BASF AG leverages its integrated sulfur chemistry platform to sustain feedstock cost advantages across European supply chains. Arkema SA anchors its position through specialized pellet formulations serving pyrotechnics and aerospace end users. American Elements competes on rare-earth-adjacent material expertise, extending its catalog into custom crystal geometries for research institutions.
Aluminum sulfide is a binary inorganic compound with the formula Al₂S₃, typically synthesized via direct combination of aluminum and sulfur at elevated temperatures or through carbothermal reduction of aluminum oxide in the presence of sulfur sources; it hydrolyzes vigorously to produce hydrogen sulfide and aluminum hydroxide, which underpins its deployment as a water treatment reagent and chemical intermediate. Powder grades dominate volume throughput due to lower processing thresholds in bulk chemical synthesis, while crystal segments command premium positioning from semiconductor and optoelectronics manufacturers requiring precise stoichiometry. Catalyst applications within the chemicals end-user segment are expanding fastest as refiners seek sulfur-transfer agents compatible with hydrodesulfurization unit retrofits.
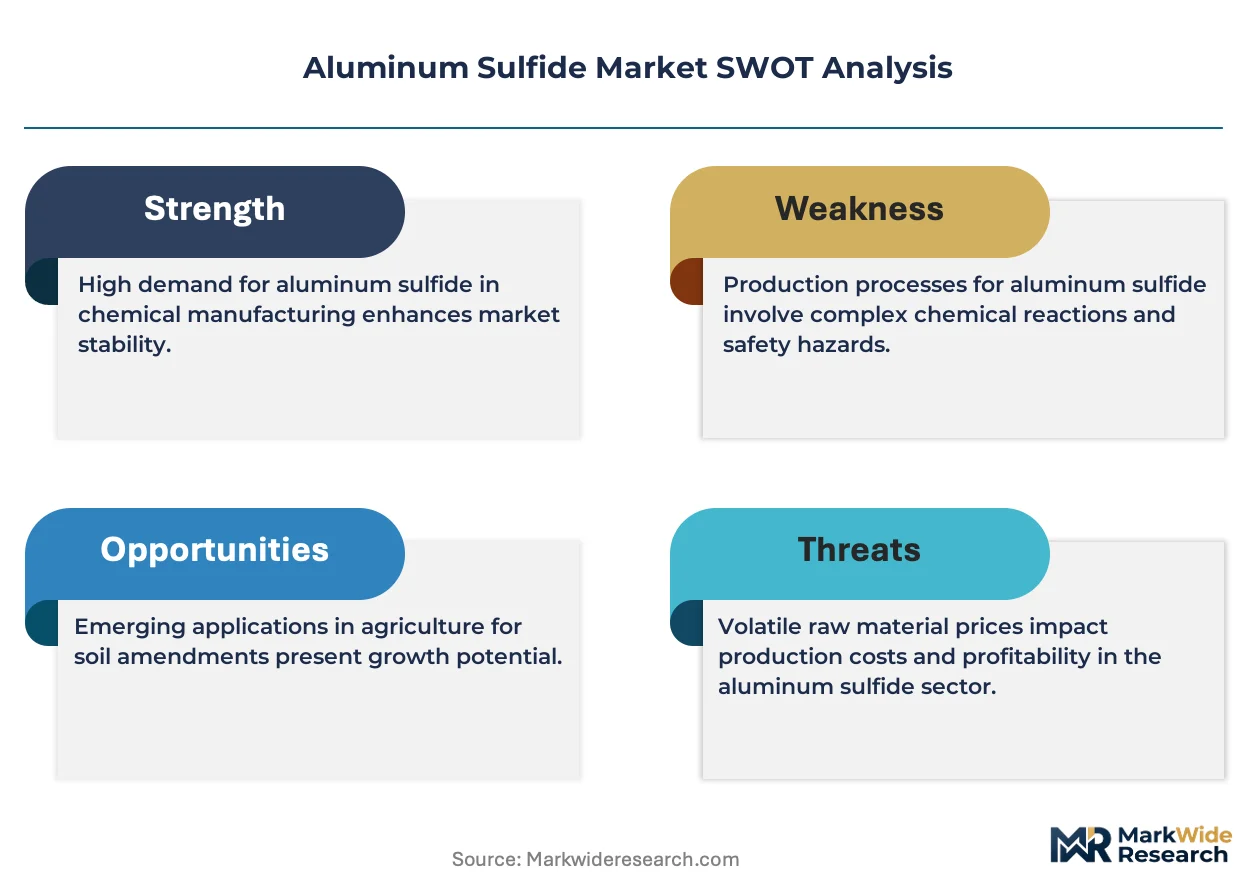
EPA discharge standards and REACH substance restrictions are tightening permissible sulfur compound thresholds in industrial effluent, compelling water treatment operators to validate aluminum sulfide against alternative coagulants. Japan's METI chemical management protocols and South Korea's MFDS industrial chemical registrations add compliance layers for suppliers targeting East Asian electronics corridors. Stakeholders must weigh feedstock sulfur volatility against long-term offtake commitments from semiconductor fabs and municipal water authorities.
Market Dynamics
EPA discharge standards and REACH substance restrictions are tightening permissible sulfur compound thresholds in industrial effluent, compelling water treatment operators to validate aluminum sulfide against alternative coagulants while semiconductor fabs demand higher-purity grades.
Growth Catalysts
- Hydrodesulfurization retrofits:Refiners in Germany and the United States are expanding procurement of aluminum sulfide as sulfur-transfer agents compatible with catalyst unit upgrades.
- East Asian electronics corridors:Japanese electronics manufacturers and South Korean semiconductor supply chains are concentrating demand for crystal-grade aluminum sulfide with precise stoichiometry.
- Wastewater chemistry mandates:Stricter EPA and REACH frameworks are pushing municipal and industrial facilities toward advanced treatment chemistries including aluminum sulfide coagulation.
Market Restraints
- Feedstock sulfur volatility:Sulfur price swings directly compress margin predictability for aluminum sulfide producers dependent on spot sulfur procurement.
- Chinese supply concentration:Inorganic chemical producers in China control substantial powder-grade capacity, creating geographic single-source risk for European and North American buyers.
- Vigorous hydrolysis limitation:Aluminum sulfide's spontaneous reaction with moisture complicates storage, transport, and handling infrastructure requirements.
Strategic Opportunities
- Electronics-grade purification:Chinese producers are realigning capacity toward higher-purity grades, creating white space for specialized suppliers to serve Japanese and South Korean semiconductor fabs.
- Pyrotechnics pellet specialization:Custom formulations for aerospace end users represent an underpenetrated niche with premium pricing potential.
- Integrated sulfur chemistry platforms:European producers with captive sulfur processing can backward integrate into aluminum sulfide production, capturing feedstock cost advantages.
Industry Challenges
- Multi-jurisdiction registration complexity:Japan's METI chemical management protocols and South Korea's MFDS industrial chemical registrations add compliance layers and timeline uncertainty for suppliers targeting East Asian electronics corridors.
- Higher-purity certification timelines:Semiconductor manufacturers require extended validation cycles for crystal-grade material qualification, stretching working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Sulfide Market |
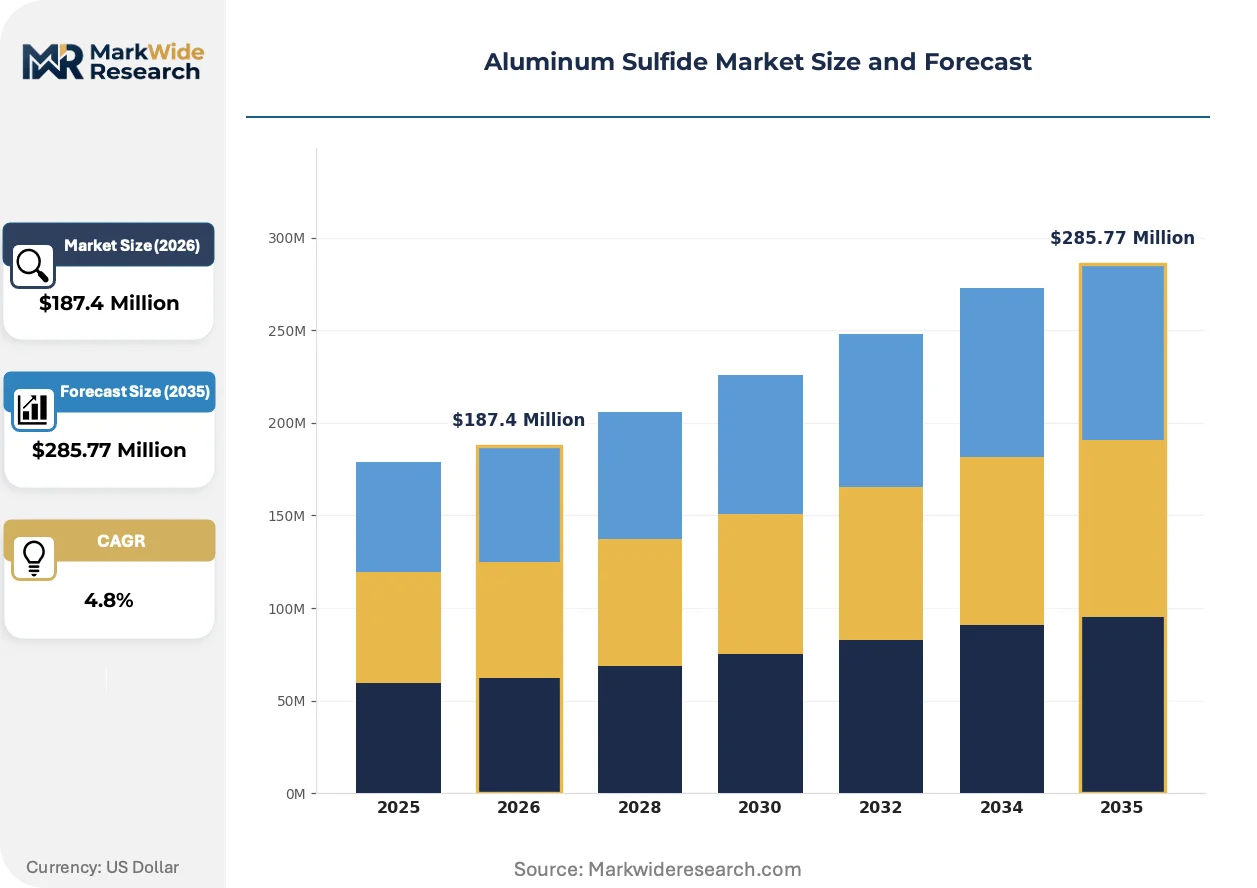
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Pellets, Crystals End User: Aerospace, Chemicals, Electronics, Agriculture Application: Water Purification, Soil Conditioning, Catalyst, Pyrotechnics Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | BASF AG, Buckman Laboratories, Arkema SA, AkzoNobel, American Elements, Chemtrade Logistics Inc., The Dow Chemical Company, Merck KGaA, Triveni Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Sulfide Market Emerging Trajectories
Japanese electronics manufacturers and South Korean semiconductor fabs are reshaping material specifications, while regulatory frameworks on three continents tighten discharge thresholds. These forces are compressing product lifecycles and rewarding suppliers with integrated quality systems.
Crystal-grade aluminum sulfide with precise stoichiometry serves optoelectronics and semiconductor applications requiring controlled bandgap properties. Japanese electronics manufacturers and South Korean semiconductor fabs are adopting this material at accelerating pace for LED and sensor substrates. This specification tier is expanding into premium positioning previously occupied by rare-earth sulfides, compressing substitution timelines for research-grade applications.
REACH substance restrictions and EPA discharge standards are tightening permissible sulfur compound thresholds in industrial effluent. Municipal water authorities and chemical processing facilities must validate aluminum sulfide coagulation performance against polyaluminum chloride alternatives. German chemical processing industries and United States refiners are most affected, driving formulation adjustments to meet combined EPA and ECHA compliance requirements.
Specification-driven procurement now dominates semiconductor supply chain engagements, displacing spot-market purchasing for electronics-grade material. Long-term offtake agreements with Japanese and South Korean fabs are replacing transactional orders, concentrating volume with qualified suppliers. This pattern is most visible in East Asian manufacturing clusters, where METI and MFDS registration status functions as a de facto supplier filter.
Aluminum Sulfide Market Segmentation
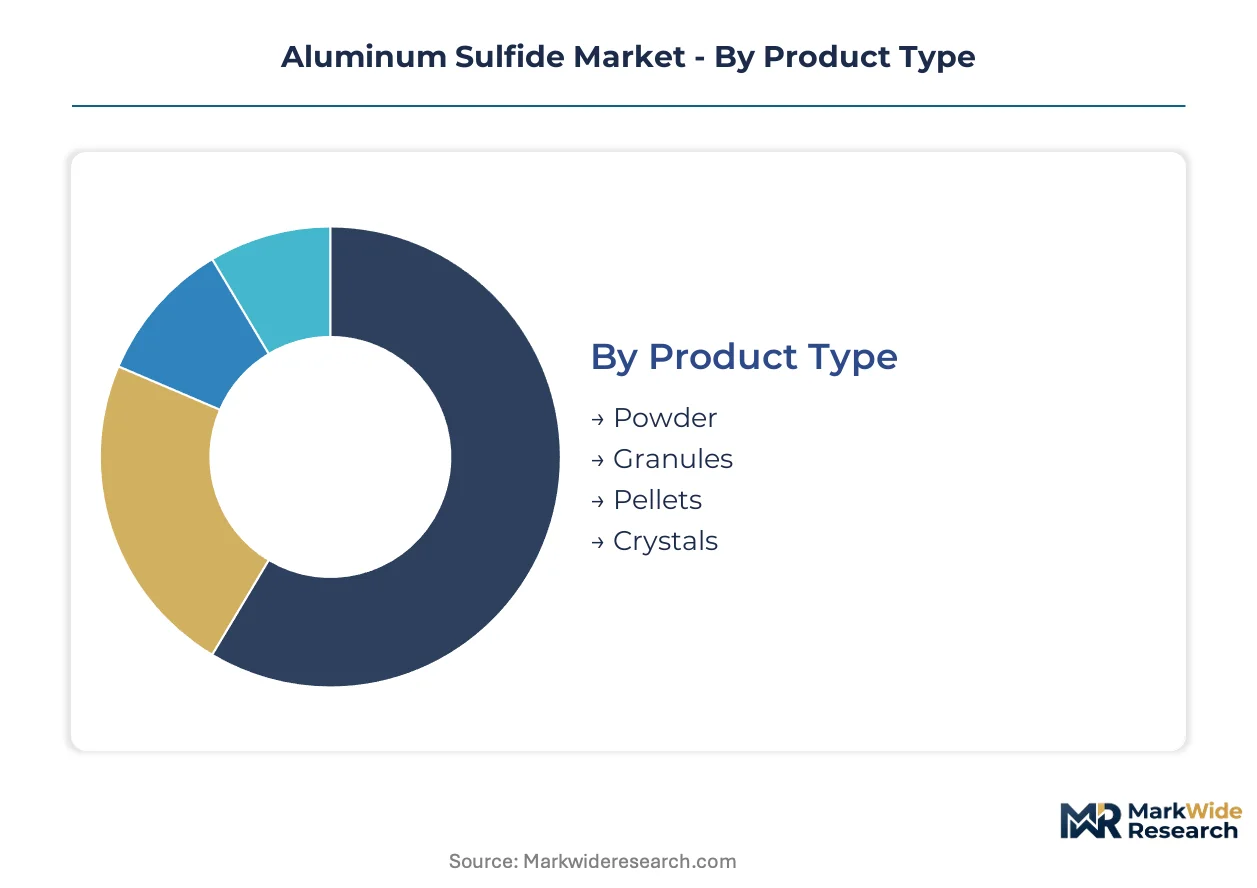
Aluminum sulfide's reactivity profile and purity gradients create distinct commercial tiers across product formats. End-use specifications from semiconductor fabs to municipal water authorities fragment demand into non-substitutable segments with divergent margin structures.
Product Type:
Volume throughput concentrates in lower-purity bulk formats, while premium positioning attaches to controlled-crystal geometries serving optoelectronics.
- Powder:Finely divided particulate with minimal post-processing, hydrolyzing vigorously upon moisture exposure. German and United States chemical processors consume bulk volumes for catalyst precursor applications, though storage infrastructure costs erode margin at smaller scale.
- Crystals:Stoichiometrically precise single-crystal or polycrystalline forms with defined bandgap properties. Japanese electronics manufacturers and South Korean semiconductor fabs concentrate procurement for LED substrate and sensor applications, with METI and MFDS registration status filtering supplier pools.
- Granules:Intermediate particle size with moderated surface area for controlled reactivity. Water treatment operators in United States municipalities favor this format for coagulation dosing precision under EPA discharge frameworks.
- Pellets:Densified cylindrical or spherical forms engineered for specific burn rates. Arkema SA and specialized European producers serve aerospace pyrotechnics end users with custom formulations commanding premium pricing.
Mature deployment sits with powder. Newer deployment is concentrated in crystals.
End User:
Application knowledge intensity separates segments, with semiconductor qualification timelines stretching working capital for suppliers.
- Chemicals:Refiners and bulk chemical producers deploying aluminum sulfide as sulfur-transfer agents in hydrodesulfurization unit retrofits. German chemical processing industries anchor European demand, with REACH substance restrictions validating performance against polyaluminum chloride alternatives.
- Electronics:Optoelectronics and semiconductor manufacturers requiring crystal-grade material with sub-ppm impurity thresholds. South Korean semiconductor supply chains and Japanese electronics corridors are gaining share fastest as LED and sensor substrate adoption accelerates.
- Aerospace:Pyrotechnics and propulsion system manufacturers specifying pellet formulations with controlled ignition characteristics. Custom geometry requirements limit supplier base to specialized European and North American producers.
- Agriculture:Soil conditioning applications leveraging aluminum sulfide's pH adjustment and sulfur delivery properties. This segment trails in commercial development due to handling complexity and alternative amendment availability.
Procurement maturity clusters in chemicals. Electronics is climbing the fastest.
Application:
Regulatory stringency varies sharply across uses, with water discharge rules imposing compliance costs distinct from semiconductor qualification burdens.
- Catalyst:Hydrodesulfurization and chemical synthesis applications requiring sulfur-transfer functionality. United States refiners and German chemical processors are expanding procurement as retrofit deadlines approach under EPA and ECHA frameworks.
- Water Purification:Coagulation and sulfide precipitation in municipal and industrial effluent treatment. Stricter EPA discharge standards and REACH thresholds are compelling validation against alternative chemistries, particularly in German and United States facilities.
- Pyrotechnics:Controlled combustion applications in aerospace and specialty industrial systems. Pellet formulation expertise concentrates with European producers serving defense and space end users.
- Soil Conditioning:Agricultural pH modification and micronutrient delivery. Limited adoption reflects competition with elemental sulfur and aluminum sulfate alternatives.
Established deployment dominates water purification. Catalyst applications show steepest expansion trajectory.
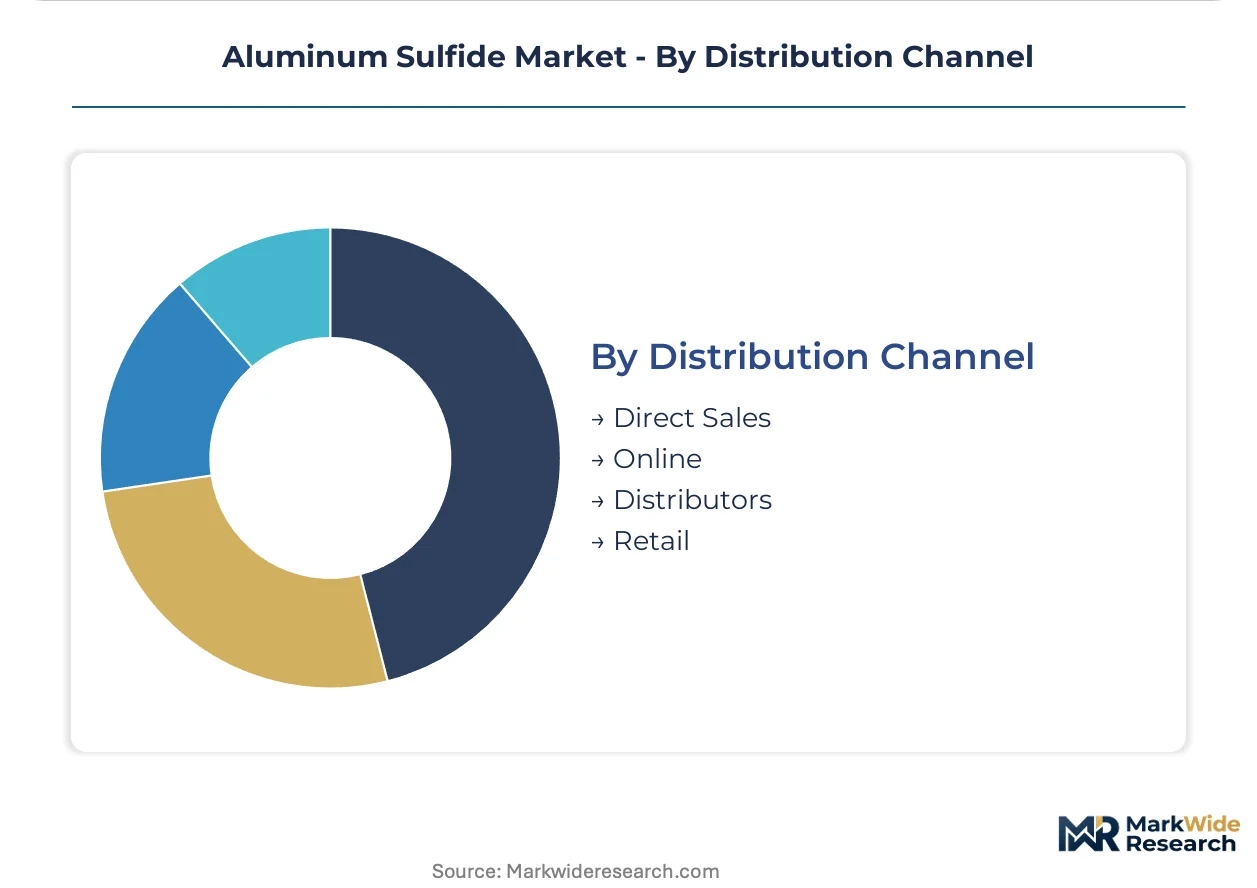
Distribution Channel:
Customer scale and specification complexity determine channel selection, with direct relationships prevailing where qualification requirements predominate.
- Direct Sales:Long-term offtake agreements between producers and qualified semiconductor fabs or municipal water authorities. Japanese and South Korean electronics manufacturers concentrate volume through this channel, with METI and MFDS documentation requirements reinforcing supplier stickiness.
- Distributors:Regional chemical distributors serving mid-scale chemical processors and water treatment operators. German and United States markets sustain this channel for powder and granule formats.
- Online:E-commerce platforms for research-grade quantities and custom crystal geometries. American Elements and specialized suppliers target research institutions through this route.
- Retail:Minimal penetration limited to specialty agricultural and hobbyist pyrotechnics applications.
Volume concentration rests with direct sales. Distributor relationships are deepening in chemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfur feedstock availability and aluminum smelting infrastructure anchor aluminum sulfide production geography across three continents. Chemical processing clusters in Germany and the United States sustain catalyst-grade demand, while East Asian electronics corridors concentrate crystal-grade procurement.
United States
Refiners in Texas and Louisiana are expanding aluminum sulfide procurement for hydrodesulfurization retrofits ahead of EPA discharge deadlines. The EPA's tightened sulfur compound thresholds in industrial effluent are compelling water treatment operators to validate coagulation performance. Houston's chemical processing corridor anchors domestic catalyst-grade consumption, with municipal utilities in California and the Northeast trialing advanced treatment chemistries.
Germany
BASF AG's integrated sulfur chemistry platform in Ludwigshafen sustains feedstock cost advantages for European supply chains. REACH substance restrictions are tightening permissible sulfur thresholds, pushing chemical processors toward validated treatment reagents. The Rhine-Ruhr industrial cluster concentrates catalyst demand from refiners and bulk chemical producers seeking ECHA-compliant sulfur-transfer agents.
China
Inorganic chemical producers in Shandong and Jiangsu provinces control substantial powder-grade capacity, creating geographic single-source exposure for international buyers. The country's dual carbon goals are pressuring smelters to optimize sulfur recovery integration. Yangtze River Delta manufacturing clusters are realigning toward higher-purity grades for electronics applications, though METI-equivalent traceability standards remain uneven.
Japan
Electronics manufacturers in Tokyo-Osaka corridor are concentrating procurement for LED substrate and sensor applications requiring precise stoichiometry. METI chemical management protocols add registration layers that filter supplier pools to qualified vendors. Kyushu semiconductor fabs are accelerating crystal-grade qualification timelines, stretching working capital deployment for approved material sources.
South Korea
Semiconductor supply chains around Seoul and Busan are gaining share fastest in crystal-grade aluminum sulfide adoption. MFDS industrial chemical registrations create compliance barriers for non-domestic suppliers targeting electronics corridors. Pyeongtaek and Hwaseong fab clusters are displacing spot-market purchasing with long-term offtake agreements, concentrating volume with METI-registered vendors.
Aluminum Sulfide Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade purification and specialized pellet formulations. The vendor base stratifies across integrated chemical conglomerates, regional sulfur processors, and rare-earth-adjacent material specialists. Three archetypes dominate: captive sulfur-chemistry platforms with backward integration advantages; precision-crystal specialists serving semiconductor fabs; and diversified inorganic producers competing on volume scale. Competitive moves concentrate on portfolio diversification into higher-purity grades and geographic expansion through distributor partnerships in East Asian electronics corridors.
Among European integrated producers, BASF AG and Arkema SA occupy positions anchored by sulfur chemistry infrastructure and specialized formulation expertise respectively. BASF AG exemplifies the captive-platform archetype with Ludwigshafen-based feedstock integration, while Arkema SA represents pellet-specialist positioning for aerospace pyrotechnics end users. American Elements sits within the rare-earth-adjacent tier, extending catalog breadth into custom crystal geometries for research institutions requiring small-batch precision.
| Leading Market Players |
|---|
| BASF AG |
| Buckman Laboratories |
| Arkema SA |
| AkzoNobel |
| American Elements |
| Chemtrade Logistics Inc. |
| The Dow Chemical Company |
| Merck KGaA |
| Triveni Chemicals |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabs in Japan and South Korea command pricing power through long-term offtake agreements that lock in crystal-grade premiums, while powder-grade procurement by German and United States chemical processors operates on spot-market volatility with sulfur-cost pass-through clauses.
Pricing Analysis
Warranty and technical service bundling separates premium crystal suppliers from unbundled powder traders, with Japanese electronics manufacturers demanding METI-registered validation support included in unit pricing. Three-tier pricing structure across electronics-grade, catalyst-grade, and industrial-grade levels reflects certification burden and purity testing intensity. Cost compression in powder grades is intensifying because Chinese capacity expansion outpaces demand growth from United States refiners. Municipal water authorities exhibit highest price sensitivity due to budget cycles, while aerospace pyrotechnics buyers accept 40-60% premiums for custom pellet geometries.
Supply Chain Analysis
Reverse-logistics infrastructure for moisture-compromised material returns centers on specialized reprocessing facilities in Germany and the United States, where aluminum sulfide's vigorous hydrolysis creates unique handling complexity. Supply concentrates in China, Germany, and the United States, with Shandong province powder capacity creating geographic single-source exposure. Feedstock draws from sulfur recovery at petroleum refineries and aluminum smelter byproduct streams. Tariff exposure on Chinese inorganic chemical imports threatens margin stability for European distributors. Distribution runs through direct sales for semiconductor fabs and regional chemical distributors for water treatment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: REACH substance restrictions and EPA discharge standards erect registration barriers that favor incumbents with validated quality systems and multi-jurisdiction chemical management expertise.
For Market Incumbents: To counter feedstock sulfur volatility, BASF AG and integrated sulfur-chemistry platforms should deepen backward integration into captive sulfur recovery, while expanding crystal-grade purification capacity in Ludwigshafen to serve Japanese semiconductor qualification timelines. Arkema SA and pellet specialists must defend aerospace margins through formulation IP and burn-rate customization capabilities that spot-market suppliers cannot replicate. For New Entrants and Emerging Players: Enter via electronics-grade purification partnerships with Yangtze River Delta producers seeking METI-equivalent traceability upgrades, targeting the white space between Chinese powder capacity and Japanese crystal demand. South Korean MFDS registration services represent an underpenetrated advisory niche. A go-to-market angle anchored to semiconductor fab qualification support commands premium positioning unavailable to commodity traders. For Investors and Strategic Acquirers: The window for entry favors rare-earth-adjacent material specialists with existing crystal-growth infrastructure and research-institution relationships that transfer to semiconductor supply chains. Long-term viability hinges on 5-10 year offtake visibility from East Asian electronics corridors. The signal to watch is Japanese METI registration approval velocity for non-domestic suppliers, which would validate acquisition theses for European purification specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | BASF AG's Ludwigshafen platform captures feedstock cost advantages against spot-market dependent competitors. |
| Electronics-Grade Purification Scale-Up | Chinese producers realigning toward higher-purity grades create partnership opportunities for METI-registered European suppliers. |
| Long-Term Offtake Agreements | South Korean semiconductor fabs displace spot purchasing, concentrating volume with qualified vendors and stretching competitor working capital. |
| Custom Pellet Formulation Development | Arkema SA's aerospace pyrotechnics specialization commands premium pricing through controlled ignition geometry IP. |
| Multi-Jurisdiction Registration Investment | Suppliers targeting East Asian electronics corridors must navigate Japan's METI protocols and South Korea's MFDS frameworks simultaneously. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving plant managers at German chemical processors, procurement leads at United States refiners, distribution channel partners in East Asian electronics corridors, and technical R&D directors at sulfur-chemistry platforms. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down production capacity assessments from Shandong and Jiangsu province filings.
Granularity-level modeling distinguished powder, crystal, granule, and pellet formats with separate purity-grade assumptions, while end-user segmentation captured chemicals, electronics, aerospace, and agriculture applications with distinct qualification timelines. CAGRs were derived from regression analysis against sulfur price indices and semiconductor capital expenditure cycles across the analysis window. Forecast inputs included EPA discharge deadline schedules and Japanese METI registration pipeline velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sulfur commodity spikes or semiconductor fab construction delays. Practitioners should monitor Chinese dual carbon policy implementation and United States refinery hydrodesulfurization retrofit acceleration for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market