
 Sodium Sulphate Market | 2026-2036
Sodium Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Sulphate Market Outlook
ISO 9001 certification cycles for chemical manufacturers is unwinding competitive entry in sodium sulphate supply, favoring producers with established quality management systems. China Nafine Group International Co. Ltd. leverages its captive salt-lake resource base to dominate natural sodium sulphate output in Asia. Lenzing AG anchors a vertically integrated position by converting by-product sulphate from its viscose fiber operations into merchant-grade supply. Grasim Industries Ltd. competes through its Aditya Birla chemicals division, sustaining broad distribution across Indian detergent and textile markets.
Sodium sulphate, chemically Na₂SO₄, is an inorganic salt existing as a white crystalline solid with a molecular weight of 142.04 g/mol, produced through either natural brine extraction or synthetic Mannheim furnace processing of sodium chloride and sulphuric acid; its primary industrial purpose centers on serving as a low-cost filler and processing aid across detergent, glass, and textile manufacturing. Natural sodium sulphate commands the largest volume share due to lower energy inputs in lake-derived extraction, while synthetic grades capture premium positioning in pharmaceutical and food-grade applications where purity thresholds exceed 99.5 percent. Industrial grade supply occupies the thickest margin pool across detergent and glass end uses, though pharmaceutical grade segments are gaining structural importance as regulatory purity requirements intensify.
China's SAMR enforces GB/T 6009 standards for industrial sodium sulphate purity, while India's BIS mandates IS 255 specifications for detergent-grade material, and REACH registration in Europe governs import thresholds for synthetic-origin product streams. These frameworks collectively elevate compliance costs for uncertified producers while creating preferential market access for established multinationals with documented substance dossiers. Stakeholders must monitor evolving purity mandates and carbon-intensity disclosures across major import jurisdictions to preserve supply chain continuity.
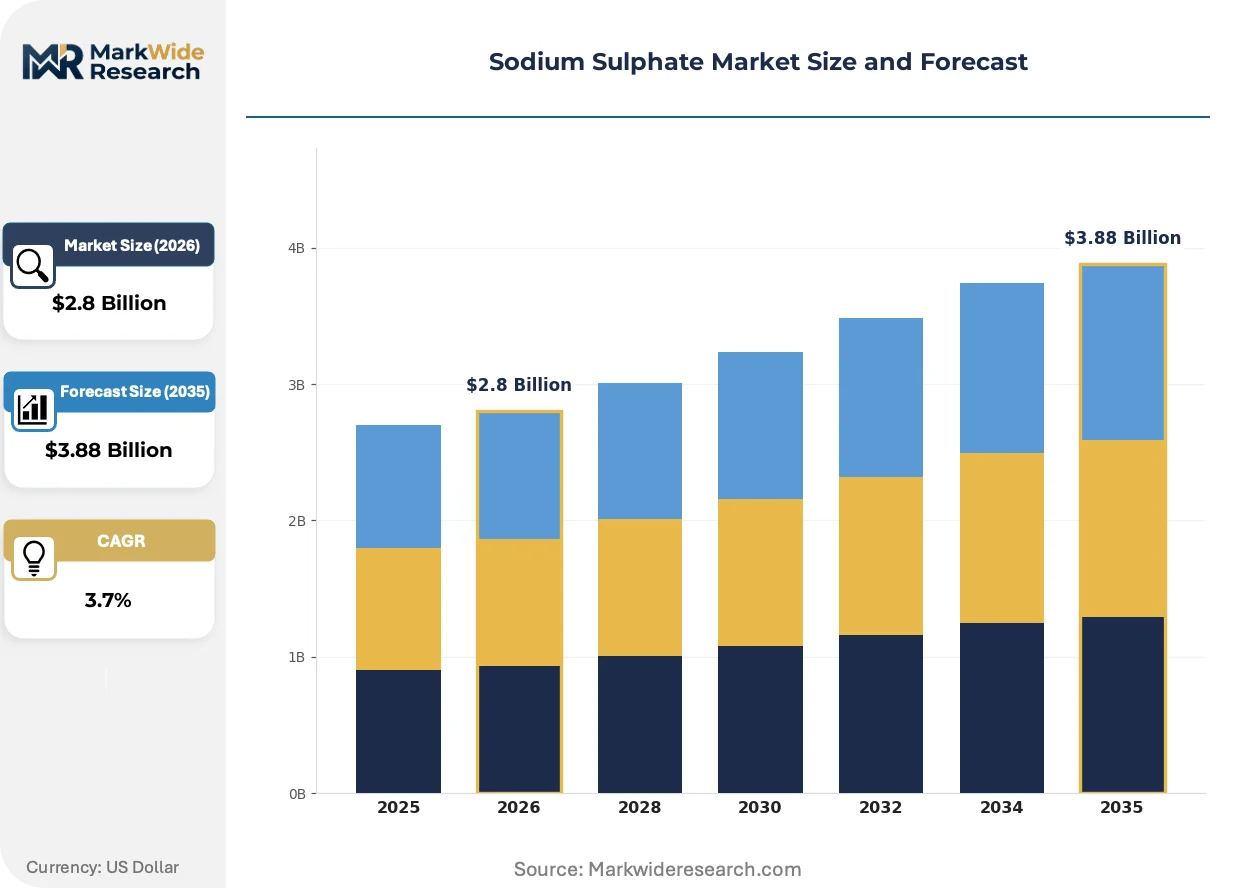
Market Dynamics
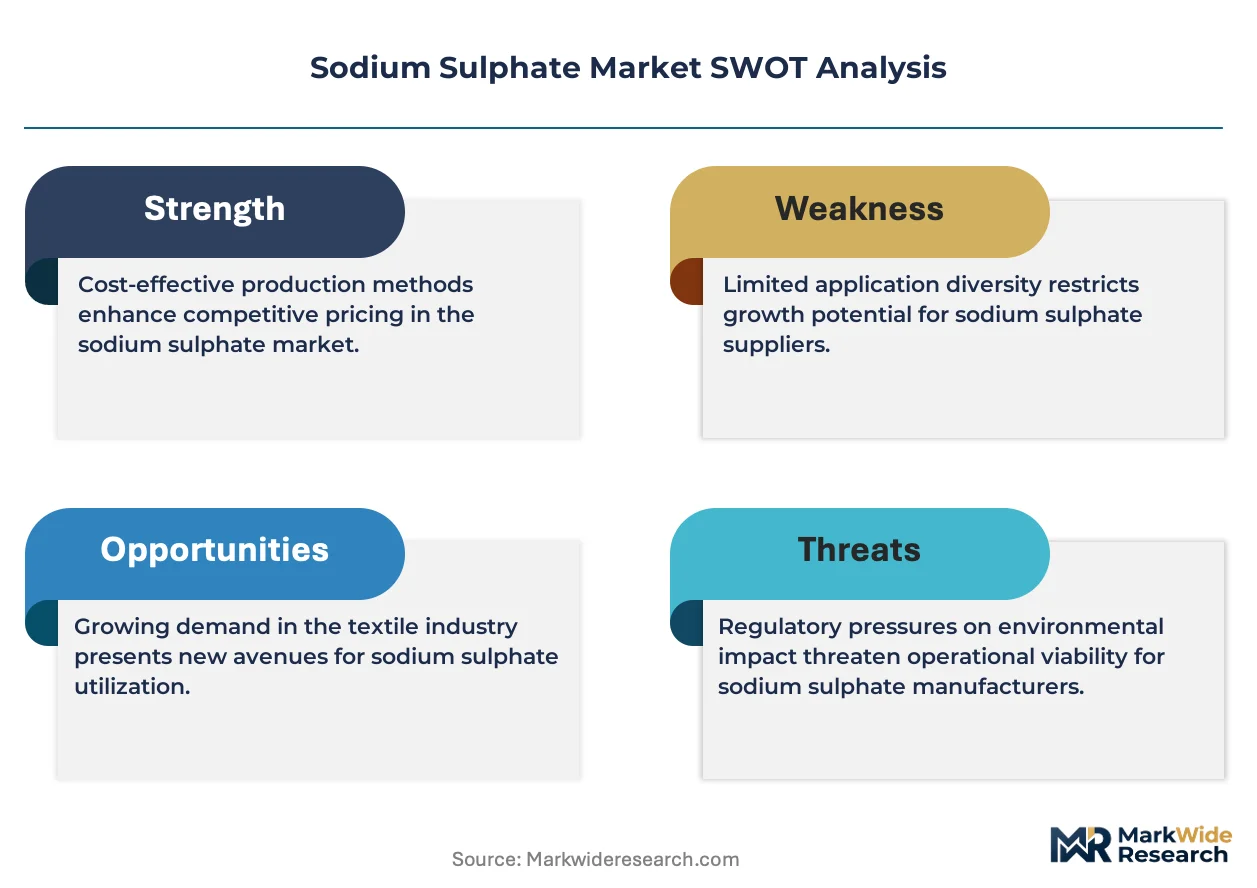
China's GB standards for industrial chemical purity are tightening product specifications across export supply chains, forcing sodium sulphate producers to re-certify operations or forfeit access to detergent and glass manufacturing customers in India and Southeast Asia.
Growth Catalysts
- Detergent manufacturing expansion:India's domestic detergent production is scaling capacity, driving offtake of sodium sulphate as a cost-effective filler in powder formulations. The country's PLI scheme for chemical manufacturing accelerates this demand trajectory.
- Glass manufacturing concentration:Float glass producers in India are expanding furnace capacity, consuming sodium sulphate as a refining and fluxing agent in melting processes.
- REACH registration compliance:European importers now require documented substance dossiers for synthetic-origin sodium sulphate, creating preferential market access for established multinationals with pre-registered supply chains.
Market Restraints
- Natural brine extraction concentration:China's Qaidam Basin and Sichuan salt lakes dominate global natural sodium sulphate supply, creating geographic single-point vulnerability for detergent manufacturers dependent on lake-derived material.
- Synthetic production energy intensity:Mannheim furnace processing of sodium chloride and sulphuric acid requires substantial thermal input, exposing synthetic-grade producers to volatile natural gas and electricity pricing.
- Zeolite substitution in detergents:Builder phosphate alternatives and concentrated liquid detergent formulations are displacing sodium sulphate filler demand in premium powder segments across European and North American markets.
Strategic Opportunities
- Pharmaceutical-grade purity migration:Regulatory purity requirements exceeding 99.5 percent are intensifying across India's CDSCO and China's NMPA frameworks, opening premium positioning for producers with crystallization and purification capabilities.
- Carbon-intensity disclosure mandates:The EU Green Deal and China's dual carbon goals are creating first-mover advantage for producers with documented low-carbon extraction processes, particularly salt-lake operations with minimal thermal inputs.
- Textile dyeing auxiliary expansion:Viscose fiber producers are converting by-product sulphate into merchant-grade supply, capturing value from waste streams in India's growing textile processing corridor.
Industry Challenges
- ISO 9001 certification cycle compression:Chemical manufacturers face unwinding competitive entry as quality management system documentation requirements extend lead times for new market participants.
- Legacy furnace reconfiguration costs:Synthetic producers must retrofit Mannheim operations to meet tightening MEE emissions standards in China, requiring substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Sulphate Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Membrane, Anhydrous End Use Industry: Textiles, Detergents, Glass, Pulp & Paper Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Packaging Type: Bags, Bulk Containers, Drums, Big Bags |
| Companies Covered | China Nafine Group International Co. Ltd., Alkim Alkali Kimya, Lenzing AG, Grasim Industries Ltd., Searles Valley Minerals Inc., Minera de Santa Marta, Tata Chemicals Ltd., Kuchuksulphate, Saskatchewan Mining and Minerals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Sulphate Market Strategic Shifts
Membrane crystallization and selective evaporation technologies are reshaping how sodium sulphate producers extract and refine material, compressing energy requirements while elevating purity thresholds for pharmaceutical and food-grade segments.
Solar-assisted evaporation systems for natural brine processing are fragmenting the traditional energy-cost advantage of lake-derived sodium sulphate. Indian producers in Rajasthan and Gujarat are piloting these installations to offset grid electricity exposure. The technology is fragmenting regional supply cost structures, enabling inland operations to compete with established Qaidam Basin suppliers on delivered cost to detergent manufacturers.
China's SAMR enforcement of GB/T 6009 standards is tightening industrial-grade purity specifications, eliminating sub-99 percent material from export-eligible supply. Indian BIS IS 255 specifications for detergent-grade material are following this trajectory. Glass manufacturers in both countries are reformulating batch compositions to accommodate higher-purity sodium sulphate, adjusting flux ratios and melting temperature profiles.
Direct procurement contracts between detergent manufacturers and salt-lake operators are displacing traditional trader-mediated distribution in India's western industrial corridors. Grasim Industries and other integrated chemical producers are establishing captive offtake agreements with Rajasthan-based natural sulphate extractors. This channel compression is most visible in Maharashtra and Gujarat, where powder detergent manufacturers seek supply security amid tightening purity mandates.
Sodium Sulphate Market Segmentation
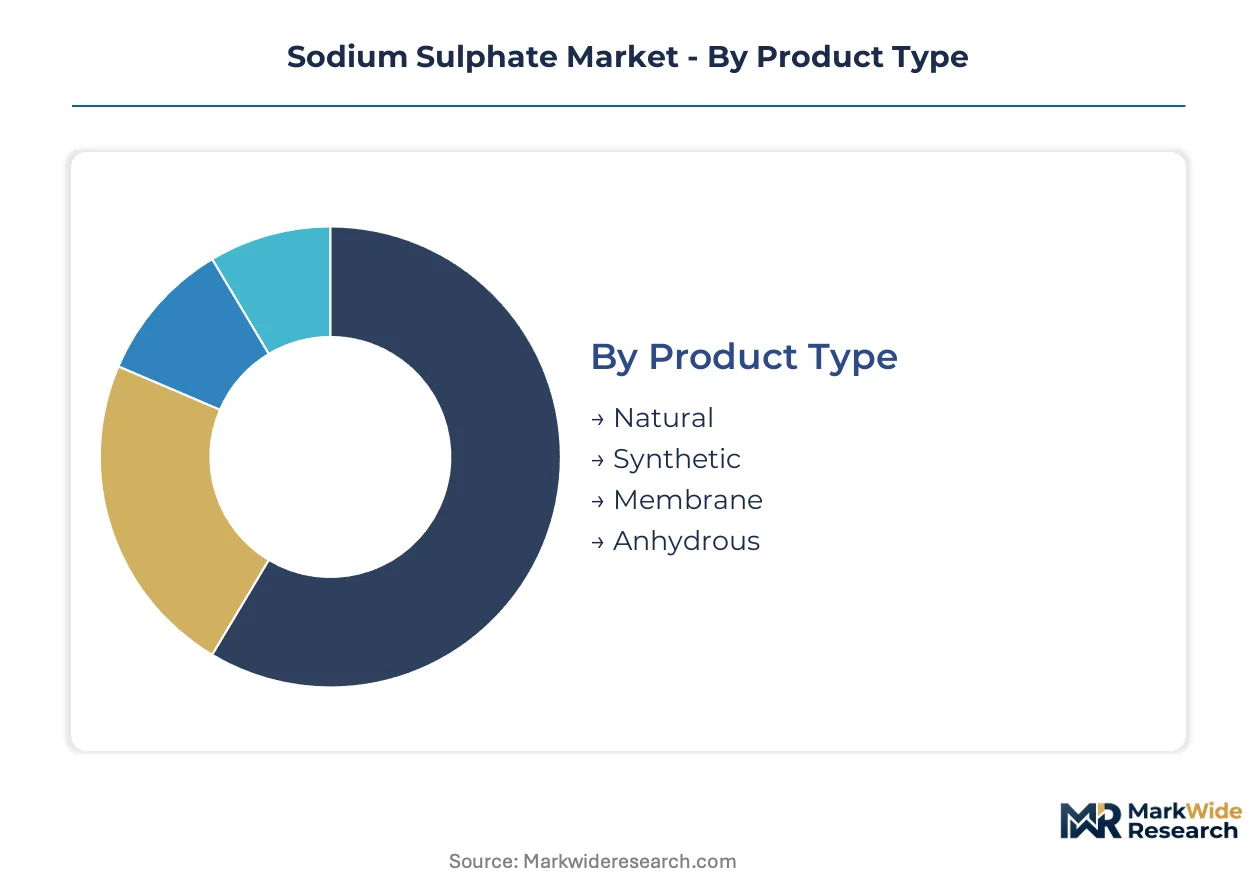
Sodium sulphate supply chains fragment across extraction methods, purity thresholds, and packaging configurations that dictate access to detergent, glass, and pharmaceutical end uses. Regulatory grade specifications in China, India, and Europe create tiered market access where certification status separates premium positioning from commodity supply.
Product Type:
GB/T 6009 and IS 255 specifications enforce divergent purity floors across natural lake-derived and synthetic furnace-origin material, channeling each type toward distinct end-use qualifications.
- Natural:Salt-lake extraction from China's Qaidam Basin and Sichuan deposits yields crystalline Na₂SO₄ with minimal thermal processing. Detergent manufacturers in India source this grade for powder formulations where cost efficiency outweighs purity premiums. Lake-derived supply concentrates geographic risk for buyers lacking diversification.
- Synthetic:Mannheim furnace processing of sodium chloride and sulphuric acid produces controlled-purity output meeting pharmaceutical and food-grade thresholds. CDSCO and NMPA registration requirements favor this origin for active pharmaceutical ingredient manufacturing. Energy intensity exposes producers to volatile natural gas pricing.
- Membrane:Selective crystallization technology enables mid-tier purity at reduced energy input compared to conventional evaporation.
- Anhydrous:Dehydrated crystalline form serves glass manufacturing flux applications requiring minimal moisture content.
Established volume favors natural extraction; emerging adoption favors membrane processing.
End Use Industry:
Cost tier differentiation separates commodity filler applications from specialized processing aids where purity commands measurable price premiums.
- Detergents:Powder formulation manufacturers in India absorb the largest volume share as sodium sulphate functions as a cost-effective inert filler and anti-caking agent. PLI scheme incentives for domestic chemical manufacturing accelerate capacity expansion in Maharashtra and Gujarat detergent corridors.
- Glass:Float glass producers consume sulphate as a refining and fluxing agent in melting furnaces, with purity specifications tightening under revised BIS standards for optical clarity requirements.
- Textiles:Viscose fiber operations generate by-product sulphate convertible to merchant-grade supply.
- Pulp & Paper:Kraft process applications utilize sulphate in cooking liquor recovery systems.
Glass manufacturing anchors volume stability; detergent expansion drives the steepest demand trajectory.
Grade:
Customer type segmentation separates industrial commodity buyers from regulated industries demanding documented purity dossiers and batch certification.
- Industrial Grade:Purity thresholds of 99 percent or lower serve detergent filler and glass flux applications where functional performance tolerates minor impurity variation. REACH registration and BIS IS 255 compliance documentation distinguish export-eligible supply from domestic-only material.
- Pharmaceutical Grade:Exceeding 99.5 percent purity with heavy metal and microbial specifications, this segment commands premium positioning for excipient and API manufacturing. CDSCO and NMPA facility inspections create entry barriers for uncertified producers.
- Food Grade:FSSAI and FDA compliance for food additive applications limits approved supplier pools.
- Technical Grade:Intermediate specification material serves textile dyeing and leather processing auxiliary functions.
Industrial grade dominates volume throughput; pharmaceutical grade captures margin expansion.
Packaging Type:
Supply concentration in lake-derived production regions shapes distribution economics and packaging selection for delivered cost optimization.
- Bulk Containers:Rail and vessel shipment of unpackaged crystalline material minimizes unit economics for detergent manufacturers with dedicated receiving infrastructure. Qaidam Basin-to-Mundra Port logistics favor this format for Indian import flows.
- Big Bags:Flexible intermediate bulk containers enable mechanized handling at glass manufacturing furnaces and textile processing facilities requiring intermediate volume delivery.
- Bags:Multi-wall paper or woven polypropylene packaging serves smaller detergent compounders and regional distributors.
- Drums:Steel or fiber containment protects pharmaceutical and food-grade material from moisture and contamination during high-value shipment.
Bulk containers maximize cost efficiency; drum packaging protects premium grade integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mundra Port rail corridor underwrites India's import dominance, connecting Qaidam Basin lake-derived supply to detergent manufacturing clusters across Gujarat and Maharashtra.
China
Qaidam Basin salt-lake operations feed the largest natural sodium sulphate extraction base globally. SAMR's tightened GB/T 6009 purity standards are eliminating sub-99 percent material from export channels. Sichuan and Qinghai provinces concentrate capacity, with Xining-Lhasa railway spurs enabling bulk shipment to coastal processors.
India
Maharashtra and Gujarat detergent corridors absorb expanding sodium sulphate volumes as PLI scheme incentives accelerate domestic chemical manufacturing. BIS IS 255 specifications for detergent-grade material are tightening in parallel with Chinese export standards. Rajasthan's inland salt deposits are piloting solar-assisted evaporation to challenge Qaidam Basin cost structures.
United States
Searles Valley brine operations in California anchor domestic natural supply for glass and detergent manufacturers. EPA emissions oversight of Mannheim furnace operations elevates compliance costs for synthetic-grade producers. Gulf Coast chemical corridors process imported bulk material for regional distribution.
Germany
REACH registration requirements for synthetic-origin sodium sulphate create preferential access for established multinationals with documented substance dossiers. Rhine-Ruhr industrial clusters consume material for detergent compounding and specialty glass applications. ECHA enforcement of carbon-intensity disclosures favors low-carbon lake-derived imports over energy-intensive domestic synthesis.
Sodium Sulphate Market Competitive Environment
Listed leaders compete with private specialists across certification depth and captive resource access. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive salt-lake positions, viscose fiber producers monetizing by-product sulphate streams, and independent extractors dependent on trader-mediated distribution. Strategic moves concentrate on direct procurement contracting with detergent manufacturers and solar-assisted evaporation technology licensing to inland competitors.
Within the integrated chemical tier, China Nafine Group International Co. Ltd. and Grasim Industries Ltd. represent archetypes of state-linked and private conglomerate positioning respectively. Lenzing AG exemplifies the by-product recovery model, converting waste sulphate from viscose operations into merchant-grade supply. These three occupy positions spanning natural extraction dominance, Indian distribution breadth, and circular manufacturing integration.
| Leading Market Players |
|---|
| China Nafine Group International Co. Ltd. |
| Alkim Alkali Kimya |
| Lenzing AG |
| Grasim Industries Ltd. |
| Searles Valley Minerals Inc. |
| Minera de Santa Marta |
| Tata Chemicals Ltd. |
| Kuchuksulphate |
| Saskatchewan Mining and Minerals Inc. |
| Others |
Value Chain & Pricing Dynamics
Zeolite substitution in European detergents is compressing sodium sulphate filler demand while simultaneously redirecting procurement gravity toward India's cost-sensitive powder manufacturers and fragmenting regional pricing benchmarks. This displacement dynamic concentrates volume leverage with Indian detergent compounders in Maharashtra and Gujarat, enabling aggressive contract negotiations against Qaidam Basin suppliers.
Pricing Analysis
Volume-discount tiering structures dominate sodium sulphate procurement, with annual offtake commitments above 10,000 metric tons unlocking 8-12 percent contract concessions from salt-lake operators. Pricing stratifies across pharmaceutical, industrial, and technical grades, with CDSCO and NMPA certification premiums separating premium synthetic supply from commodity lake-derived material. Cost compression in industrial-grade segments is intensifying because Rajasthan's solar-evaporation pilots are eroding Qaidam Basin's historical energy-cost advantage. Detergent manufacturers exhibit extreme price sensitivity, while pharmaceutical-grade buyers prioritize batch certification reliability over unit economics.
Supply Chain Analysis
Inbound logistics costs from Xining-Lhasa railway spurs to Mundra Port have tightened delivered-cost spreads for Indian detergent manufacturers sourcing Chinese lake-derived material. Supply concentrates in China's Qinghai and Sichuan provinces, with secondary extraction in Rajasthan's inland salt deposits and California's Searles Valley. Raw material dependencies center on sodium chloride feedstock, sulphuric acid availability, and thermal energy inputs for Mannheim furnace operations. Single-source vulnerability runs through Qaidam Basin concentration, where SAMR export licensing creates regulatory chokepoints. Distribution feeds from bulk rail shipment into converter-held inventory at detergent manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium sulphate market fragmentation creates specialized entry points as purity mandates split demand into certification-tiered niches. Detergent-grade commoditization contrasts with pharmaceutical-grade premium capture, enabling differentiated positioning strategies.
For Market Incumbents: Consolidate captive salt-lake positions through direct procurement contracting with Indian detergent manufacturers, displacing trader intermediation in Gujarat and Maharashtra. Backward integration into Rajasthan solar-evaporation assets defends margin position against Qaidam Basin cost erosion. SAMR certification renewal cycles create moats against uncertified competitors.
For New Entrants and Emerging Players: Anchor in pharmaceutical-grade purification capabilities serving CDSCO-registered API manufacturers, where 99.5 percent purity thresholds limit supply competition. Rajasthan's emerging solar-assisted extraction corridor offers the most penetrable geography for cost-parity challenges to Chinese imports. Technical licensing partnerships with established crystallization technology providers accelerate market access without furnace capital deployment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian chemical distributors holding BIS IS 255 certification and western India detergent corridor relationships. Five-to-ten year viability hinges on carbon-intensity disclosure differentiation as EU Green Deal procurement criteria mature. Monitor MEE emissions enforcement intensity in China as inflection indicator for synthetic-grade margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt-Lake Assets | Captive Qaidam Basin or Rajasthan extraction secures cost advantage against trader-mediated supply. |
| Pharmaceutical-Grade Certification Investment | CDSCO and NMPA facility approvals unlock premium pricing in API excipient applications. |
| Solar-Assisted Evaporation Licensing | Rajasthan pilot technology transfers enable inland producers to challenge lake-derived cost structures. |
| Direct Procurement Contracting | Grasim Industries-style captive offtake agreements eliminate distributor margins for detergent manufacturers. |
| Carbon-Intensity Disclosure Documentation | EU Green Deal compliance creates preferential access for low-thermal-input salt-lake operations. |
Study Parameters
Initial hypotheses were tested against primary input from detergent procurement managers, glass manufacturing furnace operators, pharmaceutical regulatory affairs leads, and salt-lake extraction plant managers, and refined through secondary validation against Chinese customs export data, Indian BIS certification registries, CDSCO facility inspection records, and REACH substance dossier filings. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Qaidam Basin, Sichuan, Rajasthan, and Searles Valley operations.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub anchored the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and supply-side capacity expansion schedules. Forecast inputs incorporated SAMR purity enforcement trajectories, PLI scheme incentive disbursement patterns, and zeolite substitution rates in European detergent formulations.
Material uncertainties — regulatory purity mandate acceleration, solar-evaporation technology cost curves, and Mannheim furnace natural gas price volatility — sit outside the modeled envelope. Forecasts reflect assumptions about certification cycle durations and trade lane logistics stability. Recalibration cycles align with material shifts in MEE emissions enforcement and EU carbon-border adjustment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Calcium Lactate Market