
 Sintered Steel Market | 2026-2036
Sintered Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Sintered Steel Market Intelligence
The shift towards high-density structural components for automotive and industrial applications is redrawing the competitive landscape. GKN Powder Metallurgy leverages its extensive global manufacturing footprint to serve large automotive original equipment manufacturers. Hoganas AB differentiates through its leadership in advanced iron and metal powder formulations. Sumitomo Electric Industries specializes in sintered components for electrical and electronic systems, particularly in Japan.
Sintered steel is a material produced through powder metallurgy, a process where metal powders are compacted in a die and heated to a temperature below their melting point. This technique creates complex, near-net-shape parts with controlled porosity, eliminating the need for extensive secondary machining. Within applications, machinery components constitute the largest segment due to their use in gears, bearings, and structural parts. Alloy steel variants represent a high-value product category, prized for superior strength and wear resistance in demanding industrial environments.
Component manufacturing is governed by a web of international and national standards, including ISO specifications for powder metallurgy materials. In Europe, REACH regulations scrutinize the chemical composition of metal powders, while the EPA in the United States sets environmental standards for manufacturing facilities. In China, adherence to GB standards is mandatory for market access. Producers must now decide whether to invest in advanced processes like Metal Injection Molding or focus on optimizing conventional powder metallurgy to remain cost-competitive.
Market Dynamics
The push for higher power density and efficiency in automotive and industrial machinery is the central force shaping the market. This drives demand for complex, high-strength sintered steel components, favoring advanced processes like Metal Injection Molding over conventional powder metallurgy methods.
Growth Catalysts
- Metal Injection Molding:This technology enables the production of intricate, high-precision parts, accelerating adoption within the machinery components sector for items like gears and actuators that require tight tolerances.
- Automotive Lightweighting:Vehicle manufacturers use sintered steel for complex powertrain and transmission components to reduce weight and improve fuel efficiency, a trend applicable to both internal combustion and electric vehicles.
- Industrial Policy:Advanced manufacturing initiatives in industrial clusters across Germany and China create sustained demand for high-performance materials capable of meeting stringent operational requirements in automated systems.
Market Restraints
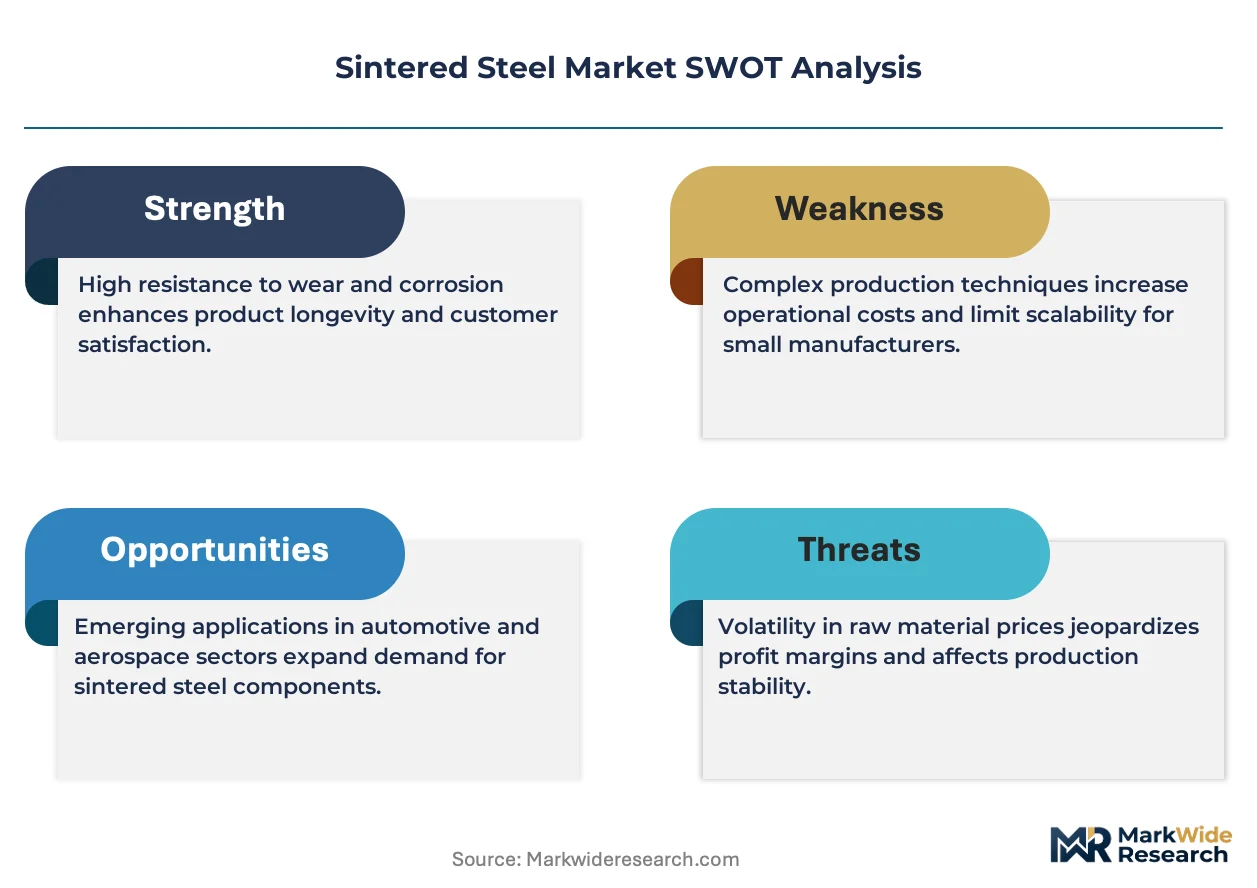
- Input Cost Volatility:The market is sensitive to price fluctuations in raw material inputs, particularly iron powder and alloying elements like nickel, chromium, and molybdenum, which can compress manufacturer margins.
- Technical Performance Limits:The inherent porosity of conventionally sintered parts can limit their fatigue strength and impact resistance compared to components made from wrought or forged steel, precluding some critical applications.
- Substitution from Alternative Processes:Sintered steel faces competition from precision casting and forging for high-strength structural parts and from additive manufacturing for low-volume, highly complex geometries.
Strategic Opportunities
- Electric Vehicle Components:The transition to electric vehicles opens new applications for sintered parts in electric motors, planetary gear sets for reduction drives, and structural components within battery packs.
- Hybrid Material Development:Opportunities exist in creating hybrid processes that combine powder metallurgy with techniques like additive manufacturing to produce functionally graded materials with tailored properties for specific applications.
- Expansion in Industrializing Economies:Markets in Southeast Asia and Eastern Europe represent growth areas as their industrial bases expand, creating new demand for locally sourced, cost-effective machinery components.
Industry Challenges
- High Capital Investment:The acquisition, installation, and qualification of advanced manufacturing equipment, such as high-temperature sintering furnaces and MIM systems, require significant upfront capital expenditure.
- Specialized Skills Gap:A shortage of metallurgists and process engineers with deep expertise in powder metallurgy, die design, and sintering science can constrain a company's ability to innovate and optimize production.
- Navigating Compliance Standards:Adherence to a complex web of standards, including ISO material specifications, European REACH regulations, and EPA environmental rules, adds significant administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sintered Steel Market |
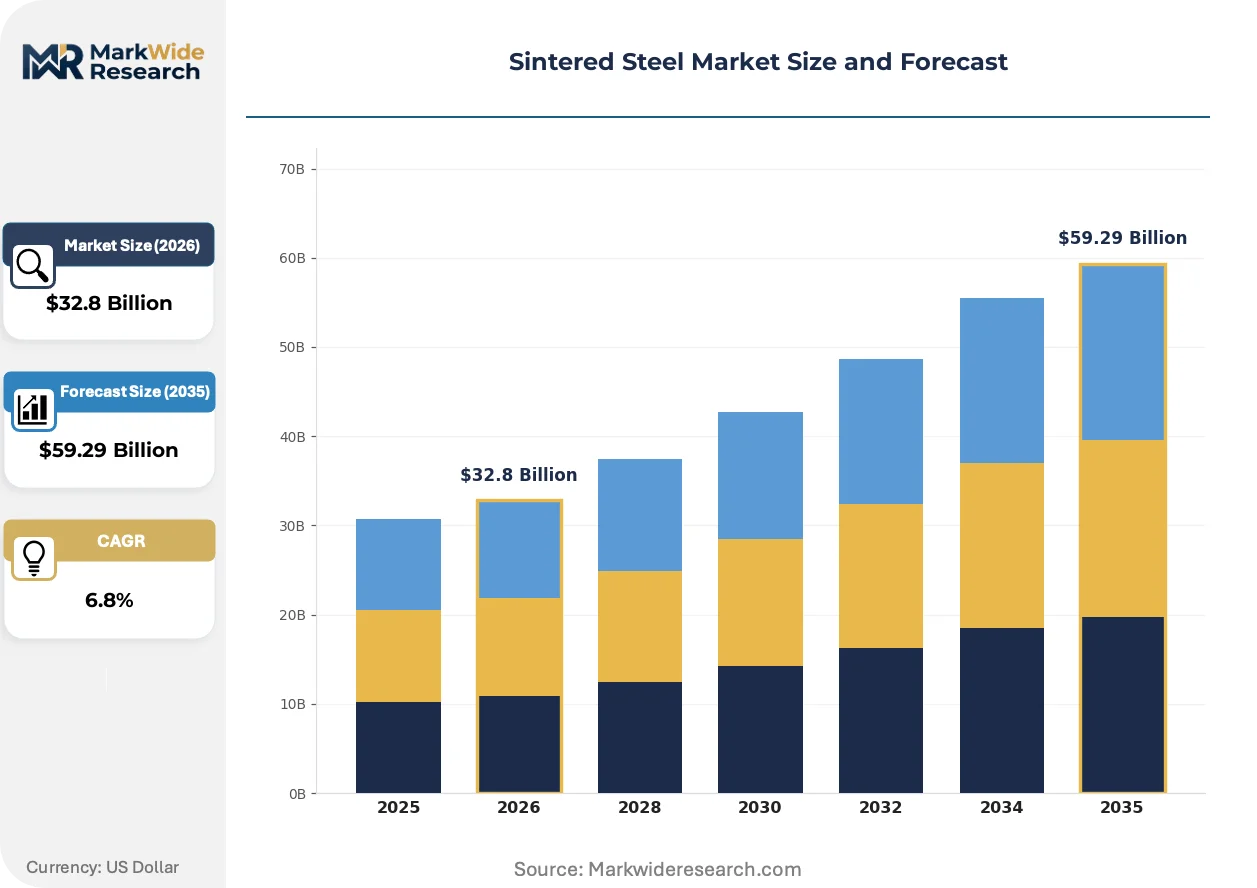
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Stainless Steel, Alloy Steel, Tool Steel, Magnetic Steel Technology: Powder Metallurgy, Hot Isostatic Pressing, Metal Injection Molding, Additive Manufacturing, Cold Isostatic Pressing Application: Machinery Components, Consumer Appliances, Electrical Equipment, Defense Equipment, Oilfield Tools End User Industry: Manufacturing Units, Defense Organizations, Energy Sector, Consumer Goods Firms, Construction Companies |
| Companies Covered | Schunk Sinter Metals, Atlas Pressed Metals, GKN Powder Metallurgy, The Miba Group, SSI Sintered Specialties, Hoganas AB, Sumitomo Electric Industries, AMES Sintering Metallic Components, ASCO Sintering Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sintered Steel Market Strategic Shifts & Innovations
Performance requirements are diverging across the sintered steel landscape. The market is simultaneously pursuing higher-density materials for demanding applications and cost-optimized powders for high-volume, less critical parts, creating distinct value streams and supply chain structures.
High-density sintering processes create components with properties approaching those of wrought steel. Automotive and industrial sectors adopt these for critical structural parts requiring superior fatigue resistance. This technology adoption is bifurcating the market between premium, high-performance components and conventional, cost-focused sintered parts, segmenting supply chains.
Europe's REACH regulation places stringent controls on chemical substances in metal powders, impacting common alloying elements. This forces powder manufacturers to reformulate products or undergo extensive compliance testing for market access. The alloy steel segment is most affected, driving investment in alternative, compliant hardening agents for global product lines.
A shift toward co-development partnerships is displacing transactional procurement for complex components. OEMs are engaging directly with powder metallurgy specialists to design custom parts, bypassing traditional distributors. This collaborative model is most advanced within Germany's machinery sector and Japan's automotive industry, where close supplier integration is prioritized.
Sintered Steel Market Segmentation
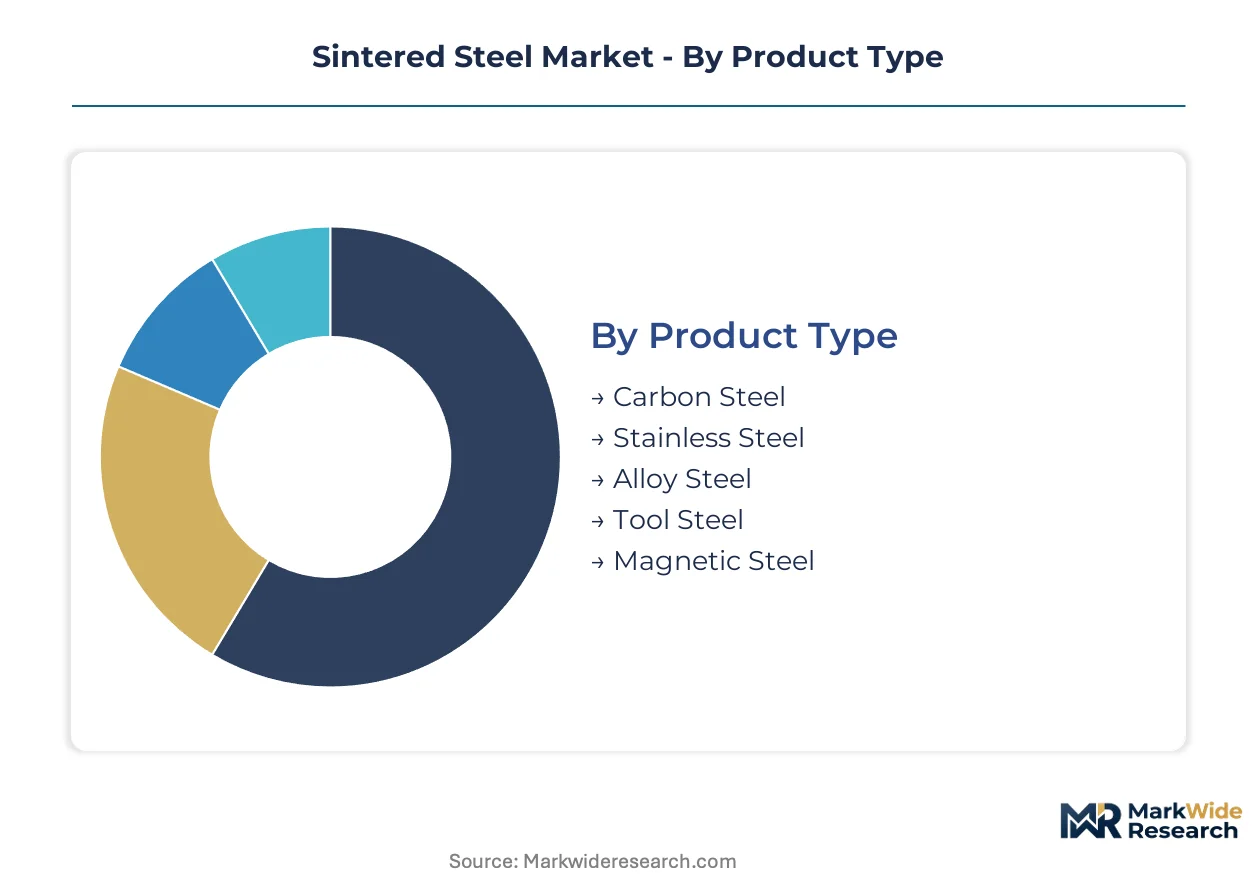
The sintered steel market exhibits diverse structural characteristics across its product types, technologies, applications, and end-user industries. Understanding these distinct segments is critical for manufacturers to align product development with specific demand patterns and regulatory requirements. This segmentation highlights areas of established volume and emerging growth opportunities.
Product Type:
The geographic distribution of product type demand often reflects regional industrial capabilities, with certain variants finding stronger domestic markets in specific countries while others are predominantly export-driven.
- Alloy Steel:These variants incorporate alloying elements like nickel, chromium, and molybdenum to achieve superior strength, hardness, and wear resistance. Demand for alloy steel concentrates in Germany's high-performance machinery sector, driven by stringent operational requirements in industrial automation.
- Carbon Steel:Comprising iron and carbon, this fundamental material offers good machinability and cost-effectiveness for a broad range of applications. Carbon steel components find widespread use in China's automotive industry for high-volume, less critical parts, balancing performance with economic production.
- Stainless Steel:Stainless steel offers corrosion resistance, finding use in medical devices and food processing equipment.
- Tool Steel:Tool steel, known for extreme hardness, is critical for dies, molds, and cutting tools.
- Magnetic Steel:Magnetic steel, engineered for specific magnetic properties, is essential for electric motors and sensors.
Carbon Steel commands the established base. The steepest expansion runs through Alloy Steel.
Technology:
The maturity of various processing technologies dictates their market penetration, with established methods serving broad industrial needs and newer approaches addressing specialized, high-performance niches.
- Metal Injection Molding:This advanced process combines plastic injection molding with powder metallurgy to produce complex, high-density components with exceptional precision. Demand for MIM parts is strong in Japan's electronics and automotive sectors, where miniaturization and intricate geometries are paramount for new product designs.
- Powder Metallurgy:The conventional method involves compacting metal powders and sintering them below their melting point to form near-net-shape parts. This foundational technology is widely adopted across industrial clusters in China for cost-effective production of gears and structural elements.
- Hot Isostatic Pressing:HIP applies pressure and temperature to densify sintered parts, improving mechanical properties and eliminating voids.
- Additive Manufacturing:Additive manufacturing builds components layer by layer from metal powders, enabling design freedom for customized, low-volume parts.
- Cold Isostatic Pressing:CIP uses an elastomer mold and hydrostatic pressure to compact powders, producing larger, uniform green parts before sintering.
Established manufacturing relies heavily on Powder Metallurgy, while Metal Injection Molding is rapidly gaining share in precision applications.
Application:
The volume requirements for sintered steel vary significantly across different applications, with some sectors demanding mass production for standard components and others seeking specialized solutions for critical functions.
- Machinery Components:This segment includes gears, bearings, and structural parts for industrial equipment, experiencing sustained demand due to the need for robust and precise mechanical elements. The manufacturing sector in Germany consistently requires high volumes of sintered steel for advanced industrial machinery and robotics.
- Electrical Equipment:Sintered steel is utilized in motor cores, sensors, and connectors for various electrical systems, benefiting from its magnetic properties and ability to form intricate shapes. Sumitomo Electric Industries significantly contributes to this segment in Japan, supplying specialized components for power generation and transmission.
- Consumer Appliances:Sintered parts in domestic appliances like washing machines offer cost-effective functional components.
- Defense Equipment:High-strength, wear-resistant sintered components are crucial for firearms, armored vehicles, and aerospace in defense.
- Oilfield Tools:Demanding oil and gas environments require resilient sintered steel for drill bits, pumps, and downhole tools.
Machinery Components represent the largest demand pool, with Electrical Equipment showing significant expansion.
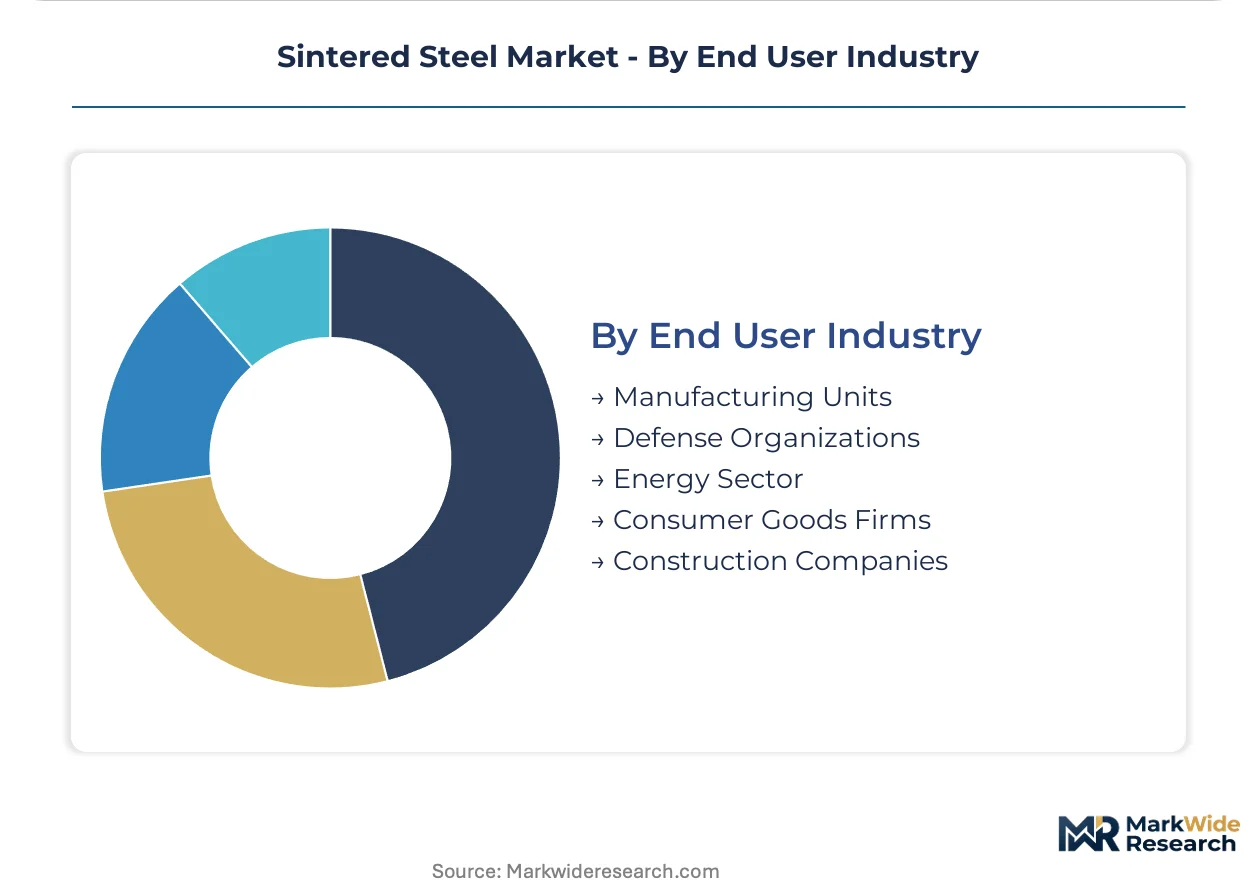
End User Industry:
The margin profiles across end-user industries influence material selection and manufacturing processes, with high-value sectors prioritizing performance and reliability over initial cost, while others focus on cost-efficiency for mass-market products.
- Manufacturing Units:This broad category encompasses diverse industries, including automotive, heavy machinery, and general industrial production, driving consistent demand for a wide range of sintered components. Large manufacturing hubs in China and Germany are primary consumers, integrating sintered parts into their production lines.
- Energy Sector:Applications in oil and gas, renewable energy, and power generation demand high-performance sintered steel for components operating under extreme conditions. The energy industry requires robust materials for turbines and exploration equipment, particularly in regions with significant resource extraction.
- Defense Organizations:Defense organizations procure sintered steel for military vehicles, weaponry, and aerospace, valuing durability and precision.
- Consumer Goods Firms:Consumer goods firms utilize sintered steel for cost-effective, high-volume components in their product lines.
- Construction Companies:Sintered parts are incorporated into heavy construction equipment, tools, and infrastructure, requiring strength and wear resistance.
Manufacturing Units form the foundational demand base, with the Energy Sector exhibiting robust growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sintered steel market's supply-side concentration dictates regional demand patterns. Major manufacturing hubs in Germany, China, and Japan drive significant consumption. These regions also lead in the adoption of advanced powder metallurgy technologies.
Germany
Demand for alloy steel components is strong in Germany's high-performance machinery sector. European REACH regulations impose strict controls on chemical substances in metal powders. Industrial clusters in Bavaria and Baden-Württemberg consistently require high volumes of sintered steel for advanced industrial automation.
China
China's automotive industry drives substantial demand for carbon steel components, balancing performance with economic production. Adherence to GB standards is mandatory for market access, influencing material specifications. Manufacturing hubs in the Yangtze River Delta utilize conventional powder metallurgy for cost-effective gear production.
Japan
Japan's electronics and automotive sectors show strong demand for Metal Injection Molding parts, prioritizing miniaturization and intricate geometries. METI initiatives support advanced materials research and development within the country. Tokyo and Osaka's industrial areas are centers for specialized sintered components for power generation.
United States
The United States industrial sector requires sintered steel for various machinery components and structural parts. The EPA sets environmental standards for manufacturing facilities, impacting production processes. Industrial centers in the Midwest and Southeast consume significant volumes for automotive and general industrial applications.
India
India's expanding industrial base creates new demand for locally sourced, cost-effective machinery components. The PLI scheme encourages domestic manufacturing and technology adoption in critical sectors. Manufacturing zones near Chennai and Pune are emerging as key consumption areas for sintered parts.
Sintered Steel Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the sintered steel market. The competitive landscape shows a tiered structure, with global specialists focusing on advanced processes and regional players optimizing for volume. Three strategic archetypes include integrated powder metallurgy giants, specialized MIM component manufacturers, and regional cost-efficient producers. Dominant competitive moves include strategic partnerships for co-development and targeted capacity expansion in high-growth segments.
Within the integrated powder metallurgy giants, GKN Powder Metallurgy represents a player leveraging an extensive global manufacturing footprint to serve large automotive original equipment manufacturers. Hoganas AB exemplifies leadership in advanced iron and metal powder formulations, anchoring the raw material supply chain for high-performance applications. Sumitomo Electric Industries occupies a position as a specialist in sintered components for electrical and electronic systems, particularly active in Japan's advanced industrial sectors. These companies collectively demonstrate the market's differentiation across material science, manufacturing scale, and application-specific expertise.
| Leading Market Players |
|---|
| Schunk Sinter Metals |
| Atlas Pressed Metals |
| GKN Powder Metallurgy |
| The Miba Group |
| SSI Sintered Specialties |
| Hoganas AB |
| Sumitomo Electric Industries |
| AMES Sintering Metallic Components |
| ASCO Sintering Co. |
| Others |
Cost & Logistics Intelligence
Scale economies in powder metallurgy production drive supply concentration, which in turn establishes regional price floors for high-volume sintered steel components. This dynamic influences investment in advanced processes like Metal Injection Molding.
Pricing Analysis
REACH regulations dictate the pricing tier structure for alloy steel, particularly in Europe, influencing material formulations. Pricing is predominantly contract-based long-term offtake for large OEM buyers, with some per-unit transactional models for smaller batches. Price differentiation stems from material grade and customization level for specific applications. Pricing softness reflects input cost volatility in raw materials like nickel and chromium. Automotive manufacturers exhibit high price sensitivity for carbon steel parts, while specialized machinery components prioritize performance over initial cost.
Supply Chain Analysis
Critical raw material dependencies for alloying elements like nickel and chromium anchor the sintered steel supply chain in specific geographies. China and Germany concentrate the production of base metal powders and high-volume sintered parts. The supply chain faces structural risk from commodity price volatility for key inputs. Downstream distribution runs through direct OEM partnerships for complex components and regional distributors for standard parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The increasing consolidation among large automotive OEMs is shifting buyer power within the sintered steel market, demanding greater supplier integration and cost efficiency. This trend redefines strategic priorities for all market participants.
For Market Incumbents:Secure long-term supply agreements with major automotive and industrial equipment manufacturers to lock in volume. Invest in advanced Metal Injection Molding capabilities in Germany and Japan to meet demand for high-precision components, countering substitution from additive manufacturing. Control upstream raw material sourcing to mitigate input cost volatility. Expand production capacity in emerging industrializing economies like India to serve new regional demand.
For New Entrants and Emerging Players:Certification fast-track pathways for new material formulations offer a route to market entry, especially for compliant hardening agents under REACH. Target the Electric Vehicle components segment in Southeast Asia for new sintered parts in motors and gear sets. Focus on hybrid material development combining powder metallurgy with additive manufacturing to address niche applications. A direct-to-OEM sales approach, emphasizing custom design and technical support, can penetrate established supply chains.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized MIM component manufacturers due to long product qualification cycles and deep OEM integration. Investors should prioritize firms with strong intellectual property in advanced powder formulations and high-density sintering processes. The long-term viability favors entities capable of navigating stringent regulatory environments across Europe and China. Watch for sustained increases in R&D spending on hybrid materials as an inflection indicator for future market leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in MIM | Increasing Metal Injection Molding capacity addresses growing demand for intricate parts in Japan's electronics sector. |
| Raw Material Backward Integration | Controlling iron powder and alloying element supply mitigates input cost volatility for global manufacturers. |
| Co-development Partnerships | Engaging with OEMs for custom part design accelerates adoption of sintered steel in Germany's machinery sector. |
| Electric Vehicle Component R&D | Developing new sintered parts for EV motors and gear sets capitalizes on the automotive industry's transition. |
| Compliance Technology Investment | Investing in REACH-compliant material formulations ensures market access for alloy steel in European markets. |
Research Approach
Operator-level perspectives from R&D metallurgists, procurement managers at automotive OEMs, and plant engineers in industrial manufacturing units anchored the qualitative base. This primary intelligence was triangulated with secondary validation from customs data, ISO material specifications, and regulatory filings. Bottom-up data collection on production volumes combined with top-down market sizing provided a robust data foundation.
Sensitivity analysis integrated various macroeconomic scenarios across the analysis window, influencing demand projections for sintered steel. The analytical framework modeled market segmentation by product type, technology, application, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected technological adoption rates. Key forecast inputs included automotive production forecasts and industrial machinery investment cycles.
Decision-makers should treat outputs as directional under current geopolitical stability assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding raw material price stability and continued industrial growth in China. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Battery Alloys Market