
 US Green Steel Market | 2026-2036
US Green Steel Market Size, Share, and Industry Trends Forecast 2026-2036
US Green Steel Market Insights
Product bundling of carbon credits with certified green steel shipments is realigning procurement contracts toward long-term offtake agreements rather than spot-market purchasing. Nucor Corporation leverages its electric arc furnace network to anchor supply commitments from construction and energy infrastructure buyers. Steel Dynamics sustains cost competitiveness through scrap optimization and regional mill placement near southeastern automotive plants. Boston Metal differentiates via molten oxide electrolysis technology that eliminates direct carbon emissions from the reduction process entirely.
US green steel denotes flat, long, alloy, or recycled steel products manufactured with substantially reduced carbon dioxide intensity, typically below one ton of CO2 equivalent per ton of crude steel equivalent, achieved through electric arc furnace processing fed by renewable power, hydrogen direct reduction, or scrap utilization. Its primary purpose is to satisfy Scope 3 emissions reduction targets for construction firms, automotive manufacturers, and energy infrastructure developers facing supply chain decarbonization mandates. Electric arc furnace production currently occupies the dominant share of installed US capacity, though hydrogen direct reduction represents the fastest-growing method as electrolyzer costs decline and hydrogen hubs mature. Flat steel commands the largest application volume due to automotive and construction sheet demand, while recycled steel concentrates margin pools where scrap quality premiums align with stringent emissions accounting protocols.
The Inflation Reduction Act, administered through the Department of Energy and the Treasury, shapes demand via production tax credits for clean hydrogen and advanced manufacturing facilities. EPA greenhouse gas reporting requirements and anticipated carbon border adjustments compel domestic mills to document emissions intensity through certified lifecycle assessments. OSHA process safety standards govern hydrogen handling at new direct reduction plants, adding compliance cost layers that favor scaled operators. Stakeholders must monitor hydrogen hub offtake contracting timelines and state-level renewable portfolio standards that determine whether promised carbon intensity reductions materialize in actual grid-connected production.
Market Dynamics
The Inflation Reduction Act's clean manufacturing tax credits are redirecting capital toward hydrogen direct reduction facilities, compressing the payback period for near-zero-emission steelmaking investments and restructuring procurement contract durations across automotive and energy infrastructure supply chains.
Growth Catalysts
- Clean Hydrogen Production Tax Credits:IRA provisions administered through the Treasury subsidize electrolyzer operations, cutting delivered hydrogen costs for direct reduction plants in Texas and Louisiana.
- Automotive OEM Decarbonization Mandates:Michigan and Ohio electric vehicle manufacturers now specify sub-one-ton-CO2 flat steel for chassis and body panel procurement, creating guaranteed offtake volumes.
- Great Lakes Scrap Network Density:Concentrated ferrous scrap supply and renewable grid interconnections in Indiana, Illinois, and Wisconsin lower feedstock logistics costs for electric arc furnace operators.
Market Restraints
- Green Hydrogen Cost Volatility:Electrolyzer electricity input costs swing with regional renewable generation intermittency, destabilizing hydrogen direct reduction economics against natural gas-based alternatives.
- Midwest Generation Bottlenecks:Transmission congestion between Iowa wind farms and Indiana mill sites limits clean power offtake, forcing reliance on marginal grid mixes during peak production.
- Scrap Quality Degradation:Contaminated post-consumer ferrous feedstock raises residual element levels in finished steel, constraining alloy-grade output for precision automotive applications.
Strategic Opportunities
- Southeastern Solar-Hydrogen Integration:Alabama and Georgia photovoltaic buildouts paired with Gulf Coast hydrogen hubs enable new direct reduction capacity with captive renewable supply.
- Federal Buy Clean Procurement Rules:General Services Administration embodied carbon thresholds for federally funded construction projects guarantee demand floors for certified low-emission structural steel.
- Molten Oxide Electrolysis Convergence:Electrochemical reduction technology paired with solid oxide electrolysis eliminates coking coal entirely, opening premium pricing tiers for zero-direct-emission specialty alloys.
Industry Challenges
- Hydrogen Handling Certification Delays:OSHA process safety standards for high-pressure hydrogen storage and pipeline transport extend facility commissioning timelines by 12-18 months.
- Scope 3 Emissions Accounting Fragmentation:Inconsistent lifecycle assessment methodologies between EPA greenhouse gas reporting protocols and private certification bodies create audit complexity for multi-source steel buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Green Steel Market |
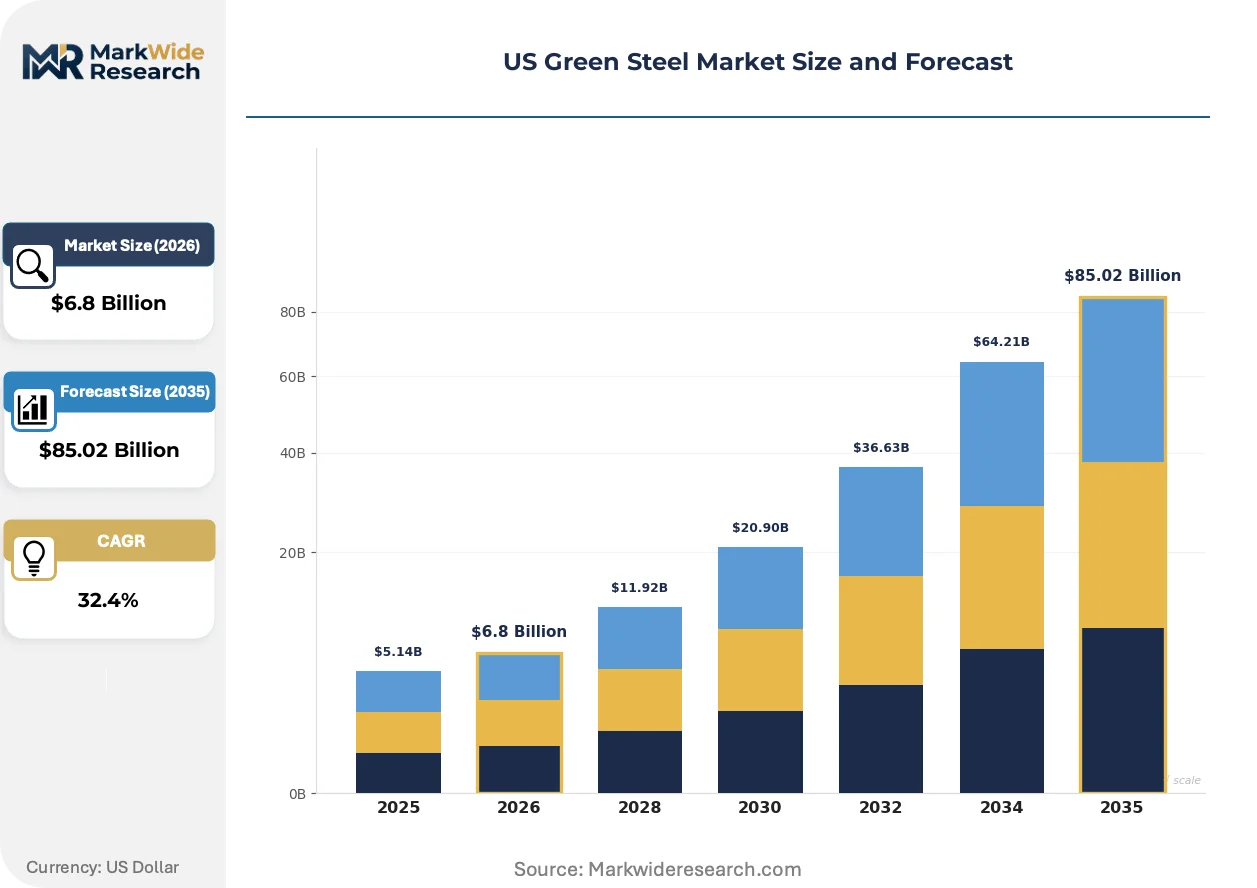
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $85.02 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Electric Arc Furnace, Hydrogen Direct Reduction, Blast Furnace, Scrap Utilization Application: Construction, Automotive, Packaging, Energy Infrastructure Material Type: Flat Steel, Long Steel, Alloy Steel, Recycled Steel Customer Type: Manufacturers, Distributors, End Users, Service Providers |
| Companies Covered | U.S. Steel Corporation, Steel Dynamics, Nucor Corporation, Green Steel Group Inc., Electra, Boston Metal, ArcelorMittal, Carbon Re, H2 Green Steel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Green Steel Market Trends and Innovations
Electrification of primary steelmaking is collapsing the traditional coke oven-blast furnace value chain, forcing incumbents to retool around scrap optimization, hydrogen reduction, or electrochemical cell architectures.
Modular hydrogen direct reduction units are decentralizing steel production geography by enabling mid-scale facilities near renewable generation clusters rather than coal deposits. Automotive OEMs in Ohio and Kentucky are contracting directly with these distributed plants for just-in-time flat steel delivery. This proximity is compressing inventory carrying costs and tightening emissions traceability through shortened transport legs.
EPA greenhouse gas reporting requirements are mandating facility-level emissions disclosure for steel mills above 25,000 tons annual CO2 equivalent, compelling capital expenditure into continuous emissions monitoring systems. The regulation is accelerating consolidation among smaller electric arc furnace operators unable to absorb compliance overhead. Great Lakes corridor mills are responding by pooling certification costs through industry associations.
Long-term offtake agreements are displacing spot-market purchasing for certified low-carbon steel, with construction firms and automotive suppliers locking in decade-long supply contracts at fixed premiums. This contractual shift is transferring price risk from buyers to producers and concentrating procurement relationships around three to five verified low-emission suppliers. The pattern is most pronounced in federally funded infrastructure projects subject to Buy Clean mandates.
US Green Steel Market Segmentation
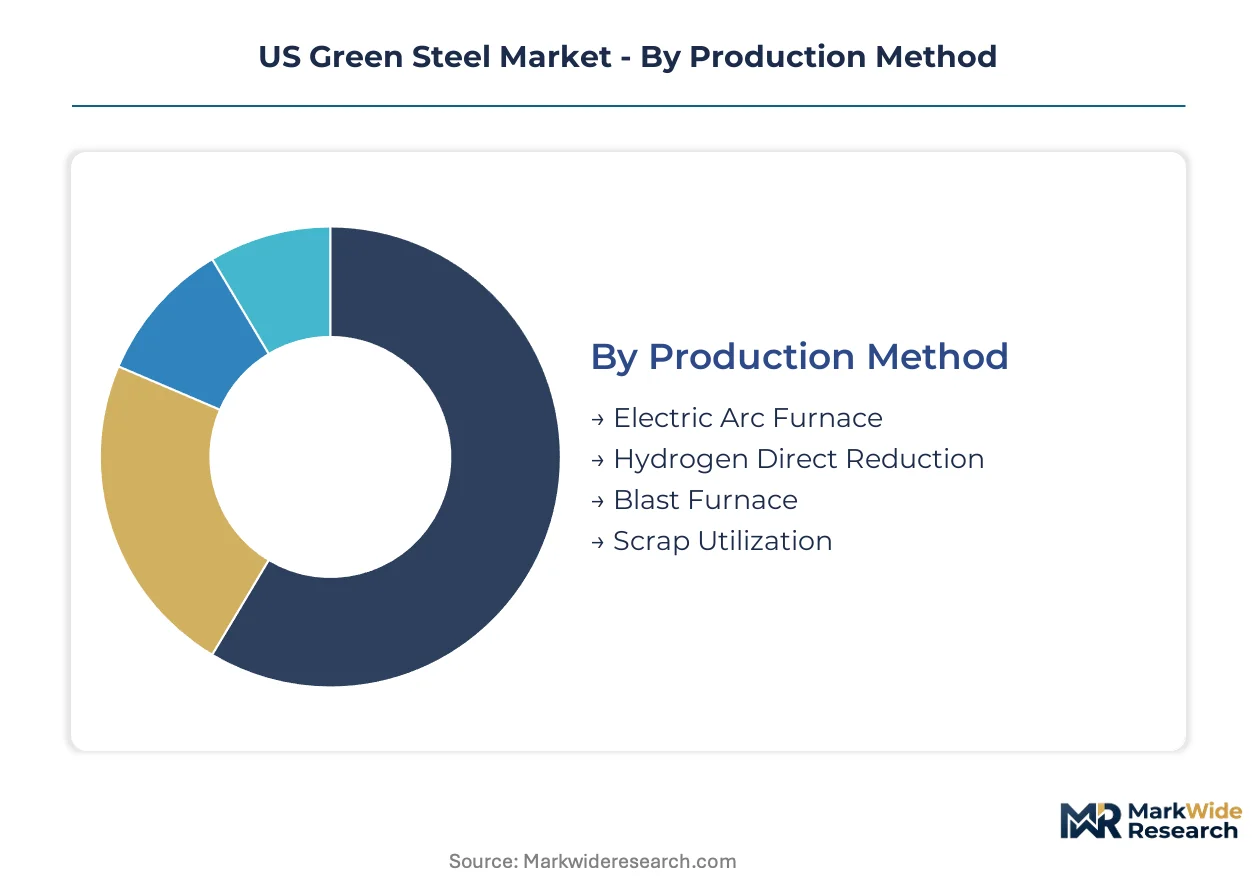
Segmentation in the US green steel market reveals how decarbonization pathways diverge across production technologies and end-use specifications. Procurement contracts increasingly specify both carbon intensity thresholds and material grades, forcing suppliers to align capacity with distinct buyer requirements rather than commoditized volume plays.
Production Method:
Production methods span standalone retrofit installations versus integrated greenfield complexes, with integration depth determining capital efficiency and emissions traceability.
- Electric Arc Furnace:Melts recycled scrap using renewable electricity, achieving sub-one-ton-CO2 intensity when grid-connected to Texas or Iowa wind farms. Michigan and Ohio automotive OEMs anchor demand through long-term offtake agreements specifying EAF-certified flat steel for EV chassis.
- Hydrogen Direct Reduction:Replaces coke with green hydrogen in shaft furnaces, eliminating Scope 1 emissions entirely. Gulf Coast hydrogen hub development in Texas and Louisiana is compressing delivered hydrogen costs for new capacity, though OSHA certification delays extend commissioning timelines.
- Blast Furnace:Traditional coke-based reduction with carbon capture retrofits, maintaining output for construction-grade long products where cost sensitivity limits green premiums.
- Scrap Utilization:Standalone scrap preprocessing and quality upgrading for direct feed into EAF or BOF operations, concentrating in Great Lakes corridor mills near Indiana and Illinois scrap networks.
Electric Arc Furnace leads volumes today; Hydrogen Direct Reduction is gaining share fastest.
Application:
Application segmentation tracks how embodied carbon regulations reshape demand concentration across federally funded and private procurement channels.
- Construction:Structural beams and rebar for commercial and infrastructure projects subject to General Services Administration Buy Clean thresholds. Federal procurement rules now mandate sub-1.5-ton-CO2 steel for buildings over 10,000 square feet.
- Automotive:Body panels and chassis components where Michigan and Ohio EV manufacturers specify near-zero-emission flat steel to meet Scope 3 reduction targets.
- Packaging:Tinplate and cold-rolled sheet for food and industrial containers, with lower carbon intensity requirements than automotive or construction tiers.
- Energy Infrastructure:Pipeline-grade long steel and offshore wind tower sections, where IRA production tax credits subsidize domestic content sourcing.
Construction commands the largest contract volumes; Automotive is expanding most quickly.
Material Type:
Material type segmentation reflects how form factor determines both production method compatibility and emissions accounting precision.
- Flat Steel:Hot-rolled and cold-rolled sheet for automotive body panels and construction cladding. Ohio and Kentucky mills specialize in just-in-time delivery to southeastern automotive plants, compressing transport emissions.
- Long Steel:Beams, bars, and structural sections for commercial construction and energy infrastructure. Indiana and Illinois EAF operators dominate through scrap-fed production optimized for rebar and wide-flange beams.
- Alloy Steel:High-performance grades with precise chemistry requirements for precision automotive and aerospace applications, constrained by scrap quality limitations on residual element control.
- Recycled Steel:Certified post-consumer content products with verified lifecycle emissions documentation, commanding premiums where corporate sustainability mandates require supply chain transparency.
Flat Steel leads volumes today; Recycled Steel is climbing the fastest.
Customer Type:
Customer type segmentation distinguishes how procurement sophistication and contract duration vary across the value chain.
- Manufacturers:Automotive OEMs and construction fabricators with dedicated sourcing teams negotiating decade-long offtake agreements at fixed green premiums.
- Distributors:Regional steel service centers aggregating demand from smaller fabricators, limited by fragmented certification requirements across multiple mill sources.
- End Users:Direct procurement by federal agencies and large developers subject to Buy Clean mandates, bypassing distributor markups for certified low-carbon structural products.
- Service Providers:Engineering and procurement contractors managing steel sourcing for infrastructure projects, absorbing compliance documentation burdens on behalf of public sector clients.
Manufacturers lead volumes today; End Users are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US steelmaking originated in Pittsburgh's Monongahela Valley during the 1870s, establishing the technological and labor foundations that persist across today's Great Lakes industrial corridor. The sector's geographic evolution tracks energy transitions from coal to natural gas and now toward renewable-powered electric arc furnaces and hydrogen direct reduction.
Great Lakes Industrial Corridor
Indiana, Illinois, and Wisconsin concentrate the nation's highest electric arc furnace capacity, fed by dense ferrous scrap networks and renewable grid interconnections. EPA greenhouse gas reporting requirements mandate facility-level emissions disclosure for mills above 25,000 tons annual CO2 equivalent. Cleveland-Cliffs operates integrated flat-rolled facilities in Burns Harbor, Indiana, serving Michigan automotive OEMs with certified low-carbon sheet steel.
Southeastern Manufacturing Belt
Alabama and Georgia photovoltaic buildouts paired with Gulf Coast hydrogen hubs enable new direct reduction capacity with captive renewable supply. OSHA process safety standards govern hydrogen handling at these facilities, extending commissioning timelines by 12-18 months. Nucor Corporation anchors regional supply commitments from Kentucky and Tennessee automotive assembly plants through its Blytheville, Arkansas mill network.
Texas-Louisiana Hydrogen Hub Zone
Gulf Coast hydrogen production tax credits under the Inflation Reduction Act subsidize electrolyzer operations, cutting delivered hydrogen costs for direct reduction plants. FERC interstate pipeline regulations shape hydrogen transport economics between production and consumption nodes. H2 Green Steel and emerging developers target Beaumont-Port Arthur industrial zones for shaft furnace complexes serving energy infrastructure demand.
Ohio River Valley
Kentucky and Ohio host precision flat steel finishing operations supplying just-in-time delivery to southeastern automotive plants. State-level renewable portfolio standards determine whether promised carbon intensity reductions materialize in actual grid-connected production. Steel Dynamics sustains cost competitiveness through scrap optimization and regional mill placement near Cincinnati and Columbus manufacturing clusters.
Pacific Northwest
Washington and Oregon hydroelectric resources support emerging electrochemical reduction pilots targeting zero-direct-emission specialty alloys. Boston Metal differentiates via molten oxide electrolysis technology that eliminates direct carbon emissions from the reduction process entirely. Federal Buy Clean procurement rules guarantee demand floors for certified low-emission structural steel in federally funded infrastructure projects across the region.
US Green Steel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and offtake contract duration. The vendor base organizes around three strategic tiers: integrated legacy producers with electric arc furnace retrofit capacity, pure-play hydrogen direct reduction entrants, and electrochemical technology specialists pursuing zero-emission pathways. Consolidation pressures favor scaled operators capable of absorbing EPA compliance overhead and OSHA hydrogen handling certification costs. Dominant competitive moves include long-term offtake contracting with automotive OEMs and strategic positioning near hydrogen hub infrastructure.
Among integrated legacy producers, U.S. Steel Corporation and Steel Dynamics exemplify the scale-driven archetype with established electric arc furnace networks and regional mill placement strategies. Nucor Corporation anchors the premium-tier vector through scrap-fed production optimization and construction sector offtake concentration. Boston Metal and Electra occupy positions within the electrochemical technology tier, representing pathways that eliminate direct reduction emissions entirely. H2 Green Steel exemplifies the hydrogen hub-aligned entrant archetype targeting Gulf Coast production nodes.
| Leading Market Players |
|---|
| U.S. Steel Corporation |
| Steel Dynamics |
| Nucor Corporation |
| Green Steel Group Inc. |
| Electra |
| Boston Metal |
| ArcelorMittal |
| Carbon Re |
| H2 Green Steel |
| Others |
Pricing and Supply Chain Analysis
Green hydrogen feedstock costs cascade through three distinct pricing tiers for finished flat steel, with IRA-subsidized electrolyzer operations in Texas and Louisiana compressing delivered hydrogen expenses for direct reduction plants serving Michigan automotive OEMs.
Pricing Analysis
Long-term offtake contracting dominates transaction structures, with decade-spanning agreements locking in fixed green premiums above spot-market baselines. Price differentiation hinges on certified carbon intensity thresholds and scrap quality grades, with sub-one-ton-CO2 products commanding substantial premiums over standard EAF output. Cost compression in hydrogen direct reduction is intensifying because electrolyzer electricity input costs swing with renewable generation intermittency. Federal construction contractors show least price sensitivity due to Buy Clean mandate compliance requirements, while regional distributors face acute margin pressure from fragmented certification costs.
Supply Chain Analysis
Regional distribution centers cluster along the Great Lakes industrial corridor, with Indiana and Illinois hubs feeding just-in-time delivery networks for Ohio and Kentucky automotive assembly plants. Supply concentrates in the US Gulf Coast hydrogen hub zone, the Great Lakes scrap network, and the Ohio River Valley finishing corridor. Raw material dependencies center on high-purity ferrous scrap, green hydrogen from electrolyzer arrays, and renewable electricity offtake contracts. Single-source vulnerability runs through concentrated electrolyzer equipment suppliers for hydrogen direct reduction capacity. Distribution runs through mill-direct relationships with automotive OEMs and construction fabricators, bypassing traditional service center intermediaries for certified low-carbon grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US green steel market functions as a regulatory compounder where Inflation Reduction Act clean manufacturing tax credits and EPA greenhouse gas reporting mandates continuously ratchet demand for verified low-emission supply.
For Market Incumbents: To counter hydrogen direct reduction entrants capturing automotive offtake volumes, legacy EAF operators should anchor backward integration into captive scrap preprocessing and quality upgrading facilities near Indiana and Illinois feedstock networks. Certification investment into ISO-compliant lifecycle assessment protocols defends position against emerging electrochemical specialists. For New Entrants and Emerging Players: Direct-to-OEM digital contracting platforms offer the most penetrable route for mid-scale hydrogen direct reduction developers, bypassing distributor markups and capturing margin pools in Michigan and Ohio EV chassis procurement. White-space targets include southeastern solar-hydrogen integrated facilities serving Alabama and Georgia photovoltaic buildouts, plus federal infrastructure project direct bidding enabled by Buy Clean procurement rule fluency. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA compliance overhead and OSHA hydrogen handling certification costs exceed smaller EAF operator absorption capacity. Long-term viability across the analysis window favors scaled operators with verified low-carbon supply chains and locked automotive offtake. Acquisition target archetype: regional EAF mills with renewable grid interconnections and underutilized flat-rolled capacity. The signal to watch is hydrogen hub offtake contracting timelines as inflection indicator for direct reduction economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Preprocessing | Cleveland-Cliffs and Steel Dynamics secure feedstock quality control against contaminated post-consumer supply degradation. |
| Hydrogen Hub Alignment | H2 Green Steel and emerging developers position shaft furnace complexes near Beaumont-Port Arthur electrolyzer clusters. |
| Long-term Offtake Contracting | Nucor Corporation locks construction and automotive procurement relationships around decade-spanning fixed-premium agreements. |
| Molten Oxide Electrolysis Scale-Up | Boston Metal eliminates direct carbon emissions entirely, opening premium pricing tiers for zero-emission specialty alloys. |
| Buy Clean Procurement Certification | Federal compliance documentation capabilities guarantee demand floors from General Services Administration infrastructure projects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EAF plant managers, automotive OEM procurement directors, hydrogen hub project developers, and federal agency sustainability officers with secondary validation through EIA electricity generation data, EPA greenhouse gas reporting protocols, SEC steel producer filings, and IRA tax credit implementation guidance from Treasury and DOE. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates.
Segment-weighting approaches applied differential growth assumptions across production methods, with hydrogen direct reduction assigned accelerated penetration curves reflecting electrolyzer cost decline trajectories, while electric arc furnace expansion tracked renewable grid interconnection buildout schedules. Application-level modeling distinguished automotive OEM decarbonization mandate stringency from construction sector Buy Clean compliance thresholds. CAGRs derived from installed capacity forecasts against demand-pull scenarios across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for molten oxide electrolysis commercialization or carbon capture retrofits would alter the outlook for hydrogen direct reduction market share. Forecasts reflect assumptions regarding IRA credit continuity, state renewable portfolio standard achievement, and scrap quality network stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Maraging Steel Market