
 United States Ceramics Tableware Market | 2026-2036
United States Ceramics Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ceramics Tableware Market Analytics
Asset-light leasing models for commercial-grade kiln equipment is tilting competitive dynamics toward mid-sized manufacturers that avoid capital-intensive infrastructure. Mikasa leverages direct-to-hotel procurement contracts to sustain volume stability across hospitality cycles. Lenox Corporation anchors its position through heritage brand equity in bone china giftware. Homer Laughlin China dominates institutional foodservice channels with durable vitrified porcelain engineered for high-temperature commercial dishwashers.
United States ceramics tableware comprises fired clay bodies—porcelain, stoneware, earthenware, and bone china—shaped through jiggering, slip casting, or pressing, then glazed and kiln-fired above 1,200°C to achieve vitrification, mechanical strength, and food-safe surfaces for dining and food presentation. Dinnerware and serveware categories concentrate the highest margin pools, with bone china commanding premium positioning in hotel and fine-dining procurement. Earthenware competes aggressively on price in casual household segments where microwave and dishwasher compatibility drives replacement cycles. Online retail channels are displacing department store dominance as hospitality buyers shift toward bulk direct purchasing and consumers research glaze chemistry and origin transparency.
The FDA governs food-contact surface safety through 21 CFR 175.300, while California Proposition 65 enforces lead and cadmium disclosure requirements that shape glaze formulation R&D priorities. EPA air quality standards for ceramic kiln emissions, particularly in Ohio and West Virginia manufacturing clusters, add compliance costs that favor producers with advanced baghouse filtration and regenerative thermal oxidizer investments. Stakeholders must monitor evolving state-level extended producer responsibility proposals and electrification incentives that could reshape kiln energy sourcing decisions.
Market Dynamics
California's Title 20 appliance efficiency framework is pressuring kiln energy standards nationwide, forcing manufacturers to reconfigure firing cycles and thermal oxidizer investments while hospitality construction concentrates demand in the southern Sun Belt corridor.
Growth Catalysts
- Fine-casual restaurant expansion:Experiential dining elevates plate presentation standards, driving ceramic tableware procurement as chains prioritize Instagram-worthy serveware for guest engagement.
- EPA air quality enforcement:Stricter emissions standards in Ohio and West Virginia manufacturing clusters favor producers with advanced baghouse filtration, consolidating competitive advantage among compliant mid-sized manufacturers.
- Slip casting automation:Robotic glaze application and precision mold technologies reduce defect rates while enabling complex geometries previously uneconomical at scale.
Market Restraints
- Natural gas price volatility:Kiln firing consumes 35-40% of production energy; input cost spikes compress margins for gas-dependent producers without long-term supply contracts.
- Ohio-West Virginia supply concentration:Over 60% of domestic vitrified porcelain capacity clusters in these states, creating geographic risk from regional weather events or labor disruptions.
- California Proposition 65 compliance friction:Lead and cadmium disclosure requirements add formulation R&D costs and delay product launches for non-specialized manufacturers.
Strategic Opportunities
- Texas and Florida hospitality construction:Sun Belt corridor development concentrates demand for durable porcelain serveware in high-traffic hotel and resort foodservice operations.
- Electrification incentives:State-level extended producer responsibility proposals and grid decarbonization programs could subsidize electric kiln retrofits, lowering carbon intensity for early adopters.
- Direct-to-hotel procurement platforms:Bulk purchasing portals bypass traditional distributor markups, capturing margin previously lost to multi-tier channel structures.
Industry Challenges
- Specialized kiln operator scarcity:Firing curve optimization requires tacit knowledge of clay body vitrification behavior; apprenticeship pipelines have collapsed in traditional manufacturing regions.
- Regenerative thermal oxidizer capex burden:EPA compliance mandates multi-million dollar filtration investments that strain balance sheets of sub-$50M revenue producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ceramics Tableware Market |
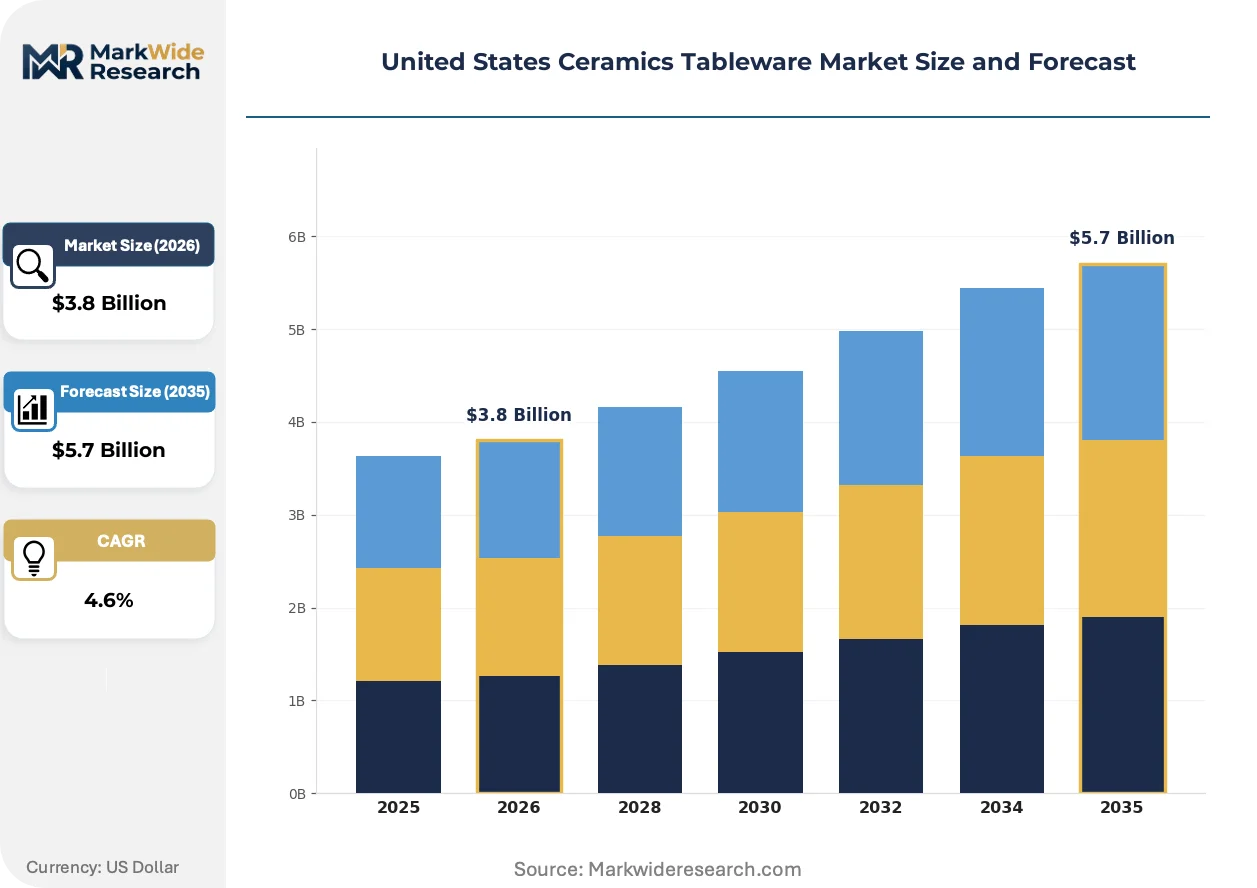
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Serveware, Bakeware, Drinkware Material: Porcelain, Stoneware, Earthenware, Bone China End User: Households, Restaurants, Cafes, Hotels Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Mikasa, Noritake, Lenox Corporation, Homer Laughlin China, Corelle Brands, Lifetime Brands, Meyer Corporation, Wedgwood, The Oneida Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ceramics Tableware Market Evolving Landscape
Digital glaze chemistry modeling and asset-light equipment leasing are compressing traditional competitive moats while transparency requirements reshape buyer-supplier relationships across hospitality procurement.
Digital twin simulation of kiln firing curves is rendering obsolete decades of trial-and-error glaze development. Large-format hotel chains now specify color-matched serveware across properties, demanding batch consistency impossible without predictive thermal modeling. This technology compresses new product development timelines from eighteen months to under six.
FDA 21 CFR 175.300 enforcement has intensified third-party food-contact surface auditing. Manufacturers must maintain chain-of-custody documentation for raw material sourcing, particularly feldspar and kaolin imports. Bone china producers face the steepest compliance burden due to lead-containing fluxes in traditional formulations.
Bulk direct purchasing by hospitality procurement teams disintermediates traditional restaurant supply distributors. Hotel groups now negotiate multi-year serveware contracts directly with Ohio and West Virginia manufacturers, capturing volume discounts while specifying custom vitrification standards for commercial dishwasher compatibility.
United States Ceramics Tableware Market Segmentation
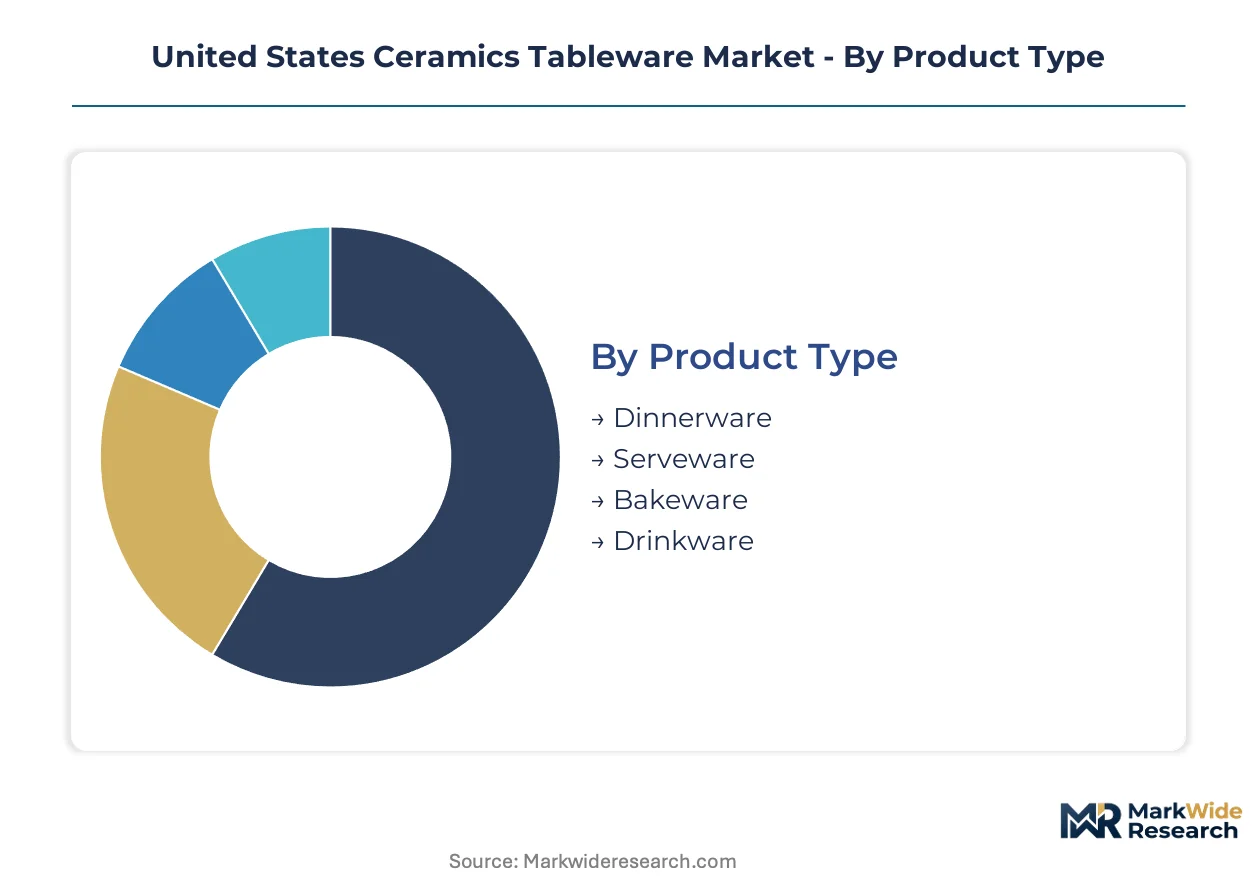
Segmentation in ceramics tableware reveals how procurement patterns diverge between hospitality bulk buyers and household replacement cycles. Material specifications and distribution channel economics create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
After-sales service intensity varies sharply across product categories, with commercial serveware demanding rapid replacement programs and household dinnerware relying on warranty coverage.
- Dinnerware:Plates, bowls, and flatware sets constitute the foundational category, with vitrified porcelain formulations engineered for thermal shock resistance. Hotel procurement teams in Texas and Florida specify commercial-grade dinnerware for high-turnover foodservice operations where chip resistance determines lifecycle economics.
- Serveware:Platters, serving bowls, and presentation pieces command premium positioning in fine-casual restaurant chains. California's experiential dining operators prioritize Instagram-worthy serveware geometries that drive guest engagement and social media visibility.
- Bakeware:Oven-safe ceramic dishes and casseroles compete against glass and metal alternatives on thermal retention properties.
- Drinkware:Mugs, cups, and beverage service items face intense substitution pressure from glass and stainless steel in casual segments.
Dinnerware holds the largest share; momentum sits with serveware as experiential dining elevates presentation standards.
Material:
Cost tier stratification determines manufacturing investment requirements and kiln firing economics across material categories.
- Porcelain:High-fired vitrified clay bodies achieve full density above 1,200°C, yielding zero-porosity surfaces mandatory for commercial dishwasher compatibility. Ohio and West Virginia manufacturing clusters dominate domestic porcelain capacity, supplying institutional foodservice channels with durable serveware engineered for high-temperature sanitization cycles.
- Stoneware:Mid-range vitrification delivers durability at lower kiln energy intensity than porcelain. Casual restaurant chains in the Sun Belt corridor specify stoneware for cost-conscious procurement programs where mechanical strength outweighs translucency requirements.
- Earthenware:Low-fired porous bodies compete aggressively on price in household segments where microwave and dishwasher compatibility drives replacement cycles.
- Bone China:Bone ash incorporation creates distinctive translucency and chip resistance for premium hotel and giftware positioning.
Porcelain holds the largest share; bone china is climbing the fastest as luxury hospitality procurement recovers.
End User:
Volume concentration and order frequency patterns diverge dramatically between contract hospitality buyers and fragmented household purchasers.
- Households:Individual consumers purchase through retail channels with seasonal replacement patterns tied to holiday entertaining and life events. Earthenware price competition dominates this segment, though online transparency around glaze chemistry and origin documentation is reshaping purchase criteria.
- Restaurants:Fine-casual chains negotiate multi-year direct procurement contracts, specifying custom vitrification standards and color-matched serveware across property portfolios. Bulk purchasing portals disintermediate traditional distributor markups in this channel.
- Cafes:Coffee-focused operators prioritize mug durability and thermal retention in high-turnover service environments.
- Hotels:Resort and full-service properties demand batch consistency across large-format serveware deployments, driving adoption of digital twin firing curve optimization.
Households hold the largest share; hotels are expanding most quickly as Sun Belt construction concentrates demand.
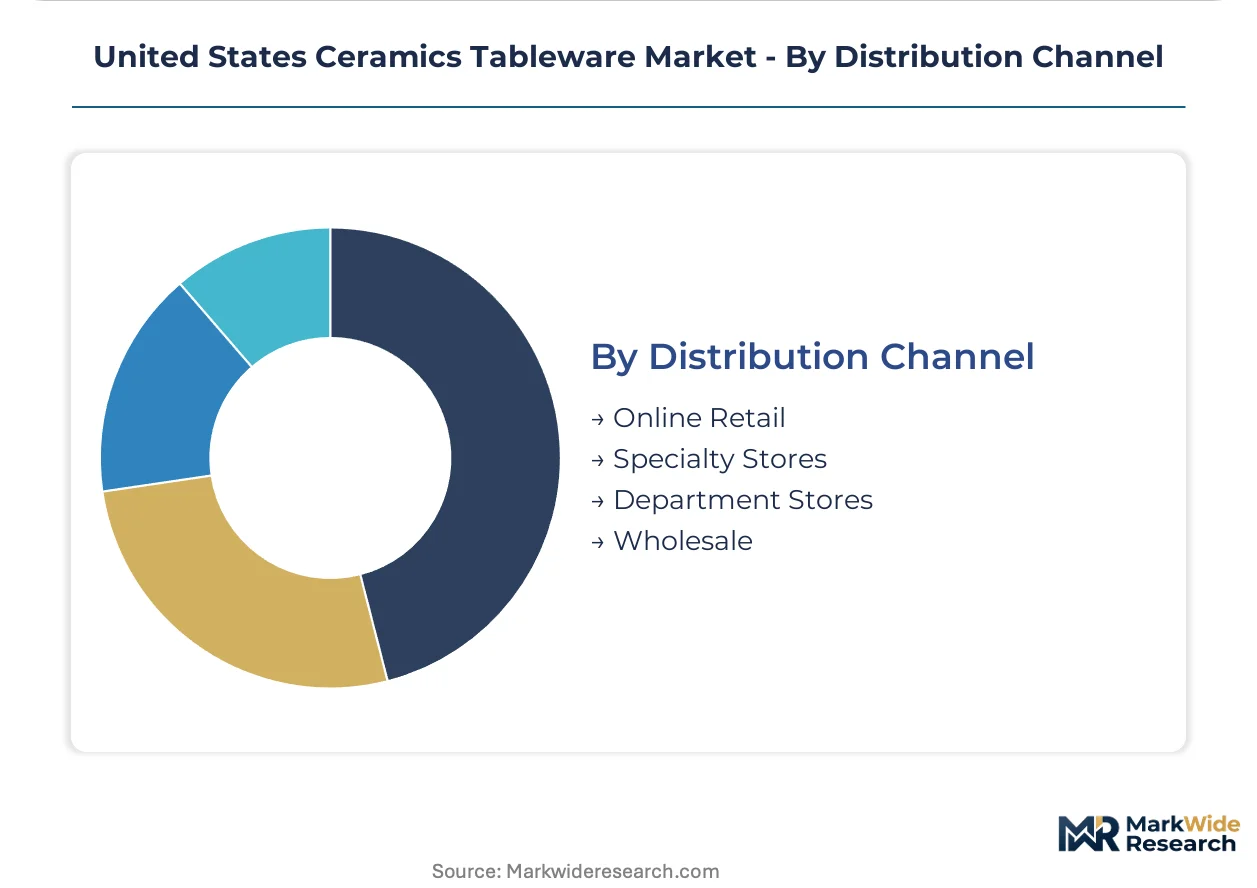
Distribution Channel:
Customer type and procurement scale determine channel economics, with hospitality buyers bypassing traditional retail structures.
- Online Retail:Direct-to-consumer platforms displace department store dominance as buyers research glaze specifications and origin transparency. Digital channels capture household replacement demand and small restaurant procurement with lower overhead than physical retail.
- Specialty Stores:Curated tabletop retailers serve giftware demand and design-conscious household segments with higher service intensity.
- Department Stores:Legacy retail anchors face share erosion from online competition and direct hospitality procurement.
- Wholesale:Traditional restaurant supply distributors retain institutional foodservice relationships though hotel groups increasingly negotiate direct manufacturer contracts.
Wholesale holds the largest share; online retail is gaining share fastest as transparency requirements reshape buyer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a modest ceramics tableware trade deficit, with Ohio and West Virginia manufacturing clusters supplying domestic hospitality demand while specialty giftware imports fill premium household segments. Regional production concentration creates supply vulnerability from localized disruptions. State-level efficiency mandates and hospitality construction patterns are redistributing manufacturing investment across the Sun Belt and traditional Rust Belt kiln sites.
Ohio
The Ohio River Valley hosts the densest concentration of vitrified porcelain capacity, with East Liverpool and surrounding communities maintaining continuous kiln operations since the late 19th century. EPA air quality enforcement under the Clean Air Act requires regenerative thermal oxidizer installations that favor established producers with capital reserves. The state's manufacturing heritage preserves specialized firing knowledge despite declining apprenticeship pipelines.
West Virginia
Adjacent to Ohio, West Virginia's northern panhandle extends the ceramics manufacturing corridor with shared clay body supply chains and natural gas kiln fuel infrastructure. The state's economic development authorities offer retention incentives for capital equipment modernization. Regional weather events and labor market tightness in the Ohio Valley create operational risk for concentrated production.
Texas
Houston, Dallas, and Austin hospitality construction concentrates demand for durable porcelain serveware in high-traffic hotel and resort foodservice operations. The state's deregulated electricity market offers variable pricing that complicates electric kiln retrofit economics. Texas-based distributors increasingly negotiate direct manufacturer contracts, bypassing traditional multi-tier channel structures.
Florida
Orlando and Miami resort development drives procurement of commercial-grade dinnerware engineered for thermal shock resistance in high-turnover operations. Florida's building code efficiency requirements indirectly shape equipment specifications for new hospitality construction. The state's logistics infrastructure supports rapid replacement programs for damaged serveware in seasonal peak periods.
California
Los Angeles and San Francisco fine-casual restaurant chains prioritize Instagram-worthy serveware geometries that drive guest engagement and social media visibility. Title 20 appliance efficiency standards pressure kiln energy consumption benchmarks that manufacturers must meet for California market access. Proposition 65 enforcement adds formulation R&D costs and disclosure requirements that reshape glaze chemistry priorities.
United States Ceramics Tableware Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The United States ceramics tableware market structures around three tiers: heritage bone china houses with giftware equity, institutional porcelain specialists with foodservice scale, and diversified tabletop conglomerates with cross-category leverage. Competitive moves concentrate on direct-to-hotel procurement bypassing distributors and digital firing curve optimization compressing product development timelines.
Among heritage-positioned manufacturers, Lenox Corporation and Wedgwood occupy positions anchored in formal giftware tradition and translucency craftsmanship. Homer Laughlin China exemplifies the institutional specialist archetype with concentrated presence in commercial foodservice channels. Mikasa represents the diversified platform approach, leveraging direct procurement contracts across hospitality cycles. These three patterns—heritage equity, institutional scale, and platform breadth—define the competitive terrain.
| Leading Market Players |
|---|
| Mikasa |
| Noritake |
| Lenox Corporation |
| Homer Laughlin China |
| Corelle Brands |
| Lifetime Brands |
| Meyer Corporation |
| Wedgwood |
| The Oneida Group |
| Others |
Value Network & Pricing Analysis
Ohio and West Virginia kiln clusters concentrate vitrified porcelain capacity, anchoring margin capture downstream where hospitality procurement teams negotiate multi-year serveware contracts. Natural gas pricing volatility and EPA compliance investments compress returns for producers without regenerative thermal oxidizer reserves.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hospitality procurement channels. Three-tier pricing structure across premium bone china, standard vitrified porcelain, and economy earthenware levels reflects FDA certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because earthenware imports compete aggressively on microwave and dishwasher compatibility claims. Casual restaurant chains exhibit highest price sensitivity; luxury hotel groups prioritize batch consistency and color-matching over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Ohio River Valley specialists including Homer Laughlin China and Lenox Corporation facilities. Domestic production draws from Appalachian kaolin deposits and imported feldspar from Turkey and India. Supply chain risk centers on single-source vulnerability for bone ash fluxes in traditional bone china formulations. Distribution runs through direct-to-hotel procurement platforms disintermediating traditional restaurant supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized kiln operator apprenticeship pipelines have collapsed across traditional manufacturing regions, constraining firing curve optimization capacity that tacit knowledge previously supplied. This capability gap threatens production scalability for mid-sized manufacturers seeking EPA compliance advantages.
For Market Incumbents: Entrench position through captive supply of regenerative thermal oxidizer capacity and backward integration into digital glaze chemistry modeling. Electrification incentive capture in Sun Belt states offers defensive moat construction against gas-dependent competitors facing margin pressure from fuel price volatility.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-hotel procurement platforms serving Texas and Florida hospitality construction. White-space exists in asset-light kiln equipment leasing for mid-sized manufacturers avoiding capital-intensive infrastructure. Go-to-market angle should emphasize California Title 20 compliance readiness and Proposition 65 disclosure documentation.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized manufacturers with EPA-compliant filtration investments and digital firing curve optimization capabilities. Long-term viability over the next decade hinges on electrification retrofit positioning and hospitality procurement relationship depth. Watch electrification incentive program expansion across Sun Belt states as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Program | EPA compliance and Title 20 positioning capture margin from gas-dependent competitors in Ohio-West Virginia corridor. |
| Direct-to-Hotel Procurement Platform | Bypassing distributor markups captures volume stability across hospitality cycles for compliant manufacturers. |
| Digital Glaze Chemistry Modeling | Predictive thermal simulation compresses product development timelines from eighteen months to under six. |
| Asset-Light Kiln Equipment Leasing | Mid-sized manufacturers avoid capital-intensive infrastructure while scaling EPA-compliant production capacity. |
| Proposition 65 Compliance Documentation | Lead and cadmium disclosure readiness unlocks California fine-casual restaurant procurement contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA enforcement records, and hospitality procurement contract databases. Primary interviews engaged kiln operations managers, hotel supply chain directors, ceramic glaze chemists, and restaurant procurement officers. Bottom-up demand modeling triangulated against top-down manufacturing capacity assessments across Ohio and West Virginia production clusters.
Forecast inputs include material segmentation by vitrification grade, end-use channel concentration between hospitality and household, and distribution model evolution across direct procurement and wholesale tiers. CAGRs were derived from elasticity-adjusted demand projections incorporating kiln energy cost trajectories and regulatory compliance investment cycles. Analysis window spans the full projection horizon without interim period specificity.
Stress conditions across natural gas price bands, EPA enforcement intensity, and Sun Belt hospitality construction absorption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding apprenticeship pipeline recovery and electrification incentive program continuity. Cross-checking against customs import data for ceramic tableware is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Titanium Carbide Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Activated Alumina Market
Ceramics
Potassium Feldspar Market
Ceramics
Colloidal Alumina Market
Ceramics
Technical Ceramics Market
Ceramics
Medical Ceramics Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Cerium Nitride Market
Ceramics
Zeolite 4A Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market