
 Hexagonal Boron Nitride (HBN) Market | 2026-2036
Hexagonal Boron Nitride (HBN) Market Size, Share, and Industry Trends Forecast 2026-2036
Hexagonal Boron Nitride (HBN) Market Intelligence
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct procurement by compound semiconductor foundries and advanced ceramics manufacturers. Momentive Performance Materials leverages its silicone heritage to cross-sell thermal interface solutions into overlapping buyer accounts. Resonac Holdings Corporation anchors Japanese supply through captive synthesis of high-purity HBN feedstock for domestic chip packaging lines. Saint-Gobain competes via its refractories channel, extending technical ceramics expertise into boron nitride shapes for aerospace hot zones.
Hexagonal boron nitride is a synthetic ceramic composed of boron and nitrogen atoms arranged in a graphene-like layered lattice with a bandgap exceeding five electron volts, yielding exceptional thermal conductivity parallel to basal planes while maintaining electrical insulation. Manufacturers produce it via boric acid-nitrogen reduction or chemical vapor deposition, then mill or sinter into forms serving primarily as non-wetting crucible liners, thermal fillers, and solid lubricants in oxygen-excluded environments. Powder grades dominate volume shipments due to their incorporation into polymer composites and metalworking pastes, while sheets and films capture disproportionate margin pools from gallium nitride epitaxy substrate demand. Coating applications are expanding fastest as plasma-sprayed HBN replaces graphite in vacuum furnace fixtures, though foam remains nascent with limited qualified suppliers.
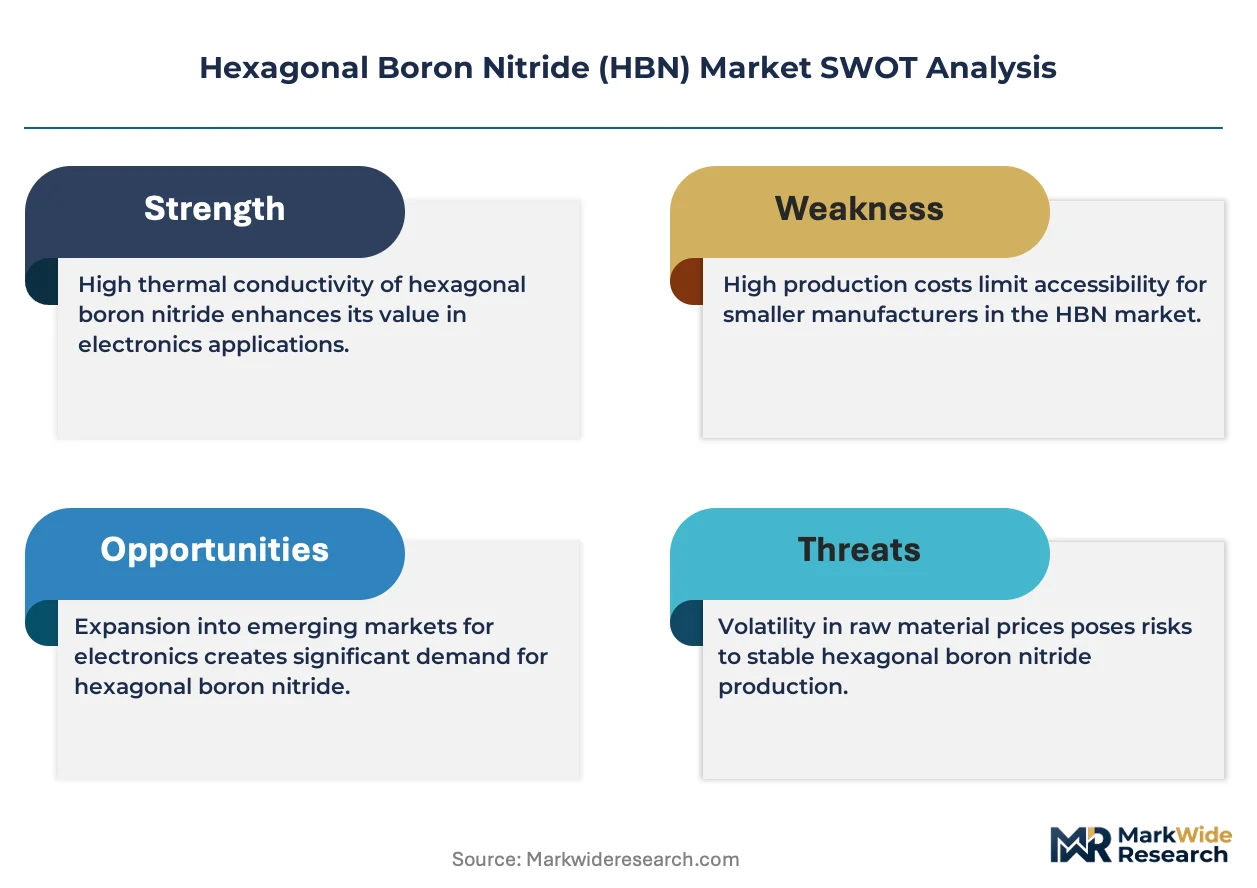
EPA oversight of boron compound workplace exposure limits shapes US manufacturing site location and ventilation investment, while REACH registration requirements in Europe filter out low-purity imports from non-compliant sources. Japan's METI promotes HBN through materials innovation programs tied to domestic semiconductor reshoring targets. Buyers must track evolving purity certifications for cosmetic-grade material against tightening EU regulation and foundry qualification timelines for next-generation thermal interface materials.
Market Dynamics
Thermal management requirements in gallium nitride power electronics are compressing qualification timelines and forcing purity upgrades across the hexagonal boron nitride supply base. Compound semiconductor foundries now specify sub-50 ppm oxygen content for thermal interface materials, reshaping synthesis and milling investments.
Growth Catalysts
- GaN-on-SiC Device Ramp:Power electronics manufacturers in China and Japan are qualifying HBN thermal fillers for 650V and 900V transistor packages, pulling high-purity powder volumes upward.
- REACH Article 33 Compliance:EU cosmetics and electronics buyers now require full substance disclosure for boron nitride imports, filtering out non-compliant Asian suppliers and consolidating volume with certified producers.
- Plasma Spray Coating Substitution:Vacuum furnace operators in Germany and the US are replacing graphite fixtures with HBN-coated molybdenum to eliminate carbon contamination in titanium alloy heat treatment.
Market Restraints
- Boric Acid Price Volatility:Turkish and US boron ore supply disruptions have compressed feedstock margins for HBN producers dependent on boric acid-nitrogen reduction routes.
- High-Purity Synthesis Bottleneck:Chemical vapor deposition capacity for electronics-grade HBN concentrates in Japanese and German facilities, creating allocation risk during foundry qualification surges.
- Aluminum Nitride Substitution:Thermal pad manufacturers in cost-sensitive LED lighting applications are switching to aluminum nitride fillers where electrical insulation requirements permit lower thermal conductivity.
Strategic Opportunities
- Indian Compound Semiconductor Fab Buildout:India's PLI scheme for semiconductor manufacturing is creating first-mover advantage for HBN suppliers qualifying thermal interface materials with domestic gallium nitride foundries.
- Solid-State Battery Thermal Barriers:Lithium-metal battery developers are testing HBN sheet laminates as dendrite-blocking interlayers, opening volume potential beyond traditional electronics applications.
- Direct Procurement Platforms:Advanced ceramics manufacturers are bypassing regional distributors to establish annual contracts with HBN powder producers, compressing channel margins and capturing purity certification traceability.
Industry Challenges
- Plasma Spray Technician Scarcity:Qualified operators for HBN coating application in vacuum furnace refurbishment are concentrated in aerospace clusters around Toulouse and Wichita, constraining service expansion.
- Foundry Qualification Timelines:GaN device manufacturers require 18-24 month stability data for thermal interface materials, locking out new HBN suppliers during critical demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexagonal Boron Nitride (HBN) Market |
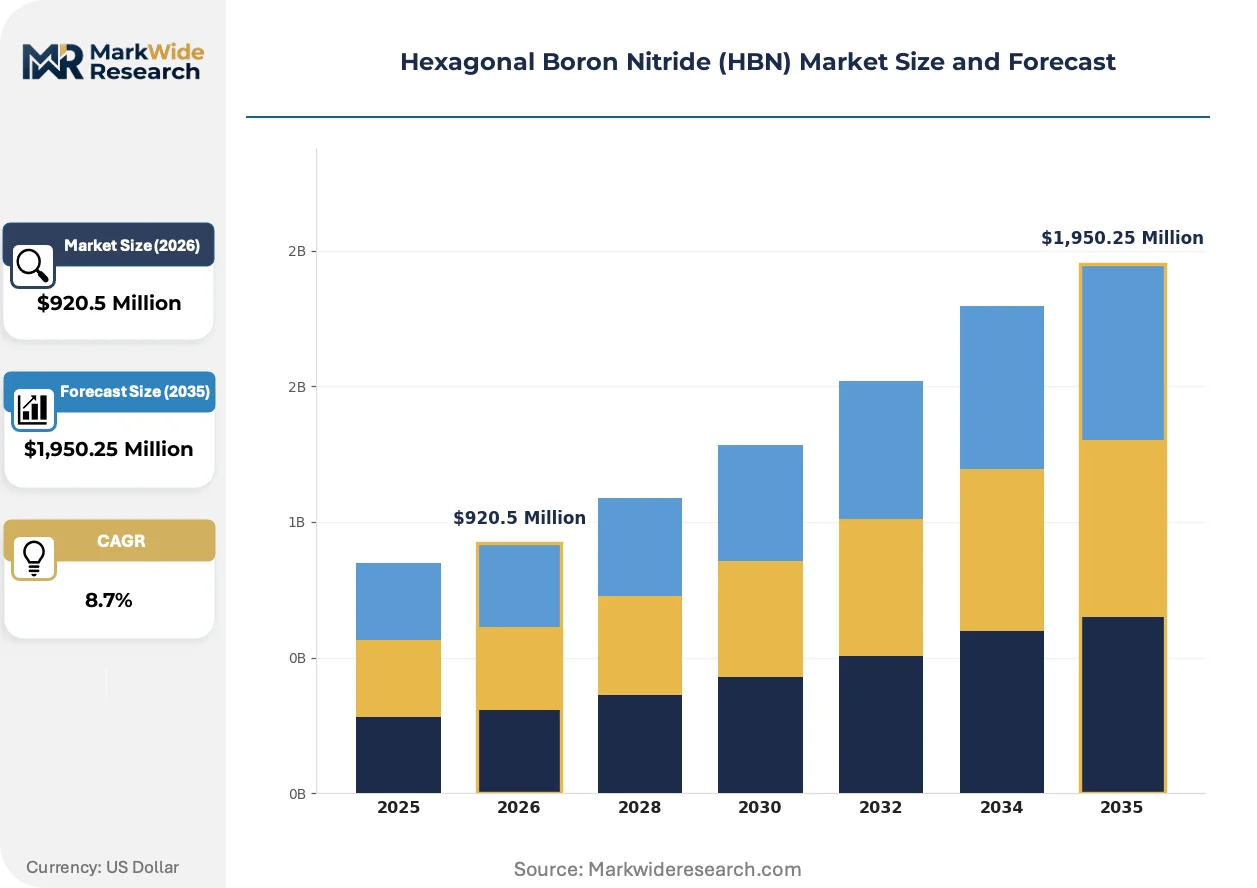
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,950.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Coating, Foam, Sheets End Use Industry: Aerospace, Electronics, Metalworking, Plastics Form: Granules, Flakes, Solids, Films Application: High-Temperature Lubricants, Insulating Materials, Cosmetic Products, Electrical Insulation |
| Companies Covered | Momentive Performance Materials Inc., Resonac Holdings Corporation, 3M Company, Grolltex Inc., Höganäs AB, Saint-Gobain, American Elements, ZYP Coatings Inc., Denka Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexagonal Boron Nitride (HBN) Market Strategic Shifts & Innovations
Synthesis and formulation technologies are diverging between cost-optimized industrial grades and ultra-high-purity electronics specifications, fragmenting equipment investment strategies across the supply base.
Hot-pressed HBN ceramic components are migrating from legacy boron nitride crucible applications into solid-source effusion cells for molecular beam epitaxy systems. MBE equipment manufacturers in Japan and Germany are specifying machined HBN pyrolytic shapes for aluminum and gallium source crucibles to reduce outgassing during III-nitride growth. This migration from traditional refractory metals is enabling longer source lifetime and reducing chamber maintenance cycles in production-scale epitaxy.
REACH registration deadlines for boron compounds are tightening purity documentation requirements for cosmetic-grade HBN used in thermal management pastes and release agents. ECHA's 2024 updated guidance on nanomaterial characterization now requires specific surface area reporting for sub-micron boron nitride powders. European cosmetic and thermal paste blenders are consolidating suppliers to those with complete dossier submissions, compressing the qualified vendor base.
Compound semiconductor foundries are unbundling thermal interface material specification from equipment OEM supply agreements. Buyers at GaN power device fabs in China and Germany now issue direct RFQs for HBN-filled greases and phase-change materials, bypassing thermal test fixture manufacturers who previously specified materials. This disintermediation concentrates volume with qualified chemical suppliers and compresses specification latency from 12 months to 90 days in active procurement cycles.
Hexagonal Boron Nitride (HBN) Market Segmentation
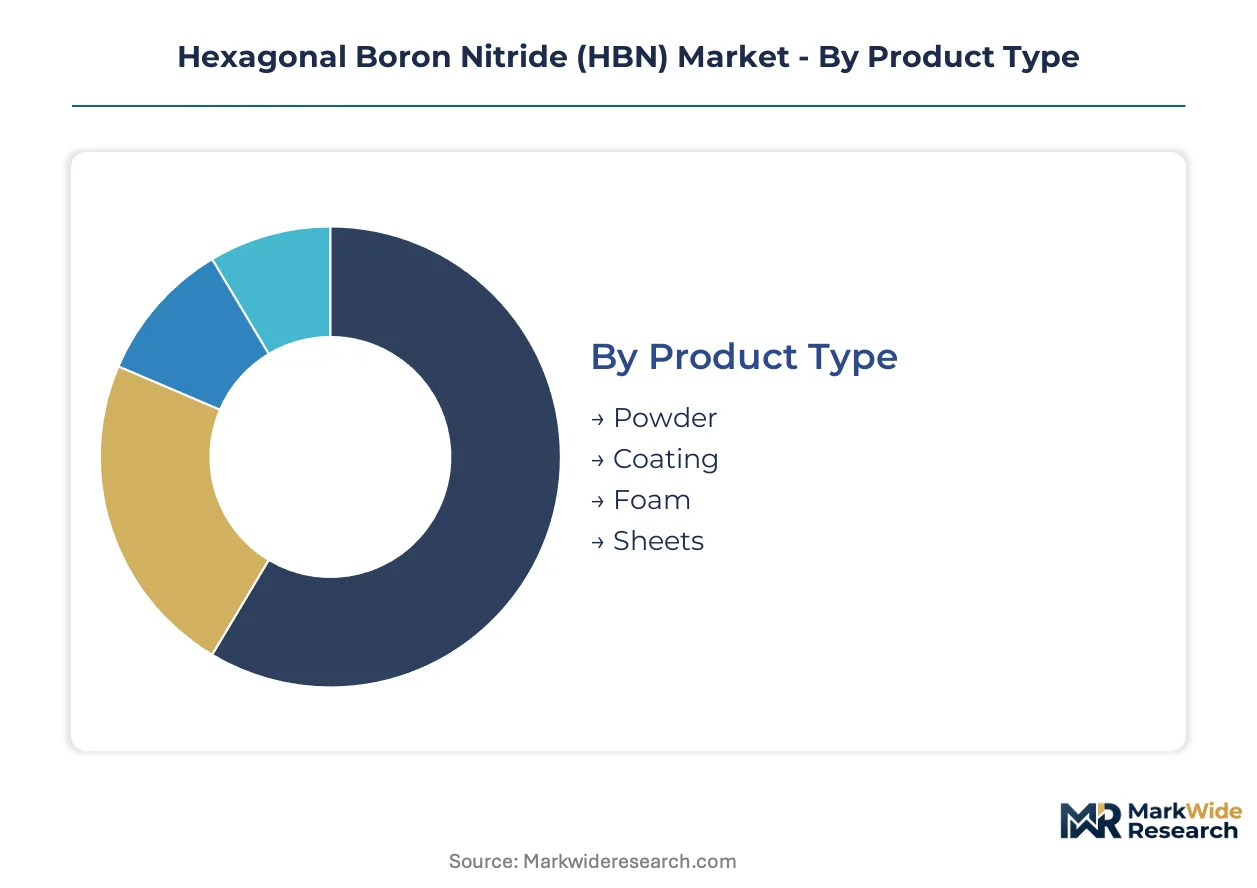
Segmentation in hexagonal boron nitride reveals how purity grades and physical forms map to divergent margin structures across semiconductor packaging, aerospace hot zones, and thermal management applications. Manufacturers configure synthesis and milling investments differently for powder volumes versus sheet laminates, creating distinct competitive arenas within the same material category.
Product Type:
Cost tier differentiation separates commodity industrial grades from qualification-intensive electronics specifications.
- Powder:Milled crystalline grades with particle sizes from sub-micron to 50 microns serve polymer composite fillers and metalworking pastes. Demand concentrates in China and Japan where GaN power device manufacturers specify sub-50 ppm oxygen content for thermal interface materials.
- Sheets:Hot-pressed or pyrolytic boron nitride plates provide substrate carriers for gallium nitride epitaxy and solid-source effusion cells. Japanese MBE equipment manufacturers specify machined pyrolytic shapes to reduce outgassing during III-nitride growth.
- Coating:Plasma-sprayed HBN layers replace graphite on molybdenum vacuum furnace fixtures, eliminating carbon contamination in titanium alloy heat treatment.
- Foam:Three-dimensional cellular structures remain nascent with limited qualified suppliers for thermal insulation in aerospace applications.
Powder commands the established base. The steepest expansion runs through Coating.
End Use Industry:
Application maturity varies sharply between established refractory markets and emerging semiconductor thermal management.
- Electronics:Thermal interface materials for GaN-on-SiC power transistors and solid-state battery dendrite barriers. Chinese and Japanese foundries drive qualification timelines compressing from 18 months toward 90 days in active procurement cycles.
- Aerospace:Hot-zone insulation for vacuum furnaces and rocket propulsion systems. German and US operators specify HBN-coated fixtures to eliminate carbon contamination in titanium heat treatment.
- Metalworking:High-temperature lubricants and release agents for extrusion and forging operations.
- Plastics:Thermal conductivity enhancement in polymer composites for LED housings and automotive components.
Metalworking commands the established base. Electronics shows the steepest expansion trajectory.
Form:
Volume scale and handling characteristics determine logistics configurations and customer technical service requirements.
- Granules:Free-flowing agglomerated particles for bulk refractory applications and crucible packing. Turkish boric acid supply disruptions have compressed feedstock margins for producers dependent on reduction-route synthesis.
- Flakes:Platelet morphologies with high aspect ratios enhance thermal conductivity in polymer matrices when aligned during compounding.
- Solids:Machined blocks and custom shapes for furnace fixtures and MBE source crucibles.
- Films:Thin laminates for solid-state battery interlayers and flexible thermal management substrates.
Granules command the established base. Films are gaining share fastest.
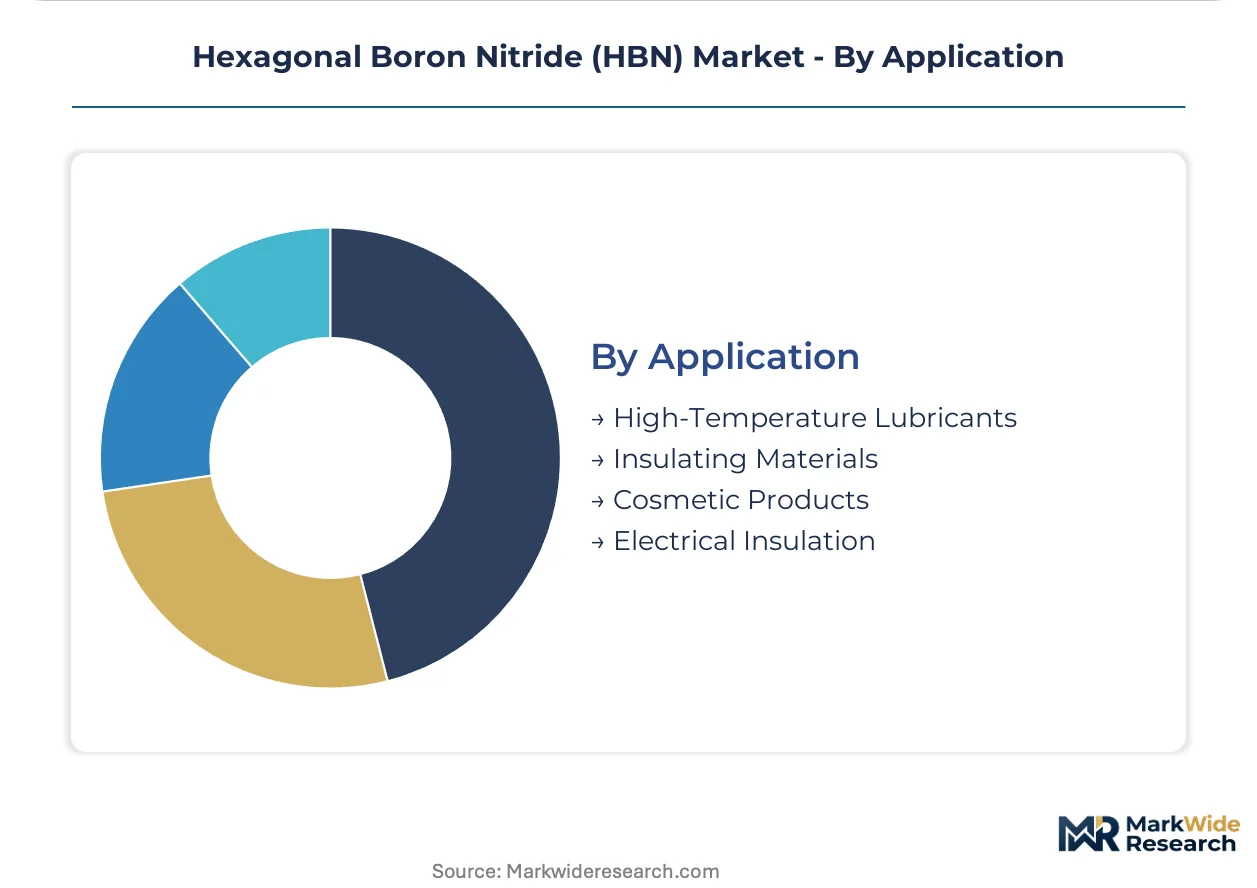
Application:
Customer type fragmentation separates specification-driven foundry procurement from price-sensitive industrial blending.
- Insulating Materials:Electrical isolation in high-voltage power modules and RF devices. REACH Article 33 compliance requirements filter out non-compliant Asian suppliers and consolidate volume with certified European producers.
- High-Temperature Lubricants:Boron nitride pastes and suspensions for metal forming and glass molding. EPA workplace exposure limits shape US manufacturing site location and ventilation investment.
- Cosmetic Products:Thermal management and slip agents in personal care formulations. ECHA nanomaterial characterization guidance now requires specific surface area reporting for sub-micron powders.
- Electrical Insulation:Substrate materials for power electronics packaging and thermal management systems.
High-Temperature Lubricants command the established base. Insulating Materials climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Japanese and German electronics-grade producers while Chinese manufacturers dominate industrial powder volumes at compressed margins. This asymmetry shapes procurement patterns across thermal interface material supply chains. Regional regulatory divergence on purity certification is fragmenting qualified supplier bases.
China
GaN-on-SiC power device foundries in Shenzhen and Shanghai drive qualification demand for sub-50 ppm oxygen content powders. MIIT materials innovation programs channel subsidies toward domestic high-purity synthesis capacity. Yangtze River Delta clusters host compound semiconductor packaging lines pulling thermal filler volumes upward.
Japan
MBE equipment manufacturers in Nagoya and Osaka specify machined pyrolytic boron nitride shapes for III-nitride growth crucibles. METI promotes HBN through semiconductor reshoring targets tied to domestic chip packaging investment. Chubu region synthesis facilities anchor captive electronics-grade feedstock supply.
Germany
Vacuum furnace operators in North Rhine-Westphalia replace graphite fixtures with plasma-sprayed HBN-coated molybdenum for titanium alloy heat treatment. REACH Article 33 compliance filters non-compliant imports and consolidates volume with certified European producers. Bavarian advanced ceramics manufacturers bypass distributors for direct powder procurement.
United States
EPA workplace exposure limits for boron compounds shape manufacturing site location decisions and ventilation capital allocation. Aerospace clusters around Wichita concentrate qualified plasma spray technicians for vacuum furnace refurbishment services. Southeast thermal management compounders serve GaN power module assemblers with compressed qualification timelines.
India
PLI scheme incentives for semiconductor manufacturing create first-mover positioning for thermal interface material suppliers qualifying with domestic gallium nitride foundries. Karnataka and Telangana fab buildouts pull specification-driven procurement away from industrial-grade distributors. Central government materials programs accelerate local synthesis partnerships.
Hexagonal Boron Nitride (HBN) Market Key Industry Players
Integrated chemical conglomerates and specialty ceramics specialists split the market along purity-grade boundaries. Japanese and German producers anchor the electronics-grade tier through captive synthesis and equipment integration relationships. Chinese manufacturers dominate industrial powder volumes via boric acid reduction scale. Competitive moves concentrate on foundry qualification partnerships and direct procurement platform development.
Among diversified materials conglomerates, Momentive Performance Materials Inc. and Saint-Gobain exemplify cross-selling strategies leveraging adjacent thermal management portfolios. Resonac Holdings Corporation anchors the Japanese supply position through integrated feedstock-to-device packaging relationships. These three represent distinct archetypes: silicone heritage extension, refractories channel expansion, and captive semiconductor supply chain integration.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| Resonac Holdings Corporation |
| 3M Company |
| Grolltex Inc. |
| Höganäs AB |
| Saint-Gobain |
| American Elements |
| ZYP Coatings Inc. |
| Denka Company Limited |
| Others |
Cost & Logistics Intelligence
Chubu region synthesis facilities in Japan anchor electronics-grade HBN capacity, concentrating pricing power with producers who control captive feedstock supply for foundry-qualified thermal interface materials. This geographic concentration enables premium capture for sub-50 ppm oxygen content powders while Chinese boric acid reduction producers compete on industrial-grade volumes at compressed margins.
Pricing Analysis
Configured-to-order pricing for machined pyrolytic boron nitride shapes commands substantial premiums over standard powder grades. Three-tier pricing structure across electronics-grade, industrial-grade, and cosmetic-grade levels reflects divergent certification burdens and qualification timelines. Cost compression in industrial powder tiers intensifies because Turkish boric acid supply disruptions have compressed feedstock margins for reduction-route producers. LED lighting thermal pad manufacturers exhibit highest price sensitivity, switching to aluminum nitride fillers where electrical insulation requirements permit lower thermal conductivity.
Supply Chain Analysis
Contract manufacturing concentration for HBN coating application rests with qualified plasma spray technicians clustered around aerospace hubs in Toulouse and Wichita. Geographic supply concentration centers on Japan, Germany, and China, with Japanese and German facilities anchoring electronics-grade chemical vapor deposition capacity. Raw material dependencies draw from Turkish and US boron ore, nitrogen feedstock, and molybdenum substrate fixtures. Single-source vulnerability concentrates in Japanese pyrolytic boron nitride synthesis for MBE crucible applications. Distribution runs through direct procurement platforms as advanced ceramics manufacturers bypass regional distributors for annual contracts with powder producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hexagonal boron nitride sits in early-cycle expansion as GaN-on-SiC power electronics penetration accelerates thermal interface material qualification timelines. Solid-state battery thermal barrier testing opens volume potential beyond traditional semiconductor applications.
For Market Incumbents: Pre-empt aluminum nitride substitution in cost-sensitive LED applications by embedding thermal performance guarantees into long-term supply agreements. Deepen backward integration into boric acid sourcing to buffer Turkish supply disruption risks. Lock in foundry qualification partnerships before 18-24 month stability data requirements freeze out new suppliers during demand surges.
For New Entrants and Emerging Players: Build out plasma spray coating service capacity in underserved aerospace clusters outside Toulouse and Wichita to capture vacuum furnace refurbishment demand. Target India's PLI-supported compound semiconductor fab buildout in Karnataka and Telangana for first-mover positioning with domestic gallium nitride foundries. Lead with REACH-compliant purity documentation to bypass the qualified vendor consolidation squeezing non-compliant Asian suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electronics-grade HBN producers with captive synthesis and multi-year foundry supply agreements. Long-term viability over the analysis window favors suppliers with demonstrated qualification track records in GaN thermal interface materials. Acquisition target archetype: mid-cap specialists with pyrolytic boron nitride machining capabilities and existing MBE equipment manufacturer relationships. Monitor foundry capital expenditure announcements in China and India as inflection indicators for thermal filler volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Feedstock | Turkish supply disruptions have made captive boric acid sourcing a margin defense priority for reduction-route producers. |
| Capacity Expansion in Electronics-Grade Synthesis | Japanese and German facilities are adding chemical vapor deposition lines to address allocation risk during foundry qualification surges. |
| Long-term Supply Agreement with GaN Foundries | Direct procurement platforms compress channel margins while locking in volume through multi-year thermal interface material contracts. |
| REACH Compliance Certification Investment | ECHA nanomaterial characterization guidance filters out non-compliant suppliers and consolidates volume with dossier-complete producers. |
| Joint Venture for Indian Compound Semiconductor Supply | Karnataka and Telangana fab buildouts under PLI scheme create first-mover advantage for domestic HBN qualification partnerships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed materials conglomerates, and ECHA registration dossiers for boron compounds. Primary interviews engaged thermal interface material procurement leads at GaN power device foundries, plant managers at boron nitride synthesis facilities, technical R&D directors at advanced ceramics manufacturers, and distribution channel partners in specialty chemical supply. Bottom-up volume estimates derived from foundry capacity buildouts and thermal filler loading specifications triangulate against top-down market sizing from trade flow analysis and producer revenue disclosures.
Forecast inputs incorporate grade tier differentiation between electronics-grade and industrial specifications, end-use industry segmentation across semiconductor packaging and aerospace applications, and regional production hub concentration in Japan, Germany, and China. Analytical framework models adoption curves for GaN-on-SiC power transistors and solid-state battery thermal barriers across the projection horizon. CAGRs derive from segment-level volume buildups calibrated to foundry qualification timelines and purity upgrade trajectories. Boric acid price volatility and REACH compliance cost pass-through assumptions inform margin sensitivity testing.
Sensitivities concentrate around GaN device ramp timing, boron ore supply disruption duration, and foundry qualification timeline compression. Forecasts reflect assumptions on thermal interface material loading rates per transistor package and plasma spray coating substitution velocity in vacuum furnace applications. Quarterly review of foundry capital expenditure announcements, ECHA guidance updates on nanomaterial characterization, and Turkish boron export license data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Advanced Polymer Composites Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Borophene Market
Advanced Materials
Curable Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market