
 GCC Ceramic Tiles and Sanitary Ware Market | 2026-2036
GCC Ceramic Tiles and Sanitary Ware Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Ceramic Tiles and Sanitary Ware Market Foresight
Project-specification channels is reconfiguring how ceramic tiles and sanitary ware reach buyers across the GCC. RAK Ceramics leverages its UAE manufacturing base to dominate hospitality and infrastructure procurement. Saudi Ceramics anchors domestic supply for Riyadh's megaproject pipeline. Porcelanosa competes on design-led positioning among architect-specified residential towers.
Ceramic tiles and sanitary ware encompass fired clay products, vitrified porcelain slabs, and glazed fixtures engineered for moisture resistance, dimensional stability, and aesthetic surface finish; manufacturing employs roller kiln firing at temperatures exceeding 1,200°C to achieve water absorption rates below 0.5% for vitrified grades, serving primarily as interior and exterior surfacing and hygienic plumbing systems for built environments. Porcelain tiles command the strongest margin pools due to technical performance requirements in commercial applications, while sanitary fixtures see fastest volume growth from hospitality venue construction across the Gulf. Residential construction remains the deepest application segment, though renovation activity among existing stock increasingly drives replacement demand for outdated ceramic installations.
SASO in Saudi Arabia and the Emirates Authority for Standardization and Metrology in the UAE enforce ceramic quality marks and water-efficiency labeling that filter substandard imports from Asian suppliers. The GCC Standardization Organization harmonizes technical requirements across member states, reducing compliance fragmentation for pan-regional distributors. Stakeholders must monitor evolving green building codes and water conservation mandates that will redefine product specification criteria across upcoming developments.
Market Dynamics
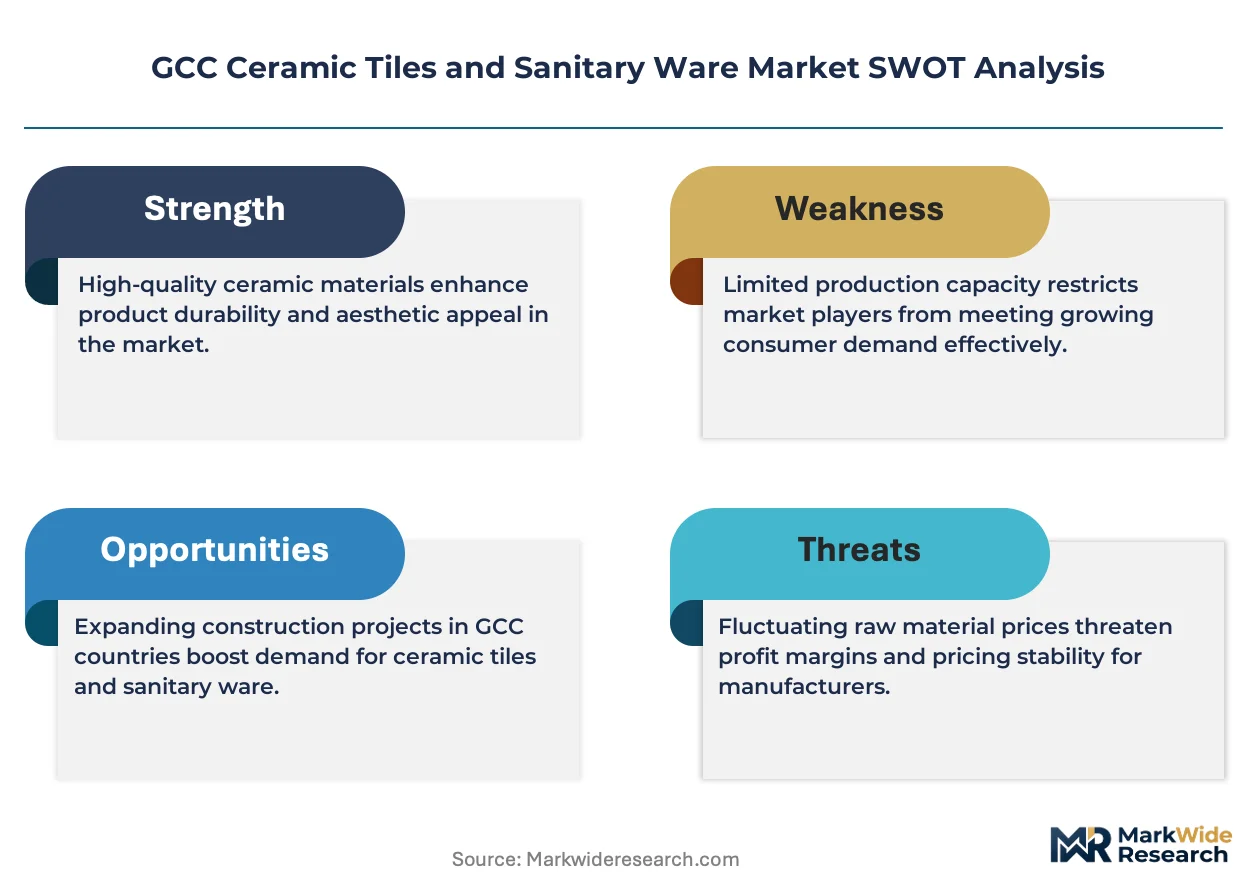
The GCC ceramic tiles and sanitary ware sector is undergoing a fundamental reconfiguration as Saudi Arabia's SASO quality mark requirements tighten compliance thresholds for imported tiles, forcing supply chain restructuring across the region.
Growth Catalysts
- SASO Quality Mark Requirements:Saudi Arabia's tightening compliance thresholds for imported tiles are filtering substandard Asian suppliers and creating premium positioning opportunities for compliant manufacturers.
- Hospitality Construction:Tourism infrastructure expansion across Dubai, Riyadh, and Doha is accelerating procurement of premium sanitary fixtures for hotel and resort developments.
- Roller Kiln Firing Technology:Advanced firing at temperatures exceeding 1,200°C enables water absorption rates below 0.5% for vitrified grades, opening commercial specification channels.
Market Restraints
- Natural Gas Price Volatility:Energy-intensive kiln operations face input cost pressure from fluctuating regional gas pricing, compressing margins for energy-inefficient producers.
- Import Concentration Risk:Heavy reliance on Asian ceramic tile suppliers exposes distributors to shipping cost spikes and extended lead times through the Strait of Hormuz.
- Technical Limitation of Glazed Porcelain:Surface abrasion resistance constraints restrict large-format porcelain deployment in high-traffic commercial flooring applications.
Strategic Opportunities
- Qatar's Post-World Cup Hospitality Conversion:Stadium and accommodation assets are being repurposed into permanent hotel inventory, generating replacement demand for sanitary installations.
- Water-Efficiency Labeling Mandates:Emirates Authority for Standardization and Metrology labeling requirements are creating specification advantages for low-flow fixture manufacturers.
- Digital Specification Platforms:Architect and interior designer procurement is migrating to BIM-integrated product libraries, enabling direct manufacturer-to-specifier relationships.
Industry Challenges
- Certification Timeline Compression:GCC Standardization Organization harmonization efforts are accelerating compliance deadlines, straining testing laboratory capacity across member states.
- Specialized Kiln Operator Scarcity:Technical expertise in roller kiln temperature profiling and defect prevention remains concentrated among veteran production engineers nearing retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Ceramic Tiles and Sanitary Ware Market |
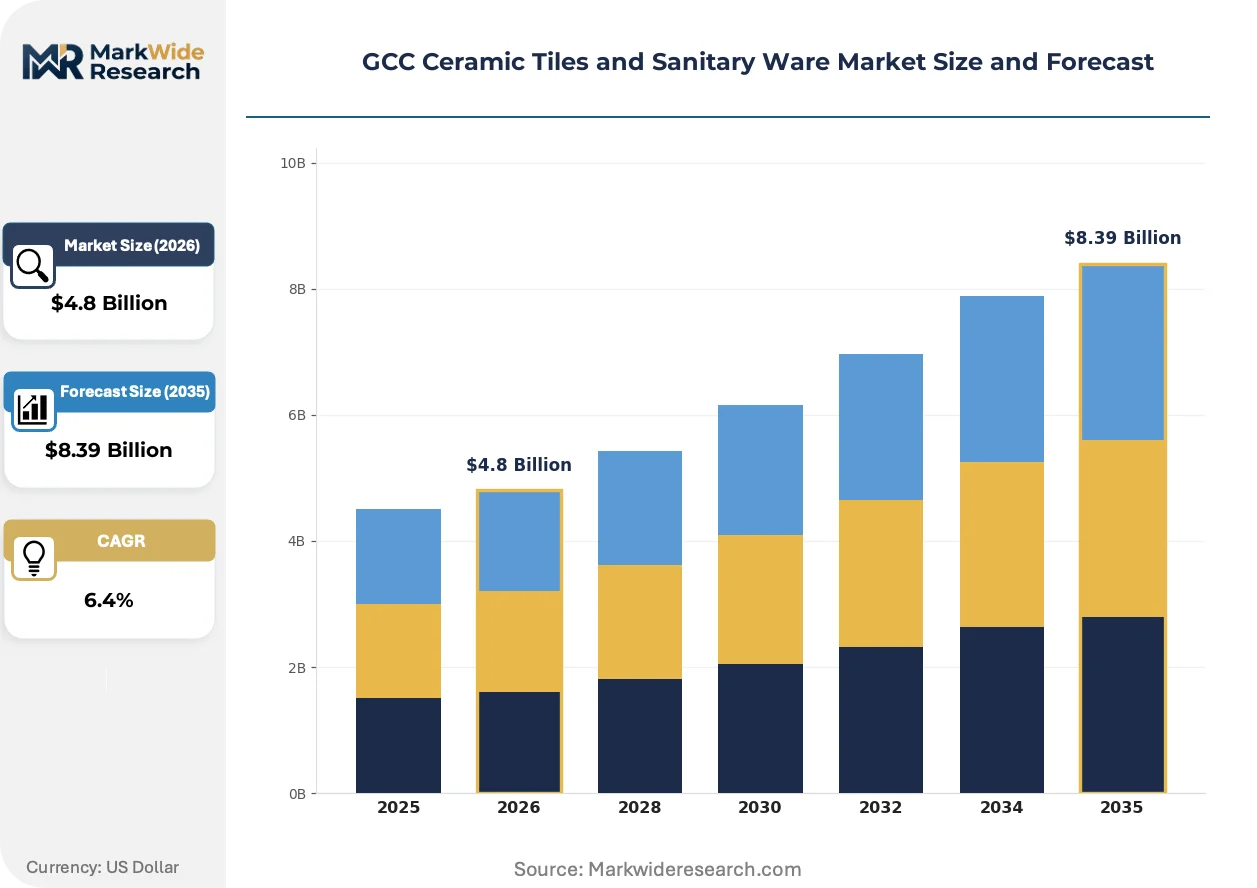
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
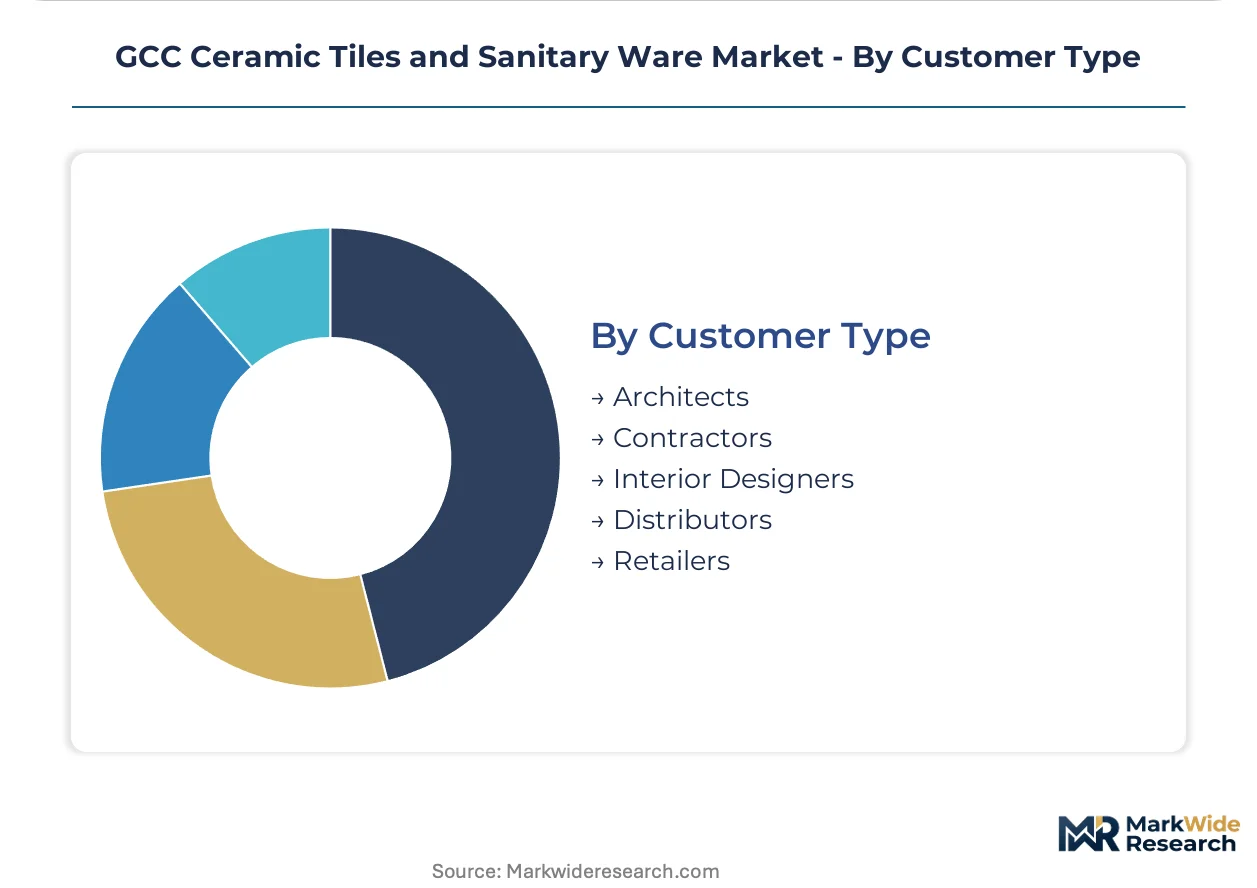
| Segmentation | Product Type: Ceramic Tiles, Porcelain Tiles, Vitrified Tiles, Sanitary Fixtures, Faucets, Water Closets Application: Residential Construction, Commercial Establishments, Institutional Buildings, Hospitality Venues, Infrastructure Projects Installation Type: New Construction, Renovation, Retrofitting, Replacement, Expansion Customer Type: Architects, Contractors, Interior Designers, Distributors, Retailers |
| Companies Covered | Porcelanosa, Duravit, RAK Ceramics, Riyadh Ceramics, Jaquar Middle East, Saudi Ceramics, Al Anwar Ceramic Tiles Co., Al Maha Ceramics, Arabian Ceramics, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Ceramic Tiles and Sanitary Ware Market Shifts & Advancements
Digital manufacturing and sustainability mandates are converging to redefine product specification criteria across Gulf construction markets, with water conservation and surface performance emerging as decisive competitive differentiators.
Thin large-format porcelain slabs are hybridizing traditional ceramic tile aesthetics with engineered stone durability, enabling seamless wall-to-floor installations. Hospitality developers in Dubai and Riyadh are specifying these hybrid surfaces at accelerating rates for luxury hotel lobbies and spa environments. The technology is hybridizing margin pools by collapsing the historical separation between tile and stone specification categories.
Emirates Authority for Standardization and Metrology water-efficiency labeling requirements are mandating flow-rate disclosures on all sanitary fixtures sold in UAE markets. This regulatory framework is compressing demand toward low-flow toilet and faucet configurations that meet or exceed 4.5-liter flush standards. Hospitality and commercial segments are responding fastest, with procurement teams embedding efficiency thresholds into mandatory tender specifications.
Project-direct specification channels are displacing traditional distributor intermediaries across megaproject procurement. Saudi giga-developments and Dubai master-planned communities are consolidating purchasing through centralized procurement offices that negotiate directly with RAK Ceramics and Saudi Ceramics manufacturing entities. This concentration is most visible in Riyadh's Diriyah Gate and Qiddiya projects, where single-source sanitary ware agreements cover thousands of residential and hospitality units.
GCC Ceramic Tiles and Sanitary Ware Market Segmentation
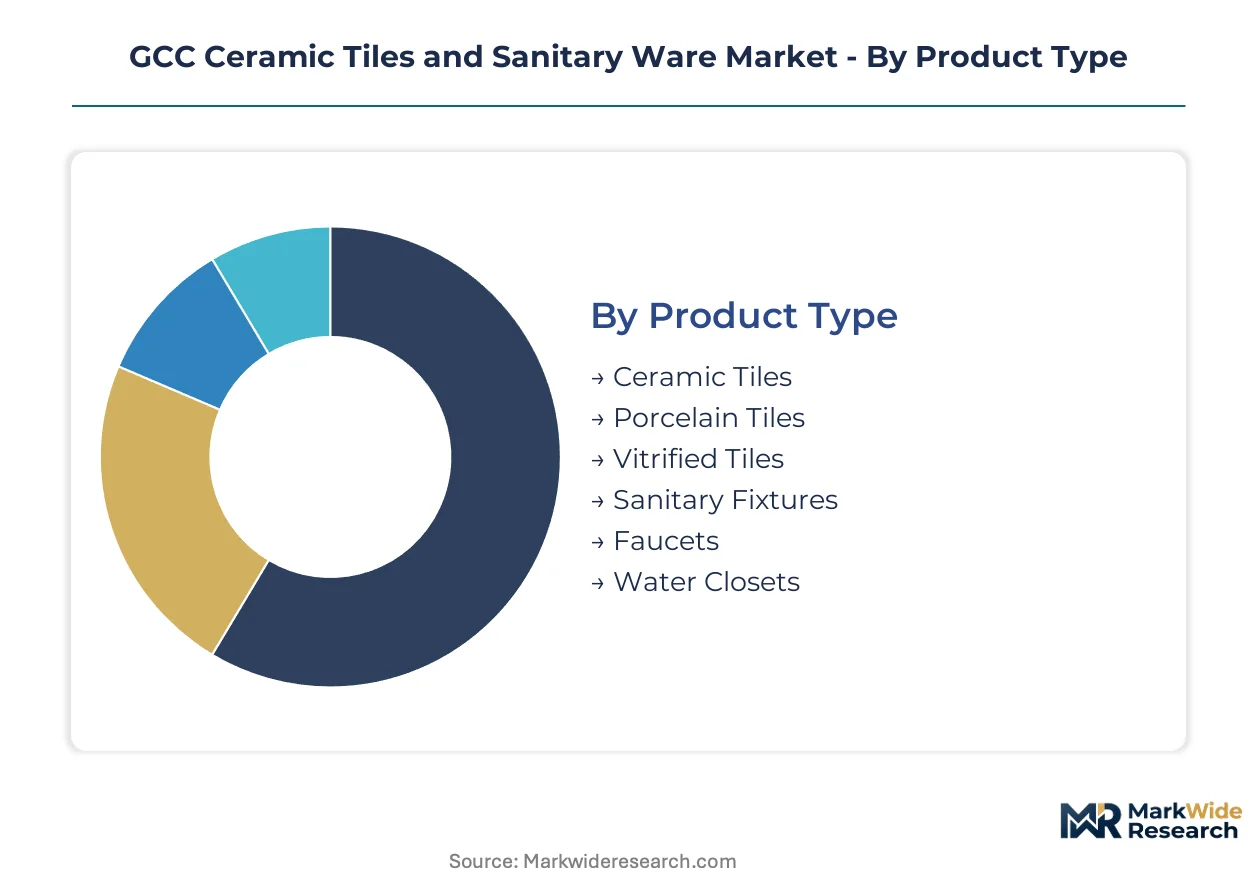
Segmentation in the GCC ceramic tiles and sanitary ware market reveals divergent procurement rhythms across product categories and customer channels. Replacement cycles for sanitary fixtures compress to 7-10 years in hospitality venues while porcelain tile installations in residential towers extend beyond 25 years, creating distinct inventory and specification strategies for manufacturers.
Product Type:
Cycle times vary dramatically across product categories, with surface materials outlasting fixtures by factors of three or more in Gulf climates.
- Ceramic Tiles:Traditional glazed clay products fired at lower temperatures serve budget residential applications across Saudi Arabia's mass housing developments. Demand concentrates in Riyadh's affordable housing zones where SASO compliance costs squeeze margins for imported alternatives.
- Porcelain Tiles:Vitrified slabs with water absorption below 0.5% dominate Dubai's luxury residential towers and commercial lobbies. Large-format specifications above 1200mm are accelerating in UAE hospitality projects where seamless aesthetic requirements override cost considerations.
- Vitrified Tiles:Double-charged and soluble salt variants balance durability with cost efficiency for Qatar's infrastructure corridors and educational facilities.
- Sanitary Fixtures:Ceramic basins, pedestals, and cisterns face replacement pressure from water-efficiency mandates across Emirates Authority for Standardization and Metrology jurisdictions.
- Faucets:Brass and stainless steel configurations with ceramic disc cartridges see fastest specification turnover in renovation channels.
- Water Closets:Wall-hung and floor-mounted configurations diverge by building age, with concealed cistern systems dominating new Dubai towers while replacement markets favor close-coupled designs.
Ceramic tiles anchor the volume base while porcelain tiles gain share at the steepest rate.
Application:
Cost tiers stratify sharply across end-use segments, with hospitality procurement budgets exceeding residential specifications by 400-600% per square meter.
- Residential Construction:Villa compounds and apartment towers across Dubai's master-planned communities generate sustained volume for mid-range porcelain and ceramic grades. Saudi giga-developments are consolidating procurement through project-direct channels that bypass traditional distributor markups.
- Commercial Establishments:Office towers and retail centers in Doha's Lusail district specify abrasion-resistant vitrified grades for high-traffic flooring. Technical performance requirements here filter out lower-grade imports that dominate residential channels.
- Institutional Buildings:Schools and healthcare facilities across Kuwait prioritize anti-bacterial glazed surfaces and accessibility-compliant sanitary configurations.
- Hospitality Venues:Hotel and resort developments in Riyadh's Diriyah Gate and Qiddiya projects specify premium large-format porcelain and designer sanitary collections.
- Infrastructure Projects:Metro stations, airports, and transit corridors across the GCC deploy heavy-duty vitrified tiles with slip-resistant finishes.
Residential construction maintains the deepest volume footprint while hospitality venues deliver the highest margin realization per unit.
Installation Type:
Customer type concentration varies by installation phase, with architects dominating new construction specifications and contractors controlling renovation procurement decisions.
- New Construction:Greenfield developments across Saudi giga-projects enable single-source sanitary ware agreements covering thousands of units. RAK Ceramics and Saudi Ceramics leverage manufacturing proximity to secure multi-year supply contracts.
- Renovation:Existing residential stock in Dubai's older districts generates replacement demand for outdated ceramic installations. Retrofit projects favor adhesive-friendly thin porcelain slabs that minimize structural load concerns.
- Retrofitting:Qatar's post-World Cup hospitality conversion is repurposing stadium accommodation into permanent hotel inventory, requiring sanitary system upgrades.
- Replacement:Failed fixtures and damaged tiles in high-traffic commercial environments drive spot procurement through distributor networks.
- Expansion:Hotel capacity additions and retail extension projects follow specification continuity requirements that favor incumbent suppliers.
New construction commands the longest planning horizons while renovation cycles are compressing toward 5-7 year intervals in premium hospitality assets.
Customer Type:
Specification authority is migrating upstream in megaproject procurement, with centralized procurement offices displacing traditional distributor intermediaries.
- Architects:BIM-integrated product libraries are enabling direct manufacturer-to-specifier relationships, particularly for large-format porcelain and designer sanitary collections. Dubai and Riyadh practices are consolidating preferred supplier lists to three or fewer brands per category.
- Contractors:Turnkey construction firms across Saudi Arabia's Neom and Red Sea projects negotiate bulk supply agreements that bundle tiles, fixtures, and installation services.
- Interior Designers:Hospitality and luxury residential projects in Doha and Abu Dhabi specify custom finishes and coordinated sanitary collections that command 40-60% premiums over standard grades.
- Distributors:Traditional stocking intermediaries are retreating to project-direct markets as manufacturer logistics capabilities improve across the GCC.
- Retailers:Showroom-based sales persist in replacement and renovation channels serving villa owners and small contractors.
Contractors control the largest transaction values while architects are gaining influence fastest through digital specification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port container terminals anchor Dubai's distribution dominance for ceramic tile imports across the Arabian Peninsula.
Saudi Arabia
Diriyah Gate and Qiddiya giga-developments are consolidating sanitary ware procurement through project-direct channels. SASO quality mark requirements are filtering substandard Asian suppliers from Riyadh's construction pipeline. Eastern Province manufacturing clusters near Dammam are expanding roller kiln capacity to serve Neom's northwest construction corridor.
United Arab Emirates
Dubai's sustained real estate development sustains large-format porcelain tile volumes for hospitality and residential towers. Emirates Authority for Standardization and Metrology water-efficiency labeling mandates are compressing demand toward low-flow fixture configurations. Jebel Ali free zone manufacturing bases anchor pan-GCC distribution networks for premium ceramic grades.
Qatar
Post-World Cup stadium and accommodation assets are being repurposed into permanent hotel inventory, generating replacement demand for sanitary installations. The country's national standardization body enforces ceramic quality marks that align with GCC harmonization protocols. Lusail district commercial towers specify abrasion-resistant vitrified grades for high-traffic flooring applications.
Kuwait
Institutional building programs across schools and healthcare facilities prioritize anti-bacterial glazed surfaces and accessibility-compliant sanitary configurations. The national quality infrastructure regulator maintains ceramic import standards that exceed baseline GCC technical requirements. Kuwait City metropolitan construction clusters concentrate procurement through centralized contractor agreements.
GCC Ceramic Tiles and Sanitary Ware Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and kiln technology supply. The vendor base stratifies across three tiers: pan-regional manufacturers with captive GCC production, import-dependent distributors serving renovation channels, and project-direct specification teams embedded within giga-developments. Dominant competitive moves include backward integration into feldspar and kaolin sourcing to secure input cost stability, and strategic partnerships with architect procurement platforms to bypass traditional distributor intermediaries.
Within the integrated manufacturing tier, RAK Ceramics and Saudi Ceramics exemplify platform players with captive UAE and domestic Saudi production bases respectively. Porcelanosa occupies a position among design-led European specialists competing for architect-specified residential towers. These three anchors represent divergent strategic archetypes: proximity-driven supply security, import-dependent design positioning, and project-direct volume capture.
| Leading Market Players |
|---|
| Porcelanosa |
| Duravit |
| RAK Ceramics |
| Riyadh Ceramics |
| Jaquar Middle East |
| Saudi Ceramics |
| Al Anwar Ceramic Tiles Co. |
| Al Maha Ceramics |
| Arabian Ceramics |
| Others |
Supply & Pricing Matrix
Indian and Chinese feldspar deposits anchor upstream raw material supply, concentrating margin capture with manufacturers possessing captive mineral sourcing or long-term offtake agreements. This upstream consolidation shapes downstream pricing power across the GCC ceramic tiles and sanitary ware sector, rewarding integrated producers while squeezing import-dependent distributors.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations across Saudi giga-developments and Dubai hospitality projects, with project-direct agreements commanding 15-30% unit cost reductions against distributor spot pricing. Price differentiation rests on SASO certification grade and water-efficiency labeling compliance, with Emirates Authority for Standardization and Metrology Tier 1 fixtures capturing 40% premiums over uncertified alternatives. Pricing pressure stems from natural gas input volatility compressing kiln operation margins. Residential renovation channels exhibit highest price sensitivity, while hospitality procurement teams prioritize performance specifications over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with RAK Ceramics' UAE facilities and Saudi Ceramics' Riyadh-Dammam corridor, supplemented by Spanish design houses serving architect-specified premium segments. Raw material dependencies encompass Saudi white clay deposits, Indian feldspar, and Italian glaze pigments. Supply chain risk centers on Strait of Hormuz shipping chokepoints exposing Asian tile imports to extended lead time volatility. Distribution runs through Jebel Ali free zone consolidation hubs serving pan-GCC project logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where SASO and Emirates Authority for Standardization and Metrology certification entrenchment creates formidable switching costs for institutional buyers. Network effects concentrate specification authority among architect-consolidated preferred supplier lists, deepening incumbent advantages.
For Market Incumbents: Insulate market position through backward integration into Saudi feldspar mining concessions and captive roller kiln capacity additions in the Eastern Province. Threat from low-cost Asian imports persists despite tightening compliance thresholds. Certification investment in water-efficiency labeling represents the critical defensive lever against European design-house encroachment in hospitality segments. For New Entrants and Emerging Players: Kuwait's institutional building programs offer geographic underpenetration with concentrated contractor procurement and anti-bacterial surface specifications creating differentiation entry points. Qatar's post-World Cup hospitality conversion generates replacement demand for sanitary installations with compressed incumbent relationships. Target specification through BIM-integrated product libraries to bypass traditional distributor gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European design specialists seeking GCC distribution scale. Long-term viability hinges on regulatory entrenchment durability across the analysis window. Acquisition target archetype: mid-cap manufacturers with SASO pre-certification and project-direct relationships in Riyadh's giga-development pipeline. Monitor Emirates Authority for Standardization and Metrology labeling mandate expansion as inflection indicator for low-flow fixture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feldspar Mining | Captive Saudi mineral supply secures input cost stability against Indian import volatility. |
| SASO Pre-Certification Investment | Accelerated compliance timelines filter Asian competitors from Riyadh megaproject tenders. |
| BIM Platform Partnership | Direct architect specification relationships displace traditional distributor intermediaries. |
| Roller Kiln Capacity Expansion | Eastern Province manufacturing proximity reduces logistics costs to Neom construction corridor. |
| Water-Efficiency Labeling Compliance | Emirates Authority for Standardization and Metrology Tier 1 status unlocks hospitality procurement. |
Research Methodology
Desk research of SASO technical regulations, GCC Standardization Organization harmonization protocols, and Emirates Authority for Standardization and Metrology labeling requirements preceded structured interviews with procurement directors at Saudi giga-developments, hospitality FF&E consultants, roller kiln operations engineers, and ceramic import distributors. Secondary validation drew from customs trade databases, construction project tracking registries, and hospitality development pipeline disclosures. Bottom-up unit demand estimates triangulated against top-down construction spend allocations.
Forecast assumptions held natural gas pricing regimes and regulatory compliance timelines fixed while varying tourism infrastructure investment trajectories and residential renovation cycle frequencies across the projection horizon. Segmentation modeling incorporated product type, application, installation phase, and customer specification authority. CAGRs derived from construction pipeline quantification and replacement cycle compression analysis. Industry-specific inputs included hospitality room inventory expansion targets and water-efficiency mandate enforcement intensity.
Practitioners should monitor SASO quality mark threshold revisions and Emirates Authority for Standardization and Metrology labeling expansion for early signals of competitive filtration acceleration. Forecasts reflect assumptions regarding regulatory enforcement consistency and giga-development execution continuity. Quarterly review of construction contract awards and hospitality project completions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
North America Ceramic Coatings Market
Ceramics
Pottery Ceramics Market
Ceramics
Wollastonite Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Europe Activated Alumina Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Kaolin Market
Ceramics
White Fused Alumina Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Cordierite Market
Ceramics
Construction Ceramics Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Taiwan Ceramic Tiles Market