
 Advanced Sintering Technologies Market | 2026-2036
Advanced Sintering Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Sintering Technologies Market Analysis
ISO 9001 certification for thermal process equipment is bifurcating the competitive landscape into qualified system suppliers and commodity furnace vendors. Tenova S.p.A. leverages its vertical integration from furnace design to process automation to dominate large-scale metal sintering installations. ALD Vacuum Technologies GmbH anchors the European market through specialized vacuum hot pressing systems for aerospace superalloys. SECO/WARWICK S.A. competes across multiple thermal technology platforms, extending its reach from heat treatment into advanced sintering applications.
Advanced sintering technologies encompass powder consolidation methods that apply heat and pressure—typically 1,000°C to 2,200°C with pressures from 10 to 200 MPa—to densify ceramics, metals, and composites without full melting, producing net-shape components with >99% theoretical density for structural, thermal, and electrical applications. Selective laser sintering leads technology adoption in polymer and metal additive manufacturing, while field assisted sintering captures premium margin pools in nanostructured ceramic production. Hot isostatic pressing occupies the mature high-value segment for aerospace defect healing, whereas electric discharge sintering remains an emerging niche for rapid consolidation of conductive materials.
FDA 21 CFR Part 820 quality system regulation shapes biomedical sintering demand by mandating process validation for implantable devices, while EPA NESHAP standards constrain furnace emissions in US manufacturing facilities. REACH compliance in Europe restricts certain binder chemistries used in powder metallurgy, redirecting R&D toward water-based and bio-derived alternatives. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with energy-intensive thermal processing economics.
Market Dynamics
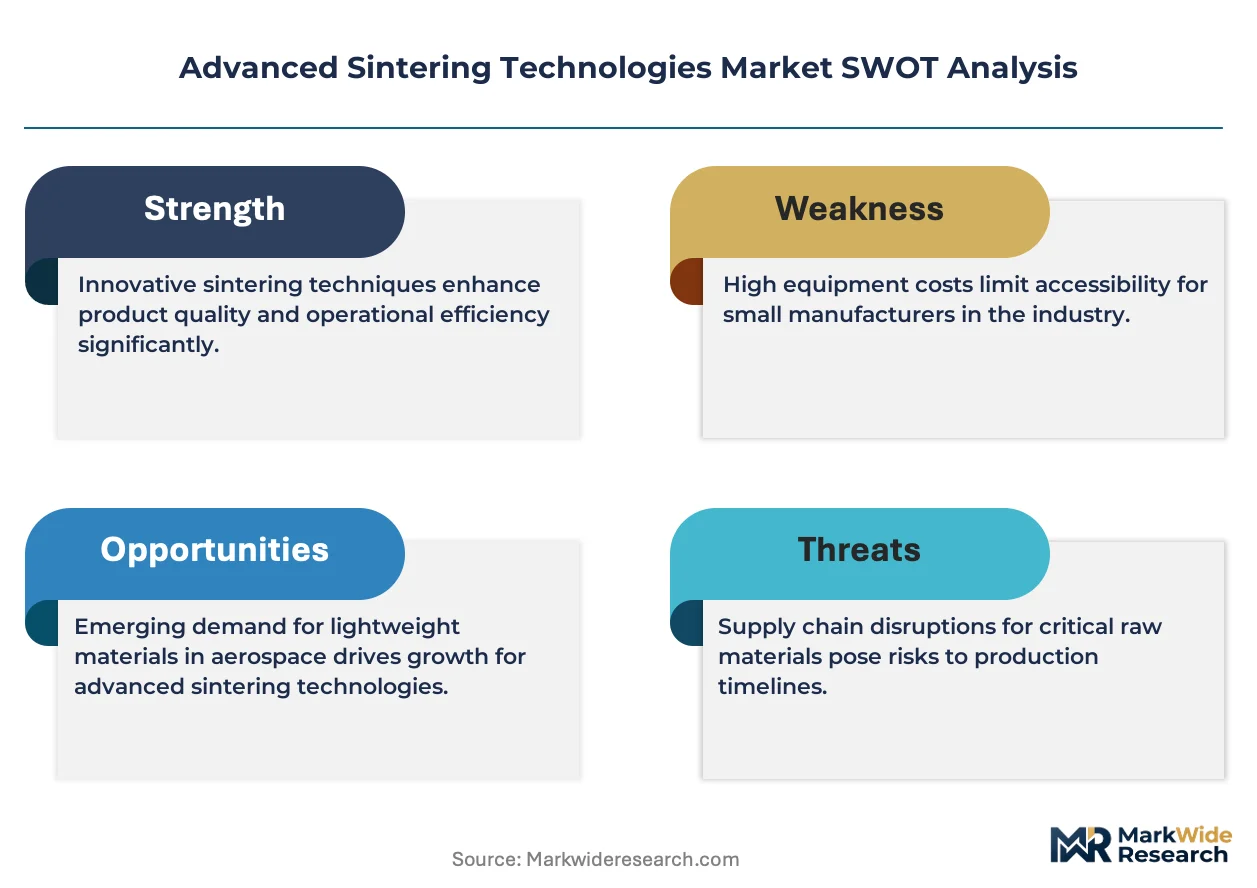
China's MIIT dual carbon goals are electrifying furnace mandates across the precision manufacturing corridor, bifurcating qualified system suppliers from commodity vendors as energy-intensive thermal processing faces carbon border adjustment pressure.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's furnace electrification requirements are accelerating replacement cycles in Aachen and Dresden precision clusters, pulling demand toward qualified electric system suppliers.
- FDA 21 CFR Part 820:Process validation requirements for implantable biomedical devices are expanding sintering adoption in orthopedic and dental implant manufacturing.
- Selective Laser Sintering:Aerospace turbine blade producers are expanding additive manufacturing capacity, consolidating net-shape production without traditional casting defects.
Market Restraints
- Tungsten and Molybdenum Price Volatility:Furnace heating element costs fluctuate with mining supply disruptions, compressing margins for vacuum hot pressing system operators.
- German Precision Corridor Concentration:Qualified furnace engineering talent and subcomponent suppliers cluster around Aachen-Dresden, creating geographic supply risk for global project timelines.
- REACH Binder Restrictions:ECHA limitations on traditional powder metallurgy chemistries are forcing costly R&D pivots toward unproven water-based alternatives.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced manufacturing are opening greenfield sintering capacity for automotive and defense component suppliers.
- Field Assisted Sintering Convergence:Integration with nanostructured ceramic production is capturing premium margin pools in semiconductor thermal management substrates.
- EU Carbon Border Adjustment Mechanism:CBAM implementation is creating competitive advantage for European electric furnace operators against carbon-intensive imports.
Industry Challenges
- ISO 9001 Thermal Process Certification:The 12-18 month qualification timeline for aerospace system approvals is constraining vendor expansion into defense supply chains.
- Multi-Physics Simulation Expertise:Coupled thermal-mechanical-electric field modeling for field assisted sintering process design exceeds available computational materials engineering talent pools.
- Legacy Heat Treatment Integration:Brownfield facilities face capital-intensive reconfiguration to accommodate advanced sintering workflows alongside existing furnace infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Sintering Technologies Market |
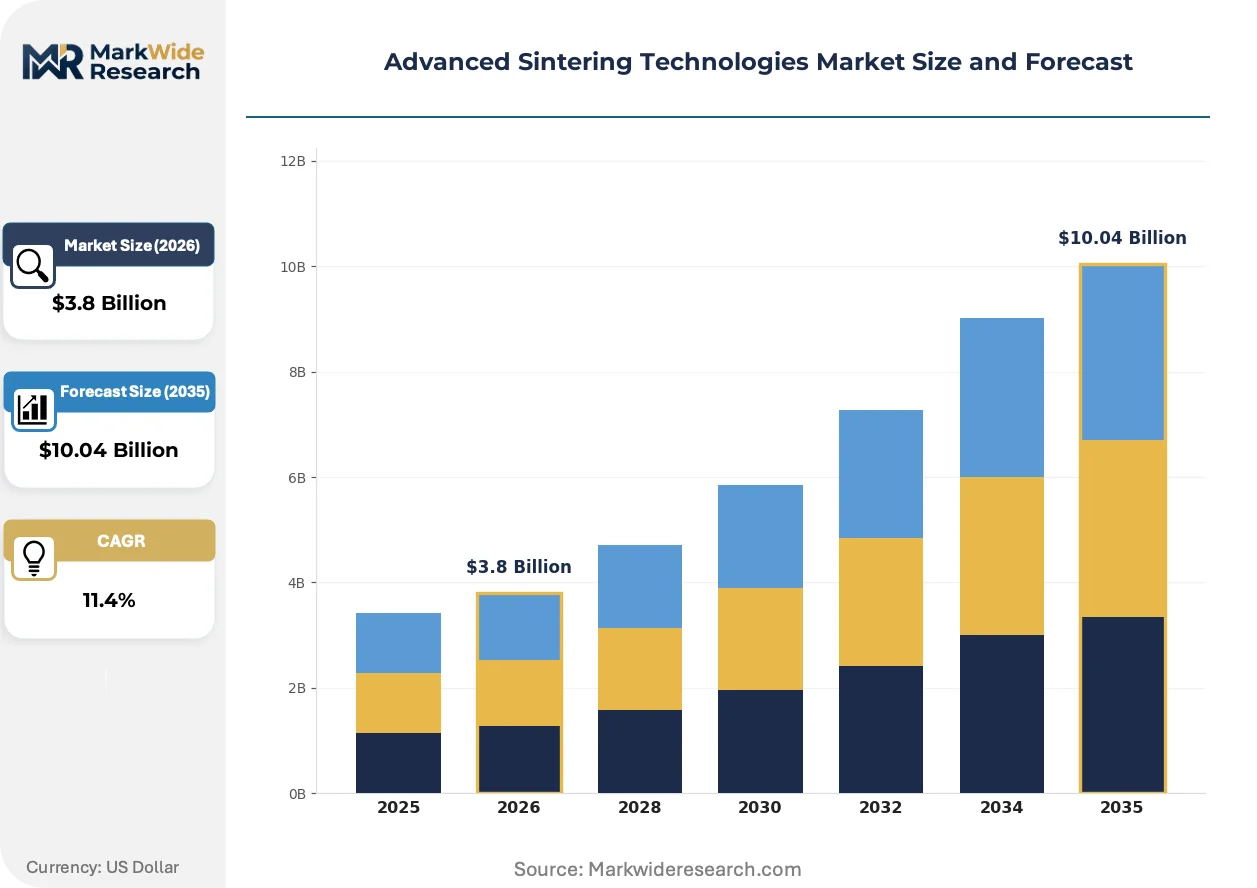
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electric Discharge Sintering, Field Assisted Sintering, Selective Laser Sintering, Hot Isostatic Pressing Material Type: Ceramics, Metals, Polymers, Composites Application: Aerospace, Automotive, Biomedical, Electronics End User: Manufacturers, Research Institutions, OEMs, Service Providers |
| Companies Covered | Tenova S.p.A., Linn High Therm, ALD Vacuum Technologies GmbH, Sumitomo Heavy Industries Ltd., BTU International, SECO/WARWICK S.A., FCT Systeme, GE Additive, Ipsen International Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Sintering Technologies Market Emerging Trajectories
Electrification mandates and additive manufacturing maturation are fragmenting traditional thermal processing workflows, while regulatory pressure on emissions and biomedical quality systems accelerates technology substitution cycles.
Spark plasma sintering is fragmenting conventional hot pressing market share by enabling sub-10-minute consolidation cycles for nanostructured ceramics. Medical implant manufacturers are adopting these systems for titanium porous structures, compressing traditional vacuum furnace investment timelines. The technology is fragmenting equipment vendor revenue pools toward integrated field-assisted platforms with in-situ densification monitoring.
EPA NESHAP standards for hazardous air pollutants from thermal processing are tightening emissions monitoring requirements across US manufacturing facilities. Metal powder sintering operations face retrofit costs for capture and abatement systems, redirecting capital toward electric alternatives. California and Texas industrial clusters are responding fastest, with facility engineers prioritizing furnace electrification in expansion planning.
Certification-driven procurement is compressing vendor qualification cycles as aerospace primes consolidate approved supplier lists. Buyers now demand ISO 9001 thermal process documentation upfront, displacing traditional trial-order relationships. This pattern concentrates most visibly in Germany's precision manufacturing corridor, where system integrators bundle process validation services with equipment sales to accelerate adoption.
Advanced Sintering Technologies Market Segmentation
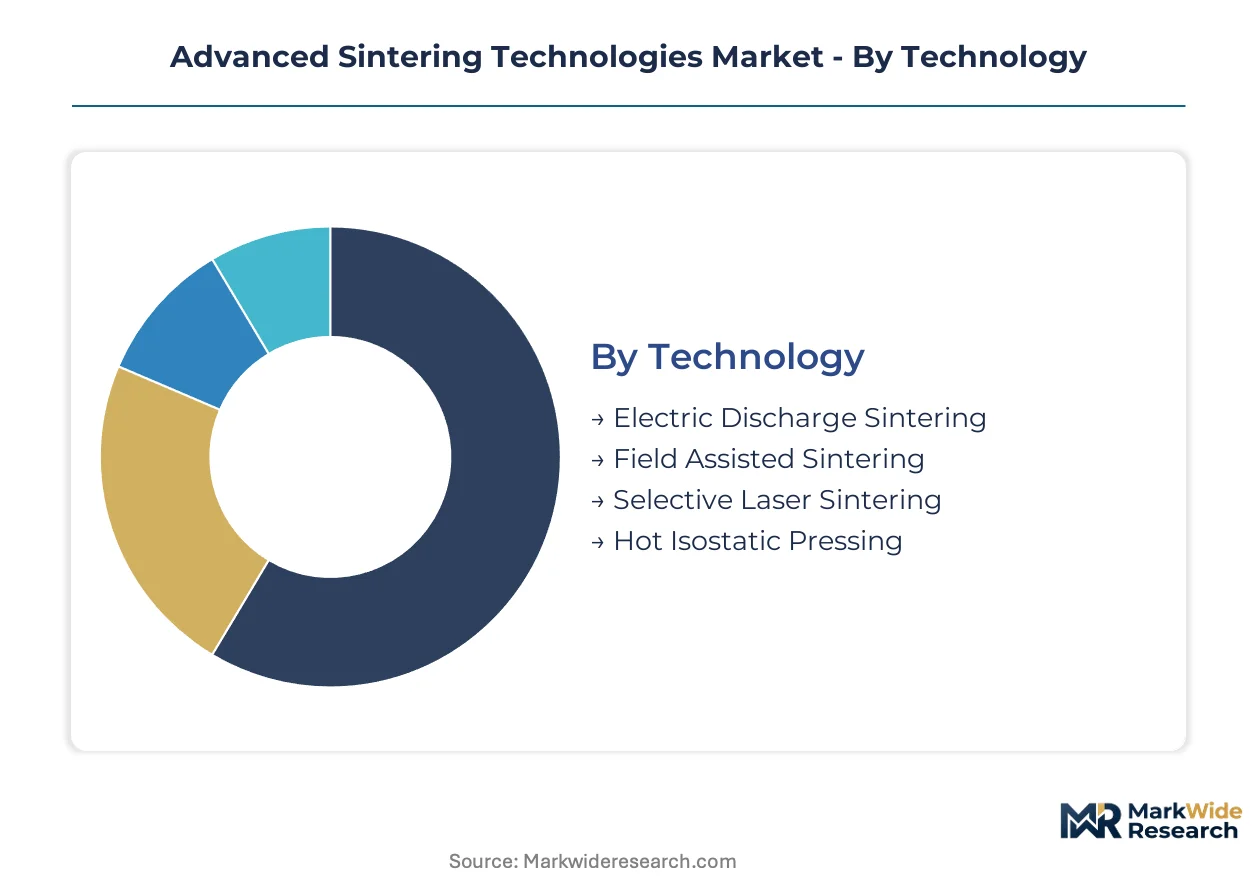
Technology-material-application-end user intersections determine equipment specification, process validation requirements, and service contract structures across the advanced sintering value chain. Margin capture varies dramatically by segment pairing—field assisted systems serving biomedical ceramics command fundamentally different pricing architectures than commodity polymer laser sintering for prototyping services.
Technology:
Premium margin pools concentrate in field assisted and hot isostatic pressing platforms where aerospace and medical certification barriers limit vendor competition.
- Field Assisted Sintering:Spark plasma and flash sintering platforms apply pulsed DC current with uniaxial pressure to achieve sub-10-minute consolidation cycles. Nanostructured ceramic producers in Germany's precision corridor are adopting these systems for semiconductor thermal management substrates, displacing conventional vacuum furnace investments.
- Hot Isostatic Pressing:Gas-pressure densification at 100-200 MPa and 1,000-2,000°C heals internal defects in cast and sintered superalloys. Aerospace turbine blade manufacturers specify HIP for critical rotating components, with process validation tied to FAA airworthiness certification pathways.
- Selective Laser Sintering:Layer-wise polymer and metal powder fusion dominates additive manufacturing prototyping and short-run production.
- Electric Discharge Sintering:Rapid Joule heating of conductive powders remains experimental for copper-graphite composites and refractory metal consolidation.
Hot isostatic pressing holds installed capacity across legacy aerospace supply chains. Field assisted sintering is rotating up the share rankings in nanostructured ceramic applications.
Material Type:
Material-process compatibility dictates furnace atmosphere control, heating element selection, and cooling rate specifications that cascade into equipment pricing tiers.
- Metals:Titanium, nickel superalloys, and tool steels require vacuum or inert atmosphere processing to prevent oxidation during high-temperature densification. Orthopedic implant manufacturers in the US and Germany drive demand for titanium porous structures with FDA 21 CFR Part 820 and EU MDR process validation requirements.
- Ceramics:Oxide and non-oxide ceramics demand precise thermal profiling and controlled atmosphere sintering for structural and electronic applications. Alumina and zirconia components for dental and orthopedic implants concentrate demand in certified biomedical supply chains.
- Polymers:Nylon 12 and TPU powders dominate laser sintering for functional prototyping and end-use parts.
- Composites:Metal-matrix and ceramic-matrix composites require hybrid processing approaches combining powder consolidation with fiber reinforcement.
Metals retain the largest installed equipment base. Ceramics are climbing the fastest in revenue contribution as semiconductor thermal management applications expand.
Application:
End-use certification intensity separates qualified system suppliers from commodity equipment vendors, with aerospace and biomedical applications imposing the steepest qualification barriers.
- Aerospace:Turbine blades, structural brackets, and thermal protection systems require defect-free microstructures with traceable process documentation. Selective laser sintering of nickel superalloys is consolidating net-shape production at GE Aviation and Pratt & Whitney facilities, eliminating traditional casting porosity.
- Biomedical:Implants and surgical instruments demand biocompatible surface finishes with validated sterilization compatibility. FDA 21 CFR Part 820 and EU MDR quality system regulations mandate process validation that extends equipment procurement cycles to 18-24 months.
- Automotive:Gears, bearings, and valve train components leverage powder metallurgy for cost-effective net-shape production.
- Electronics:Heat sinks, substrates, and passive components require thermal and electrical property optimization through controlled densification.
Aerospace commands the highest average equipment values. Biomedical is expanding most quickly as aging demographics drive implant procedure volumes.
End User:
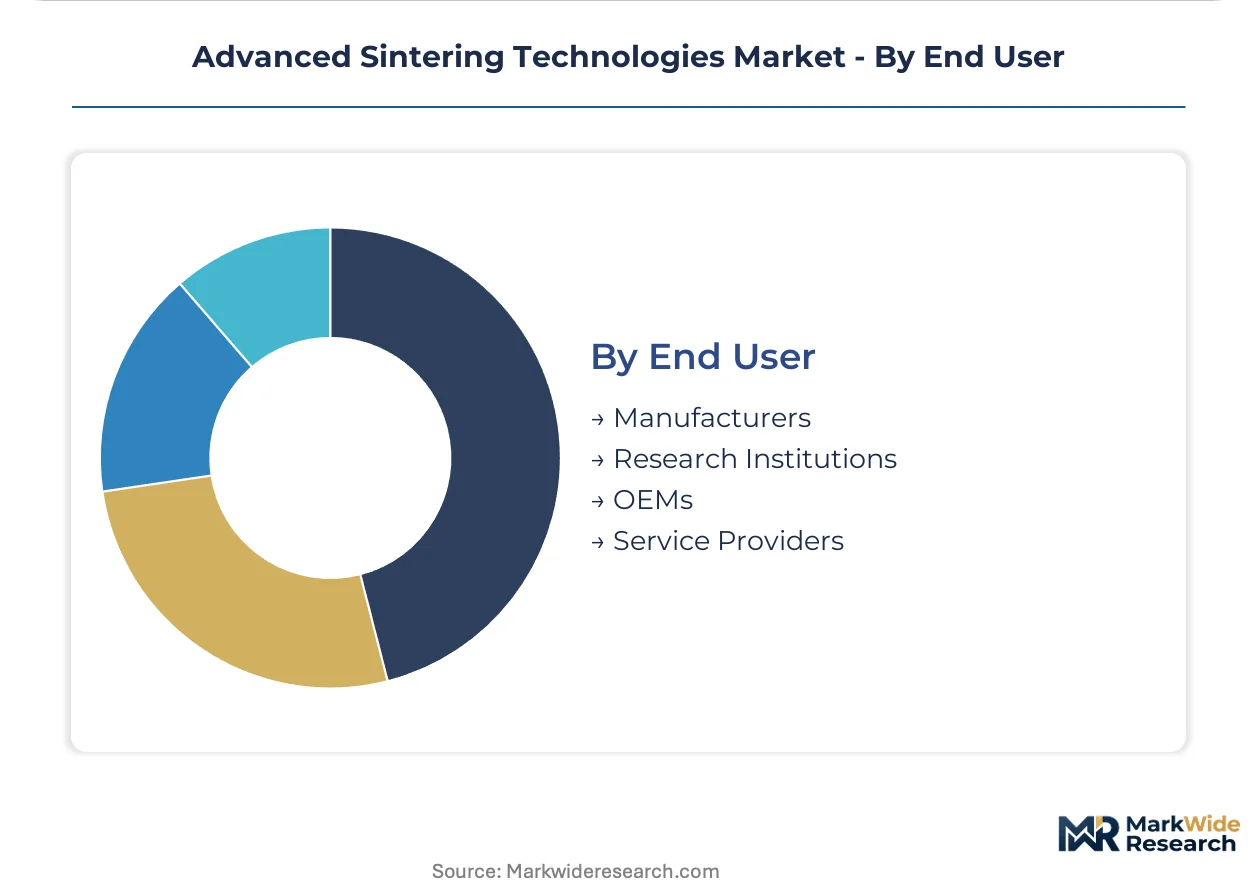
Customer type determines service contract structures, with OEMs and research institutions representing contrasting procurement patterns of capital ownership versus fee-for-access.
- OEMs:Original equipment manufacturers in aerospace, automotive, and medical device sectors invest in captive sintering capacity for proprietary component production. Boeing, Siemens Healthineers, and BMW operate internal additive manufacturing centers with dedicated process engineering teams.
- Research Institutions:Universities and national laboratories pioneer novel sintering protocols for materials science advancement. Germany's Fraunhofer Institutes and US National Labs maintain field assisted sintering platforms for government-funded ceramic and metal matrix composite research.
- Manufacturers:Tier suppliers and contract manufacturers purchase equipment for production-scale component supply.
- Service Providers:Bureaus offer on-demand sintering access without customer capital investment.
OEMs hold the dominant installed base. Research institutions are gaining share fastest as public funding for advanced materials expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon mandates in China are electrifying industrial furnace infrastructure worldwide, redirecting capital toward qualified electric system suppliers and compressing replacement cycles in precision manufacturing clusters across Germany, the United States, Japan, and India.
China
Domestic furnace electrification requirements under MIIT dual carbon goals are accelerating displacement of gas-fired thermal processing equipment. MEE emissions standards tighten compliance timelines for powder metallurgy operations. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces are retrofitting sintering lines with electric alternatives ahead of regulatory deadlines.
Germany
Aachen-Dresden precision corridor concentration drives demand for ISO 9001-certified thermal process equipment with embedded process validation services. ECHA REACH restrictions on traditional powder metallurgy binder chemistries redirect R&D toward water-based alternatives. Fraunhofer Institutes in Dresden anchor collaborative development of field assisted sintering protocols for semiconductor thermal management substrates.
United States
EPA NESHAP hazardous air pollutant standards mandate emissions capture retrofits for legacy thermal processing facilities. FDA 21 CFR Part 820 quality system regulation extends equipment procurement cycles to 18-24 months for orthopedic implant manufacturers. California and Texas industrial clusters prioritize furnace electrification in expansion planning to preempt federal enforcement actions.
Japan
METI industrial decarbonization roadmaps incentivize replacement of carbon-intensive sintering infrastructure with electric alternatives. JIS standards for thermal process equipment create certification barriers for imported systems. Kansai region manufacturers around Osaka concentrate demand for hot isostatic pressing systems serving aerospace superalloy supply chains.
India
PLI scheme production-linked incentives for advanced manufacturing open greenfield sintering capacity for automotive and defense component suppliers. BIS certification requirements for industrial thermal equipment extend vendor qualification timelines. Tamil Nadu and Maharashtra precision engineering clusters attract captive sintering investments from tier-one automotive suppliers.
Advanced Sintering Technologies Market Vendor Landscape
Listed leaders compete with private specialists across furnace engineering and thermal process automation, producing a tiered structure where scale-driven conglomerates face focused mid-cap equipment builders. Consolidation concentrates in large-scale metal sintering installations and vacuum hot pressing platforms, while fragmentation persists in field assisted and additive manufacturing niches. Strategic archetypes include vertically integrated furnace-to-automation suppliers, specialized vacuum technology developers, and diversified thermal platform operators. Competitive moves center on backward integration into heating element supply and geographic expansion through process validation service bundling.
Among European furnace engineering specialists, ALD Vacuum Technologies GmbH and SECO/WARWICK S.A. exemplify contrasting strategic positions within the qualified system supplier tier. ALD Vacuum Technologies GmbH anchors German-origin vacuum technology expertise through its GmbH structure. SECO/WARWICK S.A. represents Polish-based diversification across multiple thermal technology platforms. Tenova S.p.A. occupies a distinct position as an Italian S.p.A. with demonstrated vertical integration from furnace design through process automation. These three entities collectively illustrate the geographic and structural diversity competing for aerospace and medical certification-driven procurement.
| Leading Market Players |
|---|
| Tenova S.p.A. |
| Linn High Therm |
| ALD Vacuum Technologies GmbH |
| Sumitomo Heavy Industries Ltd. |
| BTU International |
| SECO/WARWICK S.A. |
| FCT Systeme |
| GE Additive |
| Ipsen International Holding GmbH |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 820 process validation requirements gate both supplier qualification timelines and price differentiation in advanced sintering equipment procurement. Certification-grade furnace systems command substantial premiums over commodity thermal processing units, while uncertified vendors face exclusion from aerospace and biomedical supply chains regardless of cost position.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with ISO 9001 and FDA-grade systems commanding three-tier pricing structures across premium, standard, and economy levels. Aerospace-qualified hot isostatic pressing platforms from German-origin suppliers price at substantial premiums versus uncertified alternatives from Asian manufacturers. Cost compression in standard-grade vacuum furnace segments is intensifying because of tungsten and molybdenum heating element price volatility. Contract manufacturers and tier suppliers exhibit highest price sensitivity, while OEM captive facilities prioritize certification compliance over unit economics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for furnace heating elements and vacuum pump subsystems manufactured in China and Japan. Precision manufacturing corridors in Germany, the United States, and Japan anchor qualified system supplier concentration for aerospace-grade equipment. Production draws from specialized graphite suppliers in China, refractory metal foundries in Russia, and precision machining clusters in Switzerland. Single-source vulnerability for tungsten heating elements threatens project timelines. Distribution runs through direct OEM relationships for large installations and regional service partners for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced sintering technology procurement is fragmenting across electrification mandates, additive manufacturing maturation, and biomedical certification intensification, creating specialized niches for focused equipment builders alongside integrated conglomerates.
For Market Incumbents: Fortify certification moats by accelerating FDA 21 CFR Part 820 and EU MDR process validation documentation for field assisted sintering platforms. Deepen backward integration into heating element supply chains to offset tungsten and molybdenum price volatility compressing vacuum furnace margins. Prioritize captive engineering talent retention in Germany's Aachen-Dresden precision corridor against geographic supply risk. For New Entrants and Emerging Players: Differentiate on rapid field assisted sintering process development services bundled with equipment sales, targeting nanostructured ceramic producers in semiconductor thermal management substrates. Exploit underpenetrated Indian PLI scheme greenfield capacity for automotive and defense component suppliers seeking qualified electric furnace alternatives. Lead with fee-for-access service bureau models to bypass capital-intensive OEM qualification barriers. For Investors and Strategic Acquirers: EU Carbon Border Adjustment Mechanism implementation reshapes the acquisition landscape toward European electric furnace operators with certified low-carbon process documentation. Long-term viability centers on vendors with embedded software capabilities for in-situ densification monitoring and predictive maintenance. Target mid-cap specialists with ISO 9001 thermal process certification and established aerospace prime relationships. Monitor MIIT dual carbon mandate enforcement timelines in China as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive tungsten and molybdenum supply insulates margins from mining disruption volatility. |
| Process Validation Service Bundling | Embedded FDA 21 CFR Part 820 documentation accelerates biomedical OEM procurement cycles. |
| Field Assisted Sintering Platform Launch | Sub-10-minute consolidation cycles capture premium margin pools in nanostructured ceramics. |
| Geographic Expansion via Local Certification | India BIS and China GB standards compliance opens greenfield precision manufacturing clusters. |
| Electric Furnace Electrification Transition | MIIT dual carbon alignment positions vendors for carbon border adjustment advantage. |
Methodological Framework
Operator-level perspectives from furnace engineering directors, biomedical device manufacturing executives, aerospace procurement managers, and thermal process automation specialists anchored the qualitative base. Primary interview insights combined with secondary validation from EPA NESHAP enforcement records, ECHA REACH substance restriction updates, FDA 510(k) and PMA device filings, and MIIT industrial policy circulars. SEC filings from listed furnace engineering specialists, customs data on heating element trade flows, and Fraunhofer Institute research publications provided quantitative grounding. Bottom-up equipment shipment tracking and top-down end-use demand estimation enabled cross-verification.
Sensitivity analysis tested forecast robustness against tungsten price volatility scenarios, MIIT electrification mandate acceleration variants, and aerospace OEM captive capacity expansion alternatives. Segmentation modeling spanned technology platform, material-process compatibility, application certification intensity, and end-user procurement pattern across the projection horizon. CAGRs derived from fitted growth curves applied to equipment replacement cycles, greenfield capacity announcements, and regulatory compliance deadline clustering. Industry-specific inputs incorporated semiconductor thermal management substrate demand trajectories and orthopedic implant procedure volume demographics.
Material uncertainties — tungsten supply disruption, carbon border adjustment mechanism enforcement timing, and field assisted sintering protocol standardization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through rates and qualified engineering talent availability. Practitioners should keep alternative scenarios live as dual carbon policy implementation and additive manufacturing yield rate improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Colloidal Alumina Market
Ceramics
Ceramic Kilns Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Zirconium Dioxide Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Global Ceramic Balls Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Ceramic Ware Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Zirconia Ceramics Market
Ceramics
US Kaolin Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Fly Ash and Ceramic Microsphere Market