
 Automotive LCD Display Market | 2026-2036
Automotive LCD Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive LCD Display Market Outlook
The EU Green Deal is realigning automotive display supply chains toward recyclable backlight units and low-carbon glass substrates. LG Display Co., Ltd. leverages its OLED expertise to differentiate in premium infotainment configurations. BOE Technology Group Co., Ltd. anchors high-volume TFT LCD production for Chinese OEM instrument clusters. Samsung Display Co., Ltd. competes through advanced active-matrix technology leadership in head-up display modules.
An automotive LCD display is a thin-film-transistor liquid crystal panel engineered with indium tin oxide electrodes and polarizing filters to render instrument readouts, navigation maps, and entertainment content under extreme cabin temperatures from minus forty to eighty-five degrees Celsius. TFT LCD remains the dominant product type due to mature cost curves and proven reliability in direct sunlight conditions. OLED application in infotainment systems is expanding fastest among premium vehicle platforms where contrast ratio and form-factor flexibility command margin premiums. Mini LED penetration concentrates in rear-seat entertainment where localized dimming enhances cinematic viewing experiences.
The EPA enforces volatile organic compound limits on display adhesive and coating processes affecting U.S.-bound manufacturing lines. REACH compliance in Europe mandates full material disclosure for indium and rare-earth elements in panel assemblies. NHTSA distraction-mitigation guidelines constrain head-up display luminance and field-of-view parameters. Stakeholders must monitor evolving multi-jurisdiction chemical disclosure rules alongside NHTSA's advancing driver-attention standards to preempt compliance-driven redesign cycles.
Market Dynamics
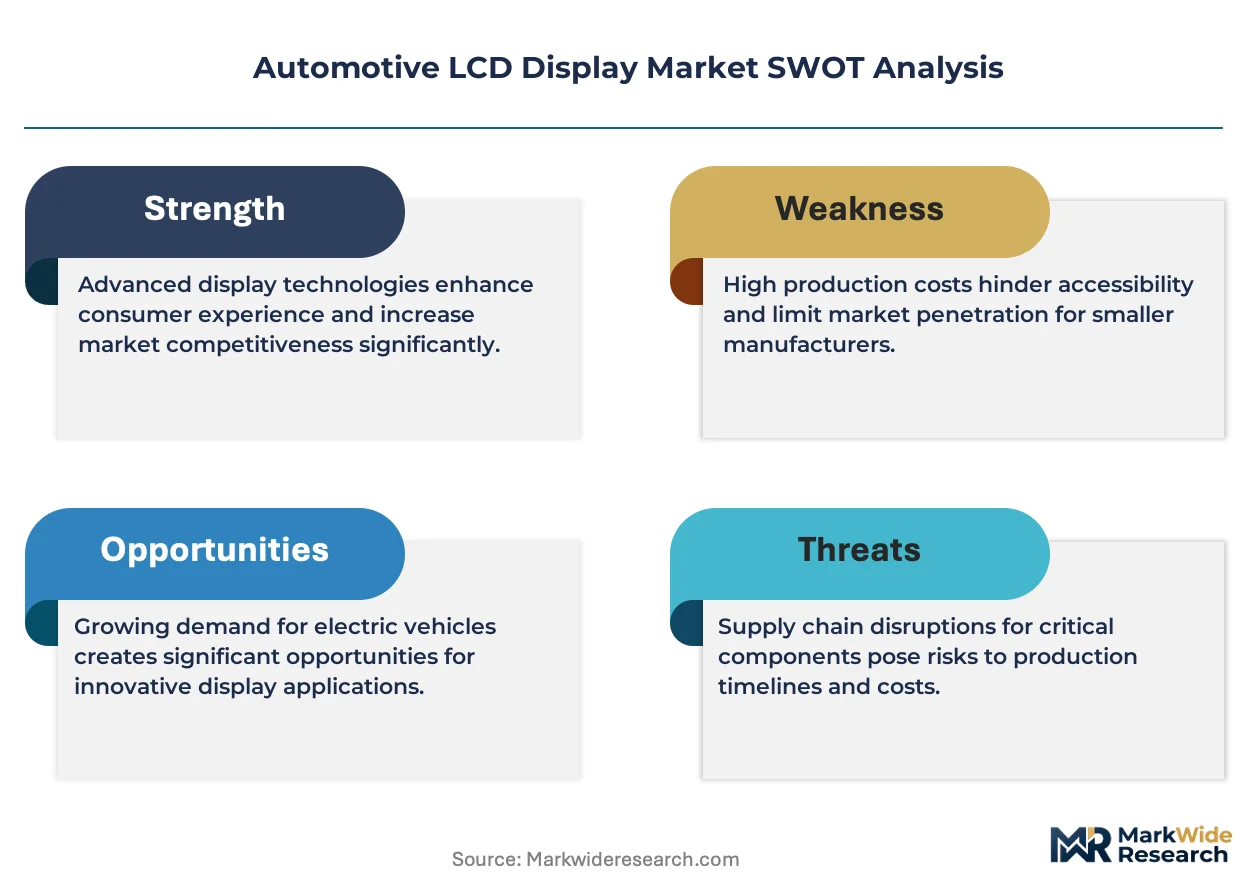
EU Green Deal material-recovery mandates are forcing display manufacturers to redesign backlight units and glass substrates for circularity, compressing traditional cost structures while opening premium positioning for compliant suppliers.
Growth Catalysts
- REACH indium disclosure:Full material traceability requirements are accelerating substitution research into alternative transparent conductive oxides for electrode layers.
- Head-up display luminance standards:NHTSA distraction-mitigation guidelines are legitimizing HUD category expansion through prescribed field-of-view and brightness parameters.
- Electric vehicle cockpit expansion:German and Chinese OEMs are specifying larger integrated display surfaces as standard equipment across mid-tier EV platforms.
Market Restraints
- Indium supply concentration:Over 80 percent of refined indium originates from Chinese smelters, creating price volatility and geopolitical exposure for ITO electrode production.
- Mini LED cost structure:Localized dimming architectures require 5-10 times more LED chips than conventional edge-lit designs, constraining adoption to ultra-premium rear-seat entertainment.
- Extreme temperature reliability:OLED organic compounds degrade faster than TFT LCD liquid crystals in sustained 85°C cabin environments, limiting instrument cluster application.
Strategic Opportunities
- Recyclable backlight unit design:EU Green Deal eco-design criteria reward modular optical film stacks that separate cleanly at end-of-life for material recovery.
- Rear-seat entertainment convergence:Cinema-grade Mini LED panels are penetrating luxury SUV and MPV segments where localized dimming commands experience premiums.
- Low-carbon glass substrate certification:Float glass producers with renewable energy sourcing can differentiate through carbon-footprint labeling demanded by German OEM sustainability scorecards.
Industry Challenges
- Multi-jurisdiction chemical compliance:Simultaneous EPA VOC limits, REACH substance restrictions, and evolving state-level disclosure rules fragment quality assurance protocols.
- Active-matrix driver IC integration:Head-up display modules require custom ASIC development cycles that extend 18-24 months, compressing platform launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive LCD Display Market |
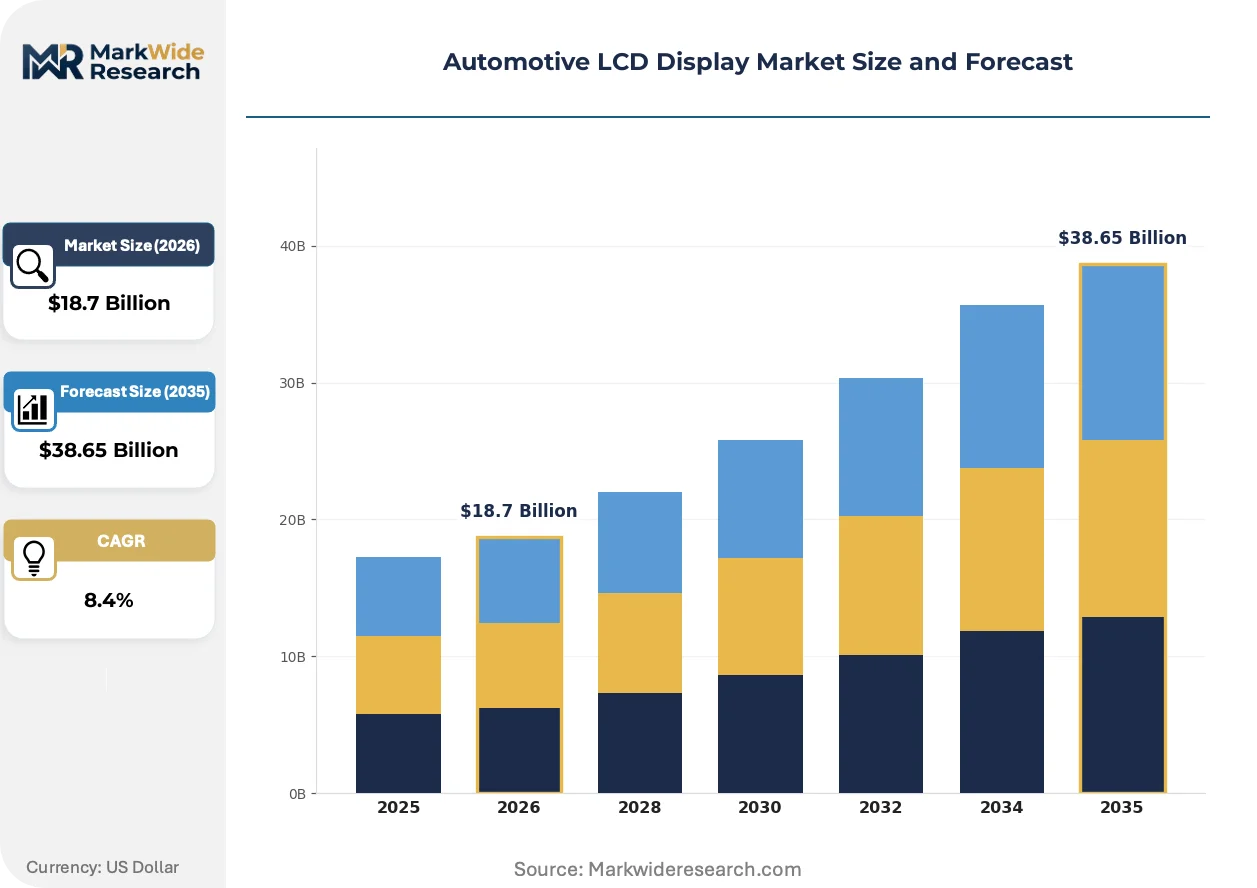
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
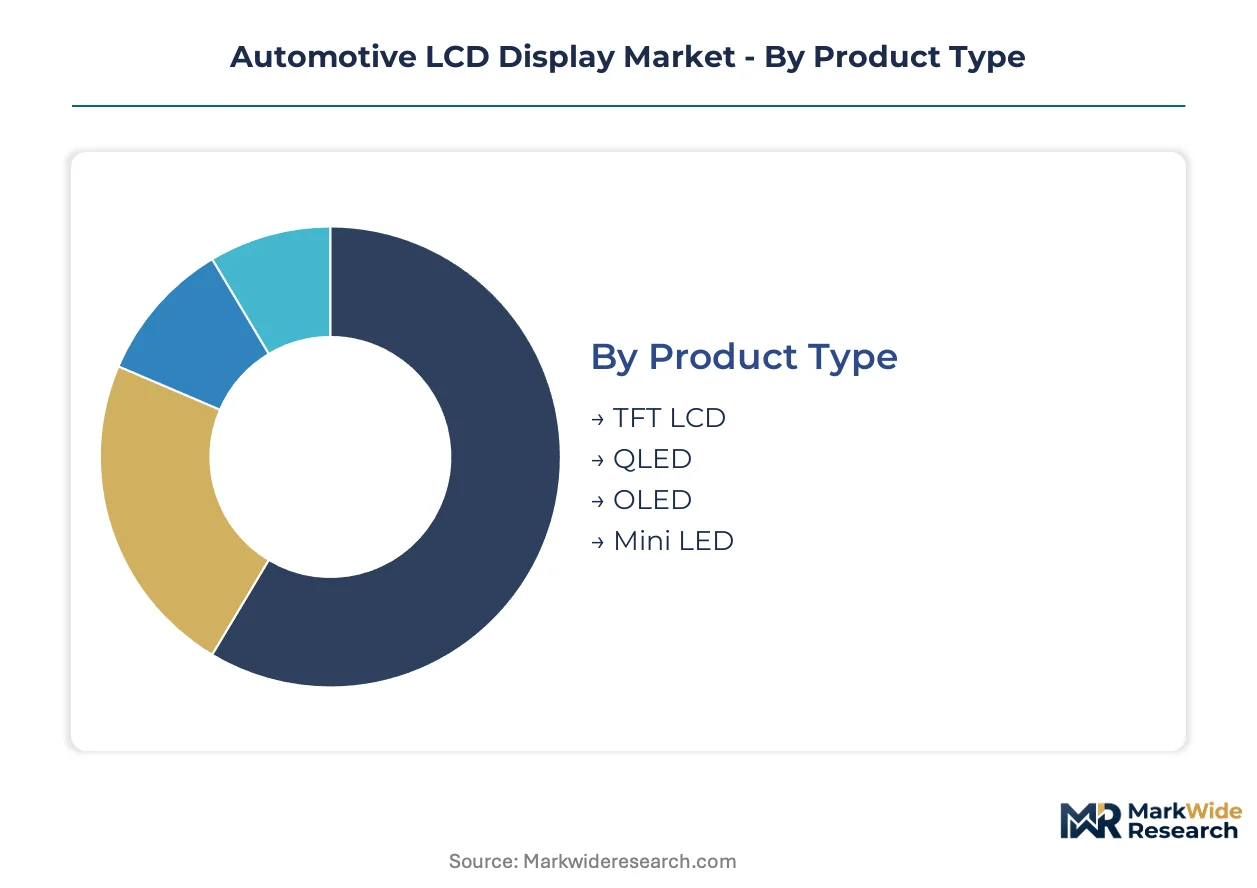
| Segmentation | Product Type: TFT LCD, QLED, OLED, Mini LED Application: Instrument Cluster, Infotainment Systems, Head-Up Displays, Rear-Seat Entertainment Technology: Active Matrix, Passive Matrix, Electroluminescent, Virtual Reality End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Japan Display Inc., Innolux Corporation, LG Display Co., Ltd., Tianma Microelectronics Co., Ltd., BOE Technology Group Co., Ltd., Sharp Corporation, AU Optronics Corporation, Truly International Holdings Limited, Samsung Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive LCD Display Market Strategic Shifts
Display technology trajectories are diverging by cabin position, with TFT LCD defending instrument cluster share through reliability certification while OLED and Mini LED carve experience-driven infotainment niches.
Mini LED backlighting is converging with quantum dot color enhancement to deliver theatrical contrast ratios in rear-seat entertainment modules. Luxury MPV and flagship SUV platforms in South Korea and Germany are specifying these configurations for differentiation. The technology is converging with content-streaming partnerships to justify hardware premiums through subscription-enabled service ecosystems.
EPA volatile organic compound enforcement on display adhesive and coating processes is tightening emission controls for U.S.-bound manufacturing lines. Tier-1 suppliers are relocating finishing operations to controlled-atmosphere facilities or reformulating chemistries to water-based alternatives. Module assembly for North American OEM programs faces 12-18 month qualification delays as facilities adapt.
Fleet procurement of standardized display specifications is compressing SKU diversity across rental and commercial vehicle channels. Volume aggregators are specifying common 10.25-inch and 12.3-inch diagonal formats with identical electrical interfaces. This consolidation is most visible in Chinese electric taxi and ride-hail platform procurement, where total cost of ownership calculations override premium feature differentiation.
Automotive LCD Display Market Segmentation
Automotive LCD display procurement patterns diverge sharply between standardized fleet specifications and bespoke premium configurations. Tier-1 suppliers in Japan and South Korea dominate instrument cluster TFT LCD volume, while German and Chinese OEMs drive customization in integrated cockpit surfaces.
Product Type:
Customization intensity spans mature cost-optimized panels to emerging premium technologies with unproven scale curves.
- TFT LCD:Thin-film-transistor liquid crystal panels with indium tin oxide electrodes and polarizing filters deliver proven reliability across minus forty to eighty-five degrees Celsius operational windows. Procurement concentrates from tier-1 suppliers in Japan and South Korea for instrument cluster applications where direct sunlight readability remains non-negotiable.
- OLED:Organic light-emitting diode configurations exploit self-emissive architecture to achieve infinite contrast ratios and curved form factors. German and Chinese premium EV platforms specify these for center-stack infotainment where design differentiation commands margin premiums, though organic compound degradation constrains instrument cluster adoption.
- QLED:Quantum dot-enhanced liquid crystal stacks leverage photoluminescent nanocrystals for expanded color gamut in mid-tier infotainment modules.
- Mini LED:Localized dimming architectures with dense LED arrays target rear-seat entertainment in luxury SUVs and MPVs where cinematic contrast justifies five-to-tenfold chip count premiums.
Most installed capacity flows through TFT LCD. Expansion is steepest in OLED.
Application:
Functional criticality determines reliability certification requirements and supplier qualification timelines across cabin positions.
- Instrument Cluster:Direct-view TFT LCD panels render speed, battery state, and diagnostic readouts with sunlight-visible luminance exceeding 800 cd/m². NHTSA distraction-mitigation guidelines constrain animation complexity while mandating failsafe operation, entrenching incumbent Japanese and South Korean suppliers with proven automotive-grade track records.
- Infotainment Systems:Center-stack displays integrate navigation, media, and vehicle settings through capacitive touch layers bonded to 10- to 15-inch diagonal panels. Chinese electric vehicle manufacturers in Germany and China are expanding specifications as standard equipment across mid-tier platforms, compressing cost structures while enlarging surface area.
- Head-Up Displays:Windshield-projected virtual images require custom active-matrix driver ASICs with 18-24 month development cycles.
- Rear-Seat Entertainment:Ceiling- and headrest-mounted screens serve luxury MPV and flagship SUV segments where localized dimming enhances streaming content consumption.
Instrument Cluster absorbs the highest unit volumes. Rear-Seat Entertainment is climbing the fastest.
Technology:
Manufacturing sophistication separates addressable markets by pixel density, refresh rate, and integration complexity.
- Active Matrix:Thin-film-transistor backplanes enable individual pixel addressing for high-resolution, fast-refresh applications. Samsung Display Co., Ltd. leverages this architecture for head-up display modules where precise luminance control meets NHTSA field-of-view parameters.
- Passive Matrix:Simplified row-column addressing suffices for low-information-content telltale indicators and basic climate readouts in economy vehicle segments.
- Electroluminescent:Solid-state phosphor emission provides uniform backlighting for legacy instrument panel applications with limited color requirements.
- Virtual Reality:Ultra-high-pixel-density microdisplays target augmented reality head-up configurations with immersive depth perception.
Active Matrix commands dominant share. Virtual Reality is gaining share fastest.
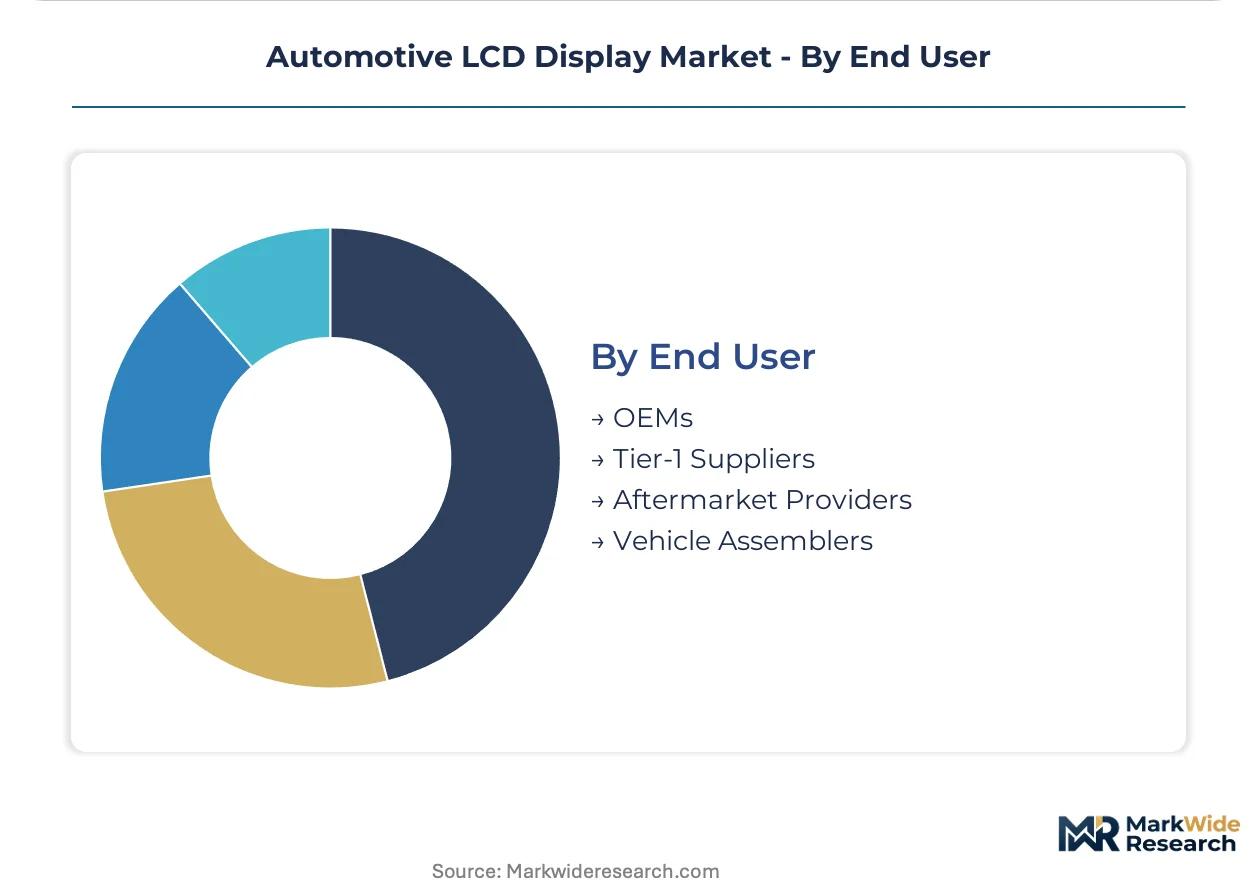
End User:
Supply chain position determines specification authority, volume aggregation potential, and technical integration responsibility.
- Tier-1 Suppliers:Denso Corporation, Continental AG, and similar systems integrators consolidate display procurement from panel manufacturers, adding touch controllers, cover lenses, and thermal management. These intermediaries manage REACH indium disclosure compliance and EPA VOC qualification for OEM-directed programs.
- OEMs:Volkswagen Group, BYD, and premium German manufacturers increasingly specify direct panel procurement for flagship platforms, bypassing tier-1 markup while capturing design differentiation.
- Vehicle Assemblers:Contract manufacturers in emerging EV ecosystems integrate standardized display modules without original specification authority.
- Aftermarket Providers:Independent distributors serve collision repair and upgrade segments with reverse-engineered compatibility layers.
Tier-1 Suppliers channel majority volume. OEM direct procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive LCD display manufacturing originated in Japanese electronics corridors during the 1980s before Korean and Taiwanese fabricators scaled TFT LCD capacity through the 1990s. German precision engineering clusters later specialized in instrument cluster integration. Chinese panel makers now dominate volume production for electric vehicle platforms.
Japan
Domestic OEMs source instrument cluster panels from established tier-1 supply relationships with Japanese display specialists. METI's carbon neutrality roadmap for manufacturing sectors drives float glass producers toward renewable energy sourcing. The Chubu region around Nagoya hosts concentrated module assembly operations serving Toyota and Honda flagship platforms.
South Korea
Hyundai Motor Group and Kia Corporation specify advanced active-matrix configurations for head-up display modules across Genesis luxury lineups. The Ministry of Trade, Industry and Energy enforces K-REACH substance disclosure requirements parallel to European standards. Samsung Display Co., Ltd. anchors driver IC development in Gyeonggi Province for HUD-specific ASIC production.
Germany
Volkswagen Group, BMW AG, and Mercedes-Benz Group AG mandate EU Green Deal-compliant recyclable backlight units for domestic EV production. The KBA enforces type-approval standards for display luminance in driver information systems. Bavaria's Munich-Stuttgart corridor concentrates systems integration facilities where Continental AG and Denso Corporation operate module finishing lines.
China
BYD, NIO, and Xpeng expand cockpit display specifications as standard equipment across mid-tier EV platforms. MIIT's dual carbon goals pressure panel makers toward low-carbon glass substrate certification. The Yangtze River Delta around Shanghai and Suzhou hosts BOE Technology Group Co., Ltd. and Tianma Microelectronics Co., Ltd. high-volume TFT LCD fabs supplying domestic OEM instrument clusters.
United States
Detroit Three automakers procure standardized 10.25-inch and 12.3-inch formats for fleet and retail vehicle programs. The EPA enforces volatile organic compound limits on display adhesive and coating processes affecting module assembly lines. Michigan and Ohio host tier-1 supplier finishing operations adapting to controlled-atmosphere facility requirements under NHTSA distraction-mitigation guidelines.
Automotive LCD Display Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and automotive-grade certification depth. Japanese and South Korean incumbents defend instrument cluster share through decades of reliability track records. Three archetypes dominate: integrated panel-module specialists, pure-play display fabricators, and diversified electronics conglomerates with captive automotive divisions. Competitive moves concentrate on capacity expansion for EV-specific formats and strategic partnerships for head-up display ASIC co-development.
Among Japanese specialists, Japan Display Inc. and Sharp Corporation occupy positions within the instrument cluster reliability tier. LG Display Co., Ltd. and Samsung Display Co., Ltd. exemplify the Korean active-matrix technology leadership archetype for premium infotainment and HUD applications. BOE Technology Group Co., Ltd. anchors the Chinese high-volume fabrication segment serving domestic EV OEM procurement.
| Leading Market Players |
|---|
| Japan Display Inc. |
| Innolux Corporation |
| LG Display Co., Ltd. |
| Tianma Microelectronics Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| Sharp Corporation |
| AU Optronics Corporation |
| Truly International Holdings Limited |
| Samsung Display Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Indium spot pricing volatility cascades through automotive display manufacturing, compressing margins on ITO electrode-intensive TFT LCD panels while amplifying cost advantages for suppliers with captive indium sourcing or alternative transparent conductive oxide development programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade certified panels from commercial-grade alternatives and aftermarket replacements. Price differentiation rests on NHTSA distraction-mitigation certification tier and glass substrate carbon-footprint labeling. Cost compression in standard-tier instrument cluster modules is intensifying because Chinese OEMs aggregate fleet procurement around common 10.25-inch and 12.3-inch formats. Fleet aggregators exhibit highest price sensitivity, while German premium EV platforms remain least sensitive due to design differentiation mandates.
Supply Chain Analysis
Workforce availability constraints in South Korea's Gyeonggi Province and Japan's Chubu region are tightening specialized active-matrix driver IC production capacity for head-up display modules. Geographic supply concentrates in China, South Korea, and Japan, with BOE Technology Group Co., Ltd. and Samsung Display Co., Ltd. anchoring high-volume fabrication. Raw material dependencies center on refined indium from Chinese smelters, polarizing films from Japanese chemical specialists, and float glass from energy-intensive European and Asian producers. Single-source vulnerability around indium supply creates structural risk exposure. Distribution runs through tier-1 systems integrators who consolidate panel procurement with touch controller and thermal management integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive LCD display demand compounds steadily as electric vehicle cockpit digitization becomes non-negotiable equipment across mid-tier platforms, with EU Green Deal circularity mandates ensuring sustained replacement and upgrade cycles.
For Market Incumbents: Deploy modular optical film stack redesign to capture EU Green Deal eco-design premium positioning before compliance deadlines force reactive adaptation. Defend instrument cluster share by accelerating reliability certification databases that emerging OLED suppliers cannot replicate. Threaten margin compression from Chinese panel makers with scale advantages in standardized formats. Leverage captive indium sourcing or alternative transparent conductive oxide partnerships as cost insulation. For New Entrants and Emerging Players: Capture rear-seat entertainment Mini LED white space where localized dimming commands experience premiums and incumbent certification track records matter less than cinematic performance specifications. Target luxury MPV and flagship SUV segments in South Korea and Germany where content-streaming partnerships justify hardware premiums. Penetrate through ASIC co-development partnerships with HUD module specialists seeking to compress 18-24 month development cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-1 systems integrators possessing REACH indium disclosure compliance infrastructure and EPA VOC qualification capabilities that pure-play panel fabricators lack. Long-term viability favors consolidators who can bridge premium infotainment OLED growth with instrument cluster TFT LCD stability. Watch for MIIT dual carbon goal acceleration as inflection signal for low-carbon glass substrate certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Backlight Unit Design | EU Green Deal eco-design criteria reward modular optical film stacks that separate cleanly at end-of-life for material recovery. |
| Active-Matrix Driver ASIC Co-Development | Samsung Display Co., Ltd. leverages Gyeonggi Province engineering clusters to compress HUD module development cycles. |
| Low-Carbon Glass Substrate Certification | German OEM sustainability scorecards differentiate float glass producers with renewable energy sourcing. |
| Alternative Transparent Conductive Oxide R&D | REACH indium disclosure requirements accelerate substitution research away from Chinese smelter concentration. |
| Rear-Seat Entertainment Content Partnerships | Luxury MPV and flagship SUV platforms justify Mini LED hardware premiums through subscription-enabled service ecosystems. |
Study Parameters
Coverage spans Japan, South Korea, Germany, China, and the United States, with primary inputs from each regional manufacturing cluster combining structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists alongside secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed panel manufacturers, and customs records of display component trade flows. Bottom-up unit shipment modeling triangulates against top-down value estimates derived from procurement contract analysis.
Granularity-level modeling addresses product type, application, technology, and end user dimensions across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster categories. CAGRs derive from curve-fitting historical shipment trajectories against announced capacity expansion timelines and OEM platform launch schedules. Forecast inputs incorporate REACH substance restriction evolution, NHTSA distraction-mitigation guideline advancement, and MIIT dual carbon goal implementation pacing.
Indium supply disruption, EPA VOC enforcement escalation, and NHTSA field-of-view parameter tightening are the dominant revision risks that could compress or extend the analysis window. Forecasts reflect assumptions around regulatory implementation timelines and OEM platform standardization rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Field Emission Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Flexible Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Display Control and Management System Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
LCD Panel Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Interactive Display Market
Display Technologies
Global Wearable Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Global Display Controllers Market
Display Technologies
Foldable Screens Market