
 Smart Privacy Glass Market | 2026-2036
Smart Privacy Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Privacy Glass Market Insights
Electrochromic thin-film deposition is narrowing the cost gap between conventional glazing and active privacy systems. Saint-Gobain leverages captive float-glass capacity to control substrate supply from European plants. Gentex Corporation anchors its position through automotive-qualified SPD supply chains. Research Frontiers competes via licensed nanoparticle dispersion technology rather than captive manufacturing.
Smart privacy glass modulates visible light transmission through electrically responsive interlayers, typically achieving switching speeds under three seconds and haze levels below five percent in clear state. Electrochromic and suspended particle device architectures dominate commercial office installations where daylight harvesting credits offset first-cost premiums. Liquid crystal technology leads automotive sunroof applications due to its instant opacity transition and proven durability under SAE J1885 thermal cycling protocols.
Building codes in Germany reference EnEV thermal transmittance thresholds that effectively mandate dynamic glazing in new commercial construction. The U.S. Department of Energy certifies electrochromic products through its Windows program, creating a procurement filter for federal retrofit contracts. Japan's METI sets performance benchmarks for net-zero building envelopes that smart glass satisfies. Stakeholders must track how ceramic thermochromic formulations evolve against liquid crystal incumbent positions in next-generation residential specifications.
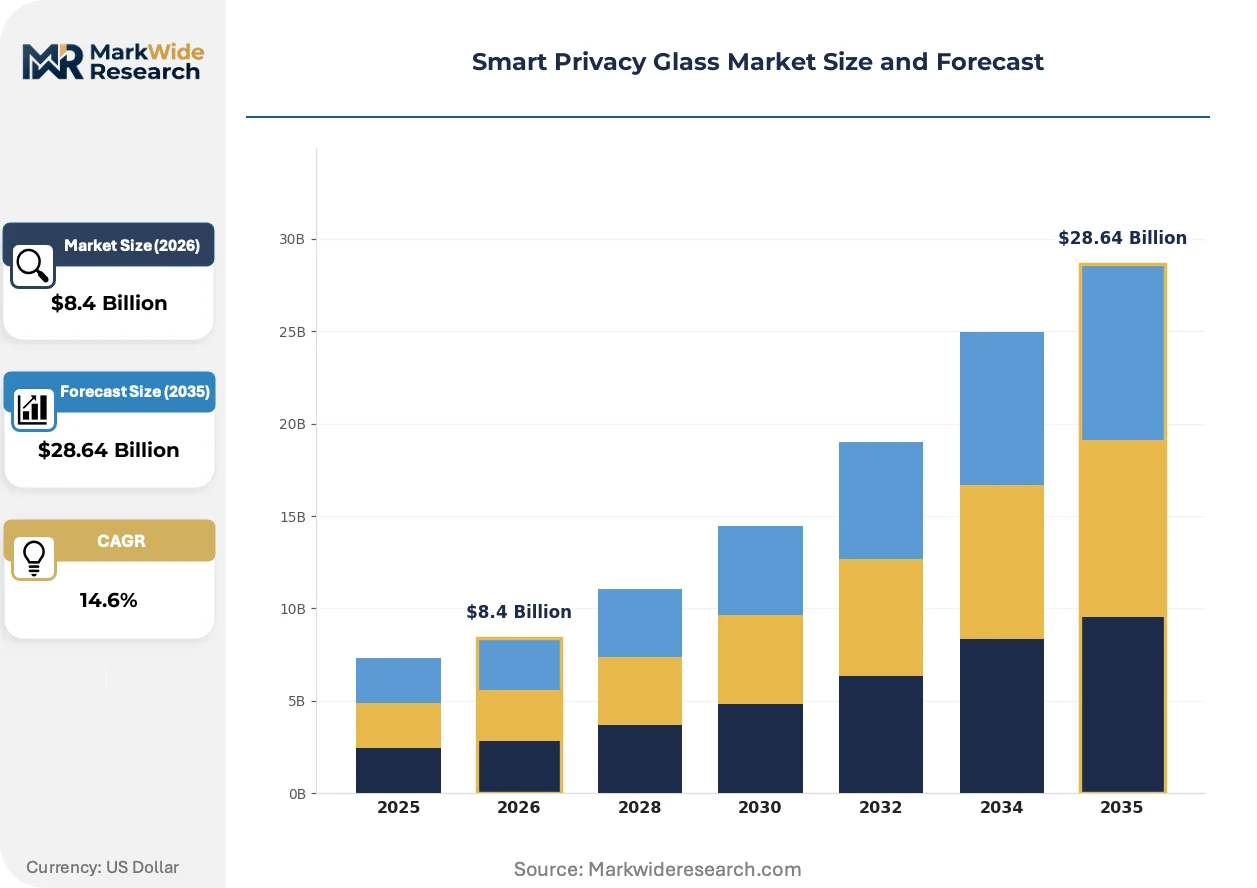
Market Dynamics
Electrochromic thin-film deposition is collapsing the cost premium between passive glazing and active privacy systems, while Germany's EnEV thermal codes and Japan's METI net-zero mandates accelerate specification velocity in commercial construction cycles.
Growth Catalysts
- EU Green Deal building codes:Tightening glazing performance standards across European member states mandate dynamic envelope solutions in new commercial construction and major retrofits.
- Automotive SPD qualification pathways:SAE J1885 thermal cycling protocols validate durability for sunroof applications, opening OEM specification channels previously closed to active glazing.
- Daylight harvesting credits:LEED and BREEAM certification schemes offset first-cost premiums through operational energy savings recognition in corporate office portfolios.
Market Restraints
- Indium tin oxide supply concentration:Sputtering target production clusters in East Asian refiners create input cost volatility and geopolitical exposure for electrochromic stack manufacturers.
- Float-glass substrate dependency:Captive flat-glass capacity at European and North American integrated producers limits independent module assemblers to spot market purchases.
- Liquid crystal haze floor:Polymer-dispersed architectures cannot achieve sub-three-percent haze in clear state, disqualifying applications requiring pristine optical clarity.
Strategic Opportunities
- Residential net-zero retrofits:Germany's KfW funding programs and similar instruments in Austria and Switzerland subsidize smart envelope upgrades in single-family housing stock.
- Healthcare privacy partitions:Hospital-acquired infection protocols favor non-porous, electronically sanitized privacy barriers over fabric curtains in patient room design.
- Ceramic thermochromic convergence:Vanadium dioxide phase-change coatings integrated with low-emissivity substrates enable passive thermal response without electrical infrastructure.
Industry Challenges
- Thin-film process engineering talent:Vacuum deposition and roll-to-roll coating expertise concentrates in semiconductor and display industries, creating recruitment competition for glass substrate specialists.
- Electrochromic stack certification timelines:NFRC and PHIUS performance validation protocols require 12-18 month testing cycles, compressing product development windows relative to software-driven building systems.
- Legacy curtain wall integration:Field-applied retrofits demand structural load analysis and gasket redesign that general glazing contractors lack training to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Privacy Glass Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Dispersed, Suspended Particle Device, Electrochromic, Micro-Blinds Technology: Liquid Crystal, Ceramic, Thermochromic, Photochromic, Fullerene-Based Application: Office Partitions, Conference Rooms, Privacy Screens, Automotive Sunroofs, Residential Windows End User: Commercial Offices, Corporate Entities, Vehicle Manufacturers, Residential Property Developers |
| Companies Covered | Gauzy Ltd, Saint-Gobain, View Inc, AGC Inc, Gentex Corporation, Corning Incorporated, Nippon Sheet Glass Co Ltd, Research Frontiers, Intelligent Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Privacy Glass Market Trends and Innovations
Active modulation technologies are compressing the performance gap between static solar control and responsive privacy systems, with deposition advances and code harmonization driving specification convergence across automotive and built environment applications.
Sputtered tungsten oxide electrochromic stacks are collapsing the switching speed differential with liquid crystal alternatives while maintaining superior solar heat gain coefficient modulation. Corporate real estate managers in Germany and Japan specify these systems for facade zones where both glare control and thermal load management matter. The technology is collapsing the historical trade-off between optical performance and energy responsiveness that forced architects to choose between competing priorities.
Japan's METI net-zero building envelope benchmarks now explicitly reference dynamic glazing U-value and g-value performance thresholds that static low-e coatings cannot satisfy. Japanese general contractors face procurement pressure to source certified electrochromic modules for government and institutional tenders. The regulation is compressing supplier qualification timelines and favoring domestic-integrated manufacturers with established testing relationships.
Facility management procurement teams now bundle smart glass specification with performance contracting arrangements that tie contractor payment to verified energy savings outcomes. Real estate investment trusts in the United States and United Kingdom pilot these structures for portfolio-wide retrofits, displacing traditional capital expenditure models. This shift concentrates buyer power among large asset managers and marginalizes smaller regional glazing distributors lacking energy modeling capabilities.
Smart Privacy Glass Market Segmentation
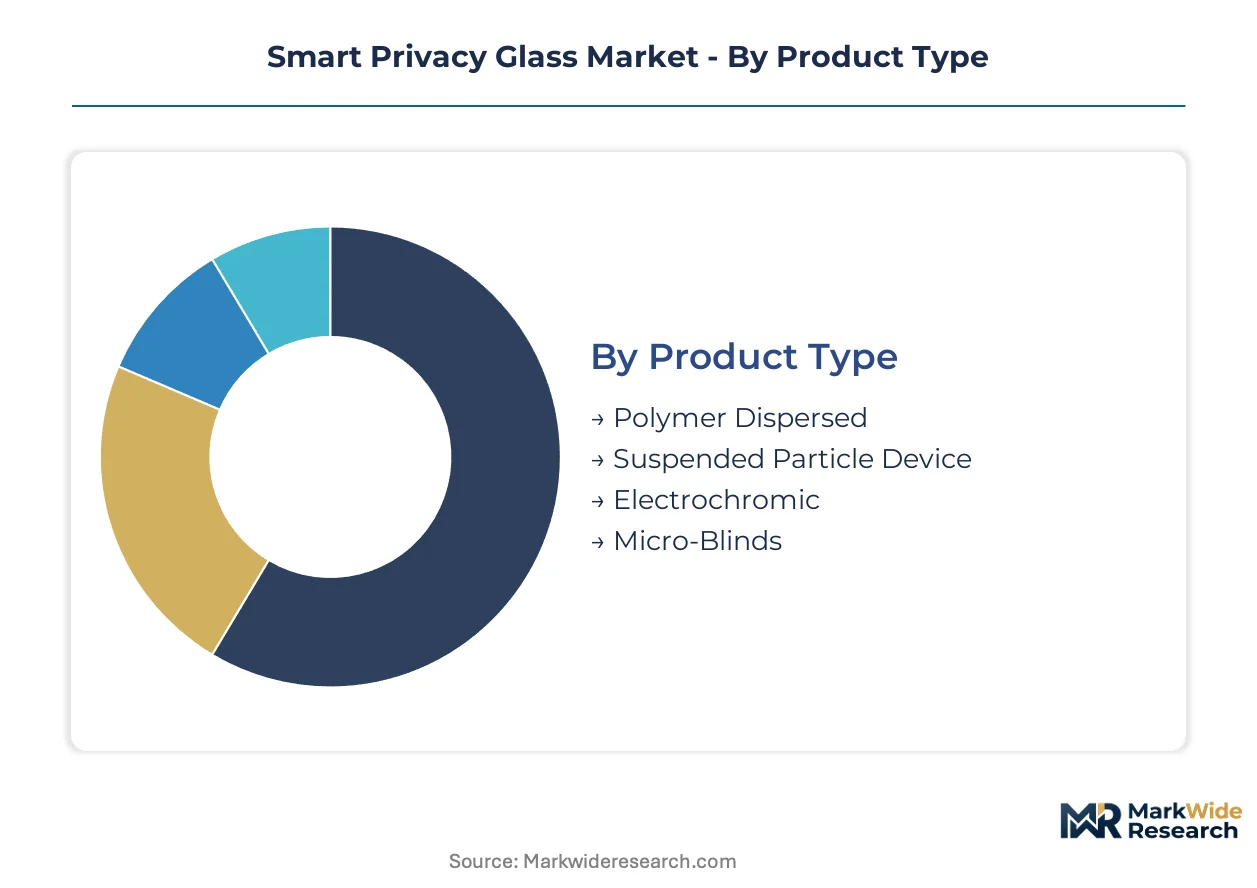
Technology heterogeneity in smart privacy glass creates distinct value propositions across switching speed, optical clarity, and energy responsiveness. Architects and procurement teams select architectures based on specific performance thresholds rather than universal superiority. Understanding segment boundaries clarifies where electrochromic deposition advances displace incumbent alternatives.
Product Type:
Cost tier differentiation separates mature liquid-crystal derivatives from emerging thin-film architectures with premium positioning.
- Polymer Dispersed:Liquid crystal droplets suspended in polymer matrices switch opacity via electric field orientation. Corporate office partitions in Germany specify these systems for instant privacy transitions where haze tolerance exceeds five percent.
- Suspended Particle Device:Nanoparticle dispersions align under voltage to modulate light transmission. Automotive sunroof demand concentrates with vehicle manufacturers seeking SAE J1885-validated durability under thermal cycling stress.
- Electrochromic:Tungsten oxide thin-film stacks enable gradual tint adjustment with superior solar heat gain control.
- Micro-Blinds:MEMS-actuated metallic louvers provide mechanical opacity switching without organic degradation risks.
Polymer Dispersed commands the established base. The steepest expansion runs through Electrochromic.
Technology:
Application context determines whether electrical responsiveness or passive thermal reaction delivers optimal lifecycle economics.
- Liquid Crystal:Field-induced molecular reorientation achieves sub-second switching speeds unmatched by ionic migration alternatives. Automotive sunroof specifications favor this maturity for passenger compartment glare control where instant response overrides energy modulation depth.
- Ceramic:Vanadium dioxide phase-change coatings integrate with low-emissivity substrates for passive thermal response. Japan's METI net-zero envelope benchmarks drive specification in institutional facades lacking electrical infrastructure for active systems.
- Thermochromic:Temperature-dependent optical transitions eliminate wiring complexity in residential retrofits.
- Photochromic:UV-triggered darkening suits exterior applications with direct solar exposure.
- Fullerene-Based:Carbon allotrope dispersions enable novel electro-optic responses in experimental architectural installations.
Liquid Crystal retains volume leadership in automotive channels. Ceramic formulations are climbing the fastest in commercial envelope specifications.
Application:
Volume concentration varies sharply between new construction integration and retrofit attachment opportunities.
- Office Partitions:Modular panel systems incorporate switchable interlayers for flexible space reconfiguration. Corporate entities in the United States specify these for open-plan to private-office conversions without structural modification.
- Conference Rooms:Full-height glazing with privacy-on-demand addresses visual confidentiality requirements. Germany's EnEV thermal codes mandate dynamic glazing in new commercial construction, compressing specification timelines for integrated envelope solutions.
- Privacy Screens:Healthcare patient room barriers replace fabric curtains with sanitizable electronic surfaces.
- Automotive Sunroofs:OEM qualification pathways validate durability under extreme thermal and vibrational loading.
- Residential Windows:Single-family net-zero retrofits in Austria and Switzerland access KfW-style subsidy programs for envelope upgrades.
Office Partitions command the established base. The steepest expansion runs through Privacy Screens.
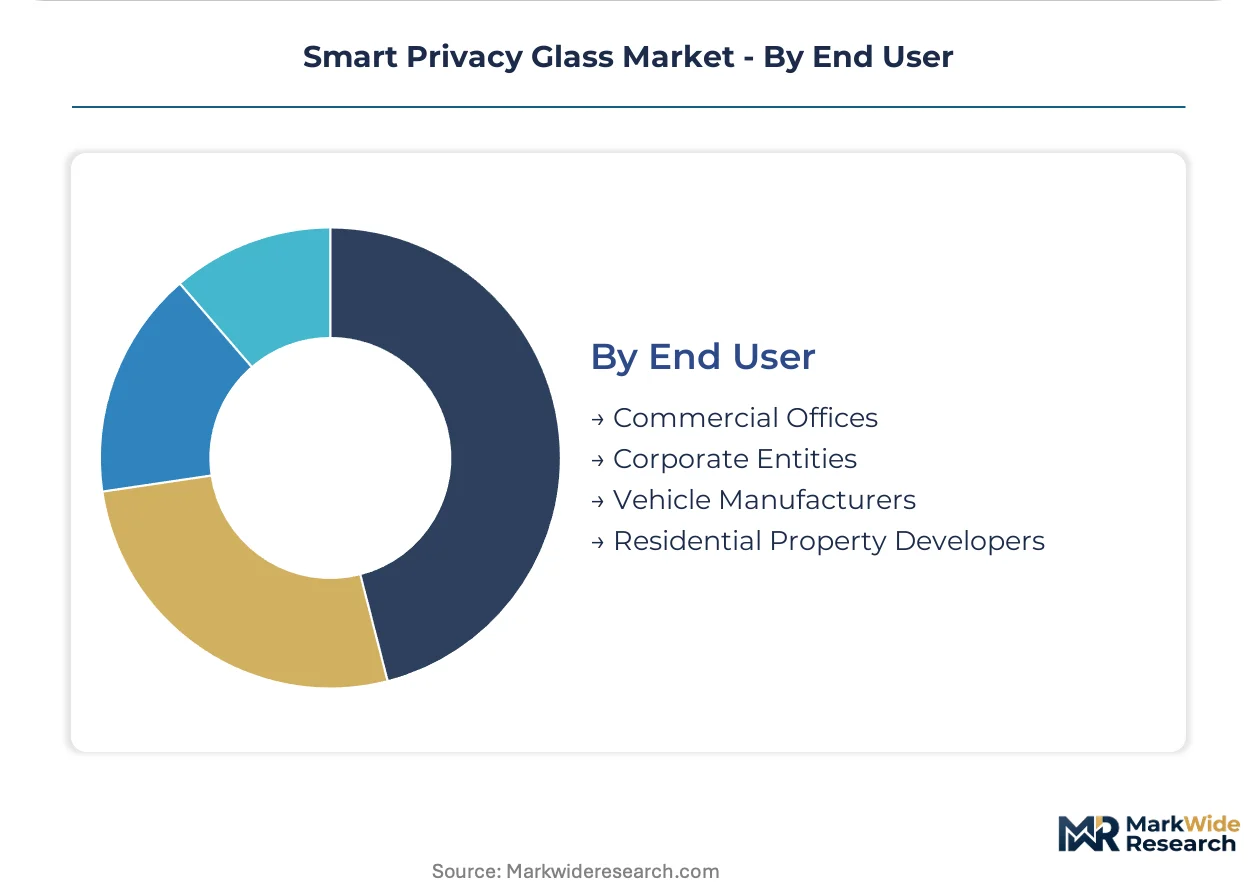
End User:
Customer type dictates procurement sophistication, with performance contracting displacing capital expenditure models among sophisticated buyers.
- Commercial Offices:Real estate investment trusts bundle smart glass with energy savings guarantees. United Kingdom portfolio managers pilot outcome-based contractor payment structures that shift risk from capital budgets to operational performance.
- Corporate Entities:Headquarters construction mandates LEED and BREEAM certification schemes that credit daylight harvesting. First-cost premiums offset through operational savings recognition in sustainability reporting.
- Vehicle Manufacturers:SPD qualification through SAE protocols opens specification channels previously closed to active glazing.
- Residential Property Developers:Premium positioning targets luxury single-family and high-rise segments where buyer education costs remain prohibitive for mass market penetration.
Commercial Offices command the established base. The steepest expansion runs through Corporate Entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate managers and automotive procurement teams concentrate specification authority in Germany, the United States, and Japan, where building energy codes and OEM qualification pathways create aligned demand cycles for active glazing systems.
Germany
Corporate headquarters construction and KfW-funded residential retrofits drive volume demand for electrochromic facade systems. The EnEV thermal transmittance thresholds mandate dynamic glazing in new commercial builds, compressing specification timelines for integrated envelope solutions. The Rhine-Ruhr industrial corridor hosts float-glass substrate producers supplying module assemblers across Central Europe.
United States
Federal building retrofits and LEED-certified corporate portfolios anchor demand for daylight harvesting installations. The Department of Energy's Windows program certifies electrochromic products, creating a procurement filter for government contracts. California's Title 24 building standards accelerate adoption in commercial construction across the San Francisco Bay Area and Los Angeles Basin.
Japan
Net-zero institutional construction and automotive sunroof integration sustain dual demand channels for switchable glazing technologies. METI's building envelope benchmarks explicitly reference dynamic glazing performance thresholds unattainable by static coatings. The Nagoya industrial cluster concentrates automotive glass fabrication serving Toyota and Honda supply chains.
United Kingdom
Real estate investment trusts pilot performance-contracting models for portfolio-wide smart glass retrofits. BREEAM certification schemes credit daylight harvesting, offsetting first-cost premiums in London commercial developments. The Midlands manufacturing belt hosts specialized coating equipment suppliers serving European module assemblers.
South Korea
Hyundai and Kia OEM specifications for premium vehicle sunroofs validate SPD durability under regional thermal cycling conditions. The national building energy code revisions favor dynamic envelope solutions in new commercial construction. The Seoul Capital Area concentrates architectural glass fabrication and systems integration expertise.
Smart Privacy Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated glass manufacturers with captive float-glass capacity, licensed technology platforms monetizing through royalty structures, and independent module assemblers sourcing substrates from spot markets. Consolidation pressure concentrates among substrate-integrated producers while fragmentation persists at the assembly tier. Dominant competitive moves include strategic partnerships for thin-film deposition expertise and geographic expansion into code-mandated construction markets.
Among substrate-integrated manufacturers, Saint-Gobain exemplifies the captive-supply archetype through European float-glass capacity, while Gentex Corporation anchors automotive-qualified positioning through SPD supply chain validation. Research Frontiers occupies a licensing-specialist position, monetizing nanoparticle dispersion technology without captive manufacturing infrastructure.
| Leading Market Players |
|---|
| Gauzy Ltd |
| Saint-Gobain |
| View Inc |
| AGC Inc |
| Gentex Corporation |
| Corning Incorporated |
| Nippon Sheet Glass Co Ltd |
| Research Frontiers |
| Intelligent Glass |
| Others |
Pricing and Supply Chain Analysis
Float-glass undercapacity in Europe is compressing module assembler margins while elevating substrate pricing power for integrated producers with captive melting capacity. This utilization asymmetry forces independent electrochromic stack manufacturers toward long-term offtake commitments or spot market exposure.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate electrochromic stack procurement between module assemblers and float-glass substrate suppliers. Pricing stratifies across premium, standard, and economy tiers based on NFRC certification tier and volume scale, with SAE J1885-validated SPD commanding brand premiums for automotive channels. Cost compression in standard-grade liquid crystal partitions is intensifying because polymer-dispersed manufacturing scales faster than quality-controlled thin-film deposition. Corporate real estate investment trusts exhibit lowest price sensitivity due to energy savings guarantee structures, while residential property developers in subsidized retrofit programs face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for electrochromic thin-film sputtering concentrates with German and Japanese vacuum deposition specialists serving Saint-Gobain and AGC module lines. Indium tin oxide sputtering targets draw from East Asian refiners, tungsten oxide precursor chemicals feed from Chinese specialty chemical producers, and float-glass substrates rest on European and North American integrated melting capacity. Single-source vulnerability around indium concentrates creates tariff exposure and geopolitical risk for electrochromic stack assemblers lacking diversified precursor supply. Distribution runs through facade systems integrators and automotive Tier 1 glazing suppliers rather than direct OEM or developer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
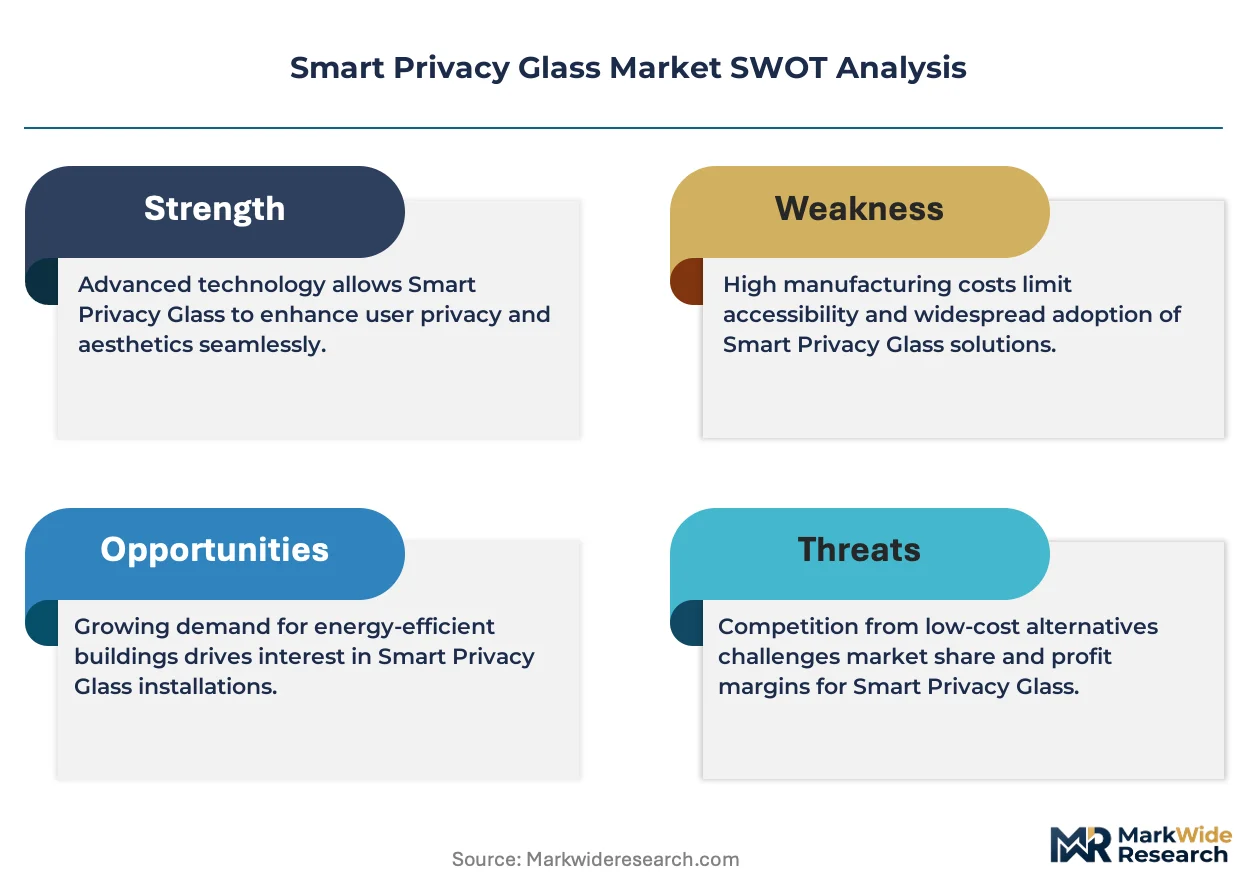
Analyst Recommendations
Vacuum deposition expertise scarcity constrains electrochromic stack expansion, with thin-film process engineering talent competing against semiconductor and display industry recruitment. This capability gap shapes competitive positioning for substrate-integrated incumbents versus independent assemblers.
For Market Incumbents: Build captive float-glass capacity moats through backward integration into European melting assets or long-term offtake structures with Rhine-Ruhr substrate producers. Certify electrochromic stacks through NFRC and PHIUS protocols ahead of code harmonization cycles to lock out independent assemblers lacking testing relationships. Defend against ceramic thermochromic substitutes by accelerating switching speed convergence with liquid crystal alternatives. For New Entrants and Emerging Players: Pursue healthcare privacy screen applications where hospital-acquired infection protocols drive specification away from fabric curtains toward sanitizable electronic barriers. Target German KfW-subsidized residential retrofits as the most penetrable geography, leveraging existing window installation contractor networks rather than facade systems integrators. Deploy performance contracting go-to-market models that shift buyer risk from capital expenditure to verified energy outcomes. For Investors and Strategic Acquirers: Capital is best deployed toward thin-film deposition specialists with established automotive or architectural qualification relationships rather than liquid crystal incumbents facing haze-floor limitations. Long-term viability across the projection horizon favors substrate-integrated manufacturers with captive supply control over independent assemblers exposed to float-glass spot volatility. Monitor ceramic thermochromic U-value performance benchmarks against electrochromic active systems as the critical inflection signal for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Deposition Partnership | Access to German vacuum coating expertise accelerates electrochromic stack qualification timelines. |
| Automotive SPD Qualification | SAE J1885 validation opens OEM sunroof specification channels at Hyundai and Kia. |
| Healthcare Privacy Screen Certification | Hospital infection control protocols favor non-porous electronic barriers over fabric curtains. |
| Residential Retrofit Subsidy Alignment | German KfW funding programs reduce customer acquisition costs for single-family envelope upgrades. |
| Performance Contracting Model | United Kingdom real estate investment trusts pilot outcome-based payment structures displacing traditional capex. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facade systems integrators, automotive Tier 1 glazing procurement managers, electrochromic thin-film deposition engineers, hospital facilities directors, and real estate investment trust sustainability officers. Secondary validation drew from Department of Energy Windows program certifications, METI net-zero building envelope benchmarks, EnEV thermal transmittance compliance databases, SAE J1885 test protocols, and SEC filings of substrate-integrated manufacturers. Bottom-up volume estimates triangulated against top-down construction spending and automotive production forecasts.
Calibration against historical electrochromic adoption curves in German commercial construction and SPD penetration in Japanese automotive sunroofs anchored growth assumptions across the analysis window. Segmentation modeling spanned technology architecture, application context, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted diffusion curves incorporating code mandate effective dates and retrofit cycle timing. Industry-specific inputs included float-glass capacity utilization rates, indium price volatility indices, and certification timeline distributions.
Sensitivities concentrate around indium supply disruption, ceramic thermochromic performance breakthroughs, and building code enforcement variance across German federal states. Forecasts embed assumptions regarding subsidy program continuity and automotive OEM qualification pathway stability. Quarterly review of NFRC certification queue lengths, METI benchmark revisions, and KfW funding authorization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Vietnam Displays Market
Display Technologies
Wireless Display Market
Display Technologies
Digital Holographic Display Market
Display Technologies
PMOLED Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Projector Screen Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Gaming Monitors Market
Display Technologies
Laptop Panels Market
Display Technologies
Touch Screen Module Market
Display Technologies
Industrial Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Europe Microdisplay Market