
 Interactive Video Wall Market | 2026-2036
Interactive Video Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Video Wall Market Intelligence
Project finance and operating lease structures for large-format display deployments is narrowing the competitive field to vendors with balance-sheet capacity or captive financing arms. Samsung Electronics leverages its captive semiconductor supply to control panel costs and lock in multi-year enterprise contracts. LG Electronics sustains aggressive R&D spending on bezel-less LCD architectures that reduce visible seams in tiled configurations. Panasonic Corporation anchors its position through deep integration with audiovisual systems integrators across the Asia-Pacific theater.
An interactive video wall comprises multiple display panels—typically LED, LCD, or projection-based—arranged in tiled matrices with integrated touch-sensing layers and processing controllers that enable simultaneous multi-user input across surfaces exceeding 100 diagonal inches, serving primarily to deliver immersive information visualization in spaces where single displays prove dimensionally inadequate. LED video wall segments now capture the dominant share of new installations as pixel pitches below 1.2 millimeters enable close-viewing clarity previously reserved for LCD alternatives. Infrared touch technology leads in command and control center deployments where gloved operation and environmental durability outweigh the thinner profiles of capacitive alternatives, while retail display applications increasingly specify optical touch frameworks for their scalability across irregular surface geometries.
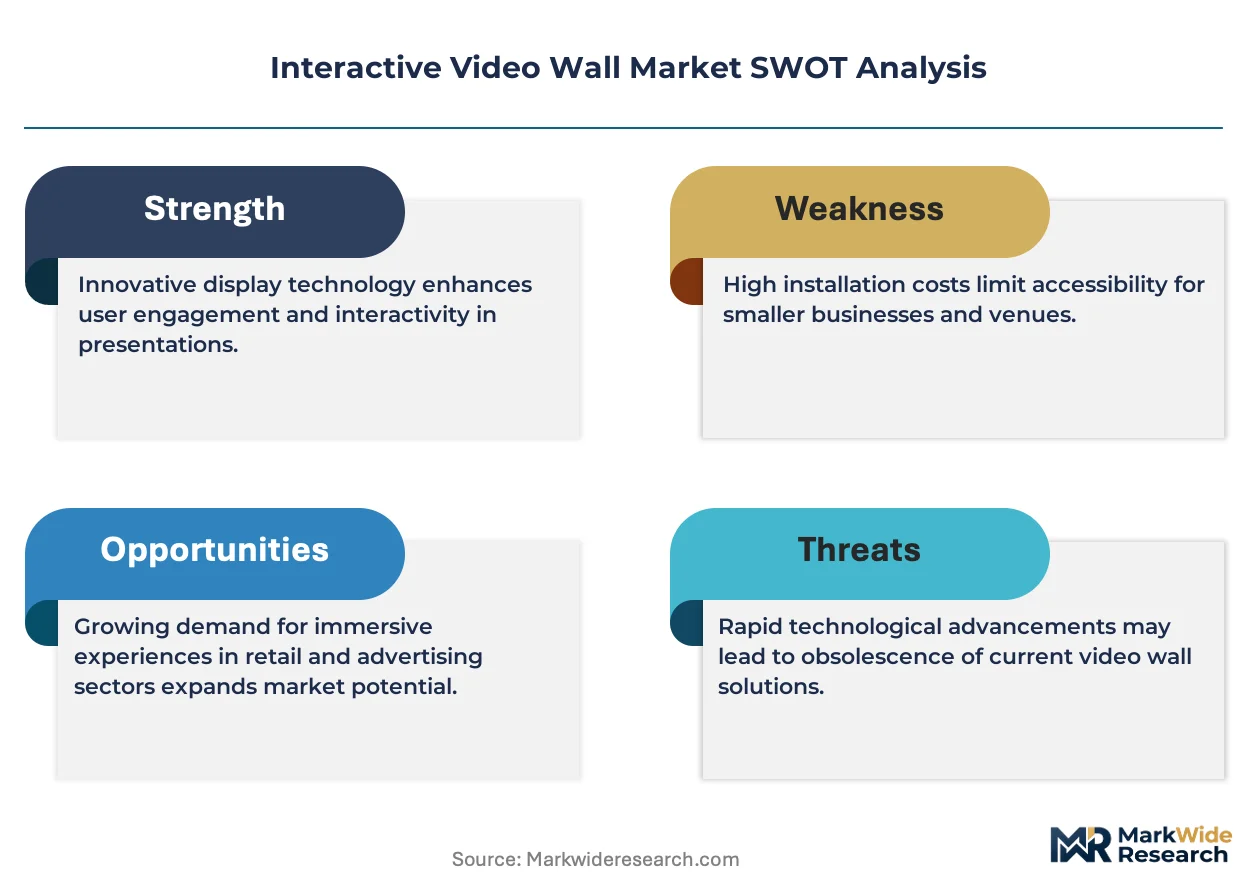
The Federal Communications Commission in the United States governs electromagnetic emissions from embedded controllers, while the EU's Restriction of Hazardous Substances Directive limits lead and cadmium in display assemblies, and China's Ministry of Industry and Information Technology enforces GB standards for energy efficiency in public information display equipment. These frameworks collectively elevate compliance costs for smaller panel assemblers while rewarding manufacturers with pre-certified platform architectures and in-house regulatory affairs teams. Stakeholders must monitor how emerging building energy codes in major metropolitan zones redefine permissible power density for permanently installed digital signage systems.
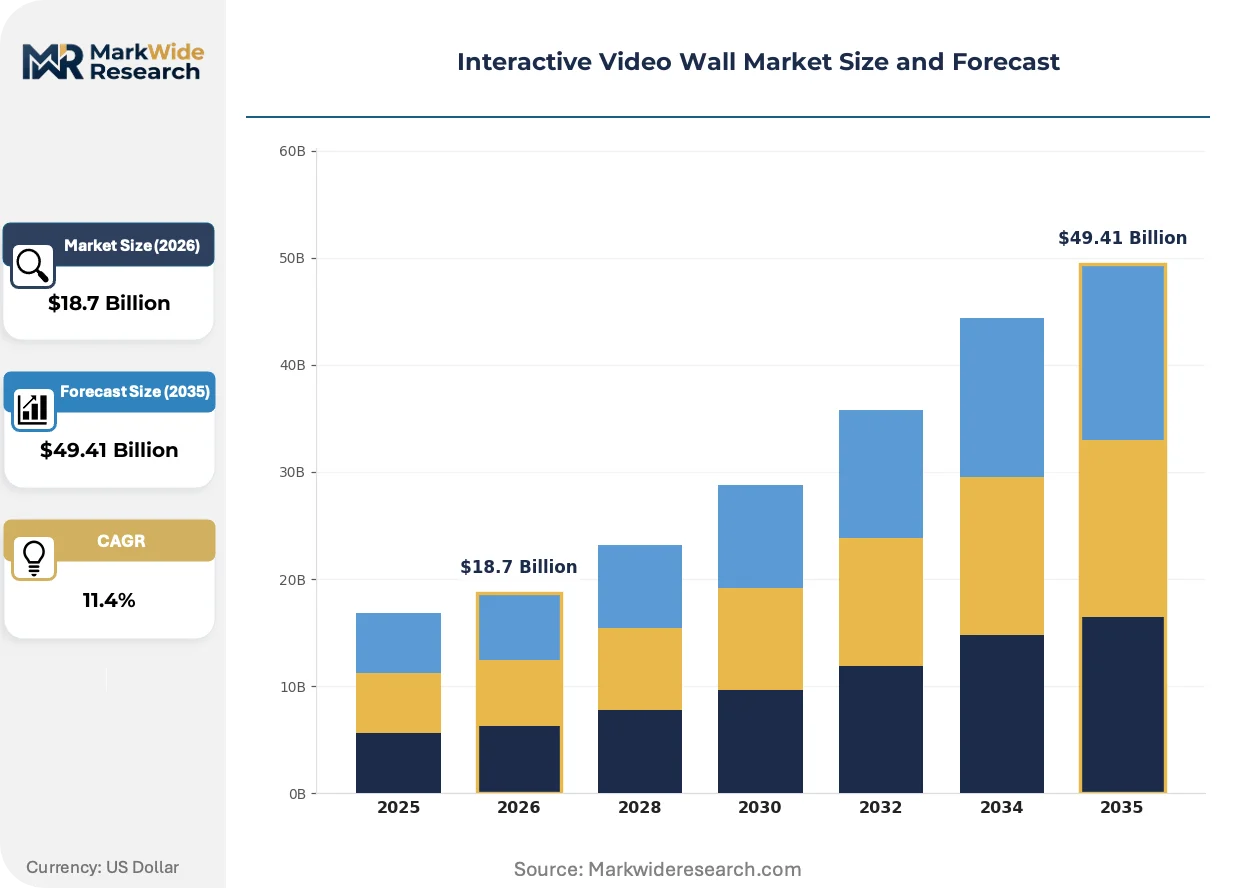
Market Dynamics
The EU Ecodesign for Energy-related Products Directive is compressing power budgets for large-format LED architectures, forcing manufacturers to redesign thermal management systems while Fortune 500 corporate communication teams accelerate real-time visualization deployments.
Growth Catalysts
- Industrial Automation Clusters:German automotive headquarters and manufacturing command centers are driving tiled LED installations for production monitoring and quality control visualization.
- RoHS Directive Compliance:Lead-free solder mandates across European display assemblies are accelerating migration to advanced chip-on-board packaging techniques.
- Pixel Pitch Compression:Sub-1.2 millimeter LED densities are enabling close-viewing clarity that displaces legacy LCD alternatives in premium meeting spaces.
Market Restraints
- Semiconductor Supply Concentration:Driver IC fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical disruption.
- Touch Layer Material Costs:Indium tin oxide price volatility inflates capacitive overlay budgets for irregular surface geometries.
- Projection Substitution:Laser phosphor projection systems retain cost advantages for temporary installations and rental staging applications.
Strategic Opportunities
- Hybrid Meeting Space Expansion:Corporate real estate teams in the United States are specifying bezel-less tiled configurations for immersive telepresence.
- Optical Touch Convergence:Camera-based sensing frameworks are scaling to curved and non-rectangular retail display surfaces previously inaccessible to infrared grids.
- GB Standard Alignment:China's Ministry of Industry and Information Technology efficiency certifications are opening public information display tenders to pre-qualified foreign suppliers.
Industry Challenges
- Systems Integration Talent Scarcity:Audiovisual integrators face shortages of technicians certified for multi-panel calibration and edge-blending.
- Legacy Control Protocol Fragmentation:Incompatible proprietary controller APIs complicate unified management across mixed-vendor installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Video Wall Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Video Wall, LCD Video Wall, Projection Video Wall, Rear Projection Video Wall Technology: Infrared Touch, Capacitive Touch, Optical Touch, Ultrasonic Touch, Laser Touch Application: Command & Control Centers, Retail Displays, Education & Training, Corporate Communication, Entertainment Venues End User Industry: Government Agencies, Broadcast Studios, Museums & Galleries, Event Management Firms |
| Companies Covered | Samsung Electronics, LG Electronics, NEC Corporation, Barco, Panasonic Corporation, Delta Electronics, Planar Systems, Christie Digital Systems, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Video Wall Market Strategic Shifts & Innovations
Touch-sensing architectures and display substrates are converging toward unified surface computing platforms, while regulatory pressure on embodied carbon reshapes supply chain sourcing decisions.
MicroLED transfer printing is hybridizing direct-view emissive displays with flexible substrate compatibility. Automotive design studios in Stuttgart and Munich are piloting curved 200-inch visualization surfaces for digital clay modeling. The technology is hybridizing previously separate categories of fixed-installation LED and mobile OLED into a single specification continuum.
The EU Ecodesign Directive's 2023 tiered standby power limits are eliminating high-consumption display controller architectures from certified product lines. Manufacturers with captive semiconductor design capabilities are integrating power management ASICs to maintain compliance without sacrificing brightness output. German industrial automation buyers now require Ecodesign compliance documentation as a mandatory tender gate.
Enterprise procurement teams are unbundling installation and maintenance from hardware acquisition, creating separate competitive pools for capital equipment and service contracts. Systems integrators in the Asia-Pacific theater are responding with subscription-based managed service offerings. This pattern is most visible in Singapore and Sydney financial services headquarters, where three-year refresh cycles now dominate previously transactional purchasing.
Interactive Video Wall Market Segmentation
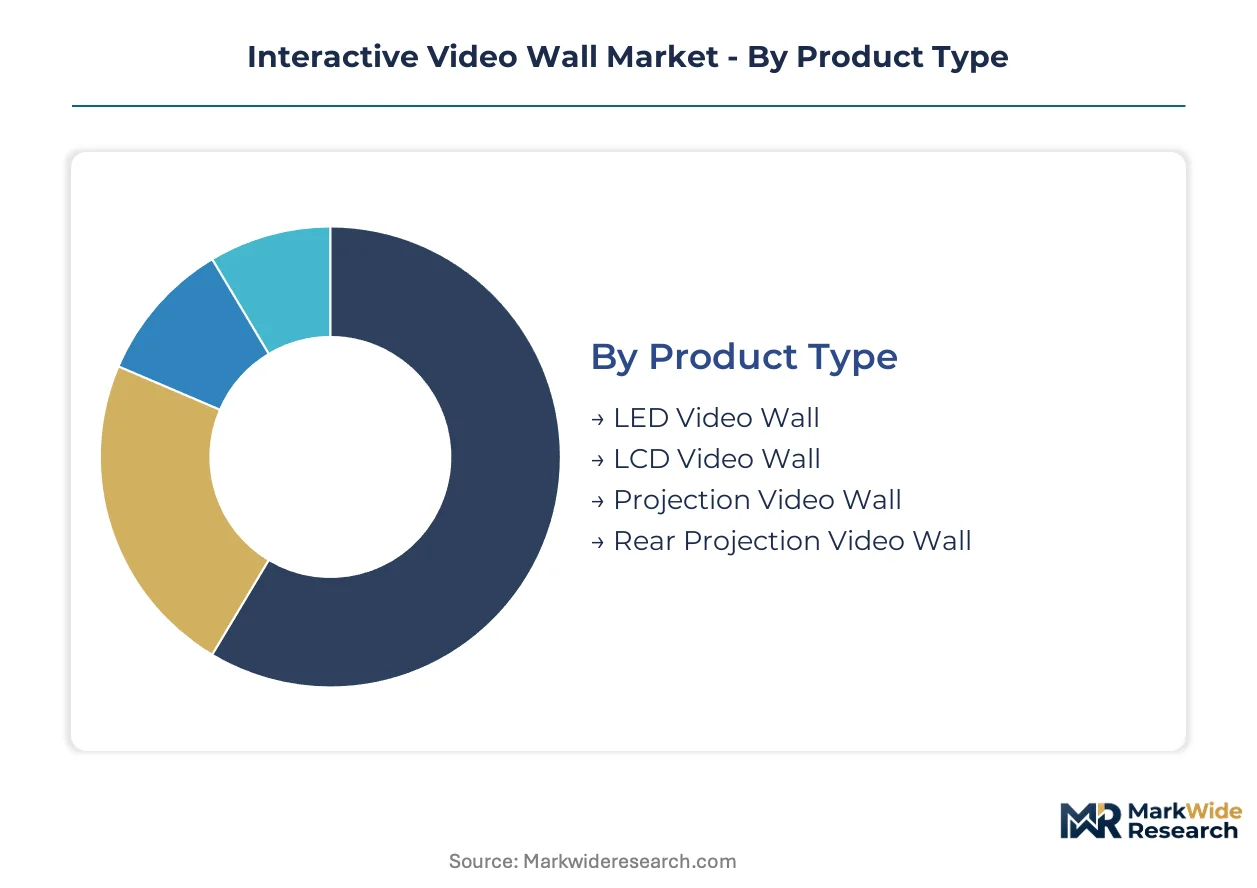
Technology heterogeneity across display substrates and touch-sensing layers creates distinct replacement cycles and margin profiles. Procurement teams segment investments by surface permanence, with command center LED installations running 7-10 year cycles against 18-24 month retail refresh schedules.
Product Type:
LED video walls command the longest replacement cycles due to modular repairability, while projection systems turn over fastest in temporary deployment scenarios.
- LED Video Wall:Direct-view emissive tiles with pixel pitches below 1.2 millimeters now enable close-viewing clarity. German automotive headquarters in Stuttgart and Munich specify these for permanent production monitoring installations where RoHS-compliant chip-on-board packaging satisfies tender gates.
- LCD Video Wall:Bezel-less tiled configurations with liquid crystal substrates and narrow mullions. Corporate real estate teams in the United States specify these for hybrid meeting spaces where budget constraints outweigh LED premium positioning.
- Projection Video Wall:Laser phosphor systems retain staging and rental advantages through lower capital outlay.
- Rear Projection Video Wall:DLP cube configurations persist in legacy command centers with existing infrastructure investments.
LED video walls anchor the volume base while projection systems gain share at the steepest rate in temporary installation segments.
Technology:
Touch layer architectures differentiate by environmental durability against surface geometry flexibility, with infrared and optical systems pulling toward opposite application poles.
- Infrared Touch:Grid-based sensing using interrupted light beams supports gloved operation and contamination resistance. Command and control center deployments across German industrial automation clusters specify these for 24/7 operational durability.
- Optical Touch:Camera-based frameworks triangulate touch points across irregular surfaces. Retail display applications in Singapore and Sydney financial services headquarters adopt these for curved and non-rectangular geometries.
- Capacitive Touch:Indium tin oxide layers enable multi-point responsiveness in controlled indoor environments.
- Ultrasonic Touch:Piezoelectric transducers detect surface acoustic wave interruptions for high-precision input.
- Laser Touch:Scanning laser triangulation creates touch-responsive surfaces without overlay films.
Infrared touch dominates replacement-resistant infrastructure while optical touch climbs the fastest in experiential retail segments.
Application:
End-use environments segment sharply by uptime requirements and content refresh velocity, with command centers prioritizing reliability over pixel density.
- Command & Control Centers:Mission-critical visualization for production monitoring and security operations. German automotive headquarters and manufacturing clusters drive specifications requiring Ecodesign compliance documentation as mandatory tender gates.
- Retail Displays:Customer-facing experiential surfaces with high content turnover. Three-year refresh cycles now dominate previously transactional purchasing in Singapore and Sydney financial services headquarters.
- Education & Training:Collaborative learning environments with multi-user input requirements.
- Corporate Communication:Hybrid meeting spaces and real-time data visualization for Fortune 500 real estate teams.
- Entertainment Venues:Immersive spectator experiences with irregular surface geometries.
Command and control centers anchor the volume base while retail displays gain share at the steepest rate in Asia-Pacific managed service contracts.
End User Industry:
Institutional procurement patterns separate by funding stability and integration complexity, with government tenders favoring pre-certified platform architectures.
- Government Agencies:Public information display installations subject to GB standard efficiency certifications in China and FCC electromagnetic emissions governance in the United States. Pre-certified foreign suppliers access tenders through regulatory affairs documentation.
- Broadcast Studios:Color-critical visualization requiring calibration stability and edge-blending precision.
- Museums & Galleries:Curved and irregular surface installations where optical touch scalability matters.
- Event Management Firms:Temporary staging applications where laser phosphor projection cost advantages persist.
Government agencies anchor the volume base while event management firms gain share at the steepest rate in rental and staging substitution patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Command center operators and corporate real estate teams concentrate procurement authority in four national markets where industrial automation, broadcast infrastructure, and hybrid workplace investment overlap.
United States
Fortune 500 corporate communication teams drive bezel-less tiled configurations for immersive telepresence in hybrid meeting spaces. The Federal Communications Commission governs electromagnetic emissions from embedded controllers, elevating compliance costs for smaller panel assemblers. New York Metro and Pacific Northwest technology headquarters anchor real-time data visualization deployments.
Germany
Automotive headquarters and industrial automation clusters in Stuttgart and Munich specify sub-1.2 millimeter LED densities for permanent production monitoring installations. The Ecodesign for Energy-related Products Directive mandates tiered standby power limits, eliminating high-consumption display controller architectures from certified product lines. Bavarian manufacturing command centers require Ecodesign compliance documentation as mandatory tender gates.
China
Public information display tenders open to pre-qualified foreign suppliers through GB standard efficiency certifications enforced by the Ministry of Industry and Information Technology. The MIIT's energy efficiency standards for public information display equipment reward manufacturers with pre-certified platform architectures. Yangtze River Delta and Pearl River Delta industrial zones concentrate panel assembly and driver IC fabrication capacity.
Japan
Broadcast studios and color-critical visualization applications demand calibration stability and edge-blending precision for studio production environments. METI oversees industrial standards coordination for display equipment efficiency and electromagnetic compatibility. Kanto and Kansai metropolitan areas anchor broadcast infrastructure investment and systems integrator networks.
Singapore
Financial services headquarters specify three-year refresh cycles for retail display applications through subscription-based managed service offerings. The city-state's building energy codes redefine permissible power density for permanently installed digital signage systems. Central business district financial institutions drive optical touch framework adoption for curved and non-rectangular surface geometries.
Interactive Video Wall Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement decisions unbundled across hardware acquisition and service contracts. The field narrows to vendors with balance-sheet capacity or captive financing arms as project finance and operating lease structures expand. Three archetypes dominate: diversified electronics conglomerates with semiconductor supply control, display-technology pure-plays with systems integrator partnerships, and regional specialists with managed service capabilities. Competitive moves concentrate on multi-year enterprise contract lock-ins and captive semiconductor supply integration.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify players leveraging captive semiconductor design to control panel costs and sustain aggressive R&D spending on bezel-less architectures. Panasonic Corporation occupies a position anchored through deep integration with audiovisual systems integrators across Asia-Pacific theater deployments. These three entities represent the scale-driven end where pre-certified platform architectures and in-house regulatory affairs teams create separation from smaller panel assemblers facing elevated compliance costs.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| NEC Corporation |
| Barco |
| Panasonic Corporation |
| Delta Electronics |
| Planar Systems |
| Christie Digital Systems |
| Daktronics |
| Others |
Cost & Logistics Intelligence
Driver IC fabrication concentrates in Taiwan and South Korea, anchoring margin pools in display controller architectures and captive semiconductor design capabilities among tier-one vendors.
Pricing Analysis
Certification level creates the primary spread, with Ecodesign-compliant LED architectures commanding premiums over non-certified alternatives in German industrial tenders. Three-tier pricing structure across premium, standard, and economy levels segments by pixel density, touch layer durability, and after-sales service bundling. Cost compression in capacitive overlay tiers is intensifying because indium tin oxide price volatility feeds directly into bill-of-materials pressure. Event management firms exhibit the highest price sensitivity, while command center operators prioritize total cost of ownership over acquisition outlay.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit driver IC fabrication capacity expansion outside Taiwan and South Korea. Panel assembly draws from LED die suppliers in China, driver IC foundries in Taiwan, and indium tin oxide substrate producers in Japan. Single-source vulnerability concentrates in 300-millimeter wafer supply for controller ASICs. Distribution runs through audiovisual systems integrators who bundle installation, calibration, and multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Fortune 500 corporate real estate teams and German automotive procurement departments, which are consolidating specification authority around Ecodesign compliance and captive financing requirements.
For Market Incumbents: Entrench position through backward integration into driver IC design and multi-year enterprise contract lock-ins with mandatory service bundling. Laser phosphor projection substitution threatens premium LED positioning in temporary installation segments. Priority levers include captive semiconductor supply and pre-certified platform architectures that eliminate tender friction. For New Entrants and Emerging Players: Establish a beachhead in subscription-based managed service offerings for Asia-Pacific financial services headquarters, where three-year refresh cycles displace transactional purchasing. Optical touch frameworks for curved retail surfaces represent the most penetrable technology segment. Go-to-market through regional systems integrator partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward display-technology pure-plays with deep systems integrator partnerships and managed service capabilities. Long-term viability hinges on regulatory affairs infrastructure and GB standard pre-qualification for Chinese public tenders. Watch for MIIT efficiency certification threshold adjustments as an inflection indicator for foreign supplier access.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Integration | Samsung Electronics controls driver IC costs through in-house fabrication, locking multi-year enterprise contracts. |
| Ecodesign Certification Investment | Panasonic Corporation integrates power management ASICs to maintain EU compliance without brightness sacrifice. |
| Managed Service Subscription Launch | Systems integrators in Singapore financial districts bundle three-year refresh cycles with installation and maintenance. |
| Optical Touch Framework Expansion | Camera-based sensing scales to curved retail surfaces previously inaccessible to infrared grid alternatives. |
| Systems Integrator Partnership Deepening | LG Electronics sustains R&D spending through audiovisual channel control across Asia-Pacific theater deployments. |
Research Approach
Desk research of regulatory filings, customs trade data, and industry association publications preceded structured interviews with corporate real estate directors, audiovisual systems integrators, display technology procurement managers, and regulatory affairs specialists. Primary fieldwork combined with secondary validation from FCC electromagnetic emission standards, EU Ecodesign tiered limits, and MIIT GB efficiency certifications. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Assumptions around semiconductor supply continuity, regulatory enforcement timelines, and corporate capital expenditure cycles were held fixed while touch technology adoption curves and service contract penetration rates were varied across the projection horizon. Segmentation dimensions modeled include display substrate type, touch sensing architecture, application environment, end-user industry, and regional regulatory cluster. CAGRs were derived from installed base growth, replacement cycle compression, and average selling price trajectory analysis.
Stress conditions across driver IC lead times, indium tin oxide commodity pricing, and EU standby power limit enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hybrid workplace investment persistence and industrial automation cluster expansion. Material shifts in Taiwan semiconductor export restrictions or MIIT certification threshold adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
United States Microdisplay Market
Display Technologies
Holographic Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Smart Screen Market
Display Technologies
Vietnam Displays Market
Display Technologies
Flexible Display Market
Display Technologies
QLED Display Market
Display Technologies
Display Material Market
Display Technologies
AMOLED Substrate Market
Display Technologies
OLED Panel Market
Display Technologies
Large Industrial Displays Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Touch Screen Module Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market