
 Eco Bowls Market | 2026-2036
Eco Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Eco Bowls Market Foresight
Food service sector demand is hardening as cafes and food trucks abandon polystyrene containers. Huhtamaki Oyj leverages its molded fiber manufacturing scale across European packaging networks. Vegware sustains compostable certification leadership through BPI and TÜV Austria validations. Eco-Products, Inc. anchors North American distribution through broadline foodservice channels.
Eco bowls are rigid food containers engineered from bagasse, palm leaf, or molded bamboo fiber with heat tolerance typically exceeding 100°C and grease resistance suitable for hot meals. They serve commercial food service operators requiring single-use serviceware that meets municipal composting stream standards. Bagasse-based product forms dominate volume due to abundant sugarcane processing byproduct supply, while palm leaf variants command premium positioning in upscale catering where aesthetic differentiation matters. Reusable silicone and stainless steel segments occupy smaller but defensible niches in institutional dining contracts with closed-loop logistics.
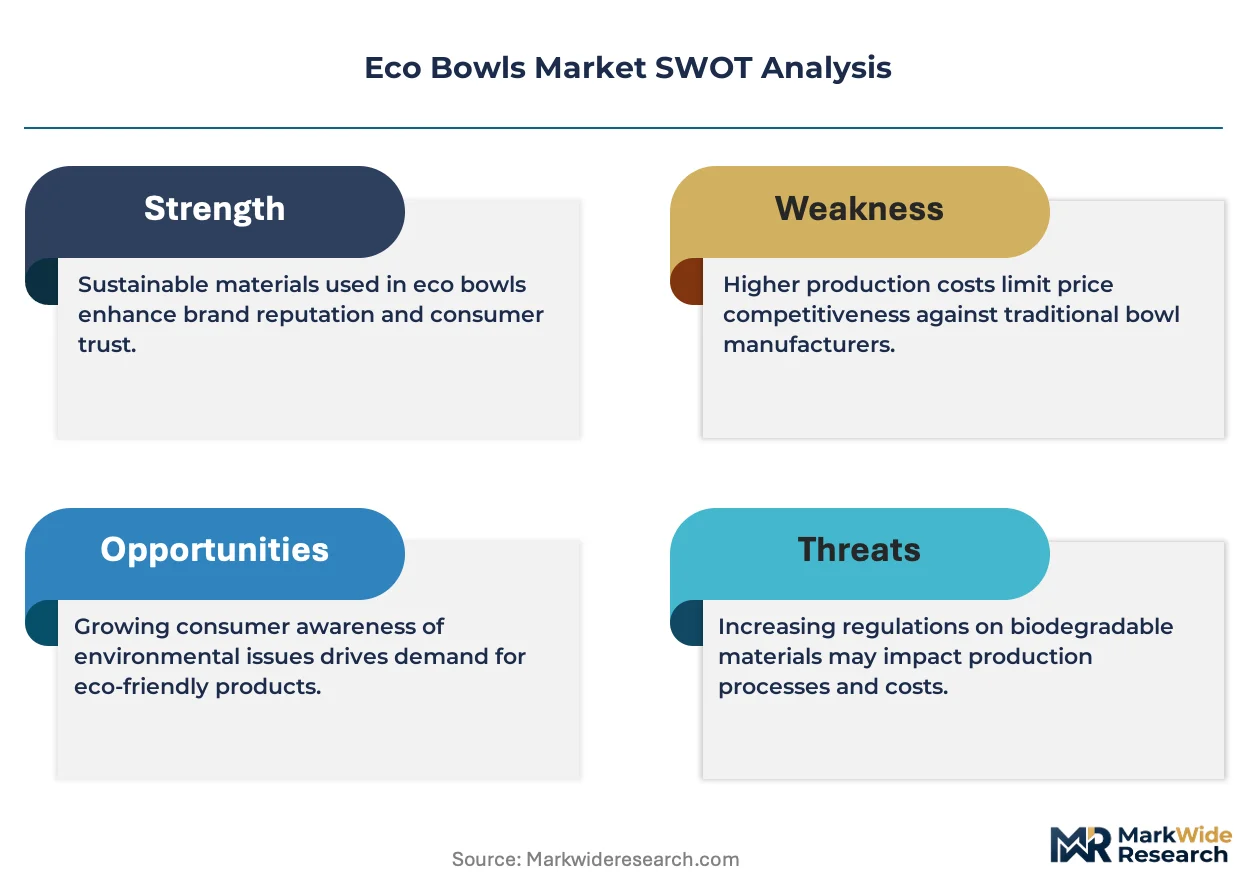
The EU Single-Use Plastics Directive, FDA food contact substance regulations, and BPI compostability certification collectively determine market access and product formulation pathways across major demand centers. REACH chemical restrictions and state-level extended producer responsibility laws in California and New York are tightening material traceability requirements. Stakeholders must monitor evolving composting infrastructure gaps between certified products and actual municipal processing capacity.
Market Dynamics
Single-use plastics bans are compressing demand timelines for food service operators, forcing rapid material transitions before composting infrastructure matures. The mismatch between certified product availability and municipal processing capacity creates operational friction across supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-outs of polystyrene containers in member states are redirecting institutional procurement toward bagasse and palm fiber alternatives.
- Sugar processing byproduct streams:Bagasse supply from Brazil and India sugarcane mills provides abundant raw material at scale for molded fiber production.
- Corporate sustainability procurement:Large food service contracts in Germany, the United States, and Japan now require compostable serviceware as standard terms.
Market Restraints
- Palm leaf supply concentration:Harvesting and pressing operations cluster in southern India and Sri Lanka, exposing buyers to monsoon-driven raw material volatility.
- Composting infrastructure gaps:BPI-certified products often lack compatible industrial composting facilities in mid-sized US municipalities.
- Silicone and stainless steel substitution:Reusable container programs in institutional dining with closed-loop logistics capture contract value from single-use alternatives.
Strategic Opportunities
- Extended producer responsibility laws:California and New York state regulations are creating compliance-driven demand for traceable, certified compostable packaging.
- Food truck and mobile catering segments:These operators require lightweight, heat-tolerant containers with minimal storage footprint.
- Home composting certification pathways:TÜV Austria's OK compost HOME standard opens residential disposal routes beyond industrial facilities.
Industry Challenges
- Molded fiber tooling capex:Precision forming dies for complex bowl geometries require significant capital investment with long amortization periods.
- Multi-certification timeline compression:Products must simultaneously secure FDA food contact clearance, BPI compostability, and regional chemical compliance before market entry.
- Moisture barrier formulation:PLA and bio-based coatings that maintain grease resistance above 100°C remain technically constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco Bowls Market |
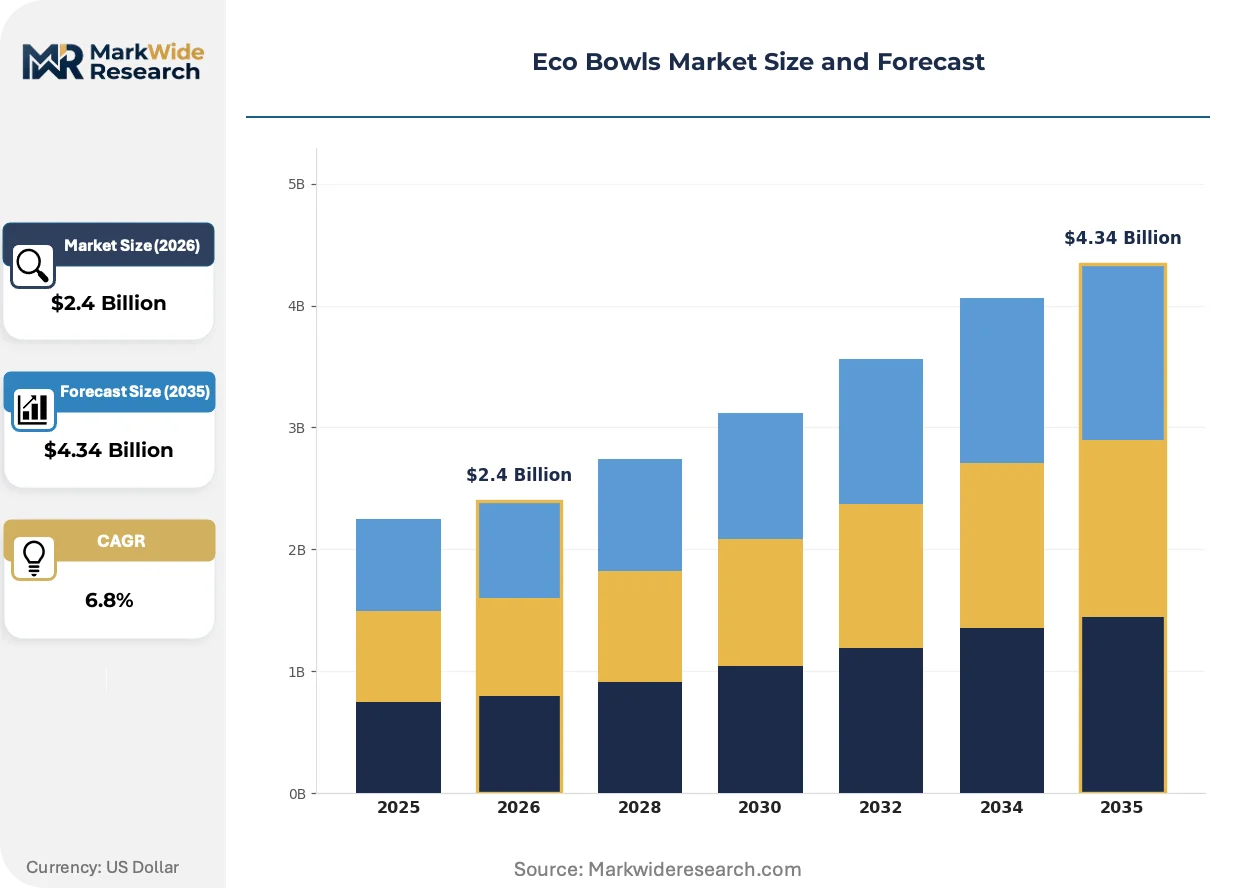
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bamboo, Wheat Straw, Bagasse, Palm Leaf, Recycled Paper, Cornstarch Product Form: Disposable, Reusable, Compostable, Biodegradable, Molded, Pressed Application: Food Service, Grocery Packaging, Outdoor Catering, Institutional Dining, Event Management, Office Pantry End User Sector: Cafes, Food Trucks, Restaurants, Catering Firms, Hotels, Community Centers |
| Companies Covered | Huhtamaki Oyj, Mondi Group, Crown Holdings, Vegware, BioPak, Eco-Products, Inc., Genpak, LLC, Pactiv Evergreen Inc., Sabert Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco Bowls Market Shifts & Advancements
Material science advances and regulatory precision are converging to redefine performance benchmarks for compostable food containers. Three developments are restructuring how operators specify, source, and dispose of serviceware.
Barrier coating technology is modularizing across supplier tiers. Bio-based PLA and PHA formulations now integrate with standard bagasse fiber substrates without requiring proprietary equipment. Mid-sized converters in Vietnam and Thailand are adopting these coating systems to serve export markets. This standardization is modularizing what had been vertically integrated supply chains into interchangeable component sourcing.
REACH chemical restrictions are tightening traceability mandates for imported molded fiber products. ECHA substance of very high concern listings now cover specific fluorinated compounds previously used in grease-resistant coatings. European distributors are demanding full material disclosure from Asian manufacturers. German retail and food service buyers are responding by consolidating supplier relationships with certified transparent producers.
Specification behavior among contract food service operators is compressing switching cycles. Multi-year agreements that once locked in plastic serviceware suppliers now include material transition clauses with 12-month compliance windows. Broadline distributors are building compostable product portfolios as core categories rather than specialty lines. This pattern is most pronounced in US coastal metropolitan markets where municipal bans phase in earliest.
Eco Bowls Market Segmentation
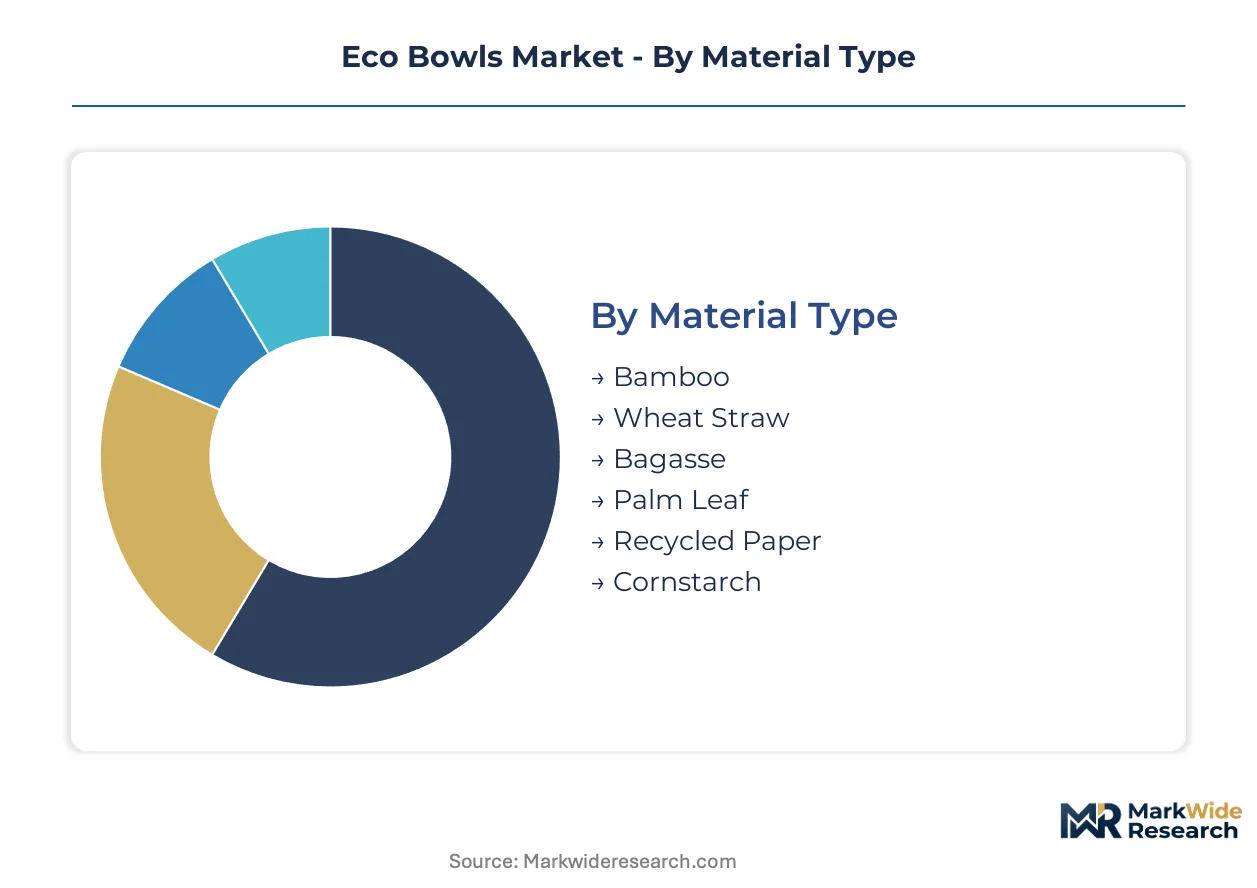
Eco bowl procurement decisions cascade through four distinct lenses: raw material origin determines regulatory compliance pathways, product form dictates disposal infrastructure requirements, application context sets performance specifications, and end user scale shapes contract economics. Each segmentation layer reveals divergent margin structures and certification burdens.
Material Type:
Bagasse and bamboo fiber production concentrates in Asian sugarcane belt and bamboo plantation zones, creating geographic supply lock-in that shapes converter location decisions.
- Bagasse:Molded fiber derived from sugarcane processing residue dominates volume production due to abundant feedstock from Brazilian and Indian mills. Food service contracts in Germany and the United States specify bagasse as the default compliant material under EU Single-Use Plastics Directive and municipal bans.
- Palm Leaf:Areca leaf sheaths pressed into rigid bowls command premium positioning in upscale catering segments across Japan and coastal US metropolitan markets. Harvesting operations cluster in southern India and Sri Lanka, exposing supply chains to monsoon seasonality and freight cost volatility.
- Bamboo:Fast-growing grass species processed into pulp for molded fiber serves institutional dining contracts requiring rapid replenishment cycles and closed-loop sourcing narratives.
- Wheat Straw:Agricultural residue from grain processing provides regional supply advantages in North American and European farming belts, reducing transport emissions for local-market producers.
- Recycled Paper:Post-consumer fiber streams feed lower-performance applications where heat tolerance requirements remain below 80°C and grease resistance is secondary.
- Cornstarch:PLA and bio-resin formulations serve specialized compostable certification pathways, though industrial processing temperature requirements limit compatible municipal infrastructure.
Bagasse absorbs the bulk of installed capacity; palm leaf is expanding most quickly in premium catering segments.
Product Form:
Cost tier stratification separates single-use disposable units from capital-intensive reusable programs, with certification grade driving price positioning within each tier.
- Compostable:BPI and TÜV Austria-certified products meeting ASTM D6400 or EN 13432 standards command price premiums in corporate sustainability procurement contracts across California and New York state compliance environments.
- Disposable:Single-use molded fiber bowls without compostable certification serve price-sensitive food truck and mobile catering operators in jurisdictions with limited enforcement infrastructure.
- Reusable:Silicone and stainless steel container programs with closed-loop logistics capture institutional dining contracts in German corporate campuses and Japanese university systems, amortizing higher per-unit costs across multiple use cycles.
- Biodegradable:Uncertified bio-based formulations occupy ambiguous regulatory positioning, facing scrutiny from ECHA substance disclosure requirements and state-level extended producer responsibility laws.
- Molded:Precision-formed fiber with complex geometries requires substantial tooling investment, concentrating production among scaled converters with multi-cavity die capabilities.
- Pressed:Lower-complexity palm leaf and bamboo compression forming enables smaller-scale manufacturing, supporting regional supplier fragmentation in Southeast Asian export markets.
Compostable forms capture the steepest expansion trajectory; disposable units retain volume dominance in emerging market penetration.
Application:
Volume concentration in food service channels contrasts with margin-rich specialty segments where aesthetic differentiation and certification compliance justify premium positioning.
- Food Service:Cafes, quick-service restaurants, and delivery kitchens across the United States and Germany drive baseline demand, with bagasse bowls replacing polystyrene under phased municipal bans.
- Outdoor Catering:Event-based consumption in parks, festivals, and sports venues demands lightweight, heat-tolerant containers with minimal post-event cleanup burden, favoring palm leaf aesthetics in Japanese and coastal US premium markets.
- Institutional Dining:Corporate campuses, hospitals, and university systems with established sustainability procurement policies specify compostable serviceware as contract minimums, particularly in German industrial regions.
- Grocery Packaging:Prepared food sections in European and North American retail chains require display-grade presentation with grease resistance for hot deli items.
- Event Management:Wedding and corporate hospitality segments prioritize visual differentiation, absorbing palm leaf premium pricing for natural texture and irregular edge aesthetics.
- Office Pantry:Smaller-scale consumption in workplace break rooms represents fragmented, price-sensitive demand with limited certification requirements.
Food service channels anchor production planning; outdoor catering is gaining share fastest as event-based sustainability mandates proliferate.
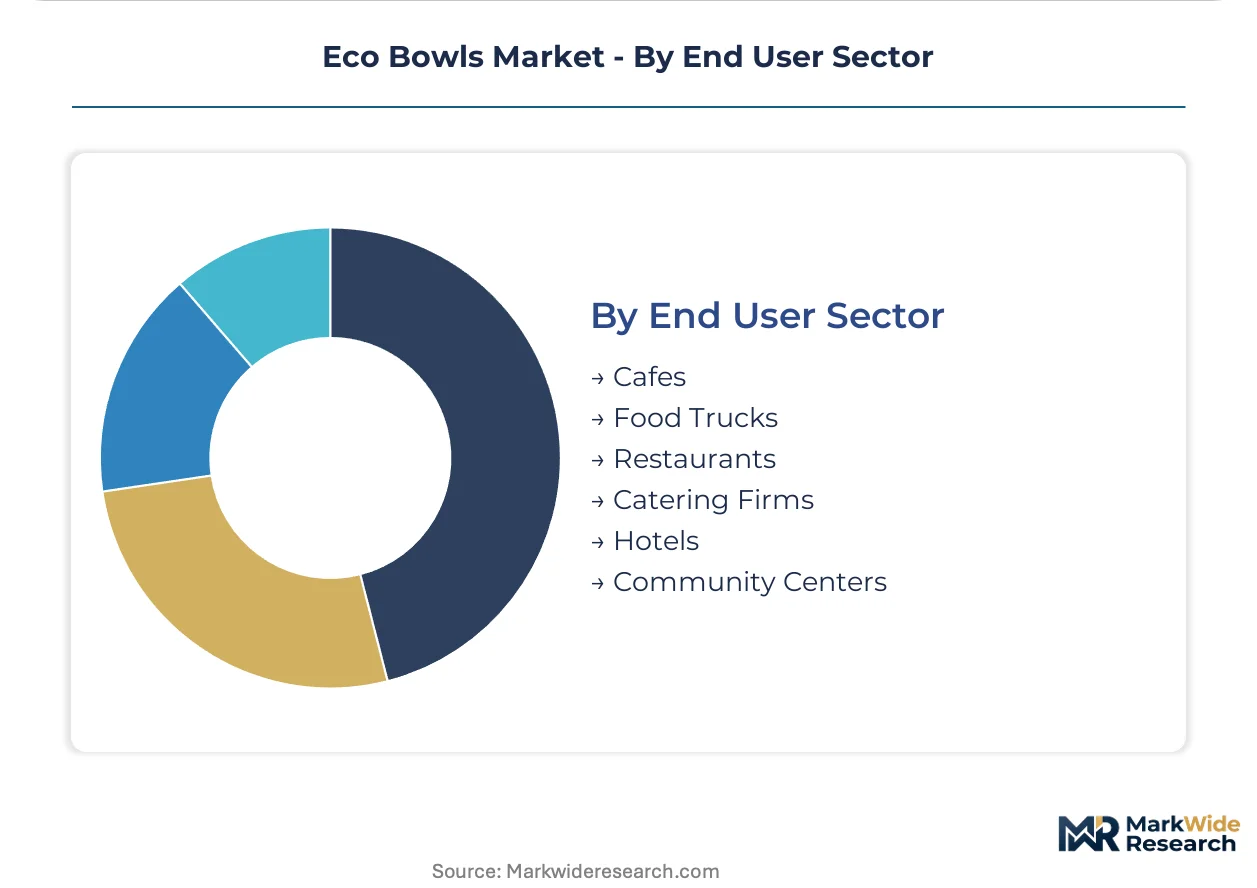
End User Sector:
Customer type segmentation reveals divergent procurement sophistication, from standardized broadline distributor relationships to specialized direct contracting with certification transparency requirements.
- Restaurants:Full-service and fast-casual operators across Germany and Japan negotiate multi-year supply agreements with material transition clauses, consolidating purchasing through broadline foodservice distributors.
- Catering Firms:Event-focused operators require flexible inventory with rapid turnaround, sourcing through regional converters capable of short-run customization for branded hospitality experiences.
- Cafes:Independent coffee shop networks in US coastal cities drive early adoption of compostable bowl standards, often exceeding municipal minimum requirements for customer-facing sustainability positioning.
- Food Trucks:Mobile operators prioritize storage efficiency and heat tolerance over certification grade, creating price-sensitive demand pockets in enforcement-lag markets.
- Hotels:Hospitality procurement departments in Japanese business hotel chains and European resort properties specify consistent serviceware across property portfolios, favoring scaled suppliers with transparent supply chain documentation.
- Community Centers:Municipal and nonprofit facilities operate under constrained budgets, accepting lower-performance alternatives where industrial composting infrastructure remains unavailable.
Restaurants concentrate procurement volume; catering firms are climbing the fastest as event-based sustainability specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Thailand attract molded fiber converters serving export markets, while EU regulatory pressure and US state-level mandates create demand pockets across three continents.
United States
California and New York state extended producer responsibility laws compress procurement timelines for food service operators. FDA food contact substance regulations govern material formulation pathways for bagasse and palm leaf imports. Los Angeles and New York City municipal bans on polystyrene drive rapid substitution toward BPI-certified compostable alternatives in broadline distribution.
Germany
Industrial regions in North Rhine-Westphalia anchor corporate sustainability procurement for institutional dining contracts. REACH chemical restrictions and ECHA substance disclosure mandates tighten traceability requirements for imported molded fiber. Bavarian packaging converters leverage EU Single-Use Plastics Directive compliance to secure multi-year food service supply agreements.
Japan
METI circular economy guidelines and corporate campus sustainability policies specify compostable serviceware as contract minimums. Tokyo and Osaka metropolitan markets absorb premium palm leaf positioning for upscale catering segments. Japanese university systems pilot closed-loop reusable container programs alongside single-use alternatives.
India
Sugarcane belt states of Maharashtra and Uttar Pradesh supply abundant bagasse feedstock for molded fiber production. BIS standards and FSSAI food contact regulations shape domestic market access requirements. Tamil Nadu and Karnataka host pressing operations for palm leaf export to European and North American premium segments.
Vietnam
Export processing zones in Ho Chi Minh City and Hanoi attract mid-sized converters adopting standardized bio-based coating systems. Vietnamese manufacturers serve EU and US demand as Chinese supply chain diversification accelerates. Local producers leverage ASEAN trade agreements to access Japanese and South Korean food service markets.
Eco Bowls Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with certification-heavy European markets favoring transparent supply chains while price-sensitive emerging markets tolerate shorter compliance windows. The vendor base organizes around three archetypes: scaled fiber converters with multi-cavity die capabilities, regional palm leaf pressers serving premium catering niches, and broadline distributors building compostable portfolios as core categories. Dominant competitive moves include backward integration into bagasse pulp supply and strategic partnerships with municipal composting operators to close infrastructure gaps.
Among Nordic-European scaled converters, Huhtamaki Oyj represents the multi-regional manufacturing archetype with molded fiber networks spanning multiple continents. Mondi Group exemplifies integrated paper and fiber packaging specialists diversifying into food service applications. Pactiv Evergreen Inc. anchors North American broadline distribution capabilities. These three occupy positions across distinct competitive vectors—manufacturing scale, material integration, and channel access—rather than direct segment overlap.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Mondi Group |
| Crown Holdings |
| Vegware |
| BioPak |
| Eco-Products, Inc. |
| Genpak, LLC |
| Pactiv Evergreen Inc. |
| Sabert Corporation |
| Others |
Supply & Pricing Matrix
Corporate sustainability procurement mandates in Germany and California are compressing supplier qualification timelines, forcing bagasse and palm fiber converters to absorb certification costs upfront while negotiating multi-year offtake agreements that lock in volume commitments before pricing power solidifies.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as food service operators facing municipal polystyrene bans seek rapid material transitions. Three-tier pricing structure across BPI-certified premium, standard compostable, and uncertified economy tiers reflects certification grade and volume scale differentiation. Price erosion runs through the disposable uncertified tier as Vietnamese and Thai converters expand molded fiber capacity. Food truck operators exhibit highest price sensitivity, while German institutional dining contracts show lowest sensitivity due to sustainability procurement floors.
Supply Chain Analysis
Bagasse pulp supply rests on Brazilian and Indian sugarcane processing infrastructure, with palm leaf sheaths drawing from southern India and Sri Lanka harvesting operations. Raw material dependencies include sugarcane residue streams, areca leaf harvesting cycles, and bio-based PLA coating formulations. Monsoon-driven raw material volatility in South Asia creates supply chain risk for premium palm leaf variants. Distribution runs through broadline foodservice distributors in North America and specialized packaging converters in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable scaled producers as multi-certification timeline compression and tooling capex requirements force sub-scale regional converters into acquisition targets or contract manufacturing roles.
For Market Incumbents: To counter silicone and stainless steel reusable program substitution in institutional dining, bagasse converters should pursue backward integration into Brazilian and Indian pulp supply and secure captive BPI certification capacity ahead of California and New York extended producer responsibility enforcement windows. For New Entrants and Emerging Players: Mid-sized US municipalities lacking industrial composting infrastructure represent an underserved buyer archetype requiring home-composting-certified product formats with TÜV Austria OK compost HOME validation, accessible through direct contracting with food truck and mobile catering operators bypassing broadline distributor markups. For Investors and Strategic Acquirers: The window for entry favors scaled molded fiber converters with multi-cavity die capabilities and transparent Asian supply chain documentation, with long-term viability hinging on five-to-ten-year municipal composting infrastructure buildout trajectories; watch for industrial composting facility permitting acceleration in US secondary cities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp Supply | Captive feedstock from Brazilian and Indian sugarcane mills secures cost position against Asian converter competition. |
| BPI and TÜV Austria Certification Investment | Dual certification opens California compliance markets and European institutional procurement channels simultaneously. |
| Municipal Composting Operator Partnership | Closing infrastructure gaps between certified products and actual processing capacity locks in customer retention. |
| Multi-Cavity Die Capacity Expansion | Precision forming capabilities for complex bowl geometries capture premium food service contract specifications. |
| Bio-Based Coating Technology Licensing | PLA and PHA barrier formulations from Vietnamese and Thai adopters modularize supply chain component sourcing. |
Research Methodology
Multi-period observation of municipal ban implementation timelines, composting infrastructure deployment, and corporate sustainability procurement policy adoption anchored the trend analysis, supplemented by interviews with molded fiber plant managers, broadline foodservice distributor category buyers, sustainability procurement leads at German industrial catering operators, and technical R&D directors at bio-based coating suppliers. Secondary validation drew from FDA food contact substance filings, BPI and TÜV Austria certification databases, EU Single-Use Plastics Directive implementation reports, and ECHA substance of very high concern listings. Bottom-up volume modeling and top-down market sizing triangulated demand estimates.
Input-output matrices mapped bagasse and palm fiber supply flows against food service operator demand clusters across the projection horizon. Segmentation dimensions modeled included material type, product certification grade, application context, and end user sector scale. CAGRs were derived from regression analysis of historical substitution rates and regulatory phase-in schedules, incorporating industrial composting facility capacity buildout curves and sugarcane processing byproduct availability forecasts as industry-specific inputs.
Revisions become necessary when municipal composting infrastructure deployment lags certified product availability, when REACH chemical restrictions expand to additional coating compounds, or when reusable container program adoption accelerates in institutional dining; a small set of permitting velocity, regulatory scope expansion, and substitution technology penetration triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Canned Food Market
Packaged Foods
Burritos Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Convenience Food Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Instant Soup Market
Packaged Foods
Sugar Bags Market
Packaged Foods
North America Pasta Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Organic Energy Bar Market