
 Quinoa Pasta Market | 2026-2036
Quinoa Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Quinoa Pasta Market Analytics
Multi-pack bundling is rebalancing buyer choice across premium and standard quinoa pasta tiers. Ancient Harvest leverages its organic supply chain to sustain shelf presence in North American health food shops. Barilla G. e R. F.lli S.p.A. anchors European distribution through its established pasta infrastructure. Banza LLC differentiates with chickpea-quinoa blends that compete on protein content.
Quinoa pasta denotes a grain-based noodle product manufactured from quinoa flour, typically blended with rice or corn flour to achieve extrusion stability and al dente texture, serving consumers requiring gluten-free alternatives with complete protein profiles. The Organic product type commands premium positioning through certified supply chains and clean-label claims. Health Food Shops channel growth outpaces Supermarkets among early adopters seeking dietitian-curated assortments. Spaghetti form dominates volume while Fusilli captures margin through artisan positioning and sauce-retention functionality.
The FDA enforces gluten-free labeling thresholds below 20 ppm, compelling manufacturers to validate supply chain segregation and testing protocols. USDA Organic certification and EU REACH compliance on food-contact materials further structure market access requirements for cross-border suppliers. Stakeholders must monitor evolving protein-content disclosure rules and regional allergen thresholds as clean-label expectations intensify.
Market Dynamics
Supply chain consolidation around certified organic quinoa sourcing in Peru and Bolivia is compressing ingredient costs while tightening traceability requirements for North American and European manufacturers seeking clean-label positioning.
Growth Catalysts
- FDA Gluten-Free Labeling Rules:The FDA's 20 ppm threshold mandates validated supply chain segregation, driving investment in dedicated processing facilities and third-party certification uptake.
- Protein-Content Disclosure Trends:Consumer scanning of complete protein profiles on packaging is elevating quinoa pasta above rice-based alternatives in retail assortment priorities.
- Italy's Organic Retail Corridors:Concentrated demand in Milan and Bologna's specialized food districts is establishing premium pricing benchmarks that ripple through EU distribution networks.
Market Restraints
- Input Cost Volatility:Quinoa grain prices fluctuate with Andean harvest cycles and climate variability, compressing margins for manufacturers without long-term grower contracts.
- Extrusion Technical Limitations:Pure quinoa flour lacks gluten's elastic properties, requiring rice or corn flour blends that dilute protein claims and complicate clean-label messaging.
- EU REACH Compliance Friction:Food-contact material regulations for imported packaging create documentation burdens and border delays for non-EU suppliers.
Strategic Opportunities
- Chickpea-Quinoa Convergence:Blending quinoa with legume flours is opening sports nutrition and pediatric nutrition applications with elevated amino acid scores.
- Dietitian-Curated Channels:Health food shops with in-house nutrition counseling are commanding loyalty premiums and repeat purchase rates above conventional supermarket placements.
- USDA Organic Certification Tailwinds:Federal procurement preferences and school nutrition program eligibility are expanding institutional demand for certified organic SKUs.
Industry Challenges
- Certification Timeline Compression:USDA Organic and gluten-free validation cycles stretch 12-18 months, delaying product launches and locking working capital in inventory.
- Skill Gaps in Ancient Grain Processing:Extrusion technicians with quinoa-specific expertise remain scarce, forcing manufacturers to train internally or poach from specialty milling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinoa Pasta Market |
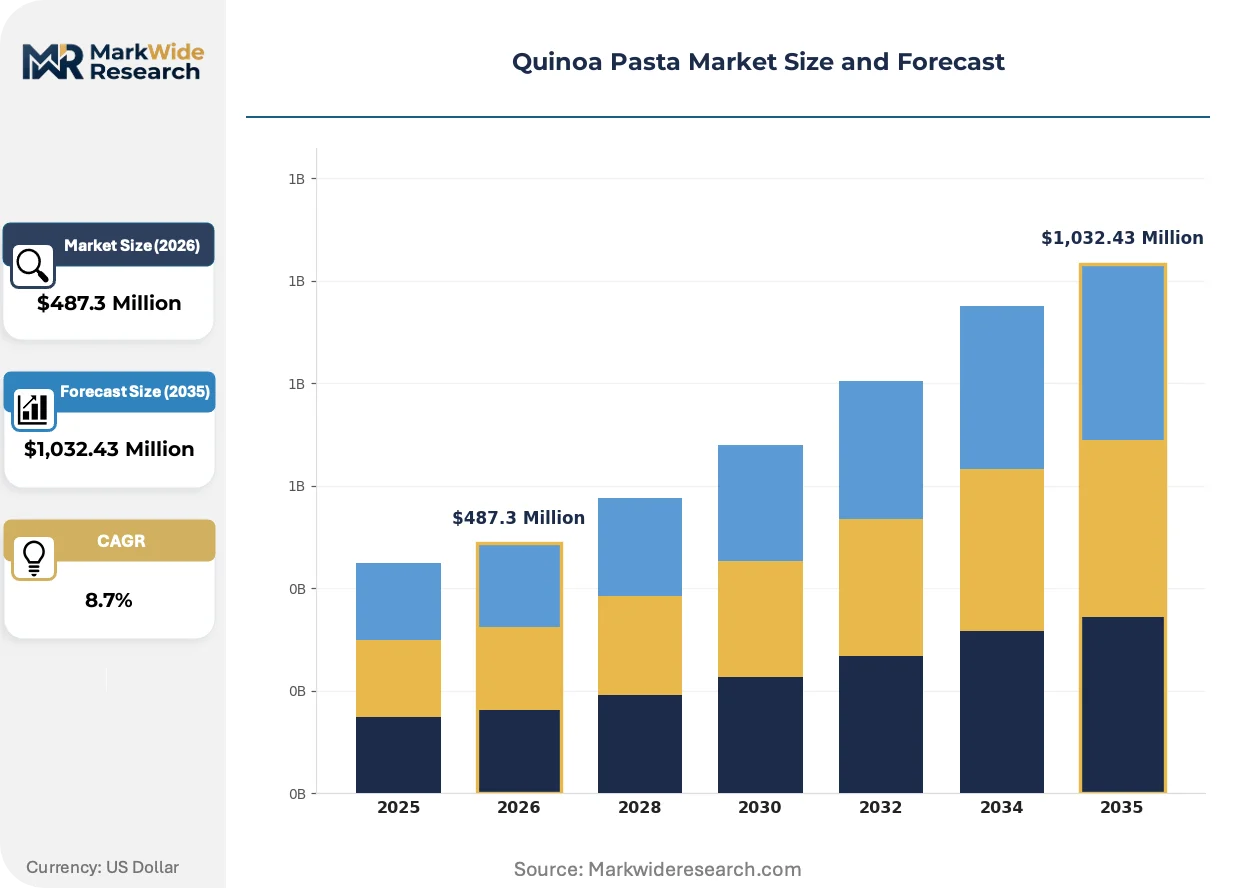
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Organic, Traditional, High-Protein Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Form: Spaghetti, Macaroni, Fusilli, Lasagna Sheets End User: Health-Conscious Consumers, Vegetarian Dieters, Gluten Intolerant Individuals, Chefs |
| Companies Covered | Quinoa Corporation, Banza LLC, Jovial Foods Inc., Barilla G. e R. F.lli S.p.A., Ancient Harvest, Doves Farm Foods Ltd, Rummo S.p.A, LE VENEZIANE SRL, Cappello's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinoa Pasta Market Evolving Landscape
Ingredient blending protocols and processing equipment configurations are evolving rapidly as manufacturers balance texture fidelity with protein retention and clean-label purity.
High-pressure extrusion technology is modularizing production lines for quinoa pasta manufacturers. Mid-sized processors in the United States and Germany are retrofitting twin-screw extruders with temperature-controlled cooling zones to preserve heat-sensitive amino acids. This modularization is enabling smaller batch runs for specialty SKUs without sacrificing throughput efficiency on standard lines.
REACH regulations on food-contact materials are tightening migration testing requirements for imported quinoa pasta packaging. European distributors now demand comprehensive substance declarations from Asian and South American suppliers. Organic and gluten-free certified products face the steepest compliance burdens, with several Italian retailers delisting SKUs lacking full material traceability documentation.
Buyer concentration among health-conscious millennials is shifting assortment decisions from traditional supermarkets toward specialized e-commerce platforms with subscription models. Direct-to-consumer channels featuring personalized nutrition matching algorithms are capturing repeat purchase loyalty in urban Canada and coastal United States markets. This channel migration is forcing legacy pasta brands to rebuild distribution partnerships or launch captive digital storefronts.
Quinoa Pasta Market Segmentation
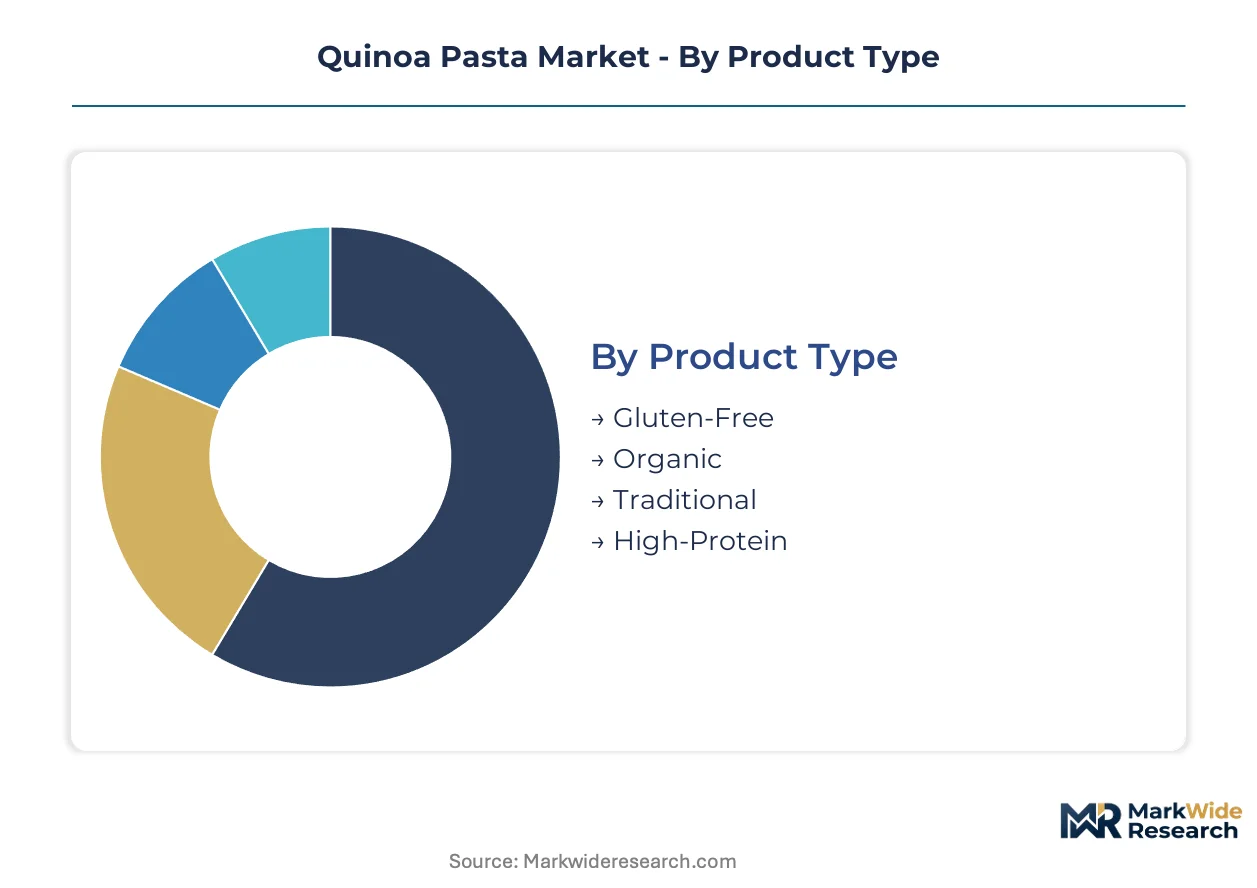
Quinoa pasta manufacturers calibrate product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles and certification burdens that reshape competitive positioning.
Product Type:
Consumers upgrade from conventional wheat alternatives toward certified specialty formats as dietary protocols tighten.
- Gluten-Free:Formulated to FDA's 20 ppm threshold with validated supply chain segregation. Demand concentrates in US households with celiac diagnoses where third-party certification commands shelf placement priority.
- Organic:USDA or EU Organic certified with full traceability from Andean cooperatives. Premium positioning in Milan and Bologna retail corridors establishes pricing benchmarks that ripple through EU distribution networks.
- Traditional:Quinoa-rice or quinoa-corn blends without specialty certifications. Budget positioning serves price-sensitive households transitioning from wheat pasta.
- High-Protein:Legume-quinoa formulations targeting sports nutrition and pediatric applications. Elevated amino acid scores differentiate from rice-based alternatives.
Volume placements concentrate in Gluten-Free; the faster expansion belongs to Organic.
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost structures.
- Online Retail:Subscription models with personalized nutrition algorithms capture repeat loyalty in urban Canada and coastal US markets. Direct-to-consumer bypasses distributor markups.
- Supermarkets:Mass-market penetration requires slotting fee negotiations and promotional calendar alignment. Standard SKUs dominate here with limited specialty placement.
- Specialty Stores:Curated assortments in Italian organic food districts command premium pricing. Smaller batch sizes accommodate artisan positioning.
- Health Food Shops:In-house dietitian counseling drives loyalty premiums above conventional retail. Early adopter concentration supports new product trials.
Supermarkets anchor volume throughput; Health Food Shops deliver the steepest margin expansion.
Form:
Shape engineering balances extrusion feasibility with sauce compatibility and cooking performance.
- Spaghetti:Long-strand format dominates production volume with established consumer familiarity. Extrusion stability requires precise quinoa-rice flour ratios.
- Macaroni:Elbow shape serves pediatric and casserole applications. Hollow center demands modified die configurations.
- Fusilli:Spiral geometry maximizes sauce retention for artisan positioning. Premium pricing in specialty retail justifies slower throughput.
- Lasagna Sheets:Flat format requires controlled moisture content to prevent breakage during boiling. Limited production due to niche demand.
Spaghetti generates baseline volume; Fusilli captures the highest margin per kilogram.
End User:
User segmentation aligns formulation intensity with dietary restriction severity and culinary application.
- Health-Conscious Consumers:Complete protein seekers without diagnosed conditions. Flexible on certification requirements, responsive to clean-label claims.
- Vegetarian Dieters:Amino acid completeness drives purchase decisions. Legume-quinoa blends satisfy protein-combining protocols.
- Gluten Intolerant Individuals:Medically necessitated avoidance with zero tolerance for cross-contamination. Validates premium pricing for certified segregation.
- Chefs:Foodservice applications demanding al dente texture under restaurant holding conditions. Batch consistency and cooking tolerance outweigh retail packaging aesthetics.
Health-Conscious Consumers provide the broadest addressable base; Gluten Intolerant Individuals exhibit the highest willingness-to-pay.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru and Bolivia supply the bulk of certified organic quinoa grain, while the United States, Italy, and Germany absorb the highest finished-product volumes. This production-consumption divide shapes freight economics and traceability investments across the value chain.
United States
Health-conscious millennials in urban coastal markets drive subscription-based quinoa pasta purchases through specialized e-commerce platforms. The FDA's 20 ppm gluten-free labeling threshold mandates validated supply chain segregation, compelling domestic manufacturers to invest in dedicated processing facilities. Chicago and Minneapolis host the densest concentrations of specialty grain extrusion capacity.
Italy
Organic retail corridors in Milan and Bologna establish premium pricing benchmarks that ripple through EU distribution networks. EFSA guidelines on gluten-free claims align with national celiac association standards, reinforcing certification requirements. Emilia-Romagna's pasta manufacturing clusters have retrofitted production lines for ancient grain formulations.
Germany
REACH regulations on food-contact materials create documentation burdens for imported quinoa pasta packaging, favoring domestic suppliers with compliant material traceability. Berlin and Hamburg anchor demand for dietitian-curated health food shop assortments. Bavarian processors are retrofitting twin-screw extruders with temperature-controlled cooling zones.
Canada
Health Canada and PMRA coordinate gluten-free labeling with organic certification standards, streamlining multi-claim product approvals. Urban centers in British Columbia and Ontario concentrate direct-to-consumer channel growth with personalized nutrition matching algorithms. Vancouver-based specialty retailers command loyalty premiums above conventional supermarket placements.
Peru
Andean cooperatives supply certified organic quinoa grain under long-term contracts that compress ingredient costs for North American and European manufacturers. The Ministry of Agriculture's export quality protocols align with USDA Organic and EU Organic equivalency agreements. Puno and Cusco regions concentrate smallholder cultivation with tightening traceability requirements.
Quinoa Pasta Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated shelf presence in mass retail channels favors established pasta manufacturers with existing distributor relationships, while fragmented specialty segments reward agile entrants with clean-label credentials. Three archetypes dominate: legacy pasta houses extending into gluten-free lines, ancient grain pure-plays with certified organic supply chains, and legume-blend innovators competing on protein content. Capacity expansion and portfolio diversification represent the dominant competitive moves.
Within the pure-play ancient grain tier, Ancient Harvest and Jovial Foods Inc. exemplify supply chain transparency strategies, while Banza LLC occupies a position at the protein-innovation intersection with legume-quinoa formulations. Barilla G. e R. F.lli S.p.A. anchors the diversified conglomerate archetype, leveraging established European distribution infrastructure. These three companies represent distinct strategic postures without implying specific market share positions or operational details.
| Leading Market Players |
|---|
| Quinoa Corporation |
| Banza LLC |
| Jovial Foods Inc. |
| Barilla G. e R. F.lli S.p.A. |
| Ancient Harvest |
| Doves Farm Foods Ltd |
| Rummo S.p.A |
| LE VENEZIANE SRL |
| Cappello's |
| Others |
Value Network & Pricing Analysis
FDA-mandated gluten-free certification requirements are forcing manufacturers toward dedicated processing facilities, which compresses margins on standard-tier products while amplifying pricing power for certified organic SKUs with validated Andean sourcing.
Pricing Analysis
Margin tightening in conventional quinoa-rice blends reflects input cost volatility from Andean harvest cycles and climate variability. Three-tier pricing structure across premium organic, certified gluten-free, and conventional economy levels stratifies the market. Pricing pressure intensifies in the standard tier as Banza LLC and Ancient Harvest compete on protein-content claims. Health-conscious millennials in coastal US markets show lowest price sensitivity, while budget-transitioning households from wheat pasta exhibit highest elasticity.
Supply Chain Analysis
Freight economics from Puno and Cusco regions to North American extrusion facilities absorb 15-20% of landed ingredient costs, favoring manufacturers with long-term grower contracts. Supply concentrates in Peru and Bolivia for certified organic quinoa grain, with secondary sourcing from Ecuador. Processing draws from rice and corn flour suppliers in the United States and Italy for extrusion stability. Single-source vulnerability around Andean climate variability threatens margin consistency. Distribution runs through health food shops with dietitian-curated assortments in urban Canada and coastal US markets, alongside legacy supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure extrusion technology is displacing conventional pasta manufacturing equipment, creating asymmetric upgrade burdens across manufacturer scale tiers.
For Market Incumbents: Extend certified organic SKU portfolios to capture USDA Organic tailwinds in institutional procurement and school nutrition programs. Barilla G. e R. F.lli S.p.A. and legacy pasta houses should retrofit established European distribution infrastructure for ancient grain formulations before pure-play specialists consolidate health food shop placements. Backward integration into Andean cooperative partnerships secures traceability documentation demanded by Italian retailers under REACH compliance. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms with personalized nutrition algorithms offer the most penetrable route for legume-quinoa blend innovators. Target sports nutrition and pediatric applications where elevated amino acid scores command premium positioning absent from rice-based alternatives. Dietitian-curated health food shops in Berlin and Vancouver provide lowest customer acquisition costs for early trials. For Investors and Strategic Acquirers: The window for entry favors pure-play ancient grain specialists with captive organic supply chains and validated gluten-free segregation protocols. Long-term viability hinges on extrusion technical capabilities and certification timeline management. Watch for delisting events among Italian retailers lacking full material traceability documentation as inflection indicators for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Extrusion Retrofit | Bavarian and Chicago processors preserve heat-sensitive amino acids through temperature-controlled cooling zones. |
| Andean Cooperative Partnership | Long-term contracts with Puno and Cusco growers compress ingredient costs while tightening traceability. |
| Direct-to-Consumer Launch | Urban Canada and coastal US subscription models bypass distributor markups with personalized nutrition algorithms. |
| USDA Organic Certification Investment | Federal procurement preferences expand institutional demand for certified organic quinoa pasta SKUs. |
| Legume-Quinoa Formulation Development | Chickpea-quinoa blends open sports nutrition applications with differentiated amino acid scores. |
Research Methodology
Document review covered FDA gluten-free labeling guidance, USDA Organic certification protocols, EFSA food-contact material regulations, and Andean agricultural export quality standards, complemented by interviews with specialty grain extrusion technicians, health food shop category buyers, dietitian-curated channel operators, and Andean cooperative export managers. Secondary validation drew from customs trade data, organic certification databases, and retail audit information. Bottom-up SKU-level volume estimates triangulated against top-down category spending projections.
Market size outputs reflect segment-level modeling across product type, distribution channel, pasta form, and end-user dietary restriction severity. CAGRs were derived from trend-line extrapolation of certification uptake rates, channel migration patterns, and protein-content disclosure evolution. Forecast inputs included Andean harvest cycle variability, REACH compliance documentation burdens, and high-pressure extrusion equipment deployment timelines.
The model holds under stable regulatory certification timelines and continued FDA gluten-free threshold enforcement; deviation in Andean climate patterns or EU food-contact material rule tightening would shift volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Hummus Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Freekeh Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Jams and Spreads Market