
 Impulse Ice-Cream Market | 2026-2036
Impulse Ice-Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Impulse Ice-Cream Market Intelligence
Convenience store shelf space for frozen treats is narrowing as retailers prioritize high-velocity SKUs with shorter replenishment cycles. Unilever Group leverages its freezer infrastructure to dominate impulse placement in petrol forecourts across Western Europe. Nestle S.A. sustains brand recognition through licensed character partnerships that command premium positioning in seasonal displays. General Mills competes via controlled distribution partnerships that limit competitor access to key convenience accounts.
Impulse ice-cream denotes individually portioned frozen desserts formulated for immediate consumption without advance planning, typically containing 10-16% milkfat and stabilized through emulsifier systems to withstand thermal shock during distribution. These products serve commercial purposes by generating high-margin, high-frequency transactions in low-service retail environments. Bars and cones capture the largest volume pools due to handheld portability and minimal packaging waste, while novelty shapes extract premium pricing through licensed entertainment tie-ins. Online retailers represent the fastest-growing distribution channel as dark-store fulfillment and insulated last-mile logistics reduce melt-loss rates.
FDA oversight of dairy labeling standards and EFSA enforcement of additive authorizations under Regulation 1333/2008 constrain formulation flexibility for multinational producers. India's FSSAI mandates specific microbial limits for frozen desserts that differentiate ice-cream from frozen confection standards, creating compliance complexity for imported brands. Stakeholders must monitor evolving refrigerant regulations under the EU F-Gas Regulation and corresponding EPA phasedown schedules, as cold-chain energy costs directly determine route-to-market economics for single-serve distribution.
Market Dynamics
Freezer infrastructure ownership determines route-to-market access across petrol forecourts and convenience chains, compressing margin pools for brands lacking captive cold-chain assets.
Growth Catalysts
- Grab-and-go consumption patterns:Urban commuters in India and Brazil favor single-serve formats from street vendors and modern retail kiosks. Portability drives repeat purchase frequency without home freezer dependency.
- FSSAI frozen dessert standards:India's microbial limit differentiation between ice-cream and frozen confection creates compliance barriers that protect domestic formulation investments.
- Dark-store fulfillment networks:Insulated last-mile logistics reduce melt-loss rates for online impulse orders. E-commerce platforms now stock frozen SKUs previously excluded from home delivery.
Market Restraints
- Dairy input cost volatility:Milkfat and milk solids concentrate price exposure for 10-16% butterfat formulations. Commodity swings compress margin predictability.
- EU F-Gas refrigerant phasedown:Cold-chain energy cost escalation under the EU F-Gas Regulation and EPA schedules raises distribution economics for single-serve units.
- Thermal shock tolerance limits:Emulsifier-stabilizer systems face performance ceilings during ambient temperature excursions in last-mile delivery.
Strategic Opportunities
- Licensed entertainment tie-ins:Character partnerships command premium positioning in seasonal convenience displays. Novelty shapes extract pricing power unavailable to standard bars.
- Clean-label emulsifier migration:FDA and EFSA additive authorization constraints are accelerating natural stabilizer adoption. Early movers capture shelf-space preference.
- Petrol forecourt freezer densification:Unoccupied forecourt real estate in Germany and the UK awaits branded freezer placement. Infrastructure-first entry blocks competitor access.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration maintenance expertise concentrates with legacy dairy distributors. New market entrants face recruitment bottlenecks for route-to-market deployment.
- Dual certification complexity:Simultaneous FDA dairy labeling and EFSA Regulation 1333/2008 compliance extends product development timelines. Multinational launch synchronization suffers.
- Retailer SKU rationalization:Convenience chains narrow frozen shelf space to high-velocity items. Low-turnover novelty formats face delisting pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impulse Ice-Cream Market |
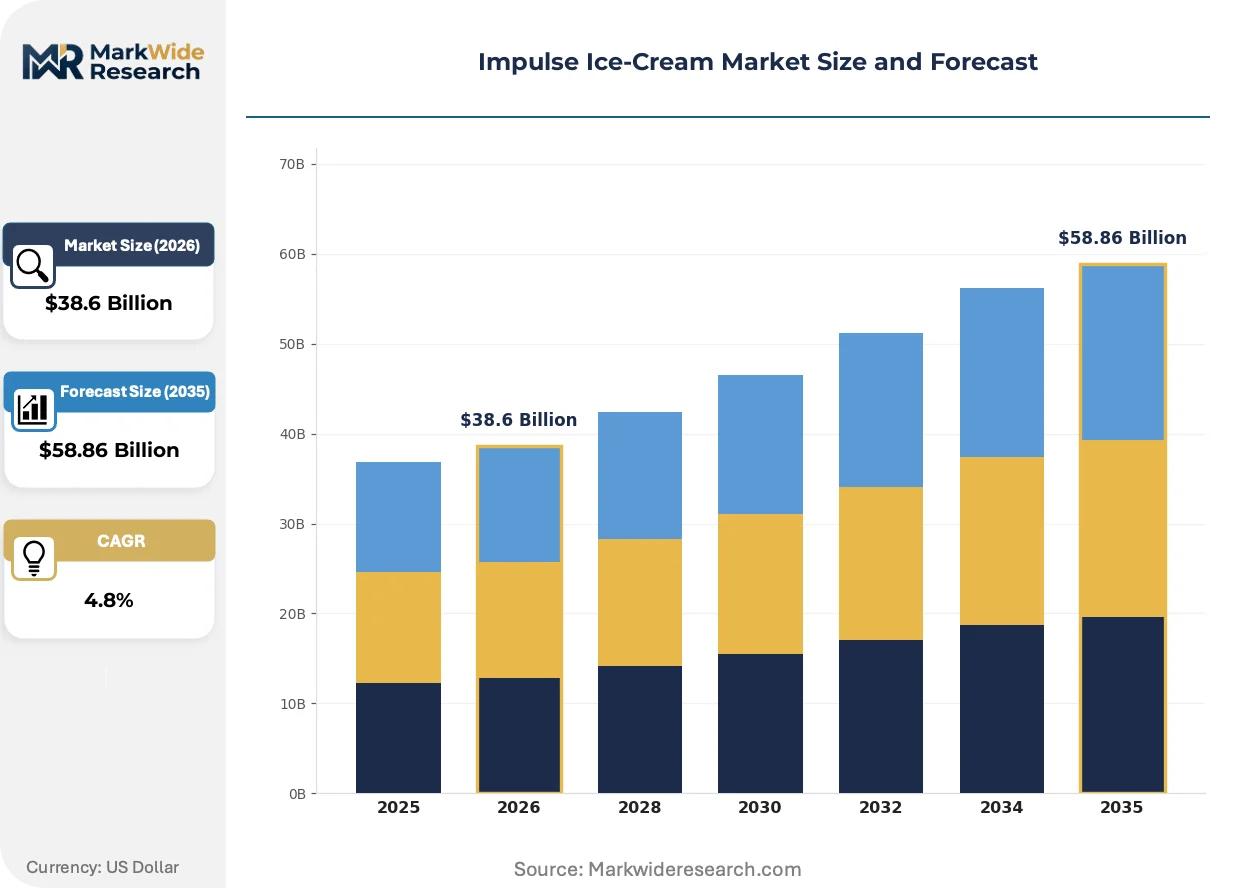
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cones, Bars, Sandwiches, Cups, Novelty Shapes Packaging Type: Stick Wrappers, Paper Cups, Plastic Cups, Cardboard Boxes, Multipacks Distribution Channel: Supermarkets, Convenience Stores, Gas Stations, Street Vendors, Online Retailers End User: Children, Teenagers, Adults, Seniors, Tourists |
| Companies Covered | Inspire Brands Inc. (Baskin-Robbins), Turkey Hill Dairy, Unilever Group, IFFCO, Pure Ice Cream Co LLC, Nestle S.A., Direct Wholesale Foods, Vadilal Industries Limited, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impulse Ice-Cream Market Strategic Shifts & Innovations
Formulation science and distribution infrastructure are converging to reshape competitive access in single-serve frozen desserts. Three developments warrant attention.
Natural stabilizer systems are migrating from artisanal producers to multinational supply chains. Guar and locust bean gum blends replace synthetic emulsifiers in bar and cone formulations. Major manufacturers accelerate reformulation to preempt EFSA enforcement actions on additive authorizations.
REACH chemical registration requirements and the EU F-Gas Regulation are forcing refrigerant transitions across European cold-chain assets. Hydrofluoroolefin adoption raises equipment replacement costs for distributors. Smaller regional brands defer network expansion pending capital recovery clarity.
Dark-store micro-fulfillment is compressing delivery windows for frozen impulse purchases. Insulated packaging and route optimization now enable 15-minute delivery promises previously impossible for ice-cream. Urban India and São Paulo represent the most visible deployment of this model.
Impulse Ice-Cream Market Segmentation
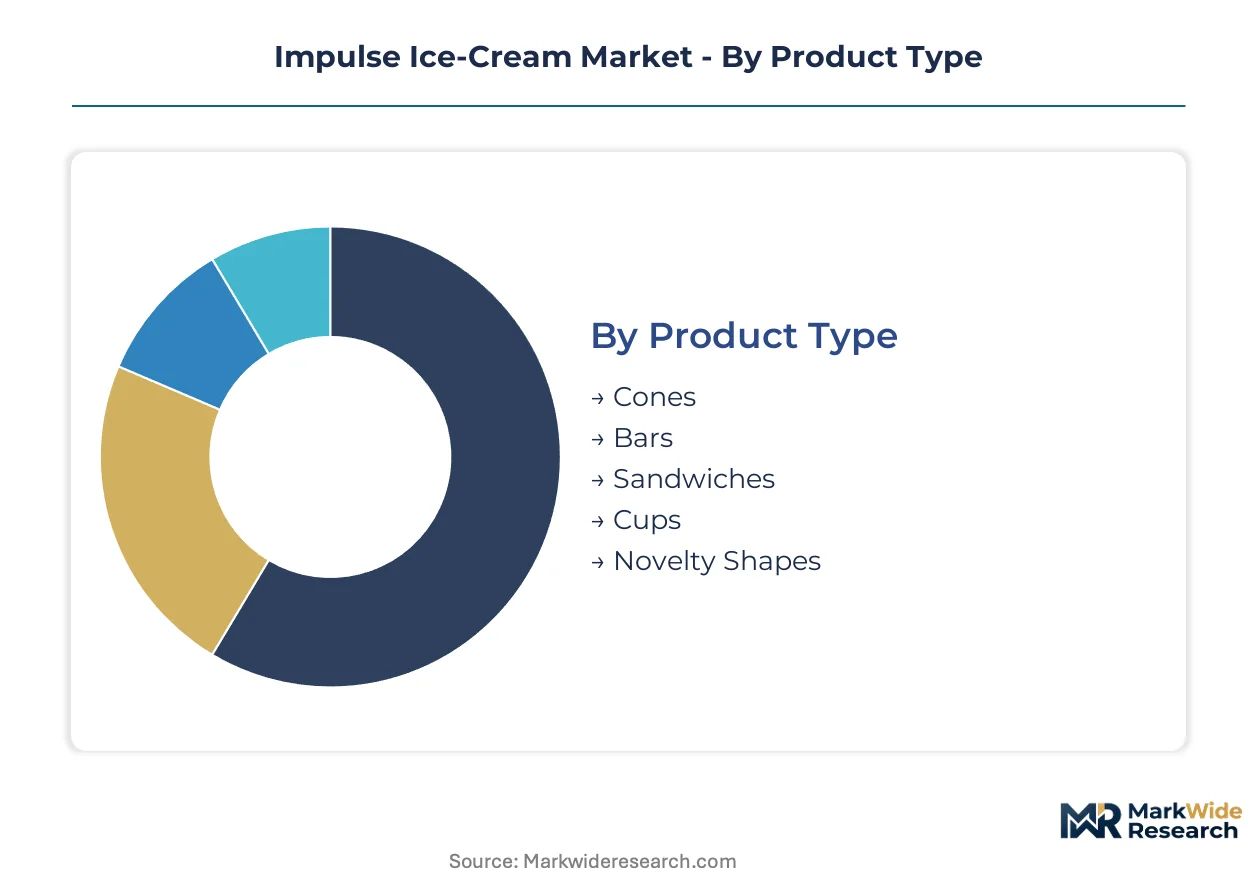
Impulse ice-cream segmentation reflects competing priorities between handheld portability, thermal protection, and route-to-market access. Manufacturers align formulation investments with freezer infrastructure ownership patterns across petrol forecourts and convenience chains.
Product Type:
Cost tier differentiation separates premium novelty formats from mass-market handheld cores, with margin structure varying sharply across manufacturing complexity and licensed content.
- Bars:Elongated frozen cores on sticks carry 10-16% milkfat formulations stabilized for thermal shock. Demand clusters in India and Brazil where street vendors and modern retail kiosks serve commuters without home freezer dependency.
- Cones:Pre-filled waffle or sugar cones with chocolate-lined barriers against moisture migration command the largest volume pools. Portability drives repeat purchase frequency in petrol forecourt placements across Germany and the UK.
- Sandwiches:Cookie or wafer layers encasing ice-cream slabs offer portion control with minimal drip risk.
- Cups:Single-serve tubs with peelable lids suit slower consumption occasions and spoon-based eating.
- Novelty Shapes:Licensed character molds extract premium pricing through entertainment tie-ins and seasonal display positioning.
Bars hold installed capacity. Novelty shapes are rotating up the share rankings.
Packaging Type:
Application requirements dictate material selection, with thermal protection and shelf presence competing for design priority in low-service retail environments.
- Stick Wrappers:Foil-laminated or waxed paper sleeves provide individual protection with minimal material cost. Dark-store fulfillment networks in urban India and São Paulo favor this format for insulated last-mile logistics efficiency.
- Cardboard Boxes:Secondary containment for novelty assortments enables seasonal display stacking and brand billboard effects.
- Paper Cups:Rolled-rim containers with polyethylene barriers suit soft-serve and scoop formats.
- Plastic Cups:Injection-molded tubs with resealable lids extend consumption windows.
- Multipacks:Cardboard sleeves containing 4-6 units bridge impulse and take-home occasions.
Stick wrappers hold installed capacity. Cardboard boxes are rotating up the share rankings.
Distribution Channel:
Customer type concentration varies by service level, with grab-and-go patterns favoring low-friction formats in transit-oriented locations.
- Convenience Stores:Narrowing shelf space prioritizes high-velocity SKUs with rapid replenishment cycles. Unilever leverages captive freezer infrastructure to dominate placement in Western European petrol forecourts.
- Online Retailers:Dark-store micro-fulfillment and route optimization enable 15-minute delivery promises previously impossible for frozen products.
- Gas Stations:Forecourt freezer densification in Germany and the UK awaits branded placement to block competitor access.
- Supermarkets:Dedicated frozen aisles with open coffin cases support planned purchase occasions.
- Street Vendors:Pushcart and kiosk networks in India drive volume through affordable single-serve formats without cold-chain capital requirements.
Convenience stores hold installed capacity. Online retailers are rotating up the share rankings.
End User:
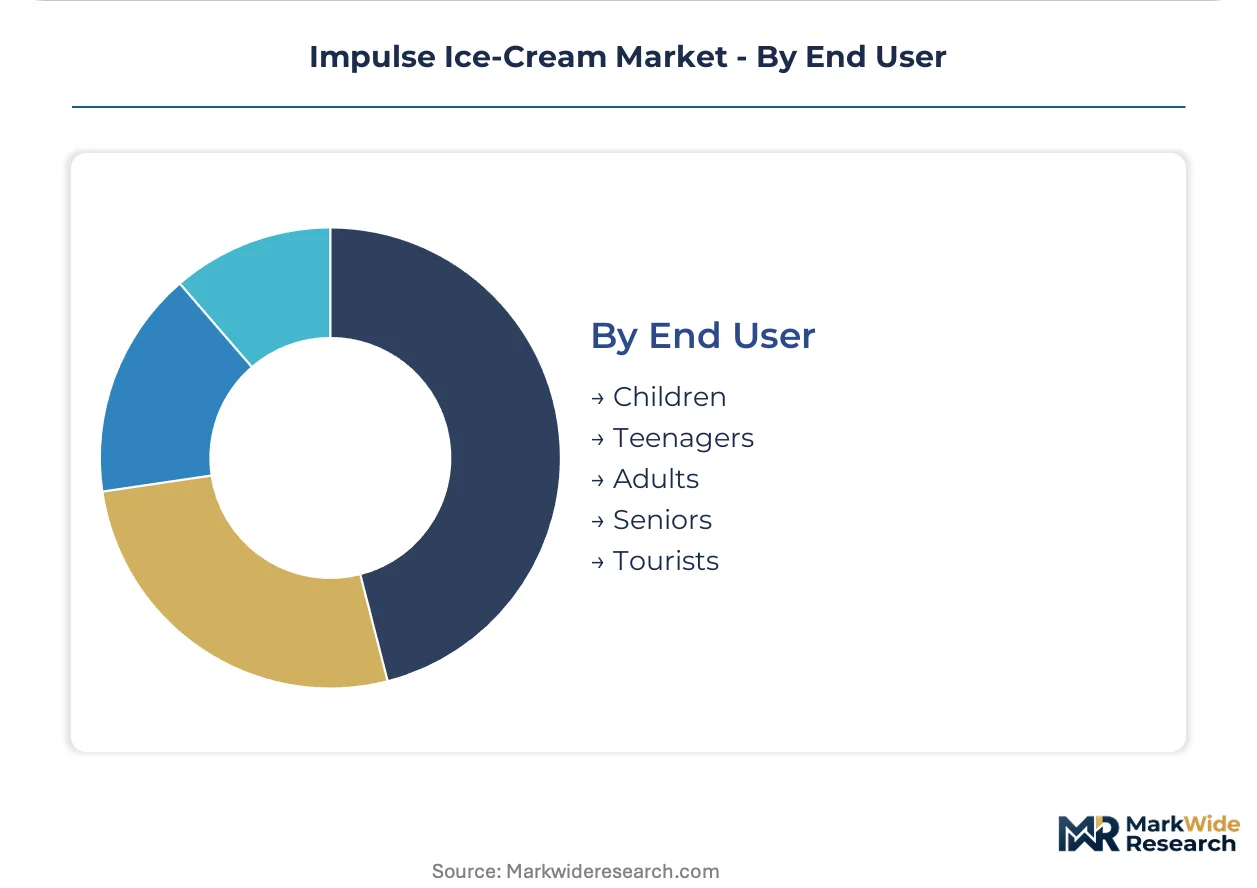
Volume concentration and margin capture diverge across age cohorts, with licensed content and health positioning segmenting appeal.
- Children:Character-driven novelty shapes command parental premium tolerance during seasonal display periods. FSSAI microbial limits for frozen desserts constrain imported formulation options in India.
- Adults:Clean-label stabilizer migration and reduced-sugar variants address formulation transparency demands under FDA and EFSA additive authorization constraints.
- Teenagers:Social sharing occasions favor photogenic formats with bold flavor profiles.
- Seniors:Smaller portion sizes and softer textures accommodate dietary restrictions.
- Tourists:Location-branded formats capture destination spending with minimal repeat purchase dependency.
Children hold installed capacity. Adults are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas refrigerant phasedown underwrites Western Europe's cold-chain modernization trajectory, while India's street-vendor distribution networks bypass formal freezer infrastructure entirely.
United States
Petrol forecourt freezer densification accelerates in Texas and California as convenience chains narrow frozen shelf space to high-velocity SKUs. EPA refrigerant phasedown schedules under the AIM Act raise retrofit costs for legacy dairy distributors. Chicago and Atlanta anchor impulse placement expansion through branded freezer infrastructure deployment.
Germany
Grab-and-go consumption patterns concentrate in Munich and Hamburg commuter corridors where Unilever leverages captive freezer assets. EFSA enforcement of additive authorizations under Regulation 1333/2008 constrains emulsifier formulation flexibility. Bavaria's dairy processing clusters supply stabilized 10-16% milkfat formulations for bar and cone production.
India
Street vendors and modern retail kiosks in Mumbai and Bangalore drive volume through affordable single-serve formats without home freezer dependency. FSSAI microbial limits for frozen desserts differentiate ice-cream from frozen confection standards, protecting domestic formulation investments. Maharashtra's cold-chain logistics networks expand to serve dark-store fulfillment in urban corridors.
Brazil
Urban commuters in São Paulo favor handheld portability from petrol forecourts and convenience chains. ANVISA's frozen dessert labeling requirements create compliance barriers for imported brands. The São Paulo-Rio de Janeiro axis anchors regional distribution infrastructure for bar and cone formats.
United Kingdom
Forecourt freezer placement competition intensifies across Shell and BP networks as retailers prioritize rapid replenishment cycles. REACH chemical registration requirements accelerate natural stabilizer migration in bar formulations. London's dark-store micro-fulfillment networks enable 15-minute delivery promises for online impulse orders.
Impulse Ice-Cream Market Key Industry Players
On the supply side, the industry is consolidating around freezer infrastructure ownership and licensed content partnerships. Three archetypes dominate: multinational FMCG conglomerates with captive cold-chain assets, regional dairy processors with formulation compliance expertise, and specialty novelty producers with entertainment licensing relationships. Competitive moves concentrate on petrol forecourt freezer densification and clean-label emulsifier reformulation to preempt regulatory enforcement.
Within the multinational conglomerate tier, Unilever Group and Nestle S.A. occupy positions defined by freezer infrastructure scale and brand portfolio breadth. General Mills represents the diversified food manufacturer archetype with controlled distribution partnerships. Vadilal Industries Limited anchors the India-focused regional specialist category with FSSAI compliance capabilities and street-vendor network access.
| Leading Market Players |
|---|
| Inspire Brands Inc. (Baskin-Robbins) |
| Turkey Hill Dairy |
| Unilever Group |
| IFFCO |
| Pure Ice Cream Co LLC |
| Nestle S.A. |
| Direct Wholesale Foods |
| Vadilal Industries Limited |
| General Mills |
| Others |
Cost & Logistics Intelligence
Maharashtra's dairy processing clusters anchor formulation supply for 10-16% milkfat bar and cone production, translating cold-chain infrastructure ownership into downstream pricing power for captive freezer networks across Indian urban corridors.
Pricing Analysis
Volume-discount tiering structures separate premium novelty formats with licensed entertainment tie-ins from mass-market handheld cores. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and brand recognition under FDA and EFSA additive authorization constraints. Cost compression in economy tiers intensifies as dairy input volatility squeezes margin predictability for 10-16% butterfat formulations. Street vendors and petrol forecourt operators exhibit highest price sensitivity, while seasonal novelty purchasers demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between India and EU dairy ingredient suppliers dominates supply chain risk planning for multinational stabilizer procurement. Manufacturing concentrates in India, Germany, and Brazil, drawing from milkfat solids, emulsifier systems, and wafer cone inputs. Single-source vulnerability in natural guar and locust bean gum sourcing threatens clean-label reformulation timelines. Distribution runs through captive freezer infrastructure at petrol forecourts and convenience chains, with dark-store micro-fulfillment emerging as an alternative last-mile structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigeration technician scarcity constrains route-to-market expansion for brands lacking legacy dairy distributor relationships, compressing competitive access to formal cold-chain networks.
For Market Incumbents: Insulate margin pools by accelerating petrol forecourt freezer densification in Germany and the UK before competitor placement blocks access. Prioritize backward integration into natural stabilizer supply to preempt EFSA enforcement actions on synthetic emulsifier authorizations. Defend against dark-store fulfillment entrants by tightening controlled distribution partnerships with convenience chains. For New Entrants and Emerging Players: Brazil's São Paulo-Rio corridor offers underpenetrated forecourt freezer real estate outside Unilever's captive infrastructure footprint. Target street-vendor networks in Indian tier-2 cities where FSSAI compliance capabilities differentiate domestic formulation investments. Enter through licensed character partnerships that command seasonal display positioning unavailable to established bar formats. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional dairy processors with captive cold-chain assets and FSSAI compliance expertise. Long-term viability over the projection horizon favors acquisition targets with freezer infrastructure ownership rather than pure formulation capabilities. Monitor dark-store fulfillment network expansion in urban India as an inflection indicator for channel displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Emulsifier Migration | Natural stabilizer adoption preempts EFSA Regulation 1333/2008 enforcement actions. |
| Petrol Forecourt Freezer Densification | Unoccupied real estate in Germany and UK blocks competitor route-to-market access. |
| Licensed Entertainment Partnership | Character tie-ins command premium positioning in seasonal convenience displays. |
| Dark-Store Micro-Fulfillment | Insulated last-mile logistics enables 15-minute delivery promises in urban India. |
| FSSAI Compliance Investment | Microbial limit differentiation protects domestic formulation against imported brands. |
Research Approach
Operator-level perspectives from brand managers, category buyers at convenience chains, cold-chain logistics directors, and street-vendor network coordinators anchored the qualitative base. Secondary validation drew from FSSAI regulatory filings, EU F-Gas Regulation implementation schedules, EFSA additive authorization databases, and Nielsen retail audit data across frozen dessert categories. Bottom-up volume modeling and top-down value reconciliation provided cross-check triangulation.
Scenario-bracketing framed low, base, and high cases across the analysis window. Segmentation dimensions included product type, packaging format, distribution channel, and end-user age cohort. CAGRs derived from historical trajectory analysis and forward-looking input cost assumptions. Modeled inputs incorporated refrigerant phasedown cost schedules, dairy commodity futures curves, and dark-store fulfillment penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive freezer infrastructure deployment by emerging regional dairy processors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
United States Online Grocery Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Canned Food Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Hummus Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Non-Fried Instant Noodles Market