
 Europe Eggs Market | 2026-2036
Europe Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Eggs Market Foresight
The EU Green Deal is restructuring capital deployment across layer farms and grading facilities. Interovo Egg Group BV leverages its Dutch processing network to supply liquid egg volumes into industrial bakery channels. AVEC Group anchors French production through cooperative member farms with dedicated cage-free conversion timelines. Lohmann Tierzucht dominates genetics supply, positioning its breeding stock as the foundation stock for European brown-egg production systems.
Eggs comprise the reproductive bodies of domesticated Gallus gallus domesticus, consisting of shell, albumen, and yolk with standardized weight grades from 53g to over 73g, serving as complete protein sources and functional ingredients in emulsification and leavening. Fresh eggs retain the largest volume position across European retail, though margin pools are deepening in liquid and powdered formats where food processing buyers consolidate procurement. Organic eggs represent the fastest-growing product type, driven by German and Austrian retail chains that have converted entire shell-egg assortments to certified organic and free-range standards.
EFSA sets maximum residue limits and Salmonella control protocols that shape flock management and testing costs, while the EU Green Deal's Farm to Fork targets on pesticide reduction and animal welfare rewrite stocking density rules for enriched and aviary systems. National regulators including Germany's BMEL and France's DGAL enforce cage-free transition deadlines that vary by member state, creating asymmetric compliance calendars. Stakeholders must monitor divergence between national welfare enforcement timelines and the pace of retail private-label conversion to avoid stranded capacity in conventional housing systems.
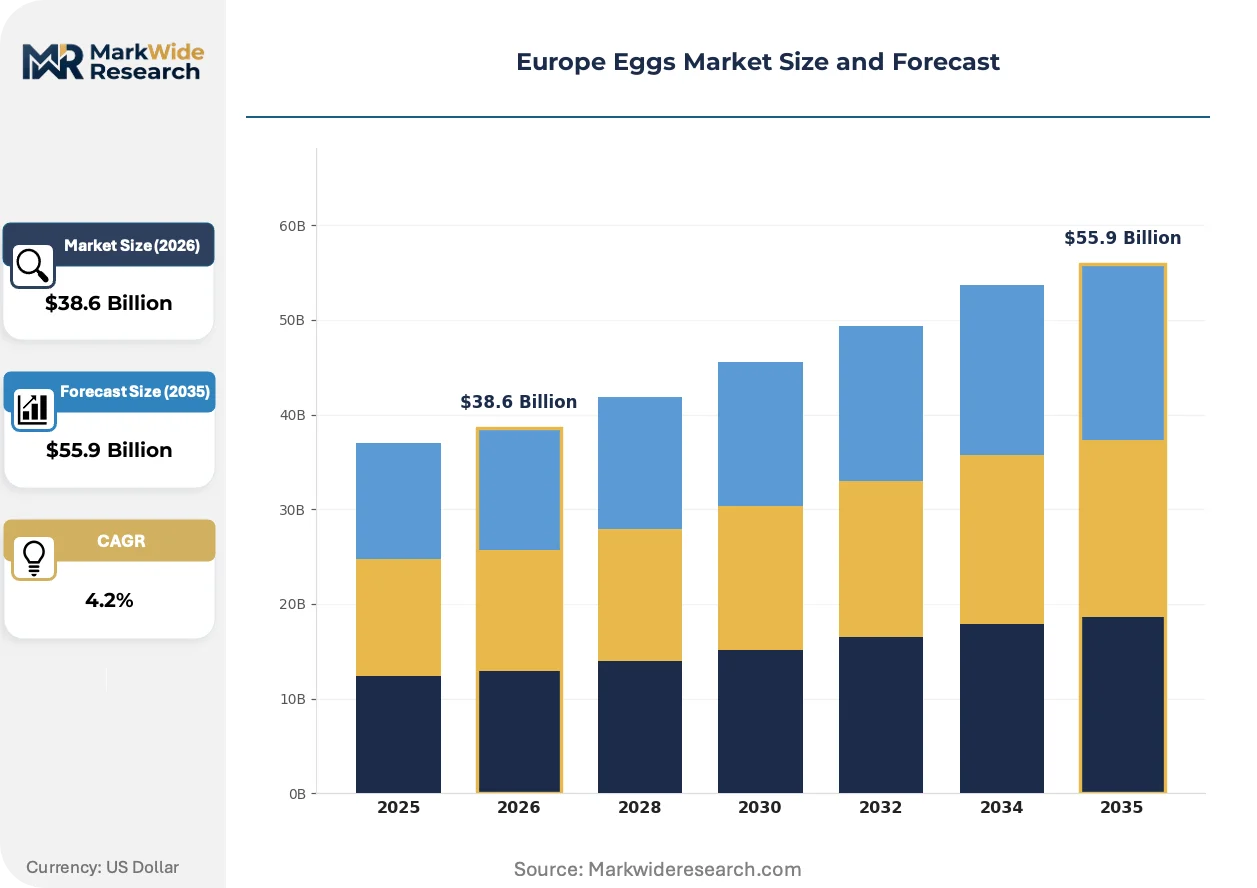
Market Dynamics
The EU Green Deal and Farm to Fork Strategy are forcing capital reallocation across European layer housing, with cage-free mandates compressing conversion timelines and carbon disclosure rules rewriting procurement specifications for industrial egg buyers.
Growth Catalysts
- EFSA Salmonella Control Protocols:Mandatory testing regimes are consolidating flock management standards, driving investment in automated monitoring systems across Dutch and German production clusters.
- Industrial Bakery Procurement:Food processing buyers are consolidating liquid and powdered egg volumes, creating dedicated supply contracts that favor integrated grading and breaking facilities.
- German Retail Organic Conversion:Discounters and supermarket chains have converted entire shell-egg assortments to certified organic, pulling upstream investment into aviary and free-range systems.
Market Restraints
- Feed Input Volatility:Soybean and grain price swings compress layer farm margins, particularly for smaller cooperative members in France and Spain lacking forward-contract coverage.
- Genetic Supply Concentration:Breeding stock availability depends on a narrow base of genetics suppliers, creating vulnerability for brown-egg production systems across Northern Europe.
- Regulatory Asymmetry:Divergent national cage-free transition deadlines between Germany's BMEL and France's DGAL create stranded capacity risk for producers with cross-border operations.
Strategic Opportunities
- Carbon Footprint Labeling:The EU Green Deal's disclosure mandates create first-mover advantage for layer farms with verified low-emission housing and renewable energy integration.
- Eastern European Processing Gap:Poland and Romania lack integrated breaking capacity, opening white space for liquid egg facilities serving regional ready-meal manufacturers.
- Precision Livestock Convergence:Sensor networks and machine vision for flock monitoring are converging with automated feeding systems, enabling predictive health management at scale.
Industry Challenges
- Veterinary Workforce Scarcity:Specialized poultry health expertise is concentrating in Netherlands and Denmark, leaving peripheral regions dependent on remote diagnostic services.
- Aviary System Capex Burden:Cage-free conversion requires capital deployment per bird that exceeds legacy enriched cage infrastructure by multiples, straining cooperative balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Eggs Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Eggs, Powdered Eggs, Liquid Eggs, Organic Eggs End User: Households, Restaurants, Bakeries, Food Processing Distribution Channel: Supermarkets, Online Retail, Wholesalers, Farmers' Markets Packaging Type: Cartons, Trays, Bulk Packaging, Eco-friendly Packaging |
| Companies Covered | Global Eggs, El Granjero, Interovo Egg Group BV, Vencomatic Group, AVEC Group, OVOBEL, Hevo Group, Lohmann Tierzucht, IGRECA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Eggs Market Shifts & Advancements
Automation in grading and breaking facilities is compressing labor dependency while precision livestock technologies rewrite flock management economics across European production clusters.
In-ovo sexing technology is converging with automated hatchery systems to eliminate male chick culling, a practice German and French retailers have committed to phasing out ahead of regulatory mandates. Industrial hatcheries in the Netherlands are retrofitting infrastructure to accommodate optical and molecular detection methods. This convergence is compressing the timeline for welfare-compliant supply chains and reshaping capital allocation across breeding and hatchery operations.
The EU Green Deal's Farm to Fork pesticide reduction targets are rewriting feed crop specifications, with EFSA residue limits tightening for soy and maize imports. Layer farms are responding by sourcing certified deforestation-free feed or investing in regional protein crop cultivation. German producers face the most immediate compliance pressure, with BMEL enforcement timelines running ahead of neighboring member states.
Discounter private-label buyers are consolidating shell-egg procurement through direct farm partnerships, bypassing traditional wholesale intermediaries. Aldi and Lidl in Germany and Austria have converted entire egg categories to fixed organic-free-range specifications, locking suppliers into long-term volume commitments. This channel compression is most advanced in German-speaking markets, where retail concentration enables rapid assortment standardization.
Europe Eggs Market Segmentation
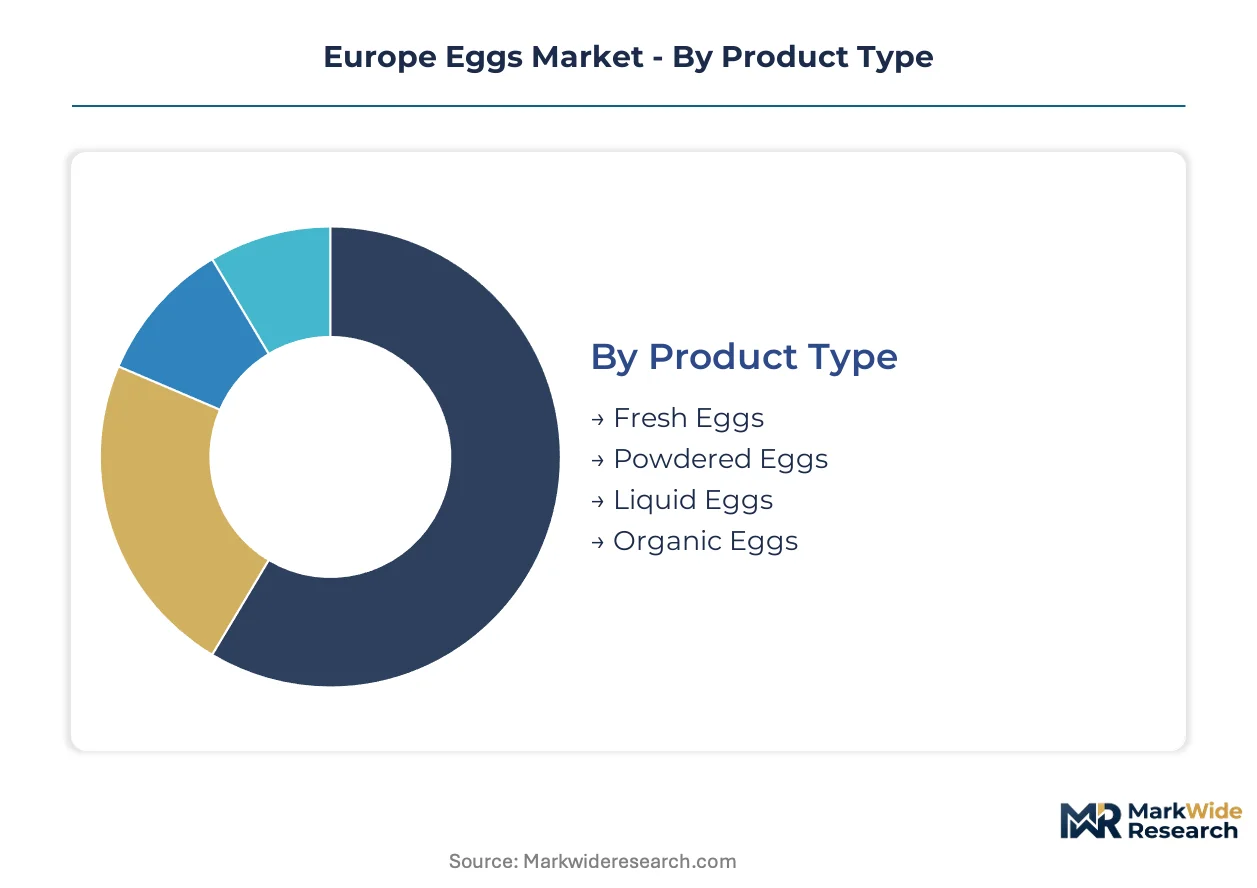
Segmentation in the Europe Eggs Market tracks how divergent buyer requirements split procurement across format, channel, and certification grade. Food processors prioritize liquid and powdered volumes for operational efficiency, while retail chains drive welfare-certified shell-egg specifications that reshape upstream housing investments.
Product Type:
Buyers differentiate primarily by shelf-life requirements and functional application in recipes or industrial formulations.
- Fresh Eggs:Shell-intact table eggs graded by weight from 53g to over 73g, retaining albumen viscosity critical for poaching and emulsification. German and French retail chains dominate procurement, with discounters converting entire assortments to cage-free and organic specifications under BMEL and DGAL enforcement timelines.
- Organic Eggs:Certified to EU organic regulations with mandatory outdoor access and feed restrictions. Austrian and German supermarkets have pulled entire shell-egg categories into this segment, forcing cooperative farms to accelerate aviary system conversions ahead of neighboring member states.
- Powdered Eggs:Spray-dried whole egg, white, or yolk fractions with extended stability for military and emergency food reserves.
- Liquid Eggs:Pasteurized whole egg or separated fractions delivered in bag-in-box or tanker formats for industrial bakeries.
Fresh eggs lead volumes today; organic eggs are gaining share fastest.
End User:
Volume concentration varies sharply between fragmented household purchasing and consolidated food manufacturing contracts.
- Food Processing:Industrial bakeries and ready-meal manufacturers procure liquid and powdered formats in dedicated supply agreements. Dutch integrated grading facilities serve pan-European channels, with breaking capacity concentrated near Rotterdam and Venlo logistics hubs.
- Bakeries:Artisan and industrial producers source shell eggs for aeration properties or liquid volumes for batch consistency. French patisserie chains maintain direct farm partnerships in Brittany and Pays de la Loire, bypassing wholesale intermediaries for specific yolk color specifications.
- Households:Retail shoppers purchasing shell eggs through supermarkets or farmers' markets, with welfare certification increasingly decisive.
- Restaurants:Foodservice operators balancing shell-egg freshness against liquid egg labor efficiency in high-volume kitchens.
Food processing commands the largest contract volumes; bakeries are expanding procurement most rapidly.
Distribution Channel:
Channel selection determines price transparency and certification verification access for downstream buyers.
- Supermarkets:Discounters and full-service chains dominate shell-egg volume, with Aldi and Lidl in German-speaking markets enforcing fixed organic-free-range specifications. Direct farm partnerships are displacing traditional wholesale layers, compressing margin pools for intermediaries.
- Online Retail:Subscription and on-demand platforms gaining traction in urban Netherlands and Scandinavian markets, though cold-chain requirements limit penetration.
- Wholesalers:Traditional intermediaries serving independent retailers and foodservice, losing share to direct sourcing.
- Farmers' Markets:Local production sales with traceability advantages in rural France, Spain, and Italy.
Supermarkets retain channel dominance; online retail is climbing the fastest.
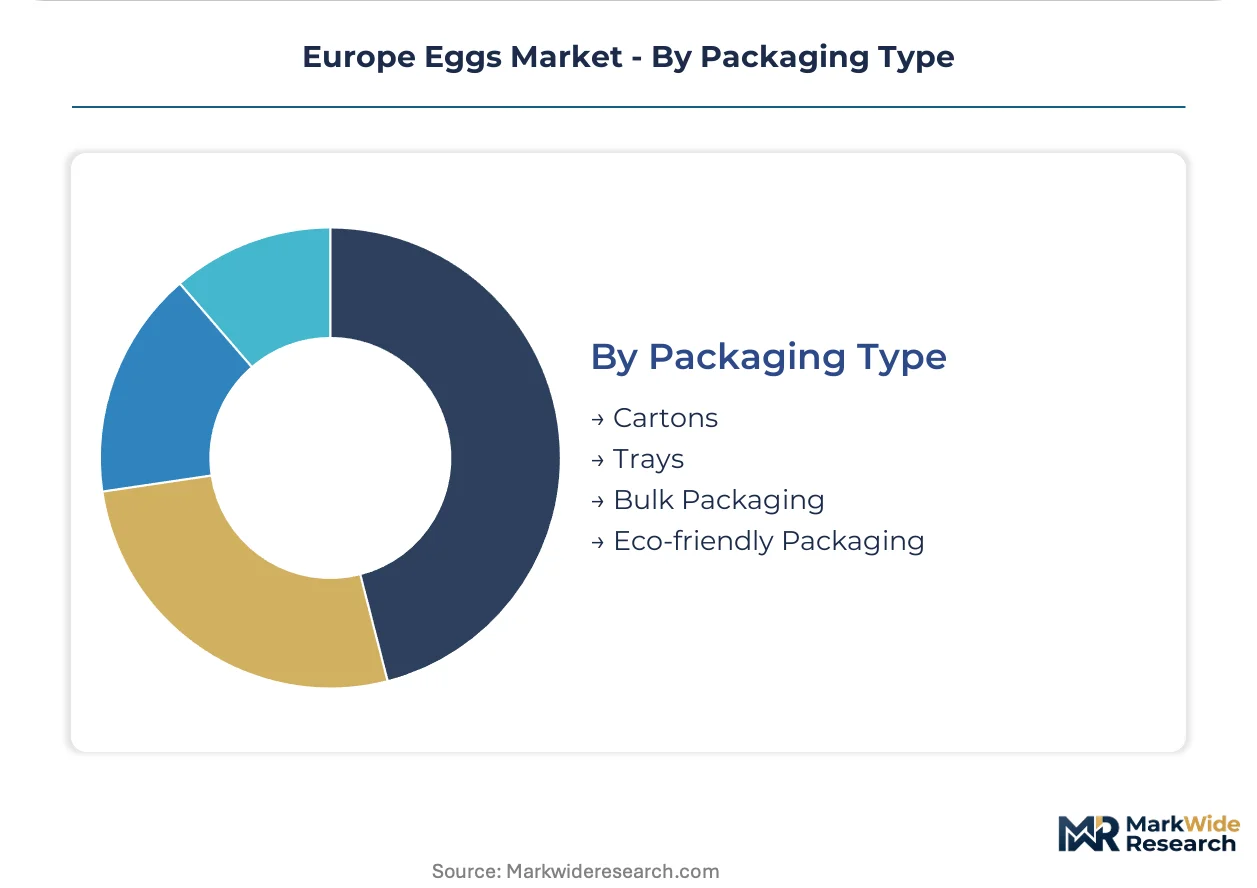
Packaging Type:
Sustainability mandates and logistics efficiency drive divergent material specifications across retail and industrial segments.
- Cartons:Molded pulp containers standard for retail shell-egg presentation, with recycled fiber content rising under EU Green Deal circular economy targets. German retailers now require minimum post-consumer recycled ratios in private-label specifications.
- Eco-friendly Packaging:Biodegradable or plastic-free alternatives responding to Farm to Fork Strategy waste reduction goals. Dutch producers are piloting potato-starch-based trays for organic egg lines, with retail trials in Albert Heijn and Jumbo chains.
- Trays:Reusable plastic or corrugated formats for foodservice and bakery bulk procurement.
- Bulk Packaging:Loose-fill containers for industrial liquid egg tanker transfers and powder sacks.
Cartons lead absolute volume; eco-friendly packaging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary expertise and genetics research capacity concentrate in Dutch and Danish university clusters, anchoring Europe's layer health management and breeding stock development. This technical workforce distribution shapes where precision livestock technologies deploy first and where regulatory enforcement tightens fastest.
Germany
Discounter chains Aldi and Lidl have converted entire shell-egg assortments to organic-free-range specifications, pulling cooperative farms into accelerated aviary conversions. BMEL enforcement timelines for cage-free mandates run ahead of neighboring member states, creating compliance pressure on cross-border operations. Lower Saxony's intensive poultry belt around Oldenburg hosts integrated grading facilities serving pan-European bakery supply chains.
Netherlands
Rotterdam and Venlo logistics hubs anchor liquid egg breaking capacity for industrial food processing buyers across the continent. EFSA Salmonella control protocols drive automated monitoring system deployment across Dutch production clusters. Wageningen University's veterinary research corridor supplies precision livestock expertise to layer farms transitioning to cage-free housing systems.
France
DGAL cage-free transition deadlines lag German enforcement calendars, creating asymmetric compliance windows for producers with cross-border flocks. Brittany and Pays de la Loire maintain direct farm partnerships with patisserie chains seeking specific yolk color specifications. AVEC Group cooperative members anchor brown-egg production through dedicated conversion timelines to enriched and aviary systems.
Poland
Ready-meal manufacturers in Warsaw and Łódź industrial zones source shell eggs from domestic layer farms lacking integrated breaking capacity. EU Green Deal carbon disclosure rules are rewriting procurement specifications for food processing buyers serving Eastern European markets. Regional protein crop cultivation investments are expanding to reduce feed import dependency under Farm to Fork pesticide reduction targets.
Spain
Andalusian and Catalonian layer farms face feed input volatility from soybean price swings, compressing margins for smaller cooperative members lacking forward-contract coverage. National welfare enforcement timelines for cage-free conversion trail Northern European schedules, extending operational windows for conventional housing systems. Valencia's food processing corridor imports liquid egg volumes from Dutch breaking facilities to supply regional bakery manufacturers.
Europe Eggs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's egg value chain, with cooperative structures dominating production and integrated processors controlling industrial formats. Market structure tilts toward consolidation in genetics supply and liquid egg processing, while shell-egg retail remains fragmented across national cooperative networks. Three archetypes prevail: genetics suppliers controlling breeding stock, integrated processors with captive breaking capacity, and cooperative production alliances serving retail private-label programs. Capacity expansion and direct farm partnerships with discounter chains represent the dominant competitive moves reshaping procurement relationships.
Among Dutch-integrated specialists, Interovo Egg Group BV and Vencomatic Group exemplify the processor archetype with grading and breaking infrastructure positioned near Rotterdam logistics hubs. French cooperative structures represented by AVEC Group anchor brown-egg production systems through member farm networks. German genetics supplier Lohmann Tierzucht occupies a foundational position in European breeding stock supply, with its layer lines underpinning production systems across Northern European markets.
| Leading Market Players |
|---|
| Global Eggs |
| El Granjero |
| Interovo Egg Group BV |
| Vencomatic Group |
| AVEC Group |
| OVOBEL |
| Hevo Group |
| Lohmann Tierzucht |
| IGRECA |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between organic-free-range shell eggs and commodity cage-housed volumes manifests in parallel supply chain configurations across Europe. German discounters enforce fixed organic specifications that compress procurement into long-term farm partnerships, while conventional eggs flow through volatile spot markets vulnerable to feed cost swings.
Pricing Analysis
Shell-egg and liquid-egg format splits dominate pricing architecture across European markets. Three-tier pricing structure across organic, free-range, and cage-housed grades tracks EFSA welfare certification levels and BMEL enforcement calendars. Cost compression in conventional shell-egg tiers is intensifying because soybean and grain price volatility transmits directly to layer farm margins. Food processing buyers exhibit lowest price sensitivity due to volume commitments and functional specifications, while household retail shoppers demonstrate highest elasticity to welfare-label premiums.
Supply Chain Analysis
EU Green Deal domestic-content mandates for deforestation-free feed are reshaping sourcing patterns across layer farm networks. Supply concentration rests on Netherlands, Germany, and France for integrated grading and breaking capacity. Raw material dependencies center on Brazilian and Argentinian soybean meal, Ukrainian grain, and domestic protein crop cultivation. Single-source vulnerability runs through genetics supply where Lohmann Tierzucht breeding stock anchors Northern European brown-egg production. Distribution runs through Rotterdam and Venlo logistics hubs serving pan-European food processing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
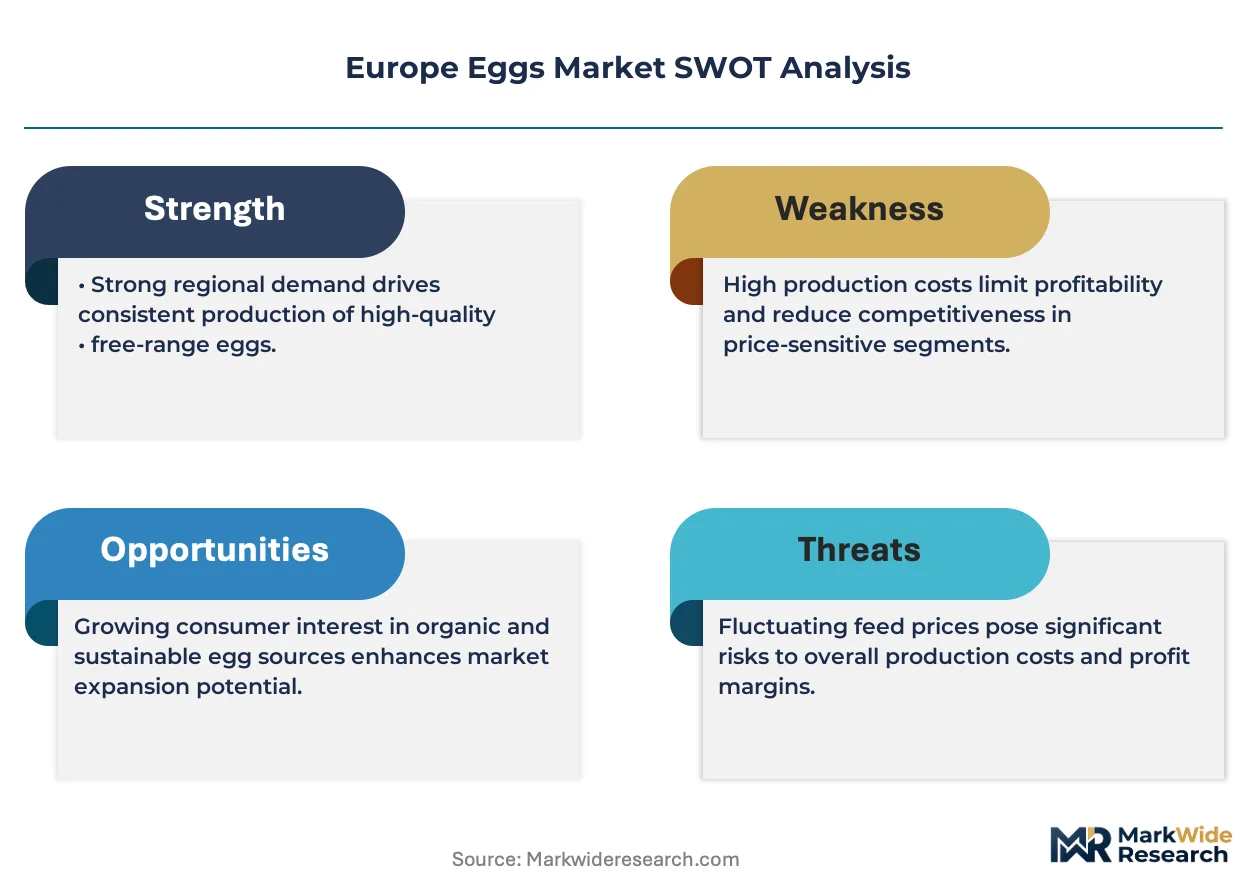
Europe's egg market functions as a geographic-arbitrage play where Dutch processing infrastructure and German retail premiumization create margin extraction opportunities against Eastern European supply gaps.
For Market Incumbents: Deploy precision livestock technology as the primary defensive lever. Invest in sensor networks and automated monitoring systems to reduce veterinary labor dependency and meet EFSA Salmonella protocols. Build backward integration into regional protein crop cultivation to hedge feed import volatility under Farm to Fork pesticide reduction targets. Channel control through direct farm partnerships with Aldi and Lidl protects against wholesale margin compression. For New Entrants and Emerging Players: Discounter private-label buyers represent the most penetrable channel partner type for new market access. Target Poland and Romania where integrated breaking capacity shortages create white space for liquid egg facilities serving regional ready-meal manufacturers. Exploit asymmetric compliance calendars between German BMEL and French DGAL enforcement timelines to position cage-free conversion services. A go-to-market angle anchored in carbon footprint verification addresses EU Green Deal disclosure mandates ahead of incumbent adaptation. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Dutch and German processors possessing captive breaking infrastructure and renewable energy integration. Long-term viability over the coming decade hinges on positioning for cage-free mandate completion and carbon-label premium capture. Acquisition targets should screen for farms with verified low-emission housing and direct retail partnerships. The signal to watch is divergence between national welfare enforcement timelines and retail private-label conversion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Cage-Free Housing Conversion | BMEL and DGAL deadlines force capital deployment ahead of stranded capacity risk. |
| Backward Integration into Feed Crops | Regional protein cultivation reduces dependency on Brazilian soybean imports under Farm to Fork targets. |
| Precision Livestock Technology Deployment | Sensor networks and machine vision enable predictive health management at Dutch production scale. |
| Carbon Footprint Verification Program | EU Green Deal disclosure mandates create first-mover advantage for low-emission layer farms. |
| Liquid Egg Processing Capacity Expansion | Poland and Romania processing gaps open white space for regional ready-meal supply. |
Research Methodology
Bottom-up food processing and retail procurement modeling reconciled against top-down layer farm capacity tracking forms the analytical core of this study. Primary interviews with layer farm managers, cooperative procurement directors, food processing buyers, retail category managers, and veterinary health specialists combined with secondary validation from EFSA regulatory filings, EU trade statistics, national agricultural ministry reports, and industry cooperative disclosures. Triangulation across stakeholder inputs and documentary sources ensures coverage of both supply-side capacity constraints and demand-side specification evolution.
Historical trendline analysis of shell-egg and liquid-egg volume trajectories informed projection construction across the modeling period. Segmentation dimensions modeled include product format, certification grade, end-use application, and regional production cluster. CAGRs derived from trend extrapolation adjusted for regulatory enforcement calendars and feed cost volatility assumptions. Industry-specific forecast inputs incorporated cage-free conversion timelines and carbon disclosure mandate implementation pace.
Revisions become necessary when EFSA protocol amendments, national welfare enforcement acceleration, or feed commodity price shocks materialize outside baseline assumptions. Forecasts reflect documented assumptions regarding retail private-label conversion rates and cooperative capital access. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Black Sapote Market