
 Africa Cashew Market | 2026-2036
Africa Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Cashew Market Outlook
Organic and fair-trade certification cycles are redrawing competitive boundaries across the Africa Cashew Market. Olam International leverages its vertically integrated supply chain from farm gate to export terminal across Côte d'Ivoire and Nigeria. Wilmar International anchors its position through large-scale kernel processing capacity in West African industrial zones. ARISE Industrial Integrated Platforms differentiates by developing dedicated agro-processing parks with captive power and logistics infrastructure.
Africa cashew comprises the seed and kernel of Anacardium occidentale, typically containing 47% fat and 21% protein by weight, with commercial grades determined by kernel size, color, and defect count under the Association of Food Industries standard. The crop serves as a critical input for confectionery, nut butter production, and premium snack formulations across European and North American buyer markets. Cashew kernels command the dominant margin pool within product type segmentation due to established demand from European confectioners and Asian snack manufacturers. Raw cashew nuts retain structural importance as the foundational trade commodity, though value capture remains concentrated at the processing stage rather than the farm gate.
Côte d'Ivoire's national cashew regulator enforces export quotas on raw nut shipments to incentivize domestic processing, while Nigeria's food safety agency mandates aflatoxin certification for kernel exports to the European Union under EFSA-aligned standards. The Economic Community of West African States harmonization framework for agricultural product standards is gradually reducing cross-border trade friction for processed cashew goods. Stakeholders must monitor how rapidly local processing capacity expands relative to export quota enforcement, as this balance will determine whether margin capture shifts from traders to domestic processors.
Market Dynamics
Domestic processing mandates across West Africa are restructuring margin capture away from raw nut traders toward integrated processors, with regulatory enforcement tightening faster than local capacity expansion.
Growth Catalysts
- ECOWAS Standards Harmonization:The regional framework for agricultural product standards reduces cross-border friction for processed cashew goods, accelerating intra-regional trade velocity.
- Confectionery Demand Pull:European confectioners are expanding kernel procurement from African origins to diversify supply away from Vietnamese and Indian processors.
- Kogi State Processing Cluster:Multiple integrated facilities coming online in Nigeria's central belt create captive demand for raw nut supply chains.
Market Restraints
- Raw Nut Export Quotas:Côte d'Ivoire's enforcement of shipment limits creates supply bottlenecks for traders dependent on unprocessed commodity arbitrage.
- Aflatoxin Testing Costs:EFSA-aligned certification requirements for EU-bound kernels impose fixed compliance burdens that disadvantage smaller processors lacking laboratory infrastructure.
- Captive Power Deficits:Processing facilities outside dedicated agro-industrial parks face unreliable grid electricity, forcing diesel generator dependence that erodes kernel margin economics.
Strategic Opportunities
- Fair-Trade Certification Premiums:Organic and ethical sourcing credentials command price differentiation in North American specialty snack channels.
- Nut Butter Formulation Expansion:Plant-based protein trends in European food manufacturing are opening industrial kernel demand outside traditional confectionery.
- ARISE Park Infrastructure:Dedicated agro-processing zones with bundled logistics and energy utilities lower barrier-to-entry for mid-scale processors.
Industry Challenges
- Skilled Roasting Technician Scarcity:Kernel processing quality depends on experienced operators for moisture control and color sorting, with training pipelines lagging facility expansion.
- Integrated Facility Capex Burden:Full-line investments in steaming, shelling, and peeling equipment require 5-7 year payback periods under current working capital constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Cashew Market |
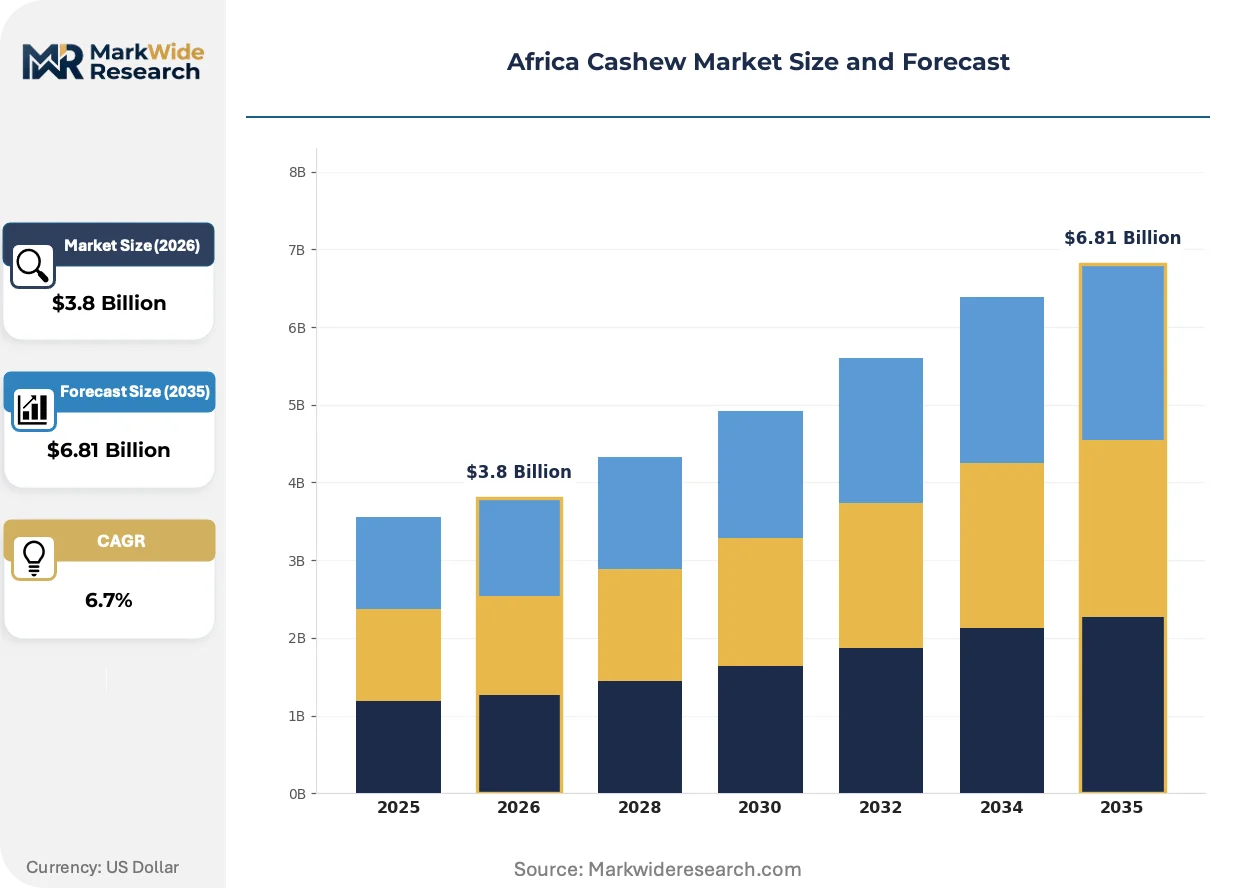
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashew Nuts, Cashew Kernels, Cashew Butter, Cashew Flour End User: Food Industry, Snack Manufacturers, Health Food Stores, Export Markets Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales Processing Type: Raw, Roasted, Salted, Spiced |
| Companies Covered | Ivory Coast Cajou, Amama Farms, Olam International, Glo-Djigbé Industrial Zone, ARISE Industrial Integrated Platforms, Wilmar International, Asian Trading International, Golden Africa, Touton, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Cashew Market Strategic Shifts
Processing technology and regulatory alignment are converging to reshape competitive boundaries, with automation and compliance infrastructure becoming primary differentiators rather than scale alone.
Steam-based shelling systems is supplanting traditional open-fire roasting across Nigerian and Ivorian processing facilities. Mid-scale operators in the Kogi cluster are adopting Chinese-origin steam boilers to reduce kernel breakage rates and improve color consistency. The technology is supplanting artisanal methods that previously dominated the 500-2000 ton annual processing tier, compressing quality variation and enabling EFSA-aligned certification.
EFSA-aligned aflatoxin testing protocols are mandating laboratory investment ahead of export clearance. Nigeria's food safety agency now requires documented B1-level certification for EU-bound shipments, forcing processors to either build in-house testing capacity or contract accredited third-party services. Smallholder-aggregating traders without laboratory partnerships are exiting the kernel export channel entirely.
Snack manufacturers are consolidating supplier relationships around vertically integrated African processors with captive raw nut supply. Procurement teams at European and North American confectioners are reducing vendor counts and extending contract durations to secure traceability documentation. This concentration is most visible in German and Dutch buying offices, where sustainability audit requirements now favor integrated Ivorian and Nigerian suppliers over Asian re-exporters.
Africa Cashew Market Segmentation
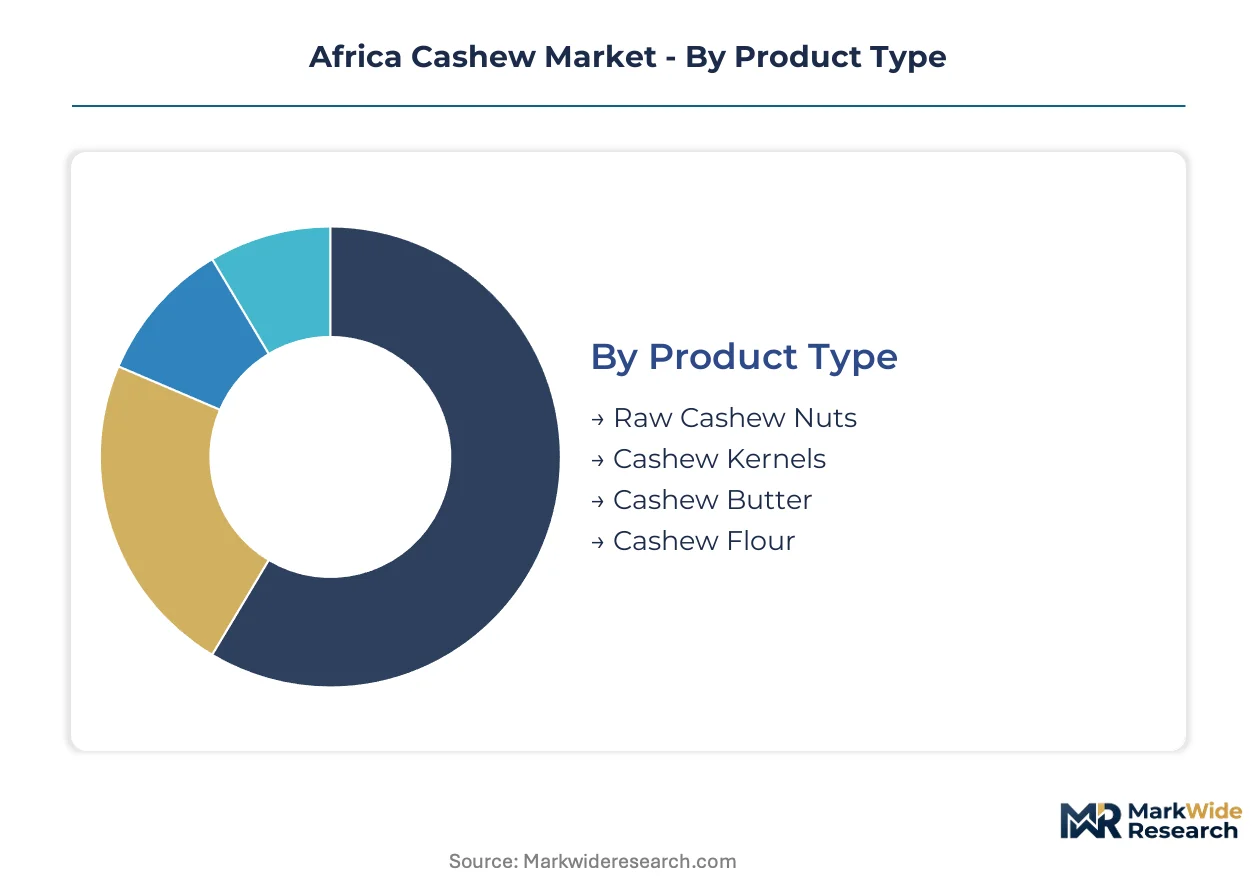
Product form determines margin capture and regulatory exposure across the Africa Cashew Market. Channel selection shapes working capital intensity and certification requirements for processors operating under ECOWAS harmonization.
Product Type:
Raw nuts flow through commodity traders while processed derivatives reach confectioners through specialized distributors.
- Cashew Kernels:Graded by size, color, and defect count under Association of Food Industries standards, these contain 47% fat and 21% protein. European confectioners in Germany and the Netherlands are consolidating procurement around Ivorian and Nigerian integrated processors with traceability documentation. Kernel margin pools concentrate at the processing stage rather than farm gate.
- Raw Cashew Nuts:The foundational trade commodity serves as critical input for domestic processing expansion. Côte d'Ivoire's national cashew regulator enforces export quotas to incentivize local value addition, creating supply bottlenecks for traders dependent on unprocessed arbitrage.
- Cashew Butter:Plant-based protein trends in European food manufacturing are opening industrial demand outside traditional confectionery channels.
- Cashew Flour:Gluten-free formulation applications in premium snack segments command specialty pricing through health food distributors.
Cashew kernels dominate installed base. Raw cashew nuts is where expansion concentrates as processing capacity scales.
End User:
Application requirements split between bulk industrial procurement and traceable specialty sourcing.
- Food Industry:Confectionery manufacturers require EFSA-aligned aflatoxin certification for EU-bound shipments, favoring processors with in-house laboratory infrastructure over smallholder-aggregating traders.
- Snack Manufacturers:West African producers are scaling purchases of value-added products, with procurement teams extending contract durations to secure supply continuity from integrated origins.
- Health Food Stores:Organic and fair-trade credentials command price differentiation in North American specialty channels.
- Export Markets:Asian snack manufacturers remain significant buyers, though European offices are diversifying supply away from Vietnamese and Indian re-exporters.
Export markets hold the largest volume share. Snack manufacturers are gaining share fastest.
Distribution Channel:
Channel economics vary sharply between working capital-heavy wholesale and certification-intensive direct relationships.
- Wholesale:Aggregators in Abidjan and Lagos coordinate bulk movements to Asian processors, though ECOWAS harmonization is gradually reducing cross-border friction for processed goods.
- Direct Sales:European confectioners are reducing vendor counts and requiring sustainability audit documentation, concentrating procurement around vertically integrated Ivorian suppliers with captive raw nut supply.
- Retail:Domestic West African markets absorb lower-grade kernels and by-products from processing operations.
- E-commerce:Specialty nut butter and organic flour segments reach North American consumers through direct-to-consumer platforms.
Wholesale channels handle the greatest tonnage. Direct sales is climbing the fastest as traceability requirements tighten.
Processing Type:
Technology choice determines breakage rates, color consistency, and certification eligibility for export markets.
- Raw:Unprocessed kernels retain maximum flexibility for industrial buyers requiring custom roasting specifications.
- Roasted:Steam-based shelling systems are supplanting traditional open-fire methods across Nigerian and Ivorian facilities, with Kogi State operators adopting Chinese-origin boilers to improve quality consistency.
- Salted:Snack-ready formulations command premium positioning through retail and foodservice channels.
- Spiced:Regional flavor profiles target intra-African markets and diaspora consumers in Europe.
Roasted processing dominates current capacity. Raw processing retains structural importance for industrial flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export quota enforcement and processing incentive programs are redrawing competitive boundaries across West African cashew origins. National regulators in Côte d'Ivoire and Nigeria are tightening compliance frameworks faster than local capacity expands.
Côte d'Ivoire
European confectioners in Germany and the Netherlands are consolidating procurement around Ivorian integrated processors with traceability documentation. The national cashew regulator enforces raw nut export quotas to incentivize domestic value addition. The Glo-Djigbé Industrial Zone outside Abidjan hosts multiple steaming and shelling facilities with captive power infrastructure.
Nigeria
Snack manufacturers across West Africa are scaling purchases of value-added products from Nigerian origins. The country's food safety agency mandates EFSA-aligned aflatoxin certification for EU-bound kernel shipments. Kogi State's processing cluster is bringing multiple integrated facilities online, creating captive demand for raw nut supply chains.
Ghana
Asian snack manufacturers remain significant buyers of Ghanaian raw cashew nuts for re-export processing. The national agricultural regulator coordinates with ECOWAS harmonization frameworks to reduce cross-border friction for processed goods. Processing facilities in the Brong-Ahafo region are adopting steam-based shelling systems to improve kernel color consistency.
Benin
Artisanal processors in the 500-2000 ton annual tier are consolidating around mid-scale steam boiler investments. The country's food safety coordination office is aligning with regional EFSA-equivalent standards for export-bound kernels. The Parakou corridor serves as a collection point for raw nut movements to Nigerian and Ivorian processing clusters.
Burkina Faso
Smallholder-aggregating traders are exiting kernel export channels due to laboratory infrastructure requirements for aflatoxin certification. The national agricultural standards body participates in ECOWAS harmonization programs for processed goods. Bobo-Dioulasso functions as a secondary collection hub for raw nut flows toward coastal processing zones.
Africa Cashew Market Competitive Environment
Player mix skews toward vertically integrated agro-industrial platforms and commodity traders with captive supply relationships. Market structure concentrates around three to five dominant operators with farm-gate-to-export-terminal control. Strategic archetypes include integrated processing park developers, multinational agricultural conglomerates with African cashew divisions, and regional commodity aggregators with laboratory certification partnerships. Competitive moves center on backward integration into raw nut supply chains and capacity expansion within ECOWAS-sanctioned industrial zones.
Among integrated agro-processing platforms, ARISE Industrial Integrated Platforms and Glo-Djigbé Industrial Zone exemplify the infrastructure-heavy archetype with bundled logistics and energy utilities. Olam International and Wilmar International occupy positions within the multinational agricultural conglomerate tier, leveraging scale advantages across West African origins. Ivory Coast Cajou represents the regional specialist model with concentrated Ivorian operational focus.
| Leading Market Players |
|---|
| Ivory Coast Cajou |
| Amama Farms |
| Olam International |
| Glo-Djigbé Industrial Zone |
| ARISE Industrial Integrated Platforms |
| Wilmar International |
| Asian Trading International |
| Golden Africa |
| Touton |
| Others |
Value Chain & Pricing Dynamics
Steam boiler adoption at scale compresses unit processing costs while elevating quality floors across Nigerian and Ivorian facilities. This scale dynamic concentrates margin capture among integrated processors with captive energy infrastructure, forcing artisanal operators toward price-taking positions in domestic retail channels.
Pricing Analysis
Certification level under EFSA-aligned aflatoxin standards creates the primary spread between export-grade and domestic-market kernels. Three-tier pricing structure across premium, standard, and economy levels stratifies by laboratory documentation, kernel color grade, and defect count under Association of Food Industries protocols. Cost compression in the standard tier is intensifying because smaller processors lack in-house testing capacity and must contract accredited third-party services. Export-market buyers demonstrate lowest price sensitivity due to traceability requirements, while domestic West African snack manufacturers negotiate aggressively on volume offtake.
Supply Chain Analysis
Côte d'Ivoire and Nigeria anchor raw nut production and kernel processing capacity across West Africa. The supply chain draws from smallholder farm-gate collection networks, steam-based shelling equipment, and EFSA-certified laboratory infrastructure. Single-source vulnerability concentrates in diesel-dependent facilities outside dedicated agro-industrial parks, where grid unreliability forces generator dependence. Distribution runs through Abidjan and Lagos wholesale aggregators for Asian-bound raw nuts, while direct sales channels serve European confectioners demanding sustainability audit documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA-aligned aflatoxin mandates are disrupting traditional trader-processor hierarchies, creating acquisition opportunities for infrastructure-ready operators. This regulatory inflection compresses timelines for laboratory investment and captive power deployment.
For Market Incumbents: Secure backward integration into Kogi State and Glo-Djigbé raw nut supply chains before export quota enforcement tightens further. Expand steaming and shelling capacity within ECOWAS-sanctioned industrial zones to capture margin pools shifting from commodity traders. Laboratory certification partnerships represent the priority lever against emerging mid-scale competitors with Chinese-origin boiler investments. For New Entrants and Emerging Players: Lead with fair-trade and organic certification to access North American specialty snack channels where price premiums persist. Target cashew butter formulation partnerships with European plant-based protein manufacturers as the most penetrable application outside traditional confectionery. Direct-to-health-food-distributor relationships bypass consolidated European procurement desks demanding multi-year traceability documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with captive power and laboratory infrastructure over pure-play traders. Long-term viability rests on regulatory compliance depth rather than scale alone. Acquisition targets should demonstrate EFSA-aligned certification capability and established relationships with German or Dutch buying offices. Watch aflatoxin testing mandate expansion into Asian destination markets as the signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | EFSA-aligned testing capacity unlocks EU-bound kernel export channels previously closed to smaller operators. |
| Captive Power Infrastructure | Diesel generator replacement with grid or renewable supply stabilizes margin economics in Kogi State processing clusters. |
| Backward Integration into Farm-Gate Supply | Direct smallholder relationships secure raw nut volumes under Côte d'Ivoire's tightening export quota regime. |
| Fair-Trade Certification Program | Organic and ethical sourcing credentials command price differentiation in North American health food distribution. |
| Steam Shelling Technology Deployment | Chinese-origin boiler adoption reduces kernel breakage rates and enables color consistency for premium grade classification. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECOWAS trade documentation, national cashew regulator filings, and confectionery industry procurement databases. Primary interviews encompassed processing facility managers in Kogi State and Glo-Djigbé, export traders in Abidjan and Lagos, and procurement leads at German and Dutch buying offices. Secondary validation drew from Côte d'Ivoire's national cashew council statistics, Nigeria's food safety agency certification records, and Association of Food Industries grading standards. Bottom-up capacity assessments across West African processing clusters were triangulated against top-down trade flow analysis.
Segmentation dimensions modeled include product form, processing technology tier, end-use application, and distribution channel intensity across the projection horizon. CAGRs were derived from installed capacity expansion schedules, regulatory enforcement timelines, and substitution elasticity estimates for Vietnamese and Indian kernel supply. Industry-specific forecast inputs encompassed steam boiler adoption curves, aflatoxin laboratory buildout rates, and ECOWAS harmonization implementation phases.
Forecasts assume regulatory continuity in EFSA-aligned aflatoxin regimes and ECOWAS agricultural standards harmonization; material policy shifts would require re-modeling. Specific risks include accelerated export quota restrictions, grid infrastructure deterioration, and Asian destination market certification convergence. Recalibration cycles align with material shifts in regulatory enforcement velocity and processing capacity utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Global Vermicompost Market