
 France Animal Protein Market | 2026-2036
France Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
France Animal Protein Market Foresight
Portion-controlled and sous-vide ready configurations is restructuring buyer choice across French retail and foodservice channels. Sodiaal Union SCA leverages its cooperative milk-protein base to extend into functional animal protein isolates for industrial buyers. LACTALIS Ingredients dominates whey and milk protein fractionation, anchoring its position through backward integration into French dairy collectives. Innovafeed competes in the insect-protein segment, specializing in black soldier fly larvae as a novel input for aquafeed and pet nutrition formulations.
France Animal Protein encompasses tissue-derived and secretion-derived protein fractions from livestock and aquaculture, including myofibrillar proteins, serum albumins, and gelatin with specified Bloom strengths ranging from 50 to 300 for food and pharmaceutical applications. These proteins serve as structural agents in processed meats, nutritional fortifiers in clinical diets, and film-forming matrices in edible coatings. Chicken and pork lead volume contribution within the product type dimension, reflecting established French poultry and swine processing infrastructure and consistent retail demand. Modified atmosphere packaging commands margin concentration among packaging types, as shelf-life extension justifies unit premiums in premium retail and export channels. Fresh processing retains structural dominance, though dehydrated and cured methods gain traction in ingredient supply to food manufacturers seeking ambient-stable inputs.
ANSES and DGAL enforce France's national food safety and animal health standards, implementing EU-wide residue monitoring and welfare certification that constrain sourcing flexibility for non-compliant imports. The EU Green Deal and national low-carbon transition plans are forcing feed reformulation and manure management investments across livestock operations, raising compliance costs for integrated protein processors. Stakeholders must monitor evolving CAP conditionality requirements and carbon border adjustment mechanisms to secure long-term supply contracts and maintain access to institutional procurement channels.
Market Dynamics
The EU Green Deal's feed-to-fork traceability mandates are forcing livestock processors to reconfigure sourcing networks and invest in chain-of-custody systems, compressing margins for non-compliant operators while rewarding integrated Brittany-based clusters.
Growth Catalysts
- Premium Pet Nutrition Expansion:Specialized collagen and gelatin derivatives for functional pet food formulations are pulling demand from pharmaceutical-grade suppliers.
- ANSES Welfare Certification:Enhanced animal welfare standards are differentiating domestic production and securing preferential placement in institutional procurement channels.
- Agri-Food Cluster Density:Brittany and Pays de la Loire's integrated processing infrastructure enables cost-competitive co-product valorization and rapid ingredient customization.
Market Restraints
- Feed Input Volatility:Soybean meal and rapeseed cake price swings destabilize cost structures for poultry and swine integrators lacking long-term supply contracts.
- Import Sourcing Rigidity:DGAL residue monitoring protocols constrain flexibility for non-EU suppliers, narrowing alternative sourcing during domestic shortfalls.
- Plant Protein Substitution:Pea and fava bean protein isolates are capturing share in processed meat applications where texture engineering permits partial reformulation.
Strategic Opportunities
- Insect Protein Scale-Up:Black soldier fly larvae cultivation for aquafeed and pet nutrition offers defensible positioning ahead of EU Novel Food authorization.
- Modified Atmosphere Premiumization:Extended shelf-life packaging justifies unit price premiums in export channels targeting Middle Eastern and Asian retail.
- Carbon Border Adjustment Preparation:Early compliance with embedded carbon accounting creates first-mover advantage in German and Benelux procurement tenders.
Industry Challenges
- Traceability System Integration:Legacy ERP platforms in mid-sized abattoirs require costly retrofitting to meet real-time chain-of-custody documentation demands.
- Specialized Protein Fractionation Talent:Scarcity of technicians trained in myofibrillar protein extraction and Bloom strength calibration limits capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Animal Protein Market |
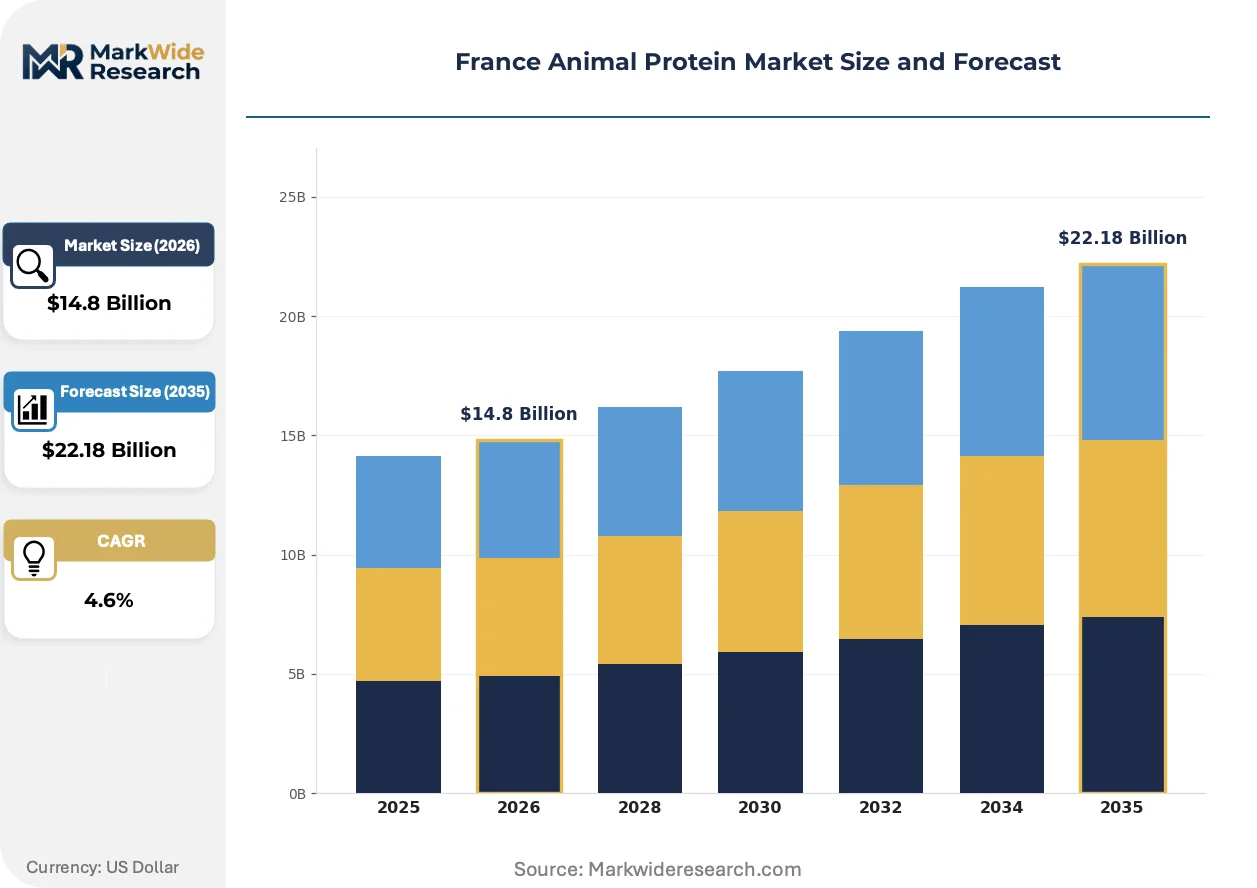
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Pork, Beef, Lamb, Aquatic, Game Processing Method: Fresh, Frozen, Cured, Smoked, Cooked, Dehydrated End User: Food Service, Retail Chains, Butcheries, Institutional Kitchens, Catering, Food Manufacturers Packaging Type: Vacuum Pack, Modified Atmosphere Pack, Frozen Block, Trays, Cans, Bulk Containers |
| Companies Covered | Darling Ingredients Inc. (Rousselot), Fonterra Co-operative Group Limited, Arla Foods amba, Sodiaal Union SCA, Innovafeed, Royal FrieslandCampina NV, Laita (EPI Ingredients), Eurial Ingredients & Nutrition, LACTALIS Ingredients, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Animal Protein Market Shifts & Advancements
Processing technology convergence and packaging format evolution are restructuring competitive advantage around shelf-life extension capabilities and clean-label positioning.
High-pressure processing is overtaking traditional thermal pasteurization for ready-to-eat poultry and sous-vide pork applications. French retail chains and foodservice distributors are adopting cold-pasteurized formats at accelerating rates. This shift is compressing the advantage of conventional cooked-meat processors while enabling premium positioning for operators with HPP line investments.
France's national implementation of EU Green Deal conditionality is mandating manure management infrastructure upgrades and feed carbon footprint disclosure. Livestock integrators face capital allocation decisions between biogas digestion systems and precision feeding technologies. Pork operations in Brittany are most affected, with cooperatives pooling investments to spread compliance costs across member farms.
Portion-controlled and sous-vide ready configurations are displacing bulk primal cuts in French retail and foodservice procurement. Buyers in Paris and Lyon metropolitan foodservice channels are specifying individually quick-frozen and vacuum-sealed formats to reduce kitchen labor and waste. This pattern concentrates demand among processors with dedicated portioning lines and recipe-ready development capabilities.
France Animal Protein Market Segmentation
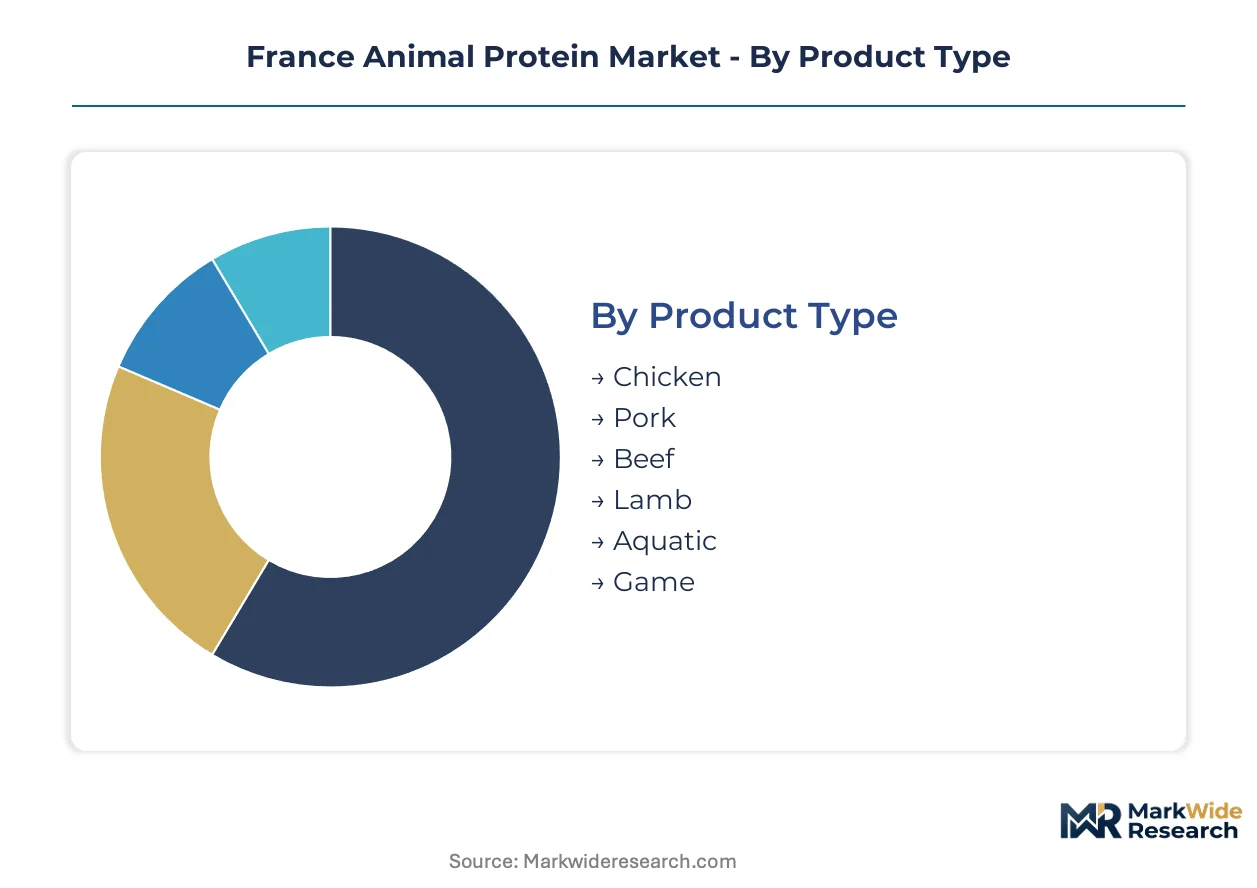
Segmentation in the France Animal Protein Market reveals how processing infrastructure, channel requirements, and regulatory compliance reshape procurement patterns across distinct buyer categories. Understanding these divisions exposes where margin concentrates and where volume growth accelerates.
Product Type:
Buyer specifications for protein functionality, fat content, and traceability credentials determine sourcing priorities across livestock categories.
- Chicken:Myofibrillar protein structures in broiler meat enable versatile texture engineering for processed applications. Demand concentrates in Brittany's integrated poultry clusters, where ANSES welfare certification secures preferential placement in Parisian retail and export channels facing EU Green Deal carbon disclosure requirements.
- Pork:Higher collagen content and defined fat-to-lean ratios suit charcuterie traditions and industrial sausage formulations. Processing gravity centers on Pays de la Loire cooperatives, where biogas digestion investments spread compliance costs across member farms under tightening manure management mandates.
- Beef:Grass-fed and grain-finished supply chains serve distinct premium and commodity tiers respectively.
- Lamb:Seasonal production patterns in Pyrenees and Massif Central regions constrain year-round supply consistency.
- Aquatic:Farmed salmon and trout dominate volume; wild-capture species retain niche positioning in specialized retail.
- Game:Venison and wild boar supply fluctuates with hunting quotas and forestry management cycles.
Chicken leads on scale through industrialized breeding and processing density; pork leads on momentum as charcuterie export demand climbs and welfare-differentiated positioning captures premium pricing.
Processing Method:
Capital intensity and shelf-life extension capabilities create tiered competitive positions across preparation states.
- Fresh:Chilled distribution networks with sub-7-day turnover dominate French retail procurement. Cold-chain density in Île-de-France and Lyon metropolitan zones supports just-in-time replenishment models that minimize working capital for supermarket buyers.
- Frozen:Blast-freezing at -18°C preserves structural integrity for industrial ingredient applications and export logistics. Food manufacturers in Normandy and Hauts-de-France specify individually quick-frozen formats to enable recipe-ready portioning with minimal thaw loss.
- Cured:Salt and nitrite preservation traditions anchor French charcuterie identity with protected designation requirements.
- Smoked:Beechwood and oak smoking specifications differentiate regional specialty positioning.
- Cooked:Sous-vide and conventional thermal processing serve ready-to-eat demand in foodservice channels.
- Dehydrated:Low-moisture protein ingredients supply pet nutrition and specialized clinical diet formulations.
Fresh processing retains volume leadership through retail dominance; frozen formats gain share fastest as food manufacturers prioritize inventory flexibility and export market access.
End User:
Channel-specific requirements for portion specification, documentation, and delivery cadence fragment demand patterns.
- Food Service:Restaurant groups and collective catering operators specify recipe-ready cuts with consistent dimensional tolerances. Procurement in Lyon and Marseille metropolitan zones emphasizes labor-saving portion control and vacuum-sealed stability for extended holding periods.
- Retail Chains:Hypermarket and supermarket buyers enforce private-label development partnerships with dedicated shelf-life and packaging specifications. E.Leclerc and Carrefour procurement teams in Île-de-France demand modified atmosphere configurations with 10-14 day retail display windows.
- Butcheries:Artisanal meat cutters prioritize whole-carcass access for custom fabrication and provenance storytelling.
- Institutional Kitchens:Hospital and school nutrition departments emphasize cost-controlled procurement with mandatory welfare certification documentation.
- Catering:Event and airline catering segments require individually portioned formats with extended ambient stability.
- Food Manufacturers:Industrial ingredient buyers specify functional protein fractions with defined water-binding and emulsification indices.
Retail chains command procurement scale through centralized tendering; food service channels expand most quickly as out-of-home consumption recovers and labor cost pressures intensify.
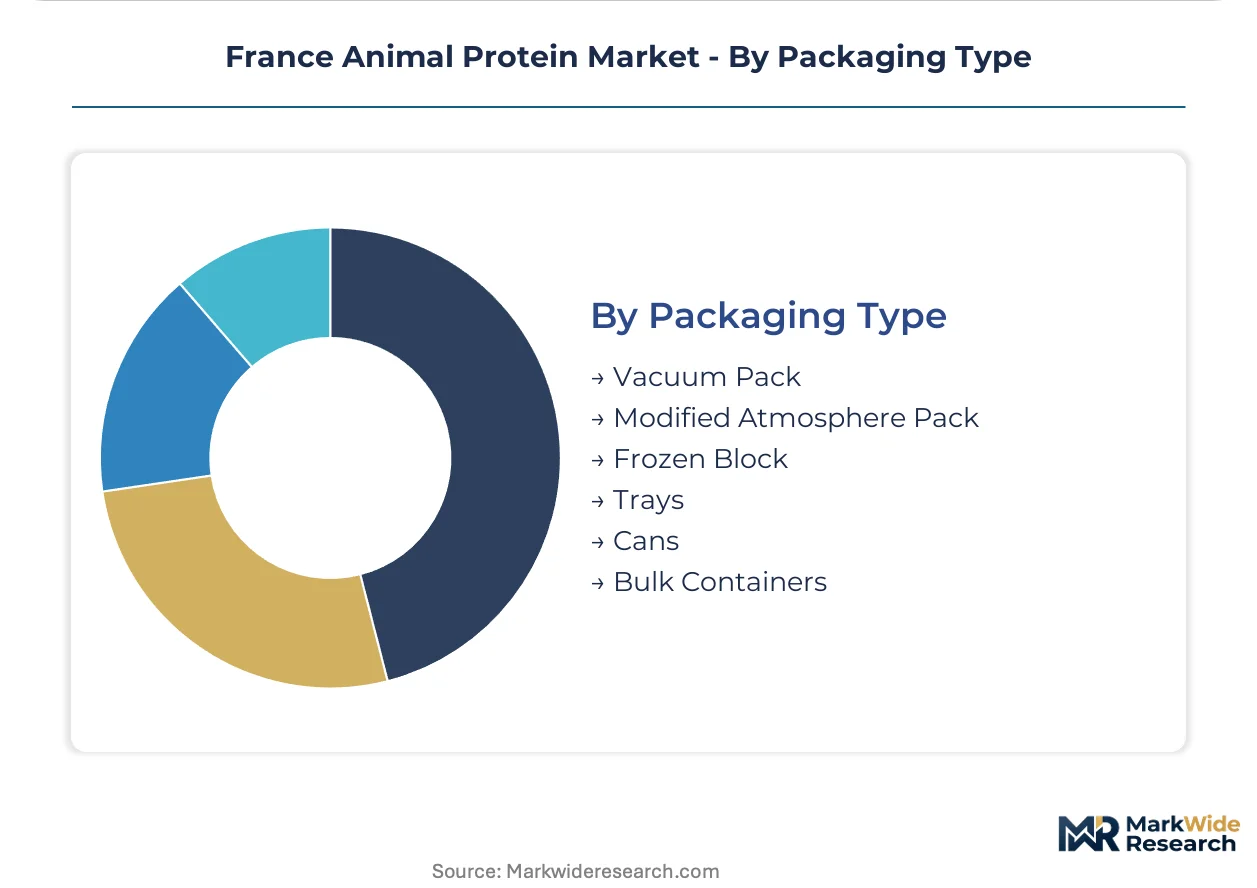
Packaging Type:
Shelf-life extension performance and unit economics determine format selection across temperature-controlled and ambient distribution chains.
- Modified Atmosphere Pack:Controlled oxygen and carbon dioxide mixtures inhibit microbial proliferation without thermal degradation. Premium retail positioning in Brittany and Pays de la Loire distribution networks justifies 15-25% unit price premiums through extended sell-by windows and reduced shrinkage.
- Vacuum Pack:Oxygen exclusion enables 21-28 day chilled shelf life for primal and subprimal cuts. Industrial buyers in Normandy meat processing clusters specify vacuum configurations for intermediate storage before further fabrication or export consolidation.
- Frozen Block:Poly-lined cardboard containers serve bulk industrial ingredient shipments with minimal packaging cost.
- Trays:Expanded polystyrene and recyclable fiber formats dominate retail display requirements with overwrap film compatibility.
- Cans:Thermal sterilization packaging preserves ambient stability for military, emergency, and remote catering applications.
- Bulk Containers:Food-grade totes and lined bins supply high-volume ingredient transfers between processing stages.
Modified atmosphere configurations lead on margin contribution through premium positioning; vacuum pack formats retain volume leadership across fresh distribution infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's animal protein industry traces its modern scale to post-war cooperative consolidation in Brittany and Pays de la Loire, where dairy and poultry collectives built integrated processing infrastructure that now anchors national supply.
Brittany
Poultry and pork processing density drives regional output, with cooperatives pooling manure management investments under EU Green Deal conditionality. ANSES welfare certification requirements filter non-compliant imports, securing preferential placement in Parisian retail channels. Saint-Brieuc and Rennes processing clusters specialize in portion-controlled and sous-vide configurations for foodservice buyers.
Pays de la Loire
Swine and dairy protein fractionation dominate, leveraging backward integration into member farms for feed-to-fork traceability. DGAL residue monitoring protocols constrain sourcing flexibility, reinforcing domestic supply chain preference. Nantes and Cholet industrial zones concentrate collagen and gelatin extraction for pharmaceutical and pet nutrition applications.
Île-de-France
Metropolitan demand from restaurant groups and retail headquarters shapes procurement specifications for recipe-ready cuts and modified atmosphere packaging. Cold-chain density supports just-in-time replenishment models. Parisian foodservice distributors specify labor-saving portion control formats to reduce kitchen labor costs.
Normandy
Dairy protein isolation and beef processing anchor the regional economy, with blast-freezing infrastructure serving industrial ingredient buyers. Vacuum-pack configurations enable intermediate storage before export consolidation. Caen and Rouen meat processing clusters supply individually quick-frozen formats to food manufacturers seeking inventory flexibility.
Auvergne-Rhône-Alpes
Charcuterie traditions and specialty meat processing sustain artisanal positioning, with protected designation requirements differentiating regional output. Lyon metropolitan foodservice channels drive demand for consistent dimensional tolerances in portioned cuts. Clermont-Ferrand and Saint-Étienne processors focus on extended shelf-life packaging for premium retail positioning.
France Animal Protein Market Competitive Landscape
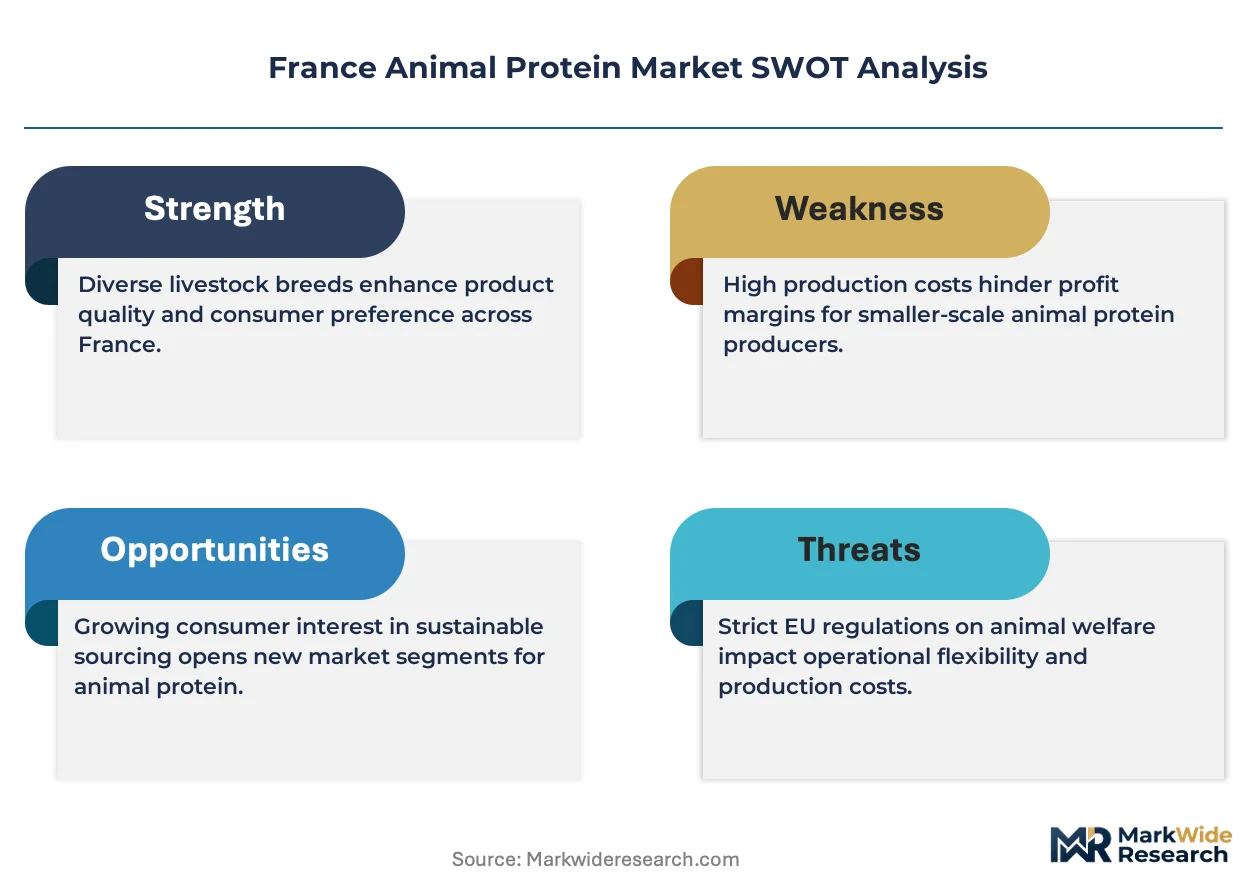
Premium-margin players sit above commodity-margin players across certification tier and traceability depth, with welfare-differentiated positioning capturing 15-25% unit price premiums in institutional procurement. The vendor base stratifies into three archetypes: cooperative-backed integrators with captive farm supply, pharmaceutical-grade fractionation specialists, and novel protein cultivators targeting aquafeed and pet nutrition. Dominant competitive moves include backward integration into dairy collectives and early positioning ahead of EU Novel Food authorization for insect-derived inputs.
Within the cooperative-integrated tier, Sodiaal Union SCA and LACTALIS Ingredients exemplify archetypes leveraging milk-protein bases to extend into functional isolates for industrial buyers. Innovafeed occupies a distinct position among novel protein cultivators, specializing in black soldier fly larvae as input for aquafeed and pet nutrition formulations ahead of regulatory authorization.
| Leading Market Players |
|---|
| Darling Ingredients Inc. (Rousselot) |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| Sodiaal Union SCA |
| Innovafeed |
| Royal FrieslandCampina NV |
| Laita (EPI Ingredients) |
| Eurial Ingredients & Nutrition |
| LACTALIS Ingredients |
| Others |
Supply & Pricing Matrix
Soybean meal and rapeseed cake price volatility feeds directly through poultry and swine integrator cost structures, compressing margins at the commodity tier while welfare-certified premiums in Brittany and Pays de la Loire sustain 15-25% price elevation for ANSES-compliant supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates welfare-certified organic supply from conventional domestic production and import-reliant commodity tiers. Price differentiation rests on ANSES certification grade and volume scale, with institutional buyers least sensitive and food manufacturers most responsive to input cost swings. Cost compression in the economy tier is intensifying because feed input volatility destabilizes non-integrated operators lacking long-term supply contracts.
Supply Chain Analysis
Direct-to-processor channels handle integrated cooperative demand from Brittany and Pays de la Loire, while spot market sourcing serves non-aligned food manufacturers. Supply concentrates in France's western livestock clusters, with raw material dependencies on Brazilian soybean meal, Ukrainian sunflower cake, and domestic cereal production. Single-source vulnerability runs through Black Sea grain corridors, constraining formulation flexibility during harvest disruptions. Distribution runs through cold-chain networks anchored in Rennes, Nantes, and Parisian metropolitan consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in France animal protein hinges on feed carbon disclosure compliance costs filtering non-integrated competitors, while premium-tier positioning around ANSES welfare certification captures institutional procurement preference.
For Market Incumbents:Acquire biogas digestion infrastructure and precision feeding technology assets to spread EU Green Deal compliance costs across cooperative member farms. Defensive consolidation into captive feed milling capacity insulates margin structures from import commodity volatility. Threat of plant protein substitution in processed meat applications demands accelerated myofibrillar protein fractionation R&D to defend functional performance differentiation.
For New Entrants and Emerging Players:Foodservice distributors in Lyon and Marseille metropolitan zones represent the most penetrable channel for portion-controlled and sous-vide ready configurations. White-space targets include insect protein cultivation ahead of EU Novel Food authorization and carbon-accounting-enabled supply for German and Benelux procurement tenders. Go-to-market positioning should emphasize recipe-ready development capabilities and vacuum-sealed stability specifications that reduce buyer kitchen labor costs.
For Investors and Strategic Acquirers:Consolidation pressure builds where mid-sized abattoirs face costly ERP retrofitting demands for real-time chain-of-custody documentation. Long-term viability favors cooperative-backed integrators with captive farm supply and backward integration into dairy collectives for protein fractionation scale. Acquisition target archetypes include pharmaceutical-grade gelatin extractors with Bloom strength calibration expertise and insect protein cultivators with regulatory pre-authorization positioning. Signal to watch: CAP conditionality enforcement tightening and carbon border adjustment mechanism implementation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive supply of soybean meal and rapeseed cake insulates margin structures from import commodity price swings. |
| ANSES Welfare Certification Investment | Premium tier access to institutional procurement channels in Parisian hospital and school nutrition departments. |
| High-Pressure Processing Line Deployment | Cold-pasteurized format adoption by E.Leclerc and Carrefour procurement teams commands shelf-life extension premiums. |
| Black Soldier Fly Larvae Scale-Up | Novel protein positioning ahead of EU Novel Food authorization secures aquafeed and pet nutrition offtake. |
| Carbon Border Adjustment Compliance | Embedded carbon accounting readiness creates first-mover advantage in German and Benelux tender participation. |
Research Methodology
Coverage spans France's regional livestock clusters, with primary inputs from each of Brittany, Pays de la Loire, Normandy, and Île-de-France, combining interviews with cooperative procurement directors, DGAL compliance officers, foodservice distributor category managers, and pharmaceutical gelatin extraction technicians with secondary validation from ANSES residue monitoring reports, EU Green Deal implementation guidance, and customs trade data on feed ingredient imports. Bottom-up volume modeling and top-down value reconciliation triangulate segment outputs.
Granularity-level modeling applies product type, processing method, end user channel, and packaging format dimensions at the regional cluster level across the projection horizon. CAGRs derive from trend extrapolation of feed input cost trajectories, welfare certification adoption curves, and portion-controlled format penetration rates. Industry-specific forecast inputs include EU Green Deal manure management investment schedules and CAP conditionality enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Black Sea grain corridor stability, EU Novel Food authorization timing for insect protein, and carbon border adjustment mechanism implementation scope. Forecasts reflect documented assumptions on feed cost normalization, certification adoption rates, and cooperative consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Europe Alfalfa Hay Market