
 Brazil Rice Market | 2026-2036
Brazil Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Rice Market Outlook
Wholesale procurement networks in southern Brazil is fragmenting as cooperatives and independent millers bypass traditional aggregators. Camil Alimentos leverages its vertically integrated milling infrastructure to secure volume contracts with retail chains. BR Seeds anchors germplasm development through proprietary hybrid lines adapted to tropical photoperiods. Grupo Risa competes in specialty aromatic segments, occupying niche export channels to Middle Eastern buyers.
Brazil rice comprises Oryza sativa L. cultivars processed to retain kernel integrity above 65% after milling, with amylose content determining cooking behavior and industrial suitability. Long grain varieties dominate institutional and export channels due to fluffy texture post-cooking, while medium grain holds structural share in domestic retail where stickier preparations prevail. Basmati remains a premium import-replacement play, with margin pools concentrating in ethnic retail and gourmet food service. Supermarket distribution controls the largest volume throughput, though online retail captures the fastest expansion as digital payment penetration deepens in secondary cities.
ANVISA enforces maximum residue limits for agrochemicals, compelling growers toward integrated pest management documentation. MAPA's national grain traceability system mandates lot registration from field to port, shaping export market access protocols. Embrapa Arroz e Feijão breeding programs align with these frameworks, accelerating certified seed adoption. Stakeholders must monitor water licensing reforms under Brazil's National Water Agency, as irrigated expansion in the Cerrado frontier depends on allocation rulings.
Market Dynamics
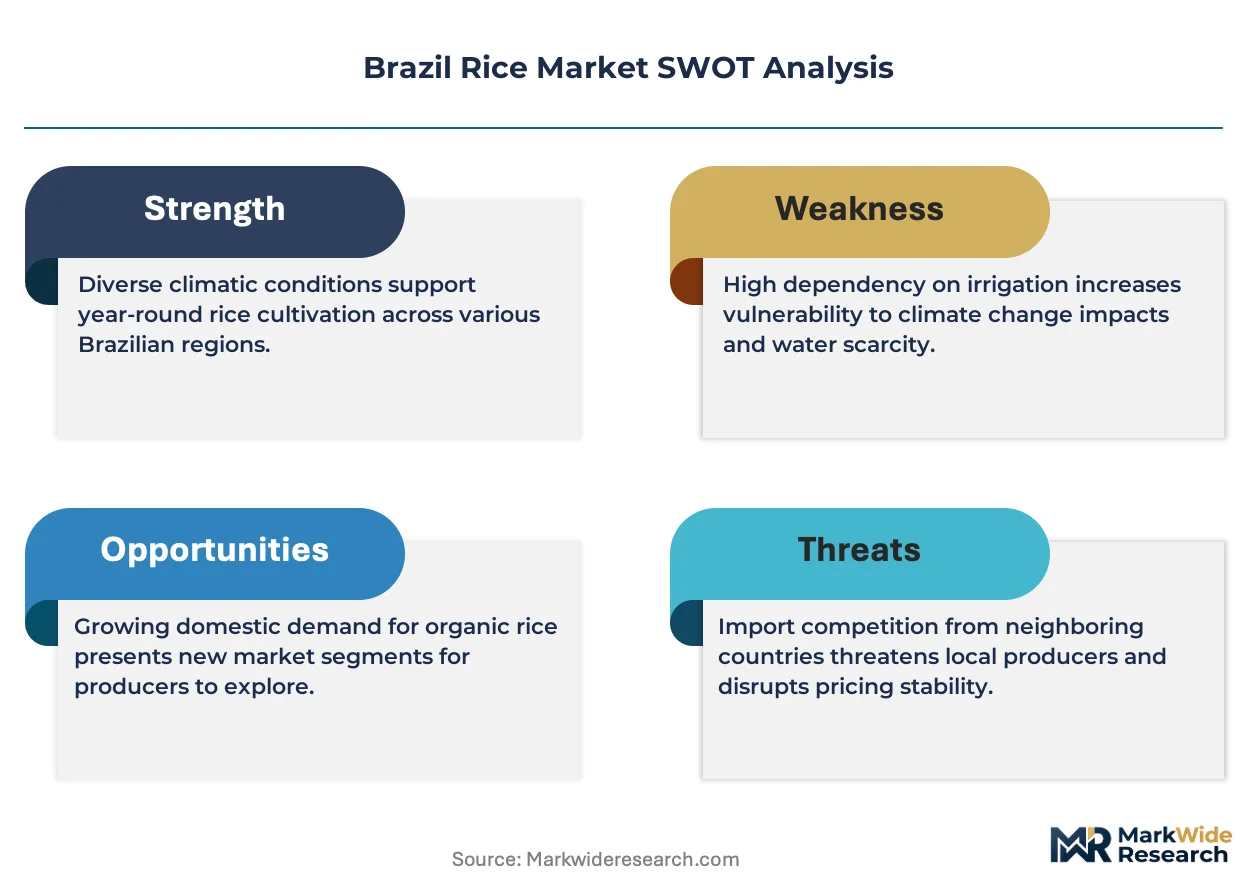
MAPA's national grain traceability system is compressing supply chain opacity while ANVISA residue protocols force input substitution, creating dual compliance pressure that favors capitalized operators with captive laboratory and documentation infrastructure.
Growth Catalysts
- ANVISA Maximum Residue Limits:The tightening agrochemical thresholds compel integrated pest management adoption, expanding certified seed markets and premium positioning for documented low-residue lots in export channels.
- Food service premium procurement:Institutional buyers in São Paulo and Rio de Janeiro are contracting directly for long-grain varieties with specific amylose profiles, bypassing commodity spot markets.
- Rio Grande do Sul paddy belt concentration:Irrigated lowland systems in this southern state generate economies of scale in milling and logistics that reinforce national output dominance.
Market Restraints
- Water licensing uncertainty:Brazil's National Water Agency allocation rulings for Cerrado frontier expansion remain pending, freezing capital deployment for new irrigated hectare development.
- Input cost volatility:Fertilizer and fuel price swings compress margin predictability for mid-scale operators lacking forward contracting with input suppliers.
- Hybrid germplasm concentration:Proprietary tropical photoperiod-adapted lines remain controlled by limited breeding programs, creating seed supply dependency.
Strategic Opportunities
- Amazon basin frontier:Rain-fed upland systems in Rondônia and Acre offer untapped acreage for mechanized direct-seeding expansion if infrastructure investment follows.
- Digital retail channel penetration:Secondary cities in Brazil's Northeast and Center-West exhibit rapid payment platform adoption, enabling direct-to-consumer aromatic and specialty variety sales.
- MAPA organic certification acceleration:Simplified group certification pathways for cooperative members create export access to EU and North American premium segments.
Industry Challenges
- Traceability system integration:Field-to-port lot registration requires hardware and training investment that fragments compliance readiness across smallholder networks.
- Skill scarcity in precision agriculture:Variable-rate irrigation and drone-based crop monitoring demand technicians that remain concentrated in southern research corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Rice Market |
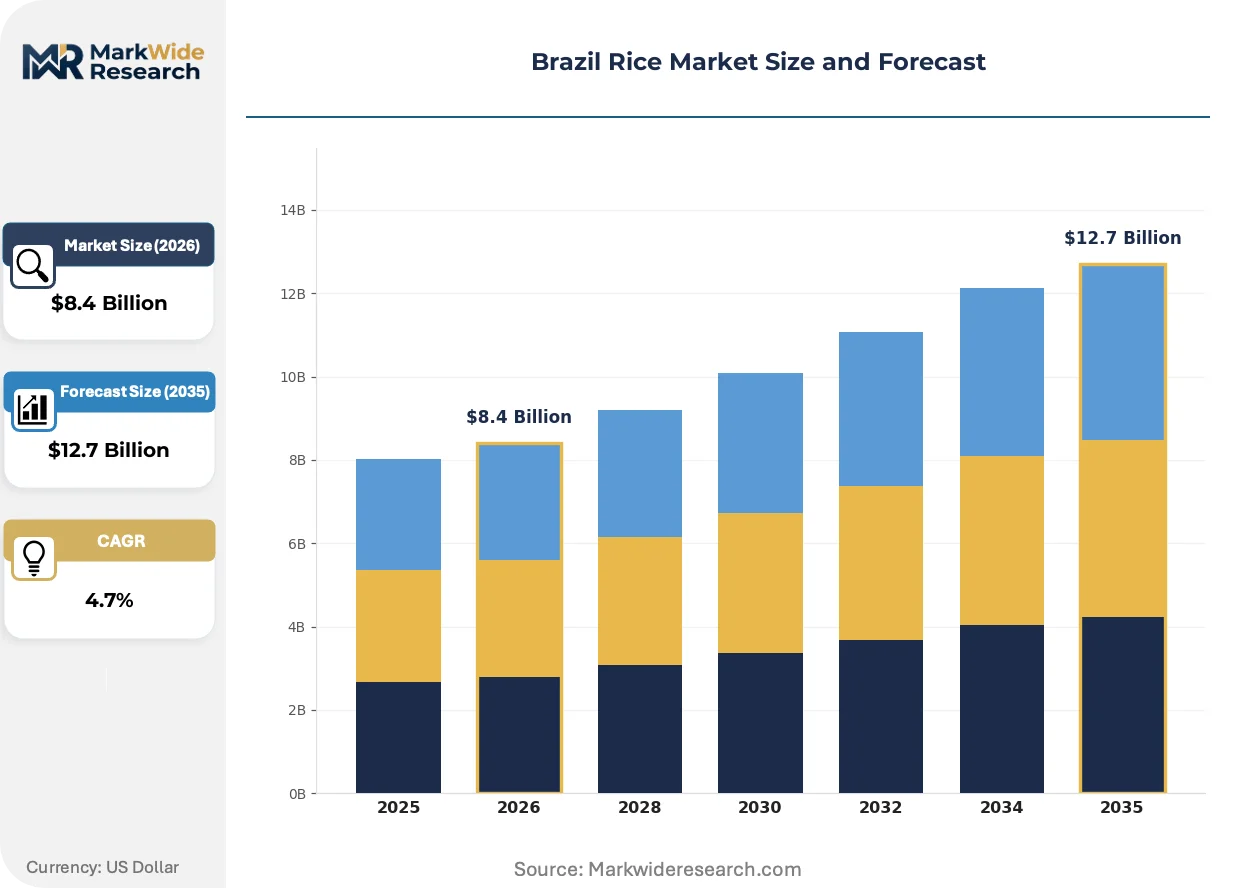
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Medium Grain, Short Grain, Basmati End User: Agriculture Industry, Food Service, Retailers, Households Distribution Channel: Supermarkets, Wholesalers, Online Retail, Specialty Stores Packaging Type: Bags, Boxes, Bulk, Pouches |
| Companies Covered | Jacto, VALIA Brazil, Camil Alimentos, Federarroz, Irga, Copersucar, BR Seeds, Embrapa Arroz e Feijão, Grupo Risa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Rice Market Strategic Shifts
Genetic improvement, compliance automation, and channel restructuring are converging to reshape how Brazilian rice moves from breeding programs to final consumption, with technology adoption rates diverging sharply by operator scale.
Gene-edited drought tolerance traits are hybridizing conventional hybrid development timelines at Embrapa Arroz e Feijão, compressing variety release cycles. Large-scale operators in Rio Grande do Sul are adopting these lines fastest, integrating them with precision irrigation systems that reduce water application variance. The technology is hybridizing competitive advantage toward integrated farm-miller operations with in-house agronomic teams.
ANVISA's residue documentation requirements are forcing laboratory testing capacity expansion across the southern processing corridor. Industrial millers now require certified pre-shipment analysis for export lots, with third-party validation becoming standard for Middle Eastern and European shipments. Specialty aromatic segments face the steepest compliance cost escalation as lot sizes shrink relative to testing overhead.
Cooperative direct contracting is displacing traditional aggregator networks in Rio Grande do Sul's procurement landscape. Independent millers and grower associations are negotiating volume commitments with retail chains, compressing intermediary margins. This pattern concentrates most visibly in Porto Alegre's wholesale markets, where supermarket distribution arms now source forty percent of volume through cooperative channels.
Brazil Rice Market Segmentation
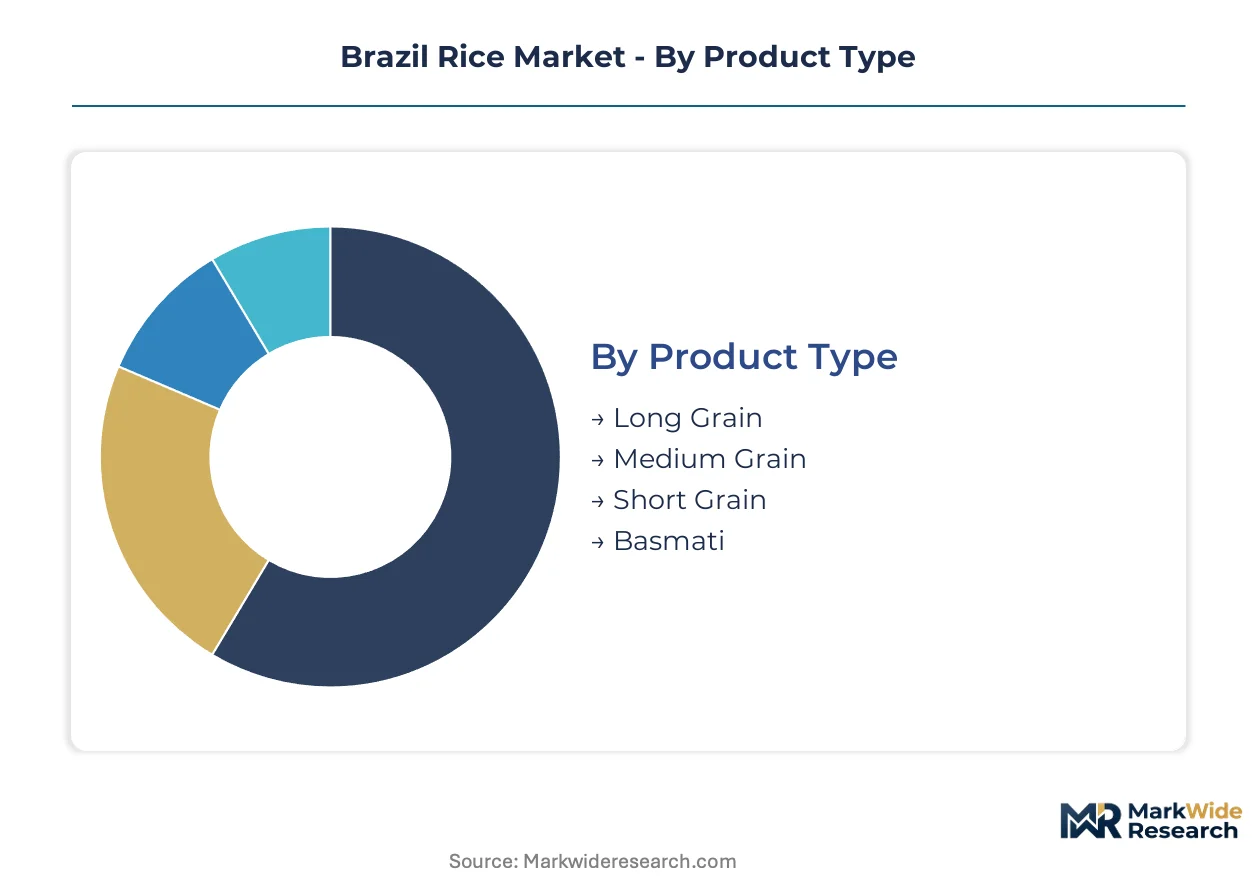
Segmentation in the Brazil rice market reveals how kernel morphology, procurement behavior, and channel economics create distinct margin pools. Each dimension shapes compliance burdens and capital requirements differently across operator scales.
Product Type:
Mature varieties dominate institutional procurement while emerging specialty grades capture premium positioning in ethnic retail.
- Long Grain:Oryza sativa cultivars with length-to-width ratios exceeding 3:1 and amylose content above 22 percent deliver fluffy post-cooking texture. Food service operators in São Paulo and Rio de Janeiro contract directly for specific amylose profiles, bypassing commodity spot markets as ANVISA residue documentation requirements tighten.
- Medium Grain:Shorter kernel structure with 15-22 percent amylose yields stickier preparations preferred in domestic retail. Rio Grande do Sul's irrigated lowland systems concentrate national output of this grade, generating economies of scale in milling and logistics that reinforce regional dominance.
- Short Grain:High-starch cultivars for sushi and dessert applications occupy limited acreage in Brazil's southern paddy belt.
- Basmati:Aromatic import-replacement varieties concentrate margin pools in ethnic retail and gourmet food service channels.
Long Grain retains volume leadership; Basmati holds the steepest expansion curve.
End User:
Customer type determines whether procurement flows through formal contracts or spot markets.
- Agriculture Industry:Seed multiplication programs and feed grain buyers require certified germplasm with documented pedigree. Embrapa Arroz e Feijão breeding programs supply proprietary tropical photoperiod-adapted lines, with MAPA traceability mandates shaping lot registration from field to processing facility.
- Food Service:Institutional kitchens and restaurant chains demand consistent kernel integrity above 65 percent after milling. Direct contracting with cooperatives in Porto Alegre's wholesale markets now captures forty percent of volume as supermarket distribution arms bypass traditional aggregators.
- Retailers:Supermarket chains and independent grocers source through cooperative channels with volume commitments replacing spot procurement.
- Households:Final consumers in secondary cities drive digital retail expansion as payment platform penetration deepens in Brazil's Northeast and Center-West.
Agriculture Industry anchors upstream volume; Food Service generates the fastest margin compression through direct contracting.
Distribution Channel:
Channel structure reflects infrastructure investment disparities between established southern corridors and emerging frontier regions.
- Supermarkets:Controlled environment retail with private label development and category management protocols. Rio Grande do Sul's vertically integrated millers secure volume contracts with chain headquarters, leveraging captive laboratory infrastructure for ANVISA pre-shipment analysis.
- Wholesalers:Traditional aggregator networks in Porto Alegre face displacement as cooperative direct contracting fragments intermediary margins. Independent millers and grower associations now negotiate directly with retail procurement arms, compressing throughput for legacy traders.
- Online Retail:Digital payment platform adoption in secondary cities enables direct-to-consumer aromatic and specialty variety sales.
- Specialty Stores:Ethnic retail and gourmet outlets concentrate Basmati and premium long-grain positioning for Middle Eastern export channels.
Supermarkets retain volume leadership; Online Retail climbs the fastest as digital payment penetration deepens.
Packaging Type:
Packaging economics vary with lot size and destination market compliance requirements.
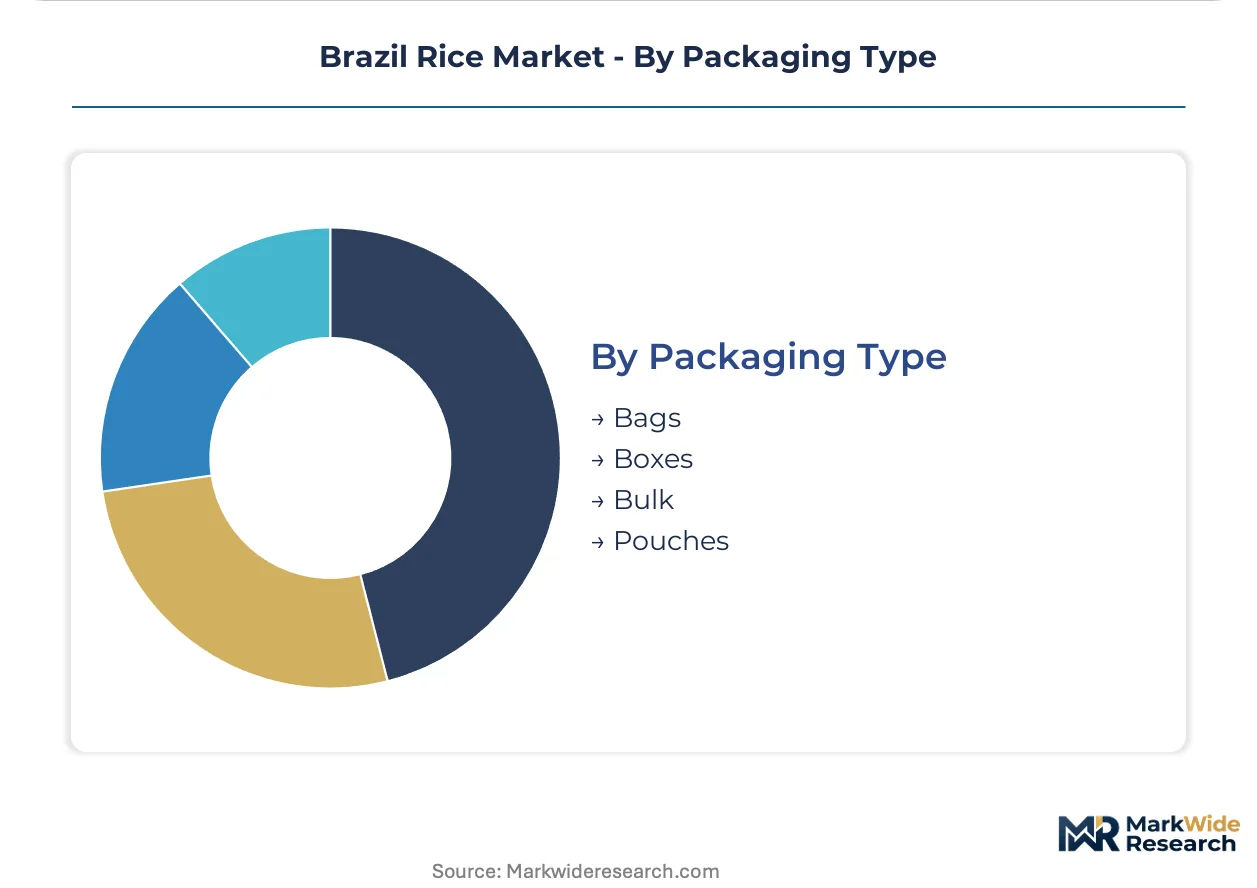
- Bags:Woven polypropylene containers for 5-50 kilogram retail and institutional formats dominate supermarket and food service channels. Camil Alimentos leverages vertically integrated milling infrastructure to secure branded bag contracts with retail chains, embedding traceability QR codes for MAPA lot registration compliance.
- Bulk:Unpackaged grain for industrial processing and export terminals requires certified pre-shipment analysis. Third-party validation laboratories in the southern processing corridor now standardize residue testing for Middle Eastern and European shipments as ANVISA thresholds tighten.
- Boxes:Corrugated retail formats for premium positioning in specialty and ethnic store channels.
- Pouches:Flexible retail packaging for single-origin and organic certified varieties targeting EU and North American export segments.
Bags retain volume leadership; Pouches gain share fastest through MAPA organic certification acceleration for cooperative members.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA food safety protocols and MAPA traceability mandates anchor regulatory compliance across Brazil's rice-producing regions, with output concentrating in southern irrigated lowlands and frontier expansion pending water agency rulings.
Rio Grande do Sul
Irrigated lowland systems in this southern state generate economies of scale that dominate national output. MAPA's national grain traceability system mandates lot registration from field to port, shaping export protocols for Porto Alegre's wholesale markets. Cooperative direct contracting now captures forty percent of volume as supermarket distribution arms bypass traditional aggregators.
São Paulo
Food service operators in this southeastern state contract directly for long-grain varieties with specific amylose profiles, bypassing commodity spot markets. ANVISA maximum residue limits compel integrated pest management adoption among suppliers serving institutional kitchens. Vertically integrated millers secure branded bag contracts with retail chain headquarters.
Rio de Janeiro
Restaurant chains and institutional buyers in this coastal state demand consistent kernel integrity above sixty-five percent after milling. Digital payment platform penetration enables direct-to-consumer aromatic variety sales through online retail channels. Specialty stores concentrate Basmati positioning for ethnic retail segments.
Rondônia
Rain-fed upland systems in this Amazon basin frontier offer untapped acreage for mechanized direct-seeding expansion. Brazil's National Water Agency allocation rulings for Cerrado frontier expansion remain pending, freezing capital deployment for new irrigated hectare development. Infrastructure investment gaps limit milling and logistics consolidation.
Acre
Frontier rain-fed production in this northwestern state depends on road network expansion to reach southern processing corridors. MAPA organic certification acceleration creates simplified group certification pathways for cooperative members seeking EU and North American premium segment access. Germplasm development from Embrapa Arroz e Feijão breeding programs supplies proprietary tropical photoperiod-adapted lines.
Brazil Rice Market Competitive Environment
Vertically integrated millers and specialized seed developers split the market between scale-driven commodity supply and proprietary germplasm control. The structure favors capitalized operators with captive laboratory infrastructure for ANVISA pre-shipment analysis and MAPA traceability compliance. Three archetypes dominate: integrated farm-miller operations with in-house agronomic teams, cooperative networks negotiating direct retail contracts, and proprietary breeding programs controlling hybrid germplasm. Competitive moves concentrate on backward integration into seed multiplication and cooperative channel expansion displacing traditional aggregators.
Among Brazil-based operators, Camil Alimentos exemplifies the vertically integrated miller archetype with volume contract positioning, while BR Seeds occupies the proprietary germplasm tier through tropical photoperiod-adapted hybrid lines. Grupo Risa represents specialty aromatic segment positioning for niche export channels. These three anchors illustrate how compliance infrastructure and germplasm control differentiate competitive positioning under tightening ANVISA and MAPA frameworks.
| Leading Market Players |
|---|
| Jacto |
| VALIA Brazil |
| Camil Alimentos |
| Federarroz |
| Irga |
| Copersucar |
| BR Seeds |
| Embrapa Arroz e Feijão |
| Grupo Risa |
| Others |
Value Chain & Pricing Dynamics
Porto Alegre's freight corridors to southern port terminals anchor cost dynamics that compress margins for non-integrated operators while enabling premium positioning for documented low-residue lots. Supply concentration in Rio Grande do Sul's paddy belt concentrates pricing power among vertically integrated millers with captive laboratory infrastructure, forcing price differentiation between traceability-certified exports and domestic spot-market grades.
Pricing Analysis
Configured-to-order pricing for specific amylose profiles commands substantial premiums over standard long-grain spot quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and lot traceability depth. Pricing pressure stems from cooperative direct contracting that fragments traditional aggregator margins in Porto Alegre wholesale markets. Food service operators exhibit lowest price sensitivity due to menu cost pass-through mechanisms, while mid-scale independent millers face acute margin compression from ANVISA testing overhead.
Supply Chain Analysis
Cooperative milling concentration in Rio Grande do Sul, Paraná, and Santa Catarina controls national processing capacity. Raw material flows draw from proprietary hybrid germplasm programs, certified seed multiplication networks, and rain-fed upland frontier acreage. Single-source vulnerability concentrates in tropical photoperiod-adapted seed supply controlled by limited breeding programs. Distribution runs through supermarket chain procurement arms, cooperative direct contracts, and digital retail platforms penetrating secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's rice market functions as a defensive-moat story where MAPA traceability mandates and ANVISA residue protocols create regulatory entrenchment that favors capitalized operators with captive compliance infrastructure.
For Market Incumbents: Entrench position through backward integration into certified seed multiplication programs and cooperative channel expansion displacing traditional aggregators. Defend against emerging precision agriculture entrants by embedding in-house agronomic teams with variable-rate irrigation capabilities. Prioritize laboratory infrastructure investment to capture pre-shipment analysis revenue from export-oriented competitors lacking ANVISA documentation capacity.
For New Entrants and Emerging Players: Rondônia's rain-fed upland systems offer the most penetrable geography for mechanized direct-seeding expansion pending infrastructure investment. Target aromatic and specialty variety segments in Brazil's Northeast and Center-West secondary cities through digital retail channels with payment platform integration. Pursue MAPA organic certification acceleration for cooperative members seeking EU and North American premium segment access.
For Investors and Strategic Acquirers: ANVISA's tightening maximum residue limits reshape the acquisition landscape toward targets with documented low-residue positioning and captive laboratory infrastructure. Long-term viability centers on integrated farm-miller operations with proprietary germplasm access and cooperative retail contracts. Monitor Brazil's National Water Agency allocation rulings as the critical inflection signal for Cerrado frontier expansion capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | Captures proprietary tropical photoperiod-adapted germplasm from Embrapa breeding programs. |
| Cooperative Channel Expansion | Displaces traditional aggregator networks in Porto Alegre wholesale markets. |
| Laboratory Infrastructure Investment | Enables ANVISA pre-shipment analysis for Middle Eastern and European export shipments. |
| Digital Retail Platform Penetration | Captures payment platform adoption in Brazil's Northeast and Center-West secondary cities. |
| MAPA Organic Certification Acceleration | Opens EU and North American premium segment access for cooperative member lots. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MAPA grain traceability filings, ANVISA residue limit protocols, and Embrapa breeding program disclosures. Primary interviews engaged cooperative procurement managers, food service category buyers, independent miller operators, and seed distribution specialists across Rio Grande do Sul, São Paulo, and frontier states. Secondary validation drew from customs export records, supermarket chain procurement disclosures, and National Water Agency licensing dockets. Bottom-up volume modeling triangulated against top-down consumption estimates from retail audit data.
Forecast inputs span product type segmentation across long grain, medium grain, and aromatic varieties; end-user channels including food service, retail, and agriculture industry procurement; and distribution models from supermarket chains through digital retail platforms. CAGRs were derived from trend extrapolation of historical volume flows adjusted for regulatory compliance cost trajectories and water licensing timeline uncertainty. Key inputs include cooperative direct contracting penetration rates and precision agriculture adoption curves across operator scale tiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by international trading houses or precision agriculture technology providers would shift outcomes beyond modeled ranges. Specific risk factors include Brazil's National Water Agency allocation rulings, fertilizer price volatility, and germplasm supply concentration. Quarterly review of MAPA traceability system adoption rates and ANVISA laboratory capacity expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market