
 Asia-Pacific Swine Feed Market | 2026-2036
Asia-Pacific Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Swine Feed Market Analysis
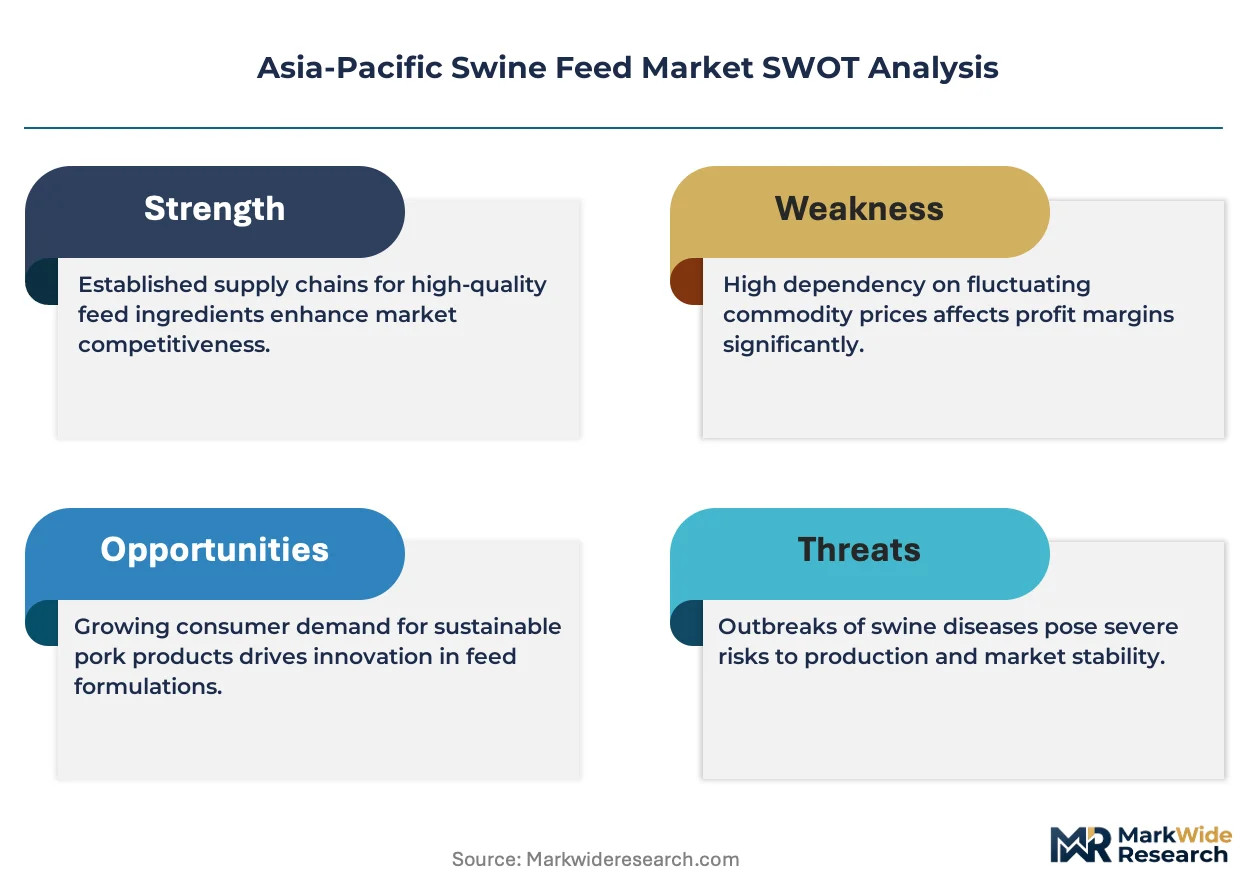
Pig farm ownership across the Asia-Pacific is consolidating as mid-scale operations shutter or merge with industrial integrators. New Hope Group leverages captive breeding-to-processing networks across Sichuan and Shandong provinces. Charoen Pokphand Foods anchors Thai supply through vertically coordinated contract farming. Cargill Inc. competes on amino acid precision and mycotoxin management protocols.
Asia-Pacific swine feed comprises nutritionally complete rations formulated from cereal grains, oilseed meals, and synthetic amino acids to optimize feed conversion ratios in commercial pork production. Pellet form dominates manufacturing due to reduced feed waste and improved digestibility, while mash retains cost advantage among smallholder cooperatives. Complete feeds capture the largest value pool across the product type dimension, though additives targeting gut health and enzyme efficiency represent the fastest-expanding margin segment. Direct sales channels control bulk volume to integrated producers, but wholesale networks sustain fragmented farmer access in Indonesia and Vietnam.
China's MEE enforces stricter nitrogen and phosphorus discharge limits, forcing reformulation toward low-protein diets with crystalline amino acid supplementation. India's FSSAI and BIS standards govern feed safety and labeling, while Vietnam's agriculture ministry implements African swine fever biosecurity protocols that alter ingredient sourcing. Stakeholders must monitor regulatory divergence on antibiotic growth promoter bans across China, South Korea, and Thailand to anticipate reformulation costs and competitive repositioning.
Market Dynamics
China's MEE nitrogen discharge limits are forcing feed mills across Shandong and Jiangsu to reformulate toward low-protein diets with crystalline amino acid supplementation, compressing traditional soybean meal demand while elevating precision nutrition margins.
Growth Catalysts
- Dual carbon policy framework:China's national carbon neutrality targets mandate methane reduction from livestock operations, accelerating adoption of feed additives that suppress enteric fermentation in commercial herds.
- Philippines commercial farm consolidation:Mid-scale operations in Central Luzon are merging with industrial integrators, creating concentrated procurement volumes for nutritionally complete formulated rations.
- Precision amino acid dosing:Crystalline lysine, methionine, and threonine supplementation protocols enable protein reduction without performance loss, cutting ingredient costs and nitrogen excretion simultaneously.
Market Restraints
- Soybean meal import dependency:Crushing capacity concentration in Argentina and Brazil exposes Asia-Pacific formulators to ocean freight volatility and currency fluctuation risks.
- African swine fever biosecurity protocols:Vietnam's agriculture ministry mandates heat-treated ingredient sourcing and facility segregation, elevating capital requirements for smaller compound feed mills.
- Antibiotic growth promoter phase-out:China's SAMR enforcement of ban implementation creates gut health performance gaps during transition periods, elevating mortality risk in non-integrated operations.
Strategic Opportunities
- Indonesia smallholder cooperative penetration:Mash feed distribution networks in East Java and North Sumatra remain underdeveloped, presenting wholesale channel expansion potential for regional compounders.
- South Korean MFDS gut health additive approval pathway:Regulatory streamlining for phytogenic and probiotic feed additives creates first-mover positioning for fermentation-derived products.
- Enzyme-nutrigenomics convergence:Xylanase and phytase optimization through genomic screening of gut microbiome responses enables customized enzyme cocktails for regional grain varietals.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-protein diet balancing with crystalline amino acid matrices remains concentrated among senior technicians at integrated producers, constraining independent mill technical service capabilities.
- Biosecurity infrastructure retrofit costs:Heat treatment systems for imported soybean meal and dedicated ingredient segregation facilities demand capital deployment that compresses margins for sub-scale operations in Vietnam and Indonesia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Swine Feed Market |
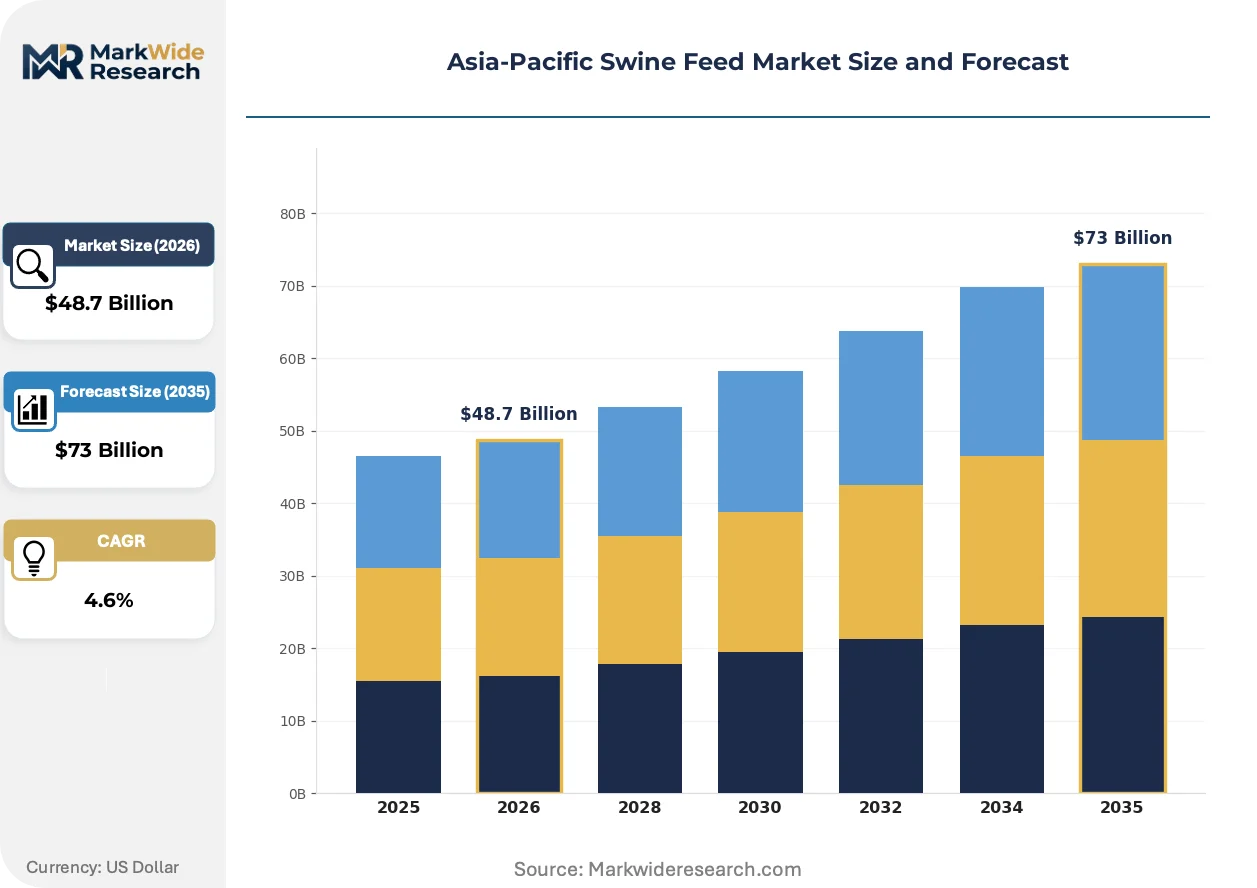
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Supplementary Feeds, Additives, Complete Feeds End User: Pigs, Farmers, Feed Manufacturers, Animal Nutritionists Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale Form: Pellets, Mash, Crumbles, Liquid |
| Companies Covered | New Hope Group, Charoen Pokphand Foods, Cargill Inc., Archer Daniels Midland, Alltech Inc., Guangdong Haid Group, Nutreco N.V., Land O'Lakes Inc., De Heus Animal Nutrition, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Swine Feed Market Emerging Trajectories
Active reformulation toward functional feed additives and precision amino acid dosing is compressing traditional commodity ingredient demand while elevating technical service requirements across the Asia-Pacific supply base.
Pellet manufacturing with steam conditioning and die specifications optimized for swine palatability is overtaking mash distribution in commercial operations. Integrated producers in China's Shandong corridor have standardized 4.0mm diameter pellet specifications, reducing feed waste by fifteen percentage points versus loose mash. This compression of physical form variation enables automated feeding system integration and real-time consumption monitoring.
China's MEE enforcement of stricter phosphorus discharge limits in concentrated livestock zones is mandating phytase superdosing and reduced mineral supplementation across complete feed formulations. Formulators must recalculate available phosphorus matrices while maintaining bone development performance, particularly affecting nursery diet specifications in the Yangtze River Delta cluster. Mills are responding with enzyme stability testing under varying thermal processing conditions.
Direct procurement contracts between integrated pork producers and amino acid manufacturers are fragmenting traditional distributor networks in Vietnam and the Philippines. Volume commitments with crystalline lysine and threonine suppliers bypass compound feed intermediaries, compressing wholesale margins while securing supply security for biosecurity-compliant operations. This pattern concentrates most visibly in Central Luzon contract farming arrangements anchored by Thai integrators.
Asia-Pacific Swine Feed Market Segmentation
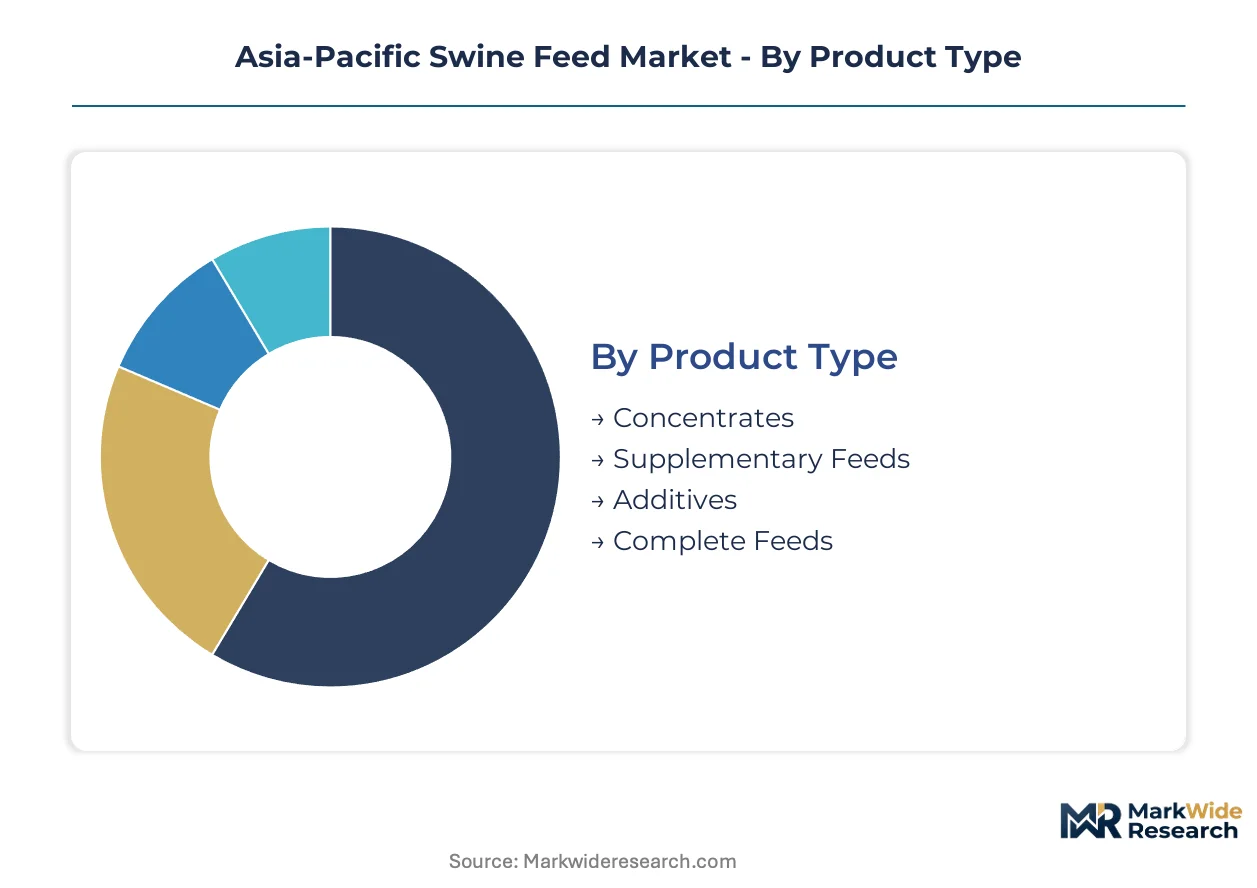
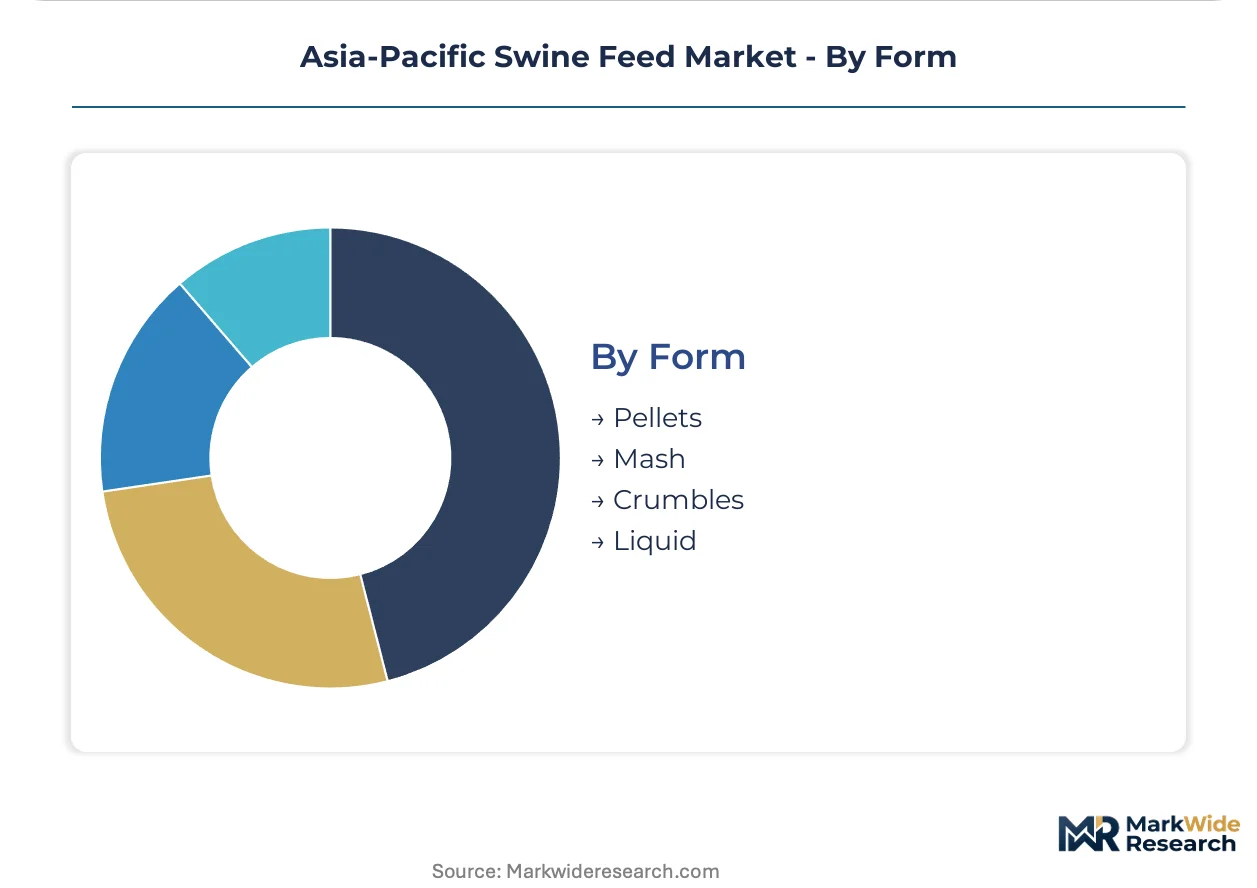
Feed form and distribution channel decisions in Asia-Pacific swine operations directly tie to biosecurity compliance costs and automated feeding infrastructure investments. Product type selection reflects the shift from commodity ingredient blending toward precision amino acid dosing and functional additive integration.
Product Type:
Reformulation cycles accelerate as MEE nitrogen discharge rules force mills to replace conventional high-protein formulations with crystalline amino acid matrices.
- Complete Feeds:Nutritionally balanced rations combining cereal grains, oilseed meals, and synthetic amino acids in fixed ratios. Procurement concentrates among integrated pork producers in Shandong and Jiangsu provinces where captive breeding-to-processing networks demand volume consistency and biosecurity traceability.
- Additives:Functional ingredients targeting gut health, enzyme efficiency, and enteric methane suppression. Demand clusters in Vietnam's commercial farm consolidation zones where African swine fever protocols elevate phytogenic and probiotic inclusion rates.
- Concentrates:Protein-rich bases requiring on-farm grain mixing, retaining cost appeal among smallholder cooperatives in Indonesia's East Java region.
- Supplementary Feeds:Mineral and vitamin premixes for diet balancing in mid-scale operations transitioning to formulated rations.
Complete Feeds sits at the top of the volume ranking, with Additives climbing the fastest.
End User:
Customer technical sophistication determines service intensity and pricing power across the value chain.
- Feed Manufacturers:Compound feed mills sourcing base ingredients and premixes for regional distribution. Procurement patterns concentrate among mills serving Vietnam's heat-treatment compliance requirements and Indonesia's cooperative networks.
- Farmers:Commercial pork producers and smallholder cooperatives specifying diet formulations. Demand fragments across the Philippines' Central Luzon integrator mergers and Vietnam's biosecurity-segregated operations.
- Pigs:Nutritional requirements by growth stage (nursery, grower, finisher, sow) driving diet specification granularity.
- Animal Nutritionists:Technical consultants prescribing low-protein amino acid matrices for nitrogen reduction compliance.
Feed Manufacturers command the largest procurement volumes, with Farmers gaining decision-making influence fastest through consolidation.
Distribution Channel:
Channel selection reflects customer scale and biosecurity segregation requirements.
- Direct Sales:Volume contracts between amino acid manufacturers and integrated pork producers. Procurement in Vietnam and the Philippines bypasses wholesale intermediaries as Thai integrators anchor Central Luzon contract farming.
- Wholesale:Distributor networks serving fragmented smallholder access in Indonesia and Vietnam. Mash feed distribution in East Java and North Sumatra remains underdeveloped.
- Offline Retail:Agricultural supply stores and cooperative purchasing for mid-scale operations.
- Online Retail:Emerging platform-based ordering for premixes and specialty additives in South Korea's MFDS-regulated market.
Direct Sales captures the dominant volume share, with Wholesale expanding fastest in previously underserved cooperative segments.
Form:
Physical form selection ties to feeding automation adoption and waste reduction targets.
- Pellets:Steam-conditioned cylindrical feeds with optimized die specifications. Shandong corridor integrators standardized 4.0mm diameter specifications, cutting feed waste fifteen percentage points versus mash while enabling automated consumption monitoring.
- Mash:Unprocessed ground mixtures retaining cost advantage among smallholder cooperatives with manual feeding systems.
- Crumbles:Broken pellet fragments for nursery diets requiring palatability and reduced selective feeding.
- Liquid:Wet feed systems for specific growth stages and medication delivery in controlled-environment facilities.
Pellets holds the volume lead, with Crumbles expanding most quickly in precision nursery diet specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated pork producers command procurement volumes that dwarf Vietnam's emerging commercial farm consolidation, yet both markets face tightening environmental discharge rules that reshape formulation standards.
China
Shandong and Jiangsu provinces concentrate demand from captive breeding-to-processing networks. MEE nitrogen and phosphorus discharge limits force mills toward low-protein diets with crystalline amino acid supplementation. Yangtze River Delta nursery operations now standardize phytase superdosing to meet available phosphorus matrices.
Vietnam
Commercial farm mergers in the Mekong Delta create concentrated procurement for formulated rations. The agriculture ministry's African swine fever protocols mandate heat-treated ingredient sourcing and facility segregation. Dong Nai province compounders retrofit capital-intensive biosecurity infrastructure to maintain supply contracts.
Philippines
Central Luzon integrator mergers generate volume commitments for nutritionally complete feeds. Contract farming arrangements anchored by Thai operators bypass traditional wholesale channels. SAMR-style antibiotic growth promoter restrictions loom in regulatory discussions.
Thailand
Vertically coordinated contract farming anchors domestic supply security. Charoen Pokphand Foods leverages captive networks across the Central Plains. MFDS regulatory streamlining for phytogenic and probiotic approvals creates additive market openings.
Indonesia
Smallholder cooperatives in East Java and North Sumatra retain mash feed cost advantages. Wholesale distribution networks remain underdeveloped relative to commercial farm penetration elsewhere. BIS-aligned feed safety standards govern import premix labeling.
Asia-Pacific Swine Feed Market Vendor Landscape
China-based producers anchor one tier; Thai and Dutch specialists hold contract farming and precision nutrition positions respectively. The vendor base splits between integrated agribusiness conglomerates with captive breeding networks and independent compound feed mills serving fragmented cooperatives. Three archetypes dominate: state-linked agricultural conglomerates with provincial supply monopolies, Southeast Asian contract farming anchors with Thai capital backing, and Western nutrition specialists competing on amino acid precision protocols. Competitive repositioning concentrates on direct procurement contracts that bypass wholesale intermediaries and biosecurity-compliant facility retrofits that exclude sub-scale competitors.
Within the integrated conglomerate tier, New Hope Group and Guangdong Haid Group represent state-adjacent operators with Sichuan and Shandong provincial network density. Charoen Pokphand Foods exemplifies the Southeast Asian contract farming anchor model. Cargill Inc. occupies the Western precision nutrition specialist position.
| Leading Market Players |
|---|
| New Hope Group |
| Charoen Pokphand Foods |
| Cargill Inc. |
| Archer Daniels Midland |
| Alltech Inc. |
| Guangdong Haid Group |
| Nutreco N.V. |
| Land O'Lakes Inc. |
| De Heus Animal Nutrition |
| Others |
Supply Flow & Price Mechanics
Integrated pork producers in Shandong and Jiangsu provinces command procurement volumes that compress supplier margins while elevating direct contract premiums over wholesale benchmarks. China's MEE discharge regulations add compliance cost layers that stratify pricing across biosecurity-certified and conventional supply tiers.
Pricing Analysis
Capacity additions in Vietnam's Dong Nai province are reshaping price floors for heat-treated soybean meal as biosecurity retrofit costs pass through to compound feed quotations. Pricing stratifies across premium, standard, and economy tiers based on amino acid precision dosing and MEE nitrogen compliance certification. Cost compression in standard-grade complete feeds is intensifying because crystalline lysine suppliers bypass wholesale intermediaries for direct volume contracts. Smallholder cooperatives in Indonesia exhibit highest price sensitivity, while integrated Thai-backed operations in Central Luzon absorb premium tiers for supply security.
Supply Chain Analysis
Domestic-content mandates in China's dual carbon policy framework are reshaping sourcing toward regional grain varietals and captive amino acid production. Supply concentration centers on China, Vietnam, and Thailand for compound feed manufacturing, with crushing capacity in Argentina and Brazil feeding soybean meal dependencies. Logistics chokepoints at Vietnamese ports elevate inventory carrying costs for heat-treated ingredient compliance. Distribution runs through direct procurement contracts to integrated producers, fragmenting traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific swine feed functions as a geographic-arbitrage play where MEE compliance costs in China's Yangtze River Delta create formulation expertise premiums that Vietnamese mills can undercut through lower environmental enforcement overhead.
For Market Incumbents: Deploy captive breeding-to-processing network density as the defensive lever. New Hope Group and Charoen Pokphand Foods should deepen backward integration into crystalline amino acid manufacturing to secure margin pools threatened by direct manufacturer-procurement bypass. Biosecurity infrastructure retrofits in Vietnam's Mekong Delta exclude sub-scale competitors, consolidating contract farming volumes for first-mover compounders. For New Entrants and Emerging Players: Wholesale distributors in Indonesia's East Java cooperative segments represent the most penetrable channel partner type for mash feed volume buildout. Phytogenic additive specialization targeting South Korea's MFDS regulatory streamlining offers white-space positioning. A fermentation-derived probiotic go-to-market angle bypasses incumbent amino acid commodity head-to-head competition. For Investors and Strategic Acquirers: Southeast Asian contract farming anchors with Thai capital backing are the most active acquirer in this space. Long-term viability centers on biosecurity-compliant facility portfolios capable of serving integrated pork producer procurement consolidation. Acquisition targets should display heat-treatment system deployment and direct sales channel penetration. The signal to watch is antibiotic growth promoter ban implementation timelines across China, South Korea, and Thailand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Manufacturing | Crystalline lysine and threonine captive supply secures margin pools threatened by direct procurement bypass. |
| Biosecurity Infrastructure Retrofit | Heat-treatment systems and facility segregation in Vietnam's Dong Nai province exclude sub-scale competitors from contract volumes. |
| Phytogenic Additive Regulatory Approval | South Korea's MFDS streamlining creates first-mover positioning for fermentation-derived gut health products. |
| Direct Sales Channel Expansion | Volume contracts with Central Luzon integrators fragment wholesale networks and compress distributor margins. |
| Low-Protein Diet Technical Service | Formulation chemist expertise in crystalline amino acid matrices commands premium pricing for MEE nitrogen compliance. |
Methodological Framework
Coverage spans East China, Southeast Asia, and South Korea, with primary inputs from each regional cluster combining interviews with compound feed mill procurement directors, integrated pork producer nutritionists, amino acid manufacturer sales executives, and Vietnamese agriculture ministry regulatory officers. Secondary validation draws from China MEE discharge filings, SAMR antibiotic ban enforcement circulars, MFDS additive approval databases, and ASEAN trade customs records. Bottom-up volume triangulation across feed form, product type, and distribution channel segments reconciles with top-down market sizing.
Rate-of-change decomposition across the analysis window isolates volume drivers by feed form adoption curves, amino acid precision dosing penetration, and biosecurity compliance cost pass-through. Segmentation modeling incorporates product type granularity, end-user technical sophistication tiers, distribution channel concentration, and physical form automation compatibility. CAGRs derive from fitted adoption curves for pellet manufacturing infrastructure and crystalline amino acid inclusion rate trajectories. Industry-specific inputs include MEE enforcement intensity indices and African swine fever protocol compliance scoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon policy acceleration, antibiotic growth promoter ban synchronization across jurisdictions, and ocean freight volatility for South American soybean meal. Forecasts reflect documented assumptions on regulatory enforcement consistency and commercial farm consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
South America Poultry Feed Market