
 Marine Algae Market | 2026-2036
Marine Algae Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Algae Market Analytics
Buyer consolidation among nutraceutical formulators is repositioning contract terms toward volume-commitment structures with preferred algae suppliers. Cargill leverages its existing agricultural procurement infrastructure to secure long-term offtake agreements with seaweed farming cooperatives. DSM anchors its position through in-house strain development for high-EPA microalgae, competing against commodity omega-3 sources.
Marine algae comprise photosynthetic organisms—macroalgae (seaweeds) and microalgae—cultivated in saltwater environments, typically harvested for their polysaccharide, lipid, and protein content ranging from 7% to 47% dry weight depending on species and growth phase. These organisms serve as functional inputs across food, feed, pharmaceutical, and energy applications where terrestrial crop alternatives face land or climate constraints. Nutraceuticals and food additives lead current revenue contribution given established extraction pathways and regulatory acceptance for human consumption, while biofuels remain development-stage with margin pools constrained by conversion efficiency and crude oil parity. Aquaculture applications within the application dimension show structural momentum as hatchery operators substitute fishmeal with algae-based proteins to reduce pressure on wild catch stocks.
The EU Green Deal and REACH frameworks govern biomass sustainability claims and chemical safety for algae-derived ingredients entering European consumer markets, while China's SAMR and GB standards dictate food-grade algae processing and labeling requirements for domestic distribution. The US FDA maintains GRAS notification pathways for novel algae proteins, shaping market access timelines for ingredient innovators. Stakeholders must monitor evolving carbon-accounting rules for aquatic biomass as jurisdictions begin classifying cultivation methods within emissions-trading schemes.
Market Dynamics
The EU Green Deal's binding sustainability criteria for biomass sourcing is forcing nutraceutical formulators to requalify their entire algae supply base, redirecting procurement toward certified cultivation operations with traceable carbon accounting.
Growth Catalysts
- REACH framework compliance:European chemical safety mandates for algae-derived ingredients are accelerating investment in controlled-environment photobioreactors that guarantee contaminant-free output for human consumption applications.
- Aquaculture feed substitution:Hatchery operators across Southeast Asia are substituting fishmeal with algae-based proteins to reduce pressure on wild catch stocks and meet Marine Stewardship Council certification requirements.
- State-backed biorefinery clusters:China's coastal provinces are absorbing rising macroalgae volumes through integrated processing facilities that convert seaweed into food-grade hydrocolloids and pharmaceutical precursors.
Market Restraints
- Input cost volatility:Seaweed farming cooperatives face fluctuating prices for synthetic rope substrates and diesel-powered vessel operations that compress margins during harvest cycles.
- Supply concentration risk:Premium omega-3 microalgae strains remain concentrated among a limited cohort of biotechnology licensors with proprietary high-EPA genetics.
- Conversion efficiency ceiling:Algal lipid extraction yields plateau below theoretical maximums due to cell wall recalcitrance, constraining biofuel economics against crude oil parity.
Strategic Opportunities
- Underpenetrated cosmetics channel:Marine collagen and fucoidan extracts are gaining traction in South Korean skincare formulations as brands seek alternatives to terrestrial animal-derived ingredients.
- Carbon credit monetization:Emerging emissions-trading schemes in Australia and Canada are classifying certified seaweed cultivation as net-negative activity, creating revenue streams beyond commodity sales.
- Bioplastics feedstock pivot:Polysaccharide-rich brown algae species are converging with PHA fermentation platforms to produce marine-degradable packaging materials for food service applications.
Industry Challenges
- Phycologist talent scarcity:Strain development programs lack sufficient trained algologists to scale domestic breeding operations outside established academic centers.
- GRAS notification timelines:Novel algae protein innovators face extended FDA review periods that delay commercial launch schedules and consume runway capital.
- Harvest mechanization gaps:Offshore macroalgae operations rely on manual cutting methods that limit scale-up velocity and create seasonal labor bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Algae Market |
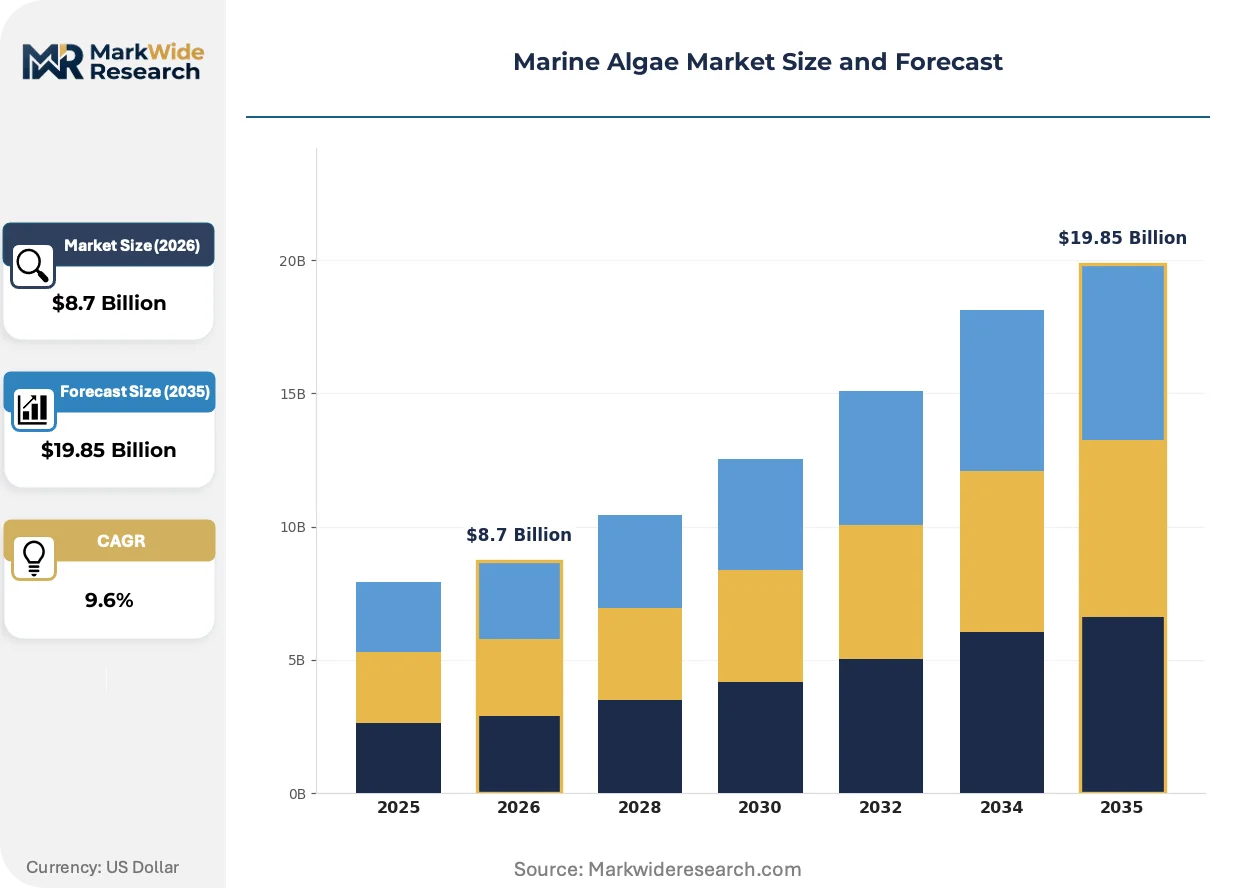
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additives, Nutraceuticals, Biofuels, Fertilizers End User: Food Industry, Healthcare, Cosmetics, Agriculture Form: Liquid, Powder, Extract, Whole Application: Aquaculture, Pharmaceuticals, Bioplastics, Animal Feed |
| Companies Covered | Cargill, CP Kelco, Algaia, Acadian Seaplants, Gelymar, DuPont, DSM, Qingdao Bright Moon, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Algae Market Evolving Landscape
Photobioreactor automation is compressing production cycles while machine-learning-driven strain selection is unlocking lipid profiles previously inaccessible through conventional breeding. These advances are repositioning algae from commodity biomass toward precision ingredients.
CRISPR-enabled metabolic engineering is converging with continuous harvesting systems to maintain algae populations in perpetual growth phase, maximizing EPA and DHA output per liter. Nutraceutical formulators in Germany and the Netherlands are adopting these integrated platforms to secure supply independence from wild-caught fish oil. The structural consequence is a compression in contract durations as buyers gain confidence in domestic production reliability.
China's SAMR is tightening GB standards for food-grade algae labeling and contaminant thresholds, forcing exporters to implement dual-track quality systems. Domestic processors are absorbing compliance costs through vertical integration into cultivation rather than third-party sourcing. European importers now face extended supplier qualification timelines that favor incumbents with established audit histories.
Long-term offtake agreements with volume-commitment structures are displacing spot-market purchasing among major nutraceutical buyers. Preferred supplier programs now mandate strain traceability and carbon-intensity disclosures as baseline qualification criteria. This shift is most visible in North American and European markets where ESG-linked procurement policies have hardened into binding vendor scorecards.
Marine Algae Market Segmentation
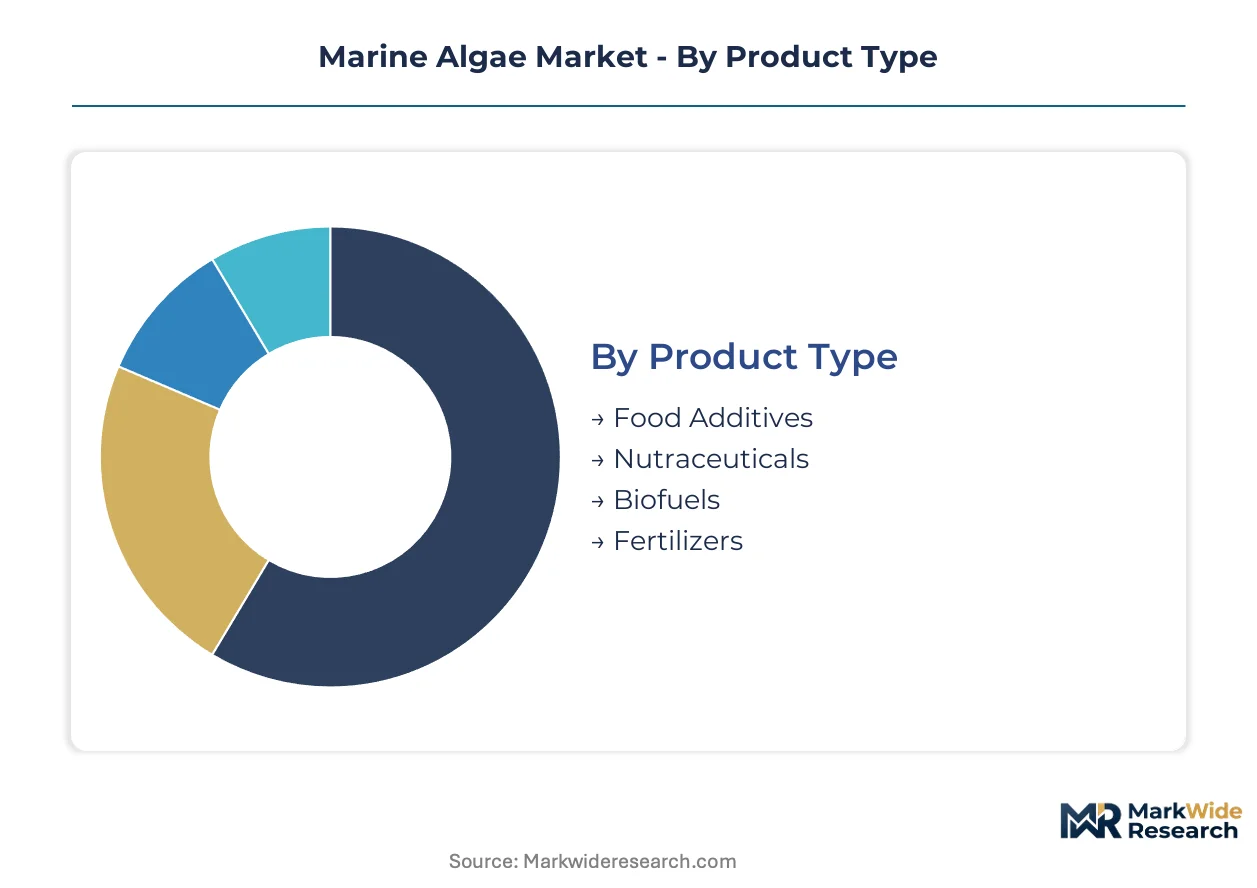
Marine algae suppliers configure production lines around distinct downstream specifications that determine extraction methods, purity thresholds, and regulatory compliance burdens. Segment boundaries reflect divergent margin structures between commodity biomass and precision ingredients.
Product Type:
Upgrade cycles differentiate commodity-grade from pharmaceutical-grade outputs, with extraction technology investments determining which tiers producers can access profitably.
- Food Additives:Carrageenan, alginate, and agar extracts function as gelling and stabilizing agents in processed foods. Chinese coastal processors dominate hydrocolloid supply for Asian food manufacturers seeking cost-competitive texturizers.
- Nutraceuticals:Omega-3 fatty acids (EPA/DHA) and protein concentrates command premium positioning through GRAS-notified or novel food approvals. DSM and Corbion anchor supply for European and North American supplement formulators replacing fish oil derivatives.
- Biofuels:Lipid-to-biodiesel conversion remains sub-economic against crude oil parity due to cell wall recalcitrance and extraction energy costs.
- Fertilizers:Seaweed-based biostimulants supply organic agriculture operations in Australia and Brazil seeking micronutrient alternatives to synthetic NPK formulations.
Volume placements concentrate in Food Additives; the faster expansion belongs to Nutraceuticals.
End User:
Customer procurement maturity shapes contract structures, with pharmaceutical and cosmetics buyers imposing stricter traceability and carbon-accounting requirements than commodity food processors.
- Food Industry:Hydrocolloid demand from plant-based meat formulators and dairy alternatives is accelerating carrageenan and alginate offtake. South Korean and Japanese food conglomerates specify contaminant thresholds exceeding baseline CODEX standards.
- Healthcare:Pharmaceutical applications leverage fucoidan and phlorotannin extracts for anticoagulant and antiviral research pipelines. Clinical trial-stage demand concentrates among biotechnology firms in Germany and the Netherlands.
- Cosmetics:Marine collagen and fucoidan extracts penetrate South Korean skincare formulations as animal-derived alternatives face consumer backlash.
- Agriculture:Biostimulant adoption spreads among Brazilian and Australian broadacre farmers seeking drought-resilience inputs exempt from synthetic fertilizer tariffs.
Contract values peak in Healthcare; Cosmetics is climbing the fastest as clean-label positioning accelerates.
Form:
Processing intensity and shelf stability requirements segment buyers by logistics infrastructure and formulation capabilities.
- Liquid:Live algae suspensions and concentrated extracts serve aquaculture hatcheries requiring immediate bioavailability. Southeast Asian shrimp and finfish operators prefer liquid delivery for direct tank dosing.
- Powder:Spray-dried whole algae and protein concentrates dominate nutraceutical encapsulation and sports nutrition applications. European contract manufacturers specify particle size distributions for tablet compression efficiency.
- Extract:Purified polysaccharide and lipid fractions command pharmaceutical and cosmetics-grade pricing contingent on solvent residue documentation.
- Whole:Unprocessed macroalgae biomass supplies traditional food processors and coastal biorefineries with integrated extraction capabilities.
Powder captures the largest shipment volumes; Extract is gaining share fastest on pharmaceutical qualification.
Application:
End-use technical specifications determine strain selection, cultivation system design, and downstream processing investments.
- Aquaculture:Algae-based proteins and live feeds substitute fishmeal in hatchery operations pursuing Marine Stewardship Council certification. Norwegian and Chilean salmon producers anchor demand for high-DHA microalgae strains.
- Pharmaceuticals:Active pharmaceutical ingredient precursors require GMP-compliant photobioreactor systems with batch-level traceability. European Union EMA and US FDA inspection histories filter supplier qualification.
- Bioplastics:Polysaccharide-rich brown algae feedstock converges with PHA fermentation platforms for marine-degradable packaging. Early-stage offtake agreements concentrate among food service distributors in California and European Union member states.
- Animal Feed:Poultry and ruminant operations in Brazil and New Zealand trial algae protein concentrates to reduce soybean import dependence and methane emissions intensity.
Aquaculture absorbs the heaviest volumes; Bioplastics shows the steepest expansion trajectory as packaging mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the heaviest macroalgae volumes through coastal aquaculture zones and state-backed biorefinery clusters. Nutraceutical formulators in Germany and the Netherlands are securing domestic supply through photobioreactor investments. Brazilian farmers are expanding seaweed-based biostimulant adoption to reduce synthetic fertilizer dependence.
China
Coastal provinces absorb rising macroalgae volumes through integrated processing facilities converting seaweed into food-grade hydrocolloids. SAMR tightening of GB standards for food-grade algae labeling forces exporters toward dual-track quality systems. Shandong Peninsula hosts concentrated hydrocolloid extraction operations serving domestic food manufacturers.
Germany
Nutraceutical formulators are adopting CRISPR-enabled photobioreactor platforms to secure EPA and DHA supply independence from fish oil. REACH framework compliance mandates accelerate investment in controlled-environment systems guaranteeing contaminant-free output. Hamburg anchors contract manufacturing clusters for European supplement brands.
United States
Algae protein innovators navigate extended FDA GRAS notification timelines that delay commercial launch schedules. California food service distributors are piloting early-stage offtake agreements for marine-degradable packaging feedstocks. San Diego biotech corridors concentrate strain development programs for high-EPA microalgae.
Brazil
Broadacre farmers are trialing algae protein concentrates for poultry and ruminant operations to reduce soybean import dependence. ANVISA regulatory pathways shape ingredient approval timelines for novel feed additives. São Paulo state processors are integrating seaweed-based biostimulants into organic agriculture supply chains.
South Korea
Skincare brands are accelerating marine collagen and fucoidan extract adoption as alternatives to terrestrial animal-derived ingredients. MFDS cosmetic safety standards dictate extract purity thresholds for domestic formulation. Seoul-based cosmetics conglomerates specify contaminant requirements exceeding baseline international standards.
Marine Algae Market Competitive Landscape
Chinese processors anchor one tier through coastal hydrocolloid extraction scale; European biotechnology specialists hold premium positioning through strain development capabilities. The vendor base separates into commodity biomass suppliers and precision ingredient developers with divergent margin structures. Three archetypes dominate: agricultural conglomerates leveraging procurement infrastructure, dedicated algae biotechnology firms with proprietary genetics, and regional seaweed farming cooperatives. Competitive moves concentrate on long-term offtake agreements with volume-commitment structures and backward integration into certified cultivation operations.
Within the agricultural conglomerate tier, Cargill occupies a position exemplifying procurement infrastructure leverage, while DSM represents the biotechnology specialist archetype through in-house strain development capabilities. Qingdao Bright Moon anchors the Chinese processor tier. These three entities exemplify the geographic and capability split defining competitive positioning: North American agricultural scale, European biotechnology precision, and Chinese coastal processing volume.
| Leading Market Players |
|---|
| Cargill |
| CP Kelco |
| Algaia |
| Acadian Seaplants |
| Gelymar |
| DuPont |
| DSM |
| Qingdao Bright Moon |
| Corbion |
| Others |
Value Network & Pricing Analysis
Sovereign-backed coastal processors in China anchor supply-side ownership patterns, compressing pricing discipline through state-coordinated volume procurement while private biotechnology specialists in Europe defend margins through strain-proprietary premiums. This ownership split creates divergent pricing power: commodity hydrocolloid producers face cost-pass-through constraints while precision omega-3 developers capture value-based premiums.
Pricing Analysis
Volume placements in food-grade hydrocolloids trade at thin spreads over cultivation costs, while nutraceutical-grade EPA concentrates sustain premium-mid-economy pricing differentiation tied to GRAS notification status and carbon-intensity certification. Price differentiation hinges on contaminant-test documentation and photobioreactor traceability, with EU REACH-compliant outputs commanding substantial premiums over conventional pond-grown biomass. Cost compression in commodity seaweed farming intensifies as diesel-powered vessel operations and synthetic rope substrates face input volatility. Aquaculture feed buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize batch-consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European nutraceutical formulators now mandate qualified backup suppliers for all high-EPA microalgae strains, forcing procurement teams to maintain parallel relationships with DSM, Corbion, and emerging domestic photobioreactor operators. Geographic supply concentration centers on China for macroalgae hydrocolloids, Norway and Chile for aquaculture feed applications, and the Netherlands for pharmaceutical-grade strain development. Raw material dependencies encompass synthetic rope substrates for offshore farming, carbon dioxide feedstock for photobioreactor systems, and solvent reagents for lipid extraction. Single-source vulnerability persists for proprietary high-EPA genetics held by limited biotechnology licensors. Distribution runs through long-term offtake agreements with volume-commitment structures displacing spot-market purchasing among major buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in marine algae hinges on backward integration into certified cultivation operations, with control over strain genetics and carbon-accounting documentation emerging as the decisive upstream lever separating commodity suppliers from precision ingredient developers.
For Market Incumbents: Deploy photobioreactor automation to compress production cycles and maintain perpetual-growth-phase populations, securing supply independence that reduces contract duration risk from confident buyers. Defend against CRISPR-enabled metabolic engineering disruptors by locking multi-year offtake agreements with European nutraceutical formulators before domestic production platforms mature. Prioritize REACH framework compliance investment to filter qualification timelines in favor of established audit histories. For New Entrants and Emerging Players: Launch via direct supply relationships with South Korean cosmetics conglomerates seeking marine collagen alternatives, bypassing entrenched hydrocolloid channels dominated by Chinese coastal processors. Target underpenetrated bioplastics feedstock partnerships with California food service distributors piloting marine-degradable packaging mandates. Pursue carbon credit monetization in Australian emissions-trading schemes as a revenue bridge during scale-up phases. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotechnology specialists with proprietary strain libraries in Germany and the Netherlands, where REACH compliance costs have compressed valuations for photobioreactor operators lacking pharmaceutical qualification histories. Long-term viability over the coming decade rests on convergence between algae-derived omega-3 and declining wild-caught fish oil reliability. Watch for FDA GRAS notification acceleration as the inflection signal signaling regulatory pathway maturation for novel protein innovators.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Controlled-environment systems guarantee contaminant-free output for EMA and FDA pharmaceutical inspections. |
| Backward Integration into Cultivation | Domestic strain development reduces dependence on limited biotechnology licensors with proprietary high-EPA genetics. |
| Long-term Supply Agreement | Volume-commitment structures with European nutraceutical formulators displace spot-market purchasing patterns. |
| Carbon Credit Certification Program | Australian and Canadian emissions-trading schemes classify certified seaweed cultivation as net-negative activity. |
| Joint Venture with Bioplastics Fermentation Platform | Polysaccharide-rich brown algae species converge with PHA production for marine-degradable food service packaging. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with photobioreactor operations directors, seaweed farming cooperative managers, nutraceutical procurement leads, and pharmaceutical regulatory affairs specialists. Secondary sources encompassed FDA GRAS notification databases, EMA inspection records, SAMR GB standard publications, and EU ETS carbon-accounting documentation for aquatic biomass. Bottom-up cultivation volume estimates from coastal province statistics triangulated against top-down demand modeling from hydrocolloid and omega-3 offtake patterns.
Data-stream reconciliation across supply-side capacity announcements and demand-side contract disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, end user, form, and application, with strain-specific lipid profiles and certification grade tiers as industry-specific modeling variables. CAGRs derived from historical volume trajectories in Chinese coastal aquaculture zones and European photobioreactor deployments, adjusted for regulatory approval timelines and conversion efficiency assumptions in biofuel economics.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-enabled metabolic engineering would alter the outlook if cell-wall recalcitrance breakthroughs accelerate lipid extraction yields. Forecasts reflect assumptions regarding REACH framework enforcement intensity and SAMR labeling standard harmonization. Deviation in FDA GRAS notification timelines or EU carbon-accounting rule finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Cashew Market