
 United Kingdom Compound Feed Market | 2026-2036
United Kingdom Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Compound Feed Market Analytics
Aftermarket nutritional consulting and feed formulation services is reconfiguring margin pools away from commodity volume sales toward value-added advisory revenue. AB Agri Ltd leverages its integrated supply chain from grain procurement to on-farm technical support to capture this shift. ForFarmers UK Ltd anchors its position through dedicated ruminant nutrition teams serving dairy cooperatives across the Midlands. Cargill Incorporated competes by extending its digital feed optimization platform to mid-sized livestock producers seeking precision agriculture tools.
Compound feed denotes industrially manufactured complete or complementary diets formulated from milled cereal grains, protein meals, and micro-ingredient premixes, typically processed through pelleting or extrusion to achieve standardized nutrient density and digestibility for targeted livestock species. Ruminant feed occupies the largest value share due to sustained dairy herd numbers and high reliance on compound supplementation during winter housing periods. Poultry feed represents the fastest-expanding product category, driven by integrated broiler operations in East Anglia and vertical coordination between processors and growers. Aquafeed remains a nascent but structurally important segment as Scottish salmon producers seek marine-independent protein sources to satisfy retailer sustainability protocols.
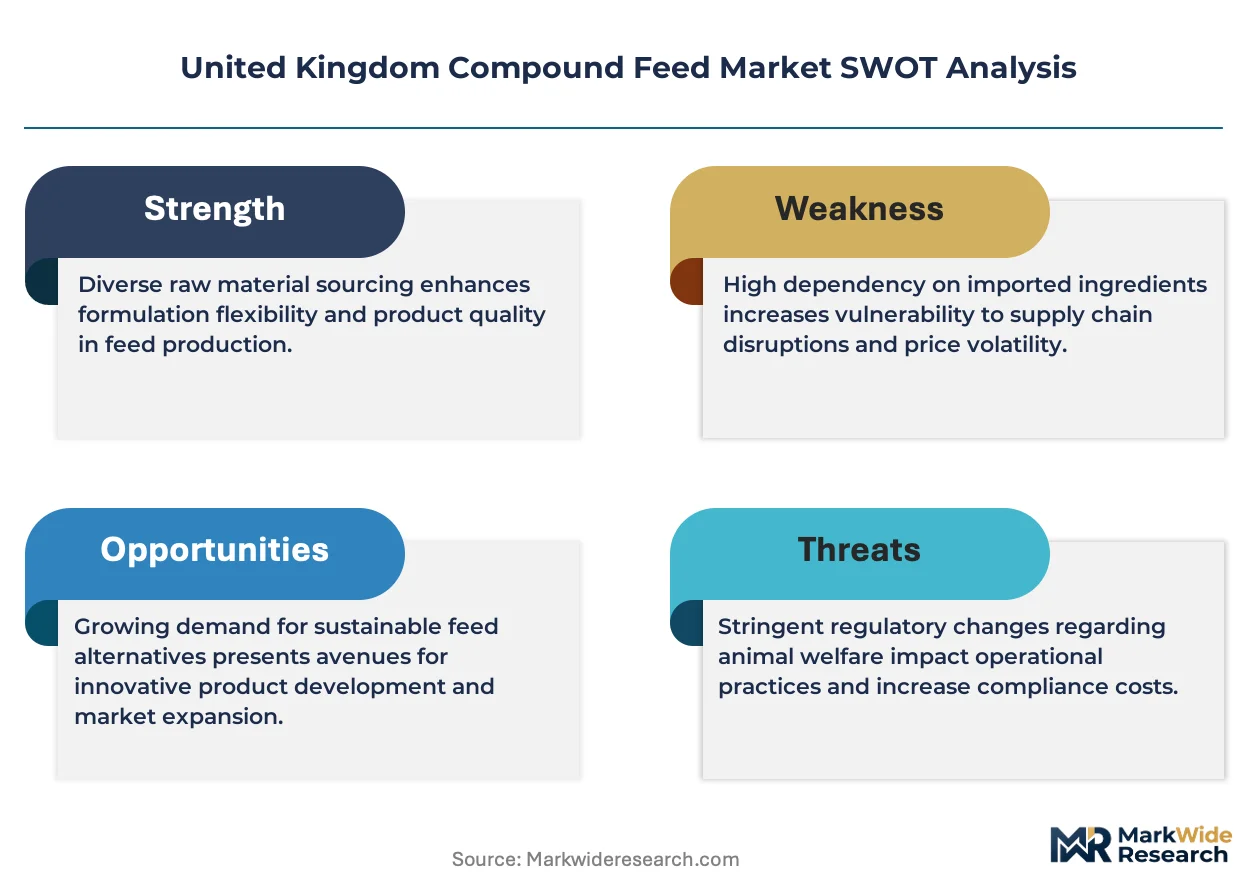
Defra's Agricultural Bill, the Environment Agency's nitrate vulnerable zone regulations, and Red Tractor assurance standards collectively shape feed composition mandates, antibiotic usage restrictions, and traceability requirements across the UK supply chain. These frameworks elevate compliance costs for smaller compounders while creating certification premiums for accredited manufacturers. Stakeholders must monitor the trajectory of post-Brexit trade agreements with South American soymeal exporters and the scaling of domestic insect protein and single-cell protein facilities to assess future ingredient cost structures and supply security.
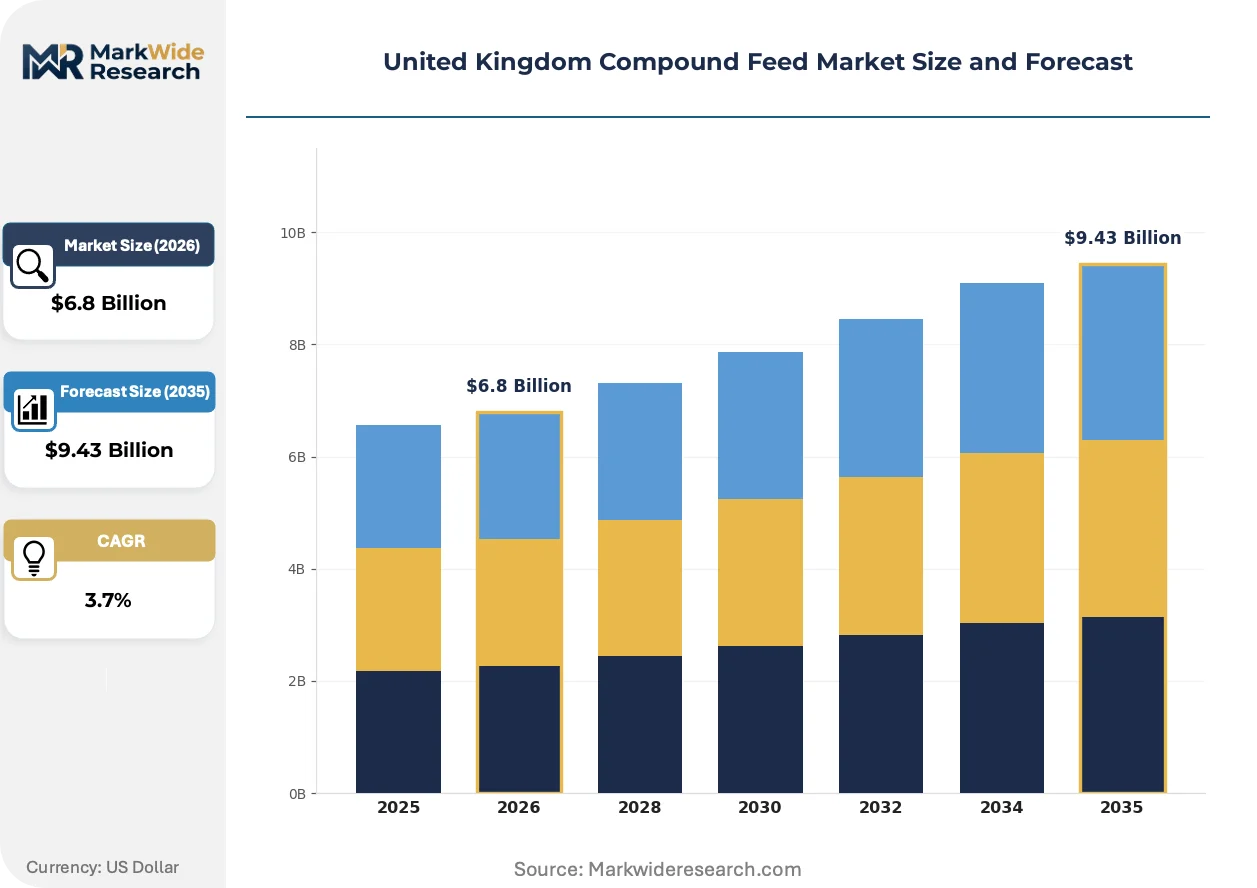
Market Dynamics
Defra's Environmental Land Management schemes and Red Tractor assurance standards are restructuring procurement priorities across the United Kingdom compound feed market, forcing manufacturers to requalify ingredient sourcing and reformulate rations around sustainability metrics.
Growth Catalysts
- Dairy precision nutrition:Large-scale dairy cooperatives in the Midlands and Yorkshire are expanding compound feed supplementation during extended winter housing periods, sustaining ruminant feed volume demand.
- Poultry integration density:East Anglia's vertically coordinated broiler operations are consolidating grower-processor relationships, driving standardized compound feed offtake at scale.
- Sustainable protein mandates:The UK's Agricultural Bill redirects subsidy structures toward marine-independent and domestic protein sourcing, accelerating interest in insect meal and single-cell protein inclusion.
Market Restraints
- Soymeal import dependency:Post-Brexit trade friction with South American exporters elevates price volatility for the primary protein meal input in poultry and pig rations.
- Nitrate vulnerable zone compliance:Environment Agency regulations restrict manure and slurry application timing, increasing compound feed costs for farmers in designated catchment areas.
- Antibiotic growth promoter phase-out:Red Tractor standards and veterinary prescribing guidelines have eliminated prophylactic usage, compressing margins for producers reliant on medicated feed formulations.
Strategic Opportunities
- Scottish aquafeed expansion:Salmon producers in the Highlands and Islands are seeking compound alternatives to fishmeal, creating demand for novel protein and oil sources.
- Digital feed optimization:Precision agriculture platforms that integrate real-time herd performance data with ration adjustment are penetrating mid-sized livestock operations previously served by commodity volume sales.
- ELM scheme carbon credits:Defra's sustainable farming incentive tier rewards low-carbon feed sourcing, offering certification premiums for compounders with verified supply chain emissions reductions.
Industry Challenges
- Formulation chemist scarcity:The technical expertise required to balance amino acid profiles, mineral bioavailability, and mycotoxin risk in alternative protein rations is concentrated among a narrow specialist cohort.
- Batch traceability infrastructure:Red Tractor and retailer audit requirements demand lot-level ingredient provenance tracking, forcing smaller compounders into costly ERP system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Compound Feed Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquafeed End User: Farmers, Livestock Producers, Aquaculture Operators, Commercial Feed Manufacturers Ingredient Type: Cereal Grains, Protein Meals, Additives, Minerals Distribution Channel: Direct Sales, Retail Outlets, Online Stores, Distributors |
| Companies Covered | AB Agri Ltd, ForFarmers UK Ltd, Wynnstay Group plc, Cargill Incorporated, Archer Daniels Midland Company, Alltech Inc, Nutreco N.V., Charoen Pokphand Group, De Heus Animal Nutrition B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Compound Feed Market Evolving Landscape
Digitalization is penetrating feed formulation and farm-level delivery, compressing the traditional separation between compound manufacturing and on-farm nutritional advisory services.
NIR spectroscopy and real-time dry matter analysis is virtualizing the feed formulation workflow. Dairy nutrition teams serving Midlands cooperatives are deploying handheld sensors to adjust rations within 24-hour cycles. This capability is compressing the value chain, enabling compounders to capture recurring advisory revenue streams previously captured by independent consultants.
Defra's Agricultural Bill and the Environment Agency's nitrate vulnerable zone regulations are tightening composition mandates and antibiotic usage restrictions. Compliance costs are elevating for smaller compounders lacking dedicated regulatory affairs functions. Accredited manufacturers with in-house quality assurance infrastructure are capturing certification premiums in Red Tractor-assured supply chains.
Retailer sustainability protocols are reshaping procurement specifications for Scottish salmon producers. Marine Stewardship Council and Aquaculture Stewardship Council chain-of-custody requirements are forcing compounders to document marine-independent protein substitution rates. This behavioral shift is most visible in the Highlands, where feed mills are restructuring supplier relationships around single-cell protein and algal oil verification systems.
United Kingdom Compound Feed Market Segmentation
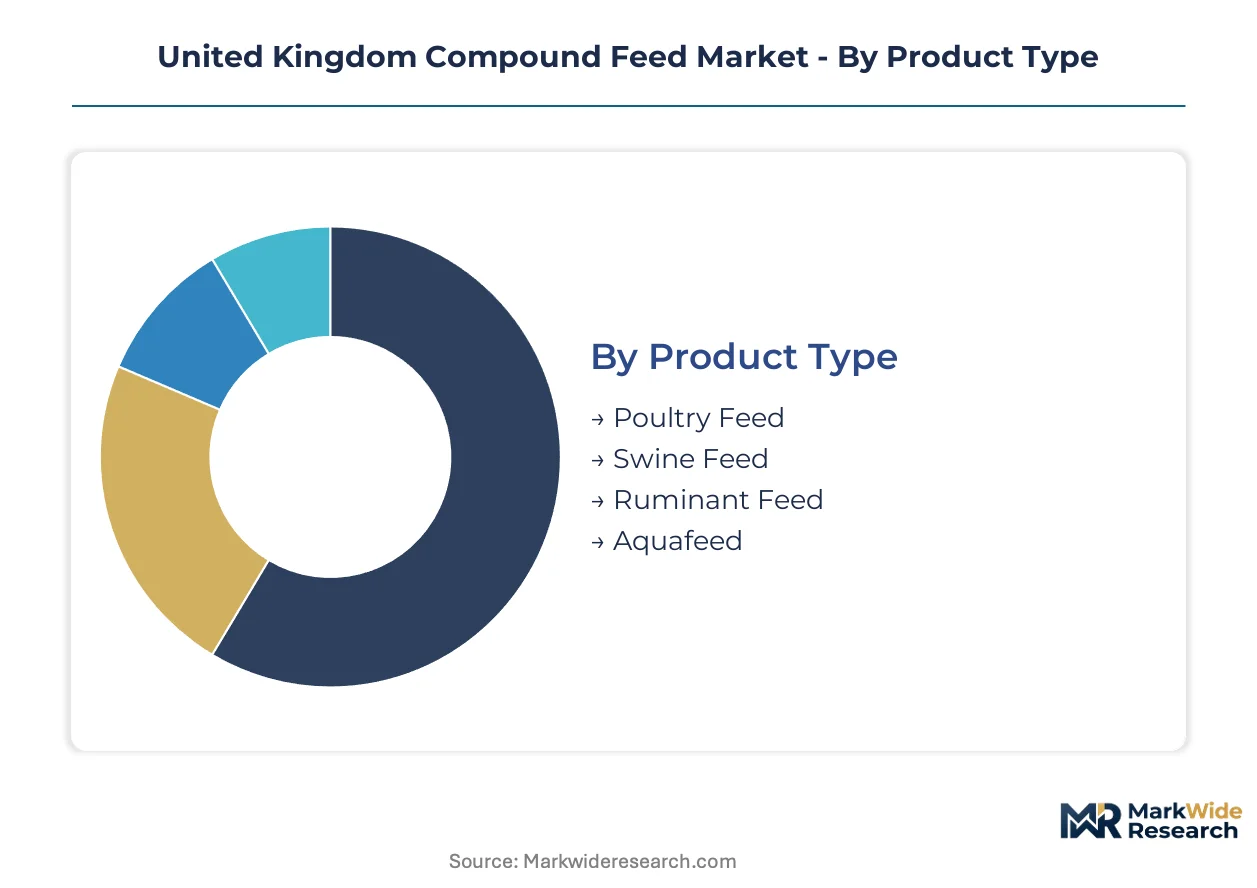
Segmentation in the United Kingdom compound feed market reveals how procurement priorities diverge across livestock species, buyer sophistication, and supply chain access. These divisions expose where margin pools concentrate and which customer cohorts drive specification changes.
Product Type:
Application dictates formulation complexity, with ruminant and poultry feeds commanding distinct technical capabilities and volume economics.
- Ruminant Feed:Complete and complementary diets formulated for dairy and beef cattle, emphasizing fiber digestibility and bypass protein protection. Demand clusters in Midlands dairy cooperatives and Yorkshire beef finishing units where winter housing periods extend compound supplementation cycles.
- Poultry Feed:Precision-formulated broiler and layer rations optimized for feed conversion ratios and carcass uniformity. East Anglia's vertically integrated operations drive standardized offtake, with processor-grower contracts specifying nutrient density and medication-free protocols.
- Swine Feed:Creep, grower, and finisher diets balancing amino acid profiles for lean tissue deposition. Specialist pig producers in eastern England seek customized formulations around antibiotic-free and zinc oxide reduction mandates.
- Aquafeed:Extruded salmon diets substituting marine-derived proteins with terrestrial and novel alternatives. Scottish Highlands producers pursue Marine Stewardship Council compliance through verified fishmeal reduction rates.
Ruminant feed holds installed capacity. Poultry feed is rotating up the share rankings.
End User:
Customer type determines whether transactions emphasize commodity volume or advisory intensity, splitting margin capture between manufacturers and service providers.
- Livestock Producers:Mid-scale dairy, pig, and poultry operations purchasing compound feed through technical service agreements. These buyers demand on-farm ration optimization and real-time formulation adjustments, compressing the traditional separation between manufacturing and consulting.
- Farmers:Smaller holdings and mixed enterprises sourcing standardized rations through distributor networks. Price sensitivity dominates purchasing decisions, with limited appetite for premium formulations or digital optimization tools.
- Aquaculture Operators:Scottish salmon producers with stringent sustainability protocols and chain-of-custody documentation requirements. Procurement specifications mandate marine-independent protein substitution rates and third-party certification.
- Commercial Feed Manufacturers:Regional compounders and premix blenders purchasing base mixes and micro-ingredients for downstream formulation. This segment concentrates in East Anglia and Yorkshire near grain handling infrastructure.
Livestock producers anchor advisory revenue streams. Aquaculture operators are climbing the specification ladder fastest.
Ingredient Type:
Supply concentration and price volatility across input categories reshape formulation economics and sourcing risk profiles.
- Cereal Grains:Wheat, barley, and maize providing metabolizable energy foundations, typically milled and pelleted with protein and mineral additions. Domestic harvest quality and import parity pricing drive cost fluctuations for UK millers.
- Protein Meals:Soymeal, rapeseed meal, and novel alternatives supplying essential amino acids for monogastric and ruminant diets. Post-Brexit trade friction with South American exporters elevates price uncertainty for poultry and pig ration formulations.
- Additives:Enzymes, acidifiers, and phytogenics replacing antibiotic growth promoters under Red Tractor and veterinary prescribing guidelines. Defra's Agricultural Bill accelerates interest in gut health and feed efficiency technologies.
- Minerals:Macro and trace mineral premixes balancing bioavailability and environmental excretion constraints. Nitrate vulnerable zone regulations in designated catchment areas restrict phosphorus and nitrogen loading, elevating precision supplementation requirements.
Cereal grains dominate volume throughput. Protein meals are expanding most quickly as formulation sophistication intensifies.
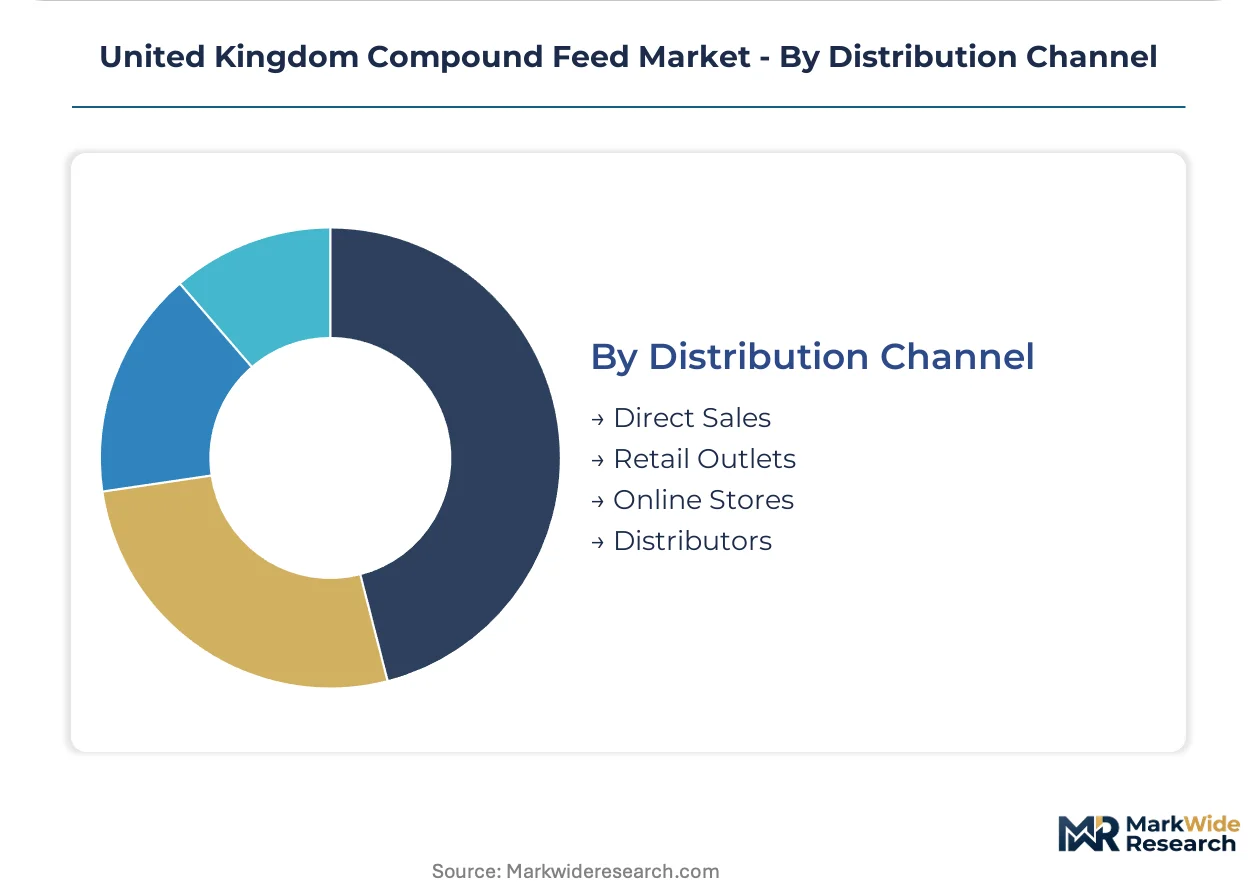
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to milling infrastructure.
- Direct Sales:Manufacturer-to-producer relationships for large-scale livestock operations and integrated poultry processors. These arrangements bundle compound supply with nutritional consulting and herd performance monitoring.
- Distributors:Regional feed merchants and agricultural cooperatives aggregating demand from smaller producers. Inventory holding and credit terms differentiate competitive positioning in this fragmented tier.
- Retail Outlets:Farm supply stores and merchant depots serving hobby farmers and smallholders with bagged and bulk options. Convenience and immediate availability outweigh formulation customization.
- Online Stores:Emerging digital procurement platforms for specialty additives, premixes, and small-batch formulations. Adoption concentrates among tech-enabled livestock producers seeking price transparency and rapid reordering.
Direct sales capture the advisory premium. Distributors are gaining ground through cooperative aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between England's intensive livestock corridors and Scotland's aquaculture-focused Highlands, with each geography imposing distinct formulation requirements on compound feed suppliers.
England East Anglia
Vertically integrated poultry operations dominate demand, with processor-grower contracts specifying standardized broiler rations and medication-free protocols. Defra's nitrate vulnerable zone regulations restrict manure application timing, elevating compound feed costs for farmers in designated catchment areas. Feed milling infrastructure clusters near grain handling terminals in Norfolk and Suffolk, enabling just-in-time delivery to contracted grower houses.
England Midlands
Dairy cooperatives anchor ruminant feed volume, extending compound supplementation through extended winter housing periods. The Environment Agency's phosphorus loading restrictions in the Severn and Trent catchments force precision mineral balancing in premix formulations. Technical service teams from major compounders maintain permanent on-farm presence across Staffordshire and Cheshire dairy belts.
England Yorkshire
Beef finishing units and pig operations concentrate in the Vale of York, sourcing customized grower and finisher diets around zinc oxide reduction mandates. Red Tractor assurance standards eliminate antibiotic growth promoter options, compressing margins for producers reliant on medicated formulations. Regional feed merchants aggregate fragmented smaller-holder demand through cooperative purchasing structures.
Scotland Highlands and Islands
Salmon producers drive aquafeed specification, pursuing Marine Stewardship Council compliance through verified fishmeal reduction rates. The Scottish Government's aquaculture growth strategy accelerates interest in marine-independent protein substitution. Feed mills from Inverness to Shetland restructure supplier relationships around single-cell protein and algal oil verification systems.
Wales
Sheep and beef enterprises in upland areas rely on complementary feed blocks during winter grazing deficits. Welsh Government sustainable farming schemes reward low-carbon feed sourcing, offering certification premiums for compounders with verified supply chain emissions reductions. Distribution runs through agricultural merchants in Aberystwyth and Welshpool serving dispersed hill farming communities.
United Kingdom Compound Feed Market Competitive Landscape
Capability concentration sits with integrated nutrition specialists; scale advantage sits with diversified agricultural conglomerates. The vendor base organizes around three tiers: multinational ingredient suppliers with captive formulation expertise, domestic cooperatives with embedded regional relationships, and specialist aquafeed compounders serving Scottish salmon producers. Consolidation pressure intensifies as compliance costs for Red Tractor and ELM scheme documentation favor manufacturers with dedicated quality assurance infrastructure. Strategic moves center on backward integration into alternative protein sourcing and digital platform deployment for real-time ration optimization.
Within the integrated nutrition tier, AB Agri Ltd and ForFarmers UK Ltd exemplify the convergence of manufacturing scale with on-farm advisory intensity. AB Agri anchors its position through supply chain control from grain procurement through technical support, while ForFarmers occupies a position serving ruminant cooperatives across the Midlands with dedicated species-specific teams. Cargill Incorporated represents the multinational archetype, extending digital feed optimization platforms to mid-sized livestock producers seeking precision agriculture tools.
| Leading Market Players |
|---|
| AB Agri Ltd |
| ForFarmers UK Ltd |
| Wynnstay Group plc |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Alltech Inc |
| Nutreco N.V. |
| Charoen Pokphand Group |
| De Heus Animal Nutrition B.V. |
| Others |
Value Network & Pricing Analysis
Road freight corridors connecting East Anglia grain terminals to Midlands dairy cooperatives carry cost dynamics that concentrate pricing power among integrated compounders while fragmenting margin capture for regional distributors. Defra's Environmental Land Management scheme compliance costs feed into downstream price differentiation between Red Tractor-accredited and standard feed formulations.
Pricing Analysis
Long-term offtake contracts between East Anglia poultry processors and integrated compounders dominate volume transactions, locking in feed conversion ratio guarantees and medication-free protocol pricing. Premium-mid-economy pricing differentiation separates Red Tractor-assured formulations from standard rations, with certification premiums widening as compliance costs escalate. Cost compression in the distributor tier intensifies because smaller compounders lack dedicated regulatory affairs infrastructure. Smaller mixed-enterprise farmers exhibit highest price sensitivity, while Scottish salmon producers demonstrate lowest sensitivity due to marine-independent protein substitution mandates.
Supply Chain Analysis
Tariff exposure between Brazil and the United Kingdom dominates supply chain risk for soymeal-dependent poultry and pig ration formulations. Raw material sourcing draws from Argentine soymeal, domestic wheat and barley harvests, and emerging Scottish insect protein facilities. Single-source vulnerability concentrates in South American protein meal imports, with Brexit-era trade friction amplifying price volatility. Distribution runs through direct manufacturer-to-producer relationships for large-scale operations, while regional agricultural merchants aggregate fragmented smaller-holder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as digital feed optimization tools embed compounders within continuous on-farm data loops, with NIR spectroscopy and real-time dry matter analysis creating interoperability between formulation chemistry and herd performance monitoring.
For Market Incumbents: Build switching-cost moats through captive technical service teams permanently stationed across Staffordshire and Cheshire dairy belts. Backward integration into domestic insect protein and single-cell protein facilities secures supply against South American trade friction. Defend against digital-native entrants by accelerating deployment of handheld sensor networks that virtualize ration adjustment workflows.
For New Entrants and Emerging Players: Welsh upland sheep and beef enterprises represent underpenetrated territory where complementary feed block demand concentrates through agricultural merchants in Aberystwyth and Welshpool. Scottish Highlands aquafeed specifications for Marine Stewardship Council compliance offer the most penetrable entry point, with marine-independent protein verification systems creating differentiation. Go-to-market through direct technical partnerships with salmon producers bypasses established compounder relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with integrated digital platforms and in-house alternative protein sourcing capabilities. Long-term viability rests on defensible advisory revenue streams displacing commodity volume margins. Acquisition targets should demonstrate established Red Tractor quality assurance infrastructure and embedded relationships with Midlands dairy cooperatives. The signal to watch is scaling velocity of domestic insect protein facility construction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Proteins | Scottish single-cell protein facilities reduce marine-derived input dependency for salmon feed compliance. |
| Digital Platform Deployment | NIR spectroscopy integration with Midlands dairy cooperatives compresses formulation-to-farm delivery cycles. |
| Red Tractor Certification Investment | In-house quality assurance infrastructure captures premiums as ELM scheme documentation costs escalate. |
| Technical Service Team Expansion | Permanent on-farm presence across Yorkshire beef finishing units locks in grower-processor contract flows. |
| Geographic Manufacturing Footprint Adjustment | East Anglia milling capacity proximity to Norfolk grain terminals optimizes just-in-time poultry feed delivery. |
Research Methodology
A standing panel of compound feed formulation chemists, Defra policy liaison officers, Red Tractor assurance auditors, and agricultural cooperative procurement managers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against Defra Agricultural Bill guidance documents, Environment Agency nitrate vulnerable zone compliance records, Marine Stewardship Council chain-of-custody databases, and Red Tractor assurance standards. Bottom-up volume modeling across livestock species segments triangulated against top-down agricultural output projections.
Scenario-bracketing around post-Brexit trade agreement trajectories and ELM scheme subsidy scaling informed the analytical framework across the projection horizon. Segmentation dimensions modeled include livestock species, buyer sophistication tier, ingredient type concentration, and distribution channel structure. CAGRs derived from trend extrapolation of dairy herd supplementation cycles, poultry integration density patterns, and aquafeed marine-independent protein substitution rates. Industry-specific forecast inputs encompassed Scottish salmon production growth targets and domestic insect protein facility commissioning timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified agricultural conglomerates or rapid digital platform deployment by technology entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market