
 Swine Feed Premix Market | 2026-2036
Swine Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Feed Premix Market Outlook
Veterinary nutritionist availability is collapsing across major pork-producing regions, forcing feed compounders to automate formulation decisions. Cargill, Incorporated leverages its digital nutrition platforms to bridge this expertise gap in North American operations. BASF SE anchors European premix supply through backward integration into vitamin A and E production. Evonik Industries AG specializes in precision amino acid matrices that reduce crude protein loads while maintaining lean growth rates.
Swine feed premix denotes a concentrated blend of vitamins, minerals, amino acids, and functional additives dosed at 0.5% to 3.0% of finished feed weight, manufactured via multi-stage micro-pulverization and thermal-stabilized coating to preserve thiamine and folic acid bioactivity through pelleting temperatures exceeding 85°C. Medicated premix carries the highest regulatory burden but commands premium positioning where veterinary prescription channels remain controlled. Vitamin premix formulations face margin compression from synthetic riboflavin oversupply, while mineral premix demand tilts toward organic chelate forms as copper and zinc environmental discharge rules tighten. Feed manufacturers represent the most consolidated end-user channel, though direct sales to commercial farms accelerate where integrators internalize blending capacity.
The EU Green Deal's Farm to Fork strategy, enforced by EFSA maximum copper thresholds and REACH zinc oxide reassessment, forces reformulation of standard grower premixes. China's MEE discharge permits for livestock operations constrain mineral premix loading rates in the Yangtze River basin. The US FDA Veterinary Feed Directive maintains prescription control over medically important antibiotics in starter premixes. Stakeholders must monitor whether amino acid precision feeding displaces mineral-heavy legacy formulations faster than regulator timelines suggest.
Market Dynamics
The EU Green Deal's copper and zinc discharge mandates are forcing simultaneous reformulation of mineral matrices and amino acid density adjustments across integrated pork operations, compressing legacy premix architectures while opening precision nutrition pathways.
Growth Catalysts
- Commercial farm consolidation in Vietnam:Integrated pork producers in the Mekong Delta are building captive feed mills, pulling concentrated premix demand away from merchant compounders.
- EFSA maximum copper thresholds:The EU Green Deal's Farm to Fork strategy mandates copper reduction in grower premixes, accelerating adoption of organic chelate forms and precision amino acid balancing.
- Micro-pulverization with thermal-stabilized coating:Advanced manufacturing processes preserve thiamine and folic acid bioactivity through pelleting temperatures exceeding 85°C, extending premix shelf stability in tropical storage conditions.
Market Restraints
- Synthetic riboflavin oversupply:Vitamin premix formulations face sustained margin compression as Chinese fermentation capacity floods the feed-grade vitamin market.
- Veterinary nutritionist scarcity:The collapsing availability of qualified formulators across North American and European pork regions forces feed compounders into expensive automation investments or formulation errors.
- REACH zinc oxide reassessment:Pending regulatory action threatens standard therapeutic mineral premixes used in European starter diets, creating formulation uncertainty and inventory risk.
Strategic Opportunities
- Direct sales channel expansion:Commercial farms with internalized blending capacity in Brazil and Thailand bypass traditional feed manufacturers, creating captive premix relationships.
- China's MEE discharge permits:Livestock operations in the Yangtze River basin face constrained mineral loading rates, creating demand for low-excretion precision premixes.
- Precision amino acid matrices:Convergence of crystalline lysine, methionine, and threonine dosing with near-infrared feed analysis enables real-time formulation adjustments at farm level.
Industry Challenges
- Veterinary Feed Directive compliance complexity:US FDA prescription control over medically important antibiotics in starter premixes requires specialized regulatory affairs staffing and documentation systems.
- Legacy formulation integration:Feed mills retrofitting thermal-stabilized coating lines face capital intensity and production downtime during multi-stage micro-pulverization upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Feed Premix Market |
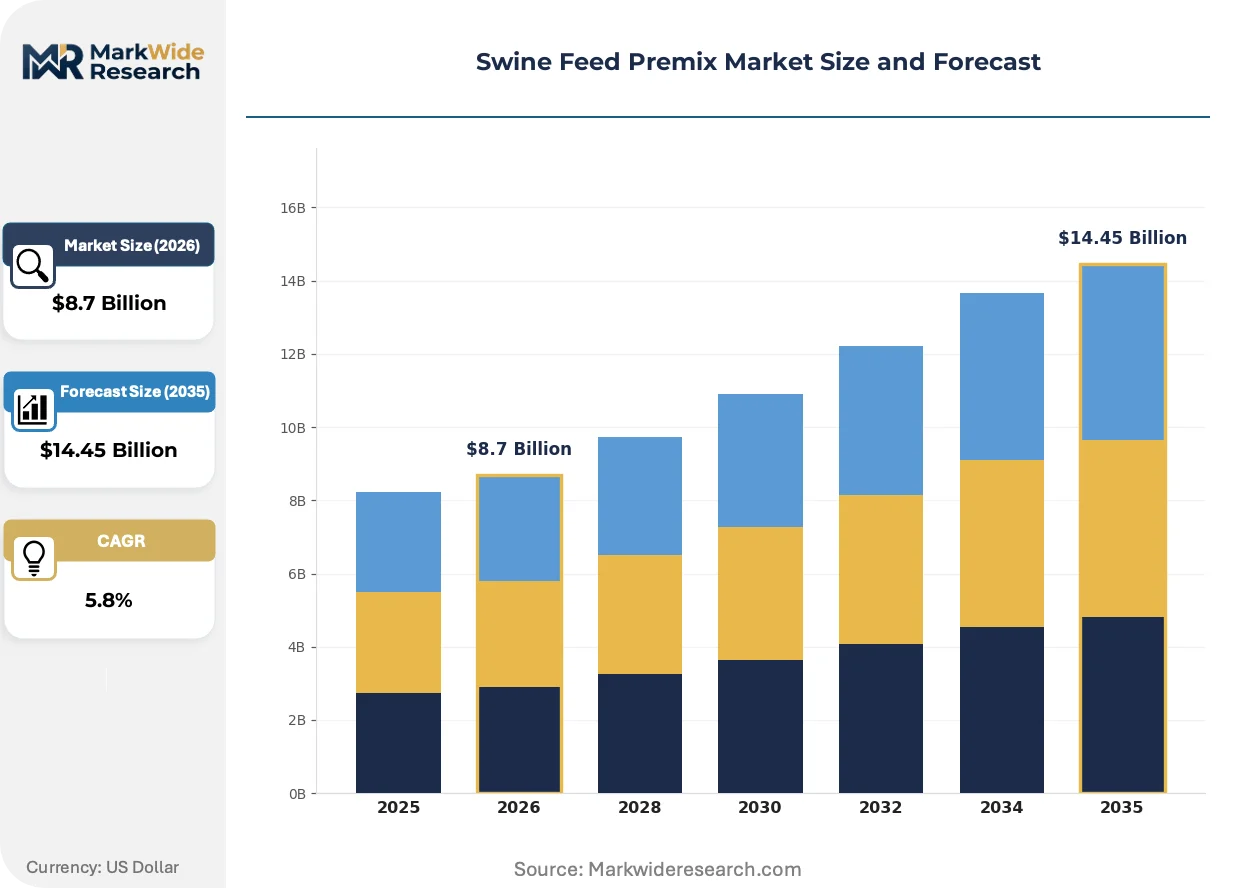
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated Premix, Non-Medicated Premix, Complete Feed, Additives Formulation Type: Vitamin Premix, Mineral Premix, Protein Premix, Energy Premix Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers End User: Commercial Farms, Smallholder Farms, Research Institutions, Feed Manufacturers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Evonik Industries AG, Koninklijke DSM N.V., BASF SE, Alltech, Lallemand Inc., Nutreco N.V., Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Feed Premix Market Strategic Shifts
Digital nutrition platforms and precision amino acid dosing are compressing the expertise gap left by retiring veterinary nutritionists, while regulatory pressure on mineral discharge accelerates formulation chemistry shifts.
Near-infrared spectroscopy coupled with cloud-based formulation algorithms is miniaturizing the decision-making architecture of premix specification. Commercial farms with captive blending capacity in Vietnam and Thailand are adopting these systems fastest, displacing reliance on external compounder expertise. The technology is miniaturizing the role of centralized formulation services into farm-level real-time adjustments.
REACH zinc oxide reassessment by ECHA is forcing European premix suppliers to eliminate therapeutic mineral levels from starter formulations. Grower operations in Germany and Denmark face the steepest reformulation costs as they pivot to organic copper chelates and elevated synthetic amino acid inclusion. Medicated premix categories carry the highest regulatory burden but command premium positioning where veterinary prescription channels remain controlled.
Integrators internalizing blending capacity are unbundling after-sales technical service from premix supply contracts. Large commercial farms in Brazil's Mato Grosso region now procure concentrated vitamin-mineral packs directly, replacing full-service compounder relationships. This pattern concentrates procurement leverage among the largest pork producers while fragmenting the merchant premix customer base.
Swine Feed Premix Market Segmentation
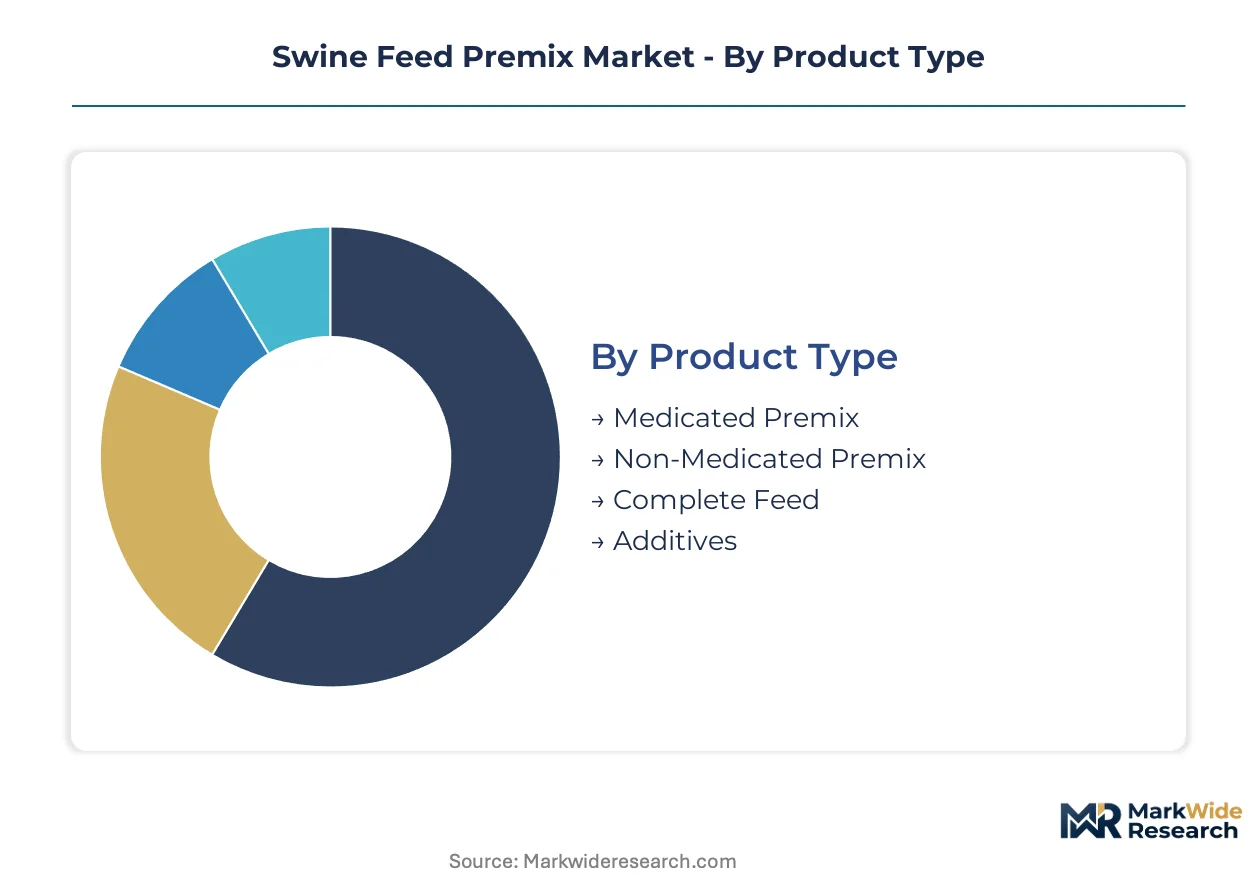
Swine feed premix segmentation reflects divergent channel economics across integrated and fragmented pork production systems. Product type and formulation choices determine whether premix flows through merchant compounders or captive mill operations.
Product Type:
Medicated and non-medicated premixes split sharply across prescription-controlled versus open distribution channels, with complete feed and additives occupying fundamentally different positions in the value chain.
- Medicated Premix:Concentrated blends containing veterinary-prescribed antimicrobials or coccidiostats dosed at therapeutic levels. Demand concentrates in US starter diets where FDA Veterinary Feed Directive maintains prescription gatekeeping, and in European markets where EFSA residue monitoring enforces strict withdrawal protocols.
- Non-Medicated Premix:Functional additive matrices excluding prescription actives, relying on organic acids, phytogenics, and enzyme complexes for gut health modulation. Vietnam's Mekong Delta integrated operations pull this segment fastest as captive mills internalize antibiotic-free formulation expertise.
- Complete Feed:Fully compounded rations with embedded premix at inclusion rates of 0.5% to 3.0%, typically bypassing separate premix procurement. Smallholder farms in Thailand and Indonesia purchase through distributor networks lacking on-farm blending infrastructure.
- Additives:Standalone functional ingredients—enzymes, mycotoxin binders, flavor enhancers—sold separately from vitamin-mineral bases. Direct sales channels from specialty suppliers to large Brazilian integrators dominate this segment's commercial flow.
Medicated premix dominates installed base through regulatory capture of veterinary prescription channels. Non-medicated premix is where expansion concentrates as antibiotic reduction mandates accelerate across major pork-producing jurisdictions.
Formulation Type:
Cost tier segmentation separates commodity vitamin and mineral inputs from precision amino acid matrices commanding formulation premiums.
- Vitamin Premix:Thermally stabilized blends of fat-soluble and water-soluble vitamins, with riboflavin and niacin comprising the largest volume constituents. Synthetic riboflavin oversupply from Chinese fermentation capacity compresses margins across standard formulations, pushing differentiation toward protected vitamin A and E variants.
- Mineral Premix:Inorganic salts and organic chelates of copper, zinc, iron, and manganese, with chelate forms commanding 40-60% price premiums over sulfates. EU Green Deal copper thresholds and REACH zinc oxide reassessment force rapid pivot toward reduced-loading organic matrices in German and Danish grower operations.
- Protein Premix:Crystalline amino acid concentrates—lysine, methionine, threonine, tryptophan—enabling low-crude-protein diet formulation. Precision dosing systems at Vietnam's commercial farms displace traditional soybean meal inclusion.
- Energy Premix:Fat and carbohydrate concentrates with emulsifier complexes for high-energy starter diets, primarily supplied to sow lactation formulations in North American farrow-to-finish systems.
Mineral premix retains the largest share of formulation spend. Protein premix is climbing the fastest as crystalline amino acid economics improve relative to conventional protein sources.
Distribution Channel:
Channel structure tracks farm scale and technical service requirements, with direct sales accelerating where integrators internalize blending competence.
- Direct Sales:Manufacturer-to-farm relationships for concentrated vitamin-mineral packs, technical formulation support, and real-time diet adjustment protocols. Brazil's Mato Grosso and Thailand's central plains regions show fastest adoption as large commercial farms unbundle from full-service compounders.
- Distributors:Regional warehousing networks serving small-to-mid-scale farms lacking volume leverage or technical staffing. Philippine and Indonesian archipelago geography sustains distributor relevance despite consolidation pressure.
- Wholesalers:Bulk commodity handlers moving standard premix formulations with minimal technical overlay, dominant in China's fragmented county-level feed mill landscape.
- Online Retail:E-commerce platforms for specialty additives and small-batch premix, currently limited to hobby farms and research institutions with non-standard specification requirements.
Distributors dominate installed base through geographic fragmentation and technical service bundling. Direct sales is gaining share fastest as farm-scale consolidation concentrates procurement leverage among top-tier integrators.
End User:
Customer type segmentation aligns with operational scale, regulatory exposure, and internalized formulation capability.
- Commercial Farms:Large-scale integrated pork producers operating captive feed mills or direct premix supply contracts. Vietnam's CP Group and Brazil's BRF internalize blending capacity, pulling concentrated premix rather than finished compound feed.
- Feed Manufacturers:Merchant compounders serving fragmented farm bases, facing margin compression as direct sales channels capture their largest customers. North American and European compounders invest in digital nutrition platforms to defend technical service differentiation.
- Smallholder Farms:Sub-scale operations purchasing complete feed or simple vitamin-mineral premix through distributor networks, concentrated in Southeast Asian and African production systems lacking capital for mill infrastructure.
- Research Institutions:Universities and government experimental stations procuring custom premix for controlled nutrition studies, representing minimal volume but disproportionate influence on formulation innovation pipelines.
Feed manufacturers dominate installed base through historical aggregation of fragmented demand. Commercial farms is where expansion concentrates as vertical integration accelerates across Southeast Asia and South America.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premix consumption patterns diverge sharply between geographies with captive feed mill infrastructure and those dependent on merchant compounders. Southeast Asia's integrated pork operations pull concentrated vitamin-mineral packs directly, while European producers navigate stringent mineral discharge mandates through reformulation. North American demand concentrates where veterinary prescription channels control medicated starter access.
United States
Large commercial farms in Iowa and North Carolina operate captive blending capacity, displacing traditional feed manufacturer relationships. The FDA Veterinary Feed Directive maintains prescription control over medically important antibiotics in starter premixes, forcing specialized regulatory compliance staffing. Minnesota's feed mill corridor invests in thermal-stabilized coating lines to preserve thiamine bioactivity through high-temperature pelleting.
Germany
Integrated pork producers in Lower Saxony face the steepest reformulation costs under EFSA copper thresholds and pending REACH zinc oxide reassessment. The EU Green Deal's Farm to Fork strategy accelerates adoption of organic chelate forms and precision amino acid balancing. Bavarian compounders pivot toward reduced-loading mineral matrices for grower operations.
China
Livestock operations in the Yangtze River basin confront MEE discharge permits constraining mineral premix loading rates. Zhengzhou and Shandong feed mill clusters scale micro-pulverization capacity to serve fragmented county-level demand. Sichuan-Chongqing integrators internalize blending competence, pulling concentrated premix rather than finished compound feed.
Vietnam
Commercial farm consolidation in the Mekong Delta drives fastest premix demand growth as CP Group and domestic integrators build captive feed mills. Operations scale protein output while antibiotic-free formulation expertise concentrates in integrated operations. Ho Chi Minh City's feed manufacturing corridor serves remaining fragmented smallholder demand through distributor networks.
Brazil
Mato Grosso and Santa Catarina integrators unbundle after-sales technical service from premix supply contracts, procuring concentrated vitamin-mineral packs directly. Large commercial farms displace full-service compounder relationships through internalized blending capacity. Paraná's pork belt adopts near-infrared spectroscopy coupled with cloud-based formulation algorithms for real-time diet adjustments.
Swine Feed Premix Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in premix supply, with backward integration into vitamin production separating the top tier from formulation-dependent competitors. The structure concentrates around agricultural conglomerates with captive raw material positions and specialty chemical firms with precision amino acid expertise. Two archetypes dominate: diversified nutrition platforms spanning multiple species and focused swine specialists with deep formulation chemistry. Competitive moves center on digital nutrition platform deployment and direct sales channel expansion to captive mill operations.
Within the integrated nutrition platform tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positions spanning feed manufacturing through protein processing. BASF SE anchors European supply through upstream vitamin A and E production, representing backward integration archetypes that control critical input costs. Evonik Industries AG occupies a precision specialist position, with its German corporate structure signaling deep amino acid chemistry expertise that enables low-crude-protein diet formulation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Evonik Industries AG |
| Koninklijke DSM N.V. |
| BASF SE |
| Alltech |
| Lallemand Inc. |
| Nutreco N.V. |
| Kemin Industries |
| Others |
Value Chain & Pricing Dynamics
Crystalline amino acid substitution for conventional soybean meal is redrawing procurement geography toward lysine fermentation clusters in China while collapsing protein premix pricing premiums across Southeast Asian captive mills. This input shift simultaneously concentrates vitamin-mineral sourcing leverage among backward-integrated suppliers and compresses formulation service margins for merchant compounders.
Pricing Analysis
Long-term offtake contracts dominate premix procurement between integrated pork producers and vitamin-mineral suppliers, insulating Brazilian and Vietnamese integrators from spot volatility in synthetic riboflavin markets. Three-tier pricing structure across organic chelate, standard sulfate, and commodity mineral grades reflects copper and zinc bioavailability differentiation. Pricing pressure stems from Chinese fermentation capacity flooding feed-grade vitamin markets, eroding margin buffers for non-integrated formulators. Smallholder farms purchasing through distributor networks exhibit highest price sensitivity, while captive mill operators in Mato Grosso and the Mekong Delta prioritize supply security over unit cost.
Supply Chain Analysis
China anchors global vitamin B and synthetic amino acid production, with Shandong and Zhengzhou feed mill clusters serving domestic county-level demand while exporting concentrated premix inputs. Germany and Denmark supply precision organic chelate technologies for EU Green Deal-compliant mineral matrices. The supply chain draws from corn-derived fermentation feedstocks, petrochemical precursors, and mineral ore concentrates. Single-source vulnerability concentrates in Chinese riboflavin fermentation capacity, where environmental discharge permit tightening threatens output stability. Distribution runs through direct manufacturer-to-farm channels for large integrators and regional warehousing networks for fragmented smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swine feed premix market sits in early-cycle expansion as precision amino acid dosing penetrates commercial farm operations faster than regulatory mineral reduction timelines. Vietnam's captive mill buildout and Brazil's direct procurement unbundling signal structural channel shifts that favor formulation technology over commodity supply.
For Market Incumbents: Shield margin position by accelerating backward integration into protected vitamin A and E production, countering Chinese fermentation oversupply. Invest in thermal-stabilized coating capacity to differentiate shelf stability for tropical storage conditions. Defend against digital nutrition platform entrants by embedding real-time formulation algorithms into customer technical service contracts. For New Entrants and Emerging Players: EU REACH zinc oxide reassessment fast-track certification for reduced-loading organic mineral premixes opens immediate white space in German and Danish grower operations. Target Vietnam's Mekong Delta antibiotic-free formulation segment, where captive mills seek non-medicated premix expertise absent from incumbent compounders. Deploy near-infrared spectroscopy bundling as the go-to-market wedge against full-service feed manufacturer relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European premix specialists holding EFSA-compliant formulation libraries but lacking Asian manufacturing footprint. Long-term viability hinges on amino acid precision feeding adoption curves outpacing mineral-heavy legacy replacement timelines. Watch for MEE discharge permit tightening in China's Yangtze River basin as the inflection signal for low-excretion premix demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Production | BASF SE's captive vitamin A and E supply anchors European premix cost positioning against Chinese fermentation imports. |
| Digital Nutrition Platform Deployment | Cargill's cloud-based formulation algorithms compress the veterinary nutritionist expertise gap across North American operations. |
| Direct Sales Channel Expansion | Manufacturer-to-farm relationships in Brazil's Mato Grosso bypass merchant compounders and capture procurement leverage. |
| Thermal-Stabilized Coating Capacity Addition | Minnesota feed mill corridor investments preserve thiamine bioactivity through 85°C pelleting for tropical export markets. |
| Precision Amino Acid Matrix Development | Evonik's crystalline lysine-methionine-threonine dosing enables low-crude-protein diets compliant with EU nitrogen discharge rules. |
Study Parameters
The analysis maps vitamin premix, mineral premix, protein premix, and medicated premix sub-sectors, each validated through procurement directors at integrated pork operations, formulation chemists at merchant compounders, and regulatory affairs specialists at vitamin manufacturers. Primary interviews with veterinary nutritionists, feed mill operations managers, and distributor channel partners combined with secondary validation against EFSA residue monitoring databases, FDA Veterinary Feed Directive compliance filings, and Chinese MEE discharge permit records. Bottom-up volume triangulation across captive mill capacity additions and top-down value reconciliation against raw material input costs anchored forecast construction.
Consistency checks validated volume and value outputs against feed industry association statistics, customs trade data for vitamin and amino acid imports, and SEC filings from publicly traded nutrition platforms. The analytical framework modeled product type, formulation chemistry, distribution channel, and end-user scale dimensions across the projection horizon. CAGRs derived from segmented growth rate reconciliation with macro protein demand drivers and regulatory compliance cost trajectories. Forecast inputs incorporated veterinary nutritionist availability indices and near-infrared spectroscopy adoption curves as technology penetration modifiers.
Underlying assumptions cover sustained commercial farm consolidation in Southeast Asia, stable EFSA copper threshold enforcement, and continued Chinese fermentation capacity expansion, with deviation risk concentrated in REACH zinc oxide reassessment outcomes and MEE permit tightening severity. Forecasts reflect these assumption layers with explicit sensitivity to regulatory timeline acceleration. Recalibration cycles align with material shifts in EU Green Deal implementation schedules and Vietnamese integrator captive mill completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
UAE Agriculture Market