
 Oxygenator Market | 2026-2036
Oxygenator Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygenator Market Analysis
Hollow-fiber polypropylene membranes are displacing older silicone-based designs and is realigning cost structures across the supply base. Medtronic leverages its integrated manufacturing footprint to sustain price competitiveness in membrane oxygenator production. Getinge AB anchors its position through deep specialization in extracorporeal systems for cardiac surgery. LivaNova PLC differentiates via concentrated R&D investment in coating technologies that reduce platelet activation during prolonged perfusion.
An oxygenator is a medical device that facilitates gas exchange between blood and a gaseous medium, typically employing microporous hollow fibers with surface areas of 2–4 square meters and rated blood flows of 1–7 liters per minute to oxygenate blood and remove carbon dioxide during cardiopulmonary bypass or extracorporeal membrane oxygenation. Membrane technology now dominates the product landscape due to superior biocompatibility profiles and reduced hemolysis rates compared with bubble oxygenators, which have retreated to niche pediatric and short-duration applications. ECMO represents the fastest-expanding application segment as hospitals build dedicated extracorporeal life support programs, while cardiac surgery remains the largest revenue pool by procedure volume. Gas exchange technology commands premium positioning where optical sensor integration enables real-time monitoring of blood parameters during perfusion.
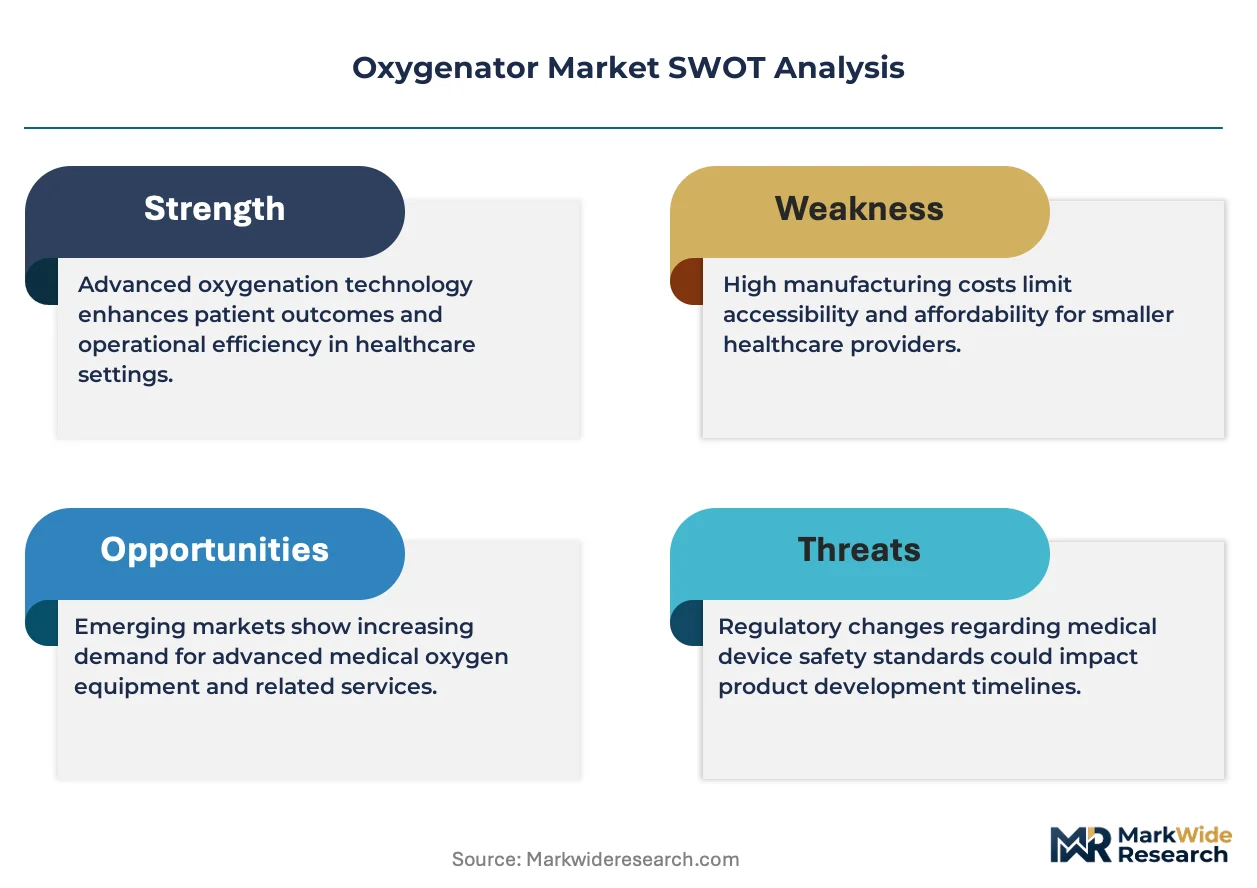
The FDA's 510(k) premarket notification framework governs device clearance, while ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements shape design verification protocols for manufacturers targeting US commercialization. The EU Medical Device Regulation imposes stricter clinical evidence thresholds through notified body conformity assessments, extending market access timelines for European launches compared with prior directive-era pathways. Stakeholders must monitor evolving CMS reimbursement determinations for ECMO procedures, as coverage expansion or contraction will directly alter hospital capital commitment to oxygenator inventory and disposable circuit procurement.
Market Dynamics
ECMO program expansion at major academic medical centers is restructuring hospital procurement patterns and concentrating demand among high-volume tertiary care institutions. This demand concentration is compressing supplier margins while elevating performance requirements for membrane biocompatibility and optical sensor integration.
Growth Catalysts
- CMS Reimbursement Expansion:Coverage determinations for extracorporeal life support procedures are reducing hospital capital risk and accelerating dedicated ECMO program investment across United States academic networks.
- Hollow-Fiber Membrane Technology:Polypropylene hollow-fiber designs with superior hemocompatibility profiles are capturing share from silicone-based alternatives in prolonged perfusion applications.
- FDA 510(k) Pathway Modernization:Streamlined cardiovascular device clearance timelines are shortening product development cycles and accelerating commercial access for next-generation oxygenator designs.
Market Restraints
- Polypropylene Supply Concentration:Hollow-fiber membrane feedstock depends on limited specialty polymer suppliers concentrated in East Asian manufacturing corridors, exposing cost volatility.
- EU MDR Clinical Evidence Burden:Stricter notified body conformity assessments under the Medical Device Regulation are extending European market access timelines versus prior directive-era pathways.
- Bubble Oxygenator Niche Persistence:Lower-cost bubble designs retain position in short-duration pediatric procedures, constraining membrane premium pricing power in select segments.
Strategic Opportunities
- Optical Sensor Integration:Real-time blood parameter monitoring during perfusion is expanding into premium product tiers and creating differentiation beyond gas exchange efficiency.
- Coating Technology Convergence:Heparin-based and phosphorylcholine surface modifications combined with hollow-fiber architectures are reducing platelet activation in prolonged ECMO runs.
- Latin American ECMO Infrastructure:Underpenetrated extracorporeal life support capacity in Brazil and Mexico presents white-space expansion as cardiovascular surgical volumes rise.
Industry Challenges
- Perfusionist Talent Scarcity:Specialized ECMO specialist training programs are failing to match program expansion velocity, creating operational bottlenecks at newly established centers.
- ISO 10993 Biocompatibility Verification:Extended design validation timelines for blood-contacting materials are compressing product refresh cycles and elevating R&D resource requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygenator Market |
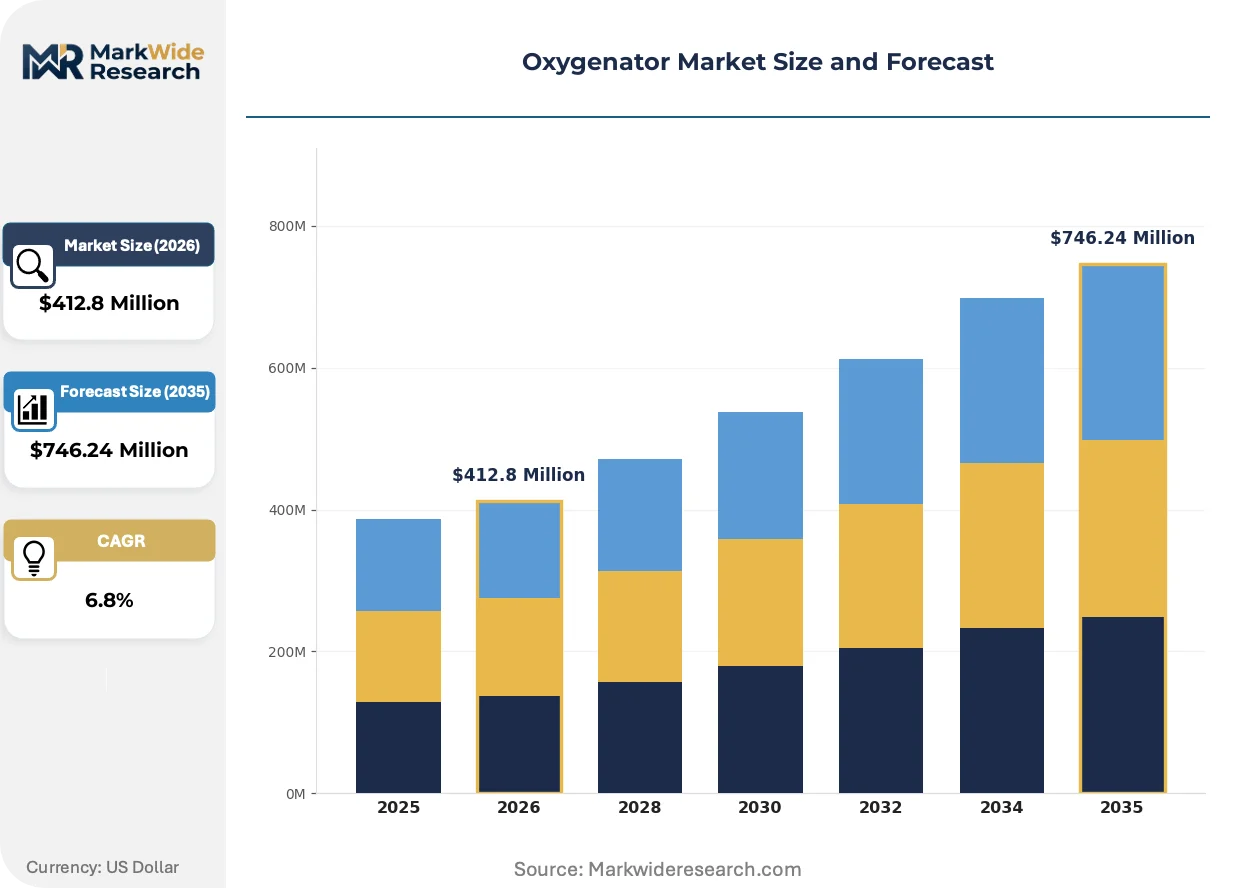
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $746.24 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane, Bubble, Film, Plate Technology: Microfluidics, Optical Sensors, Gas Exchange, Membrane Technology End User: Hospitals, Clinics, Homecare, Research Labs Application: Cardiac Surgery, Respiratory Support, Transplantation, ECMO |
| Companies Covered | Medtronic, Terumo Corporation, Getinge AB, LivaNova PLC, Eurosets Srl, Nipro Medical Corporation, Edwards Lifesciences Corporation, Xenios AG, Chalice Medical Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygenator Market Emerging Trajectories
Gas exchange technology is converging with digital monitoring capabilities and surface engineering advances to redefine performance benchmarks. These developments are elevating product complexity while compressing differentiation cycles.
Surface modification chemistry is expanding into mainstream oxygenator design as manufacturers deploy phosphorylcholine and heparin coatings to reduce thrombogenicity during extended perfusion. Cardiac surgery departments at high-volume United States academic centers are adopting these enhanced devices for complex procedures exceeding four hours. This coating adoption is expanding into standard product configurations and eroding the premium position of uncoated alternatives.
The EU Medical Device Regulation is tightening clinical evidence requirements for Class III cardiovascular devices through notified body conformity assessments. Manufacturers targeting European commercialization must now submit expanded premarket clinical data packages compared with prior directive-era submissions. This regulatory tightening is delaying European launches and redirecting commercialization sequencing toward United States FDA 510(k) pathways.
Hospital purchasing consortia are consolidating oxygenator procurement across multi-hospital health systems to extract volume-based pricing concessions. Integrated delivery networks are replacing individual hospital contracting and unbundling after-sales service from device supply agreements. This purchasing consolidation is most visible in United States metropolitan markets where academic medical center clusters dominate ECMO case volumes.
Oxygenator Market Segmentation
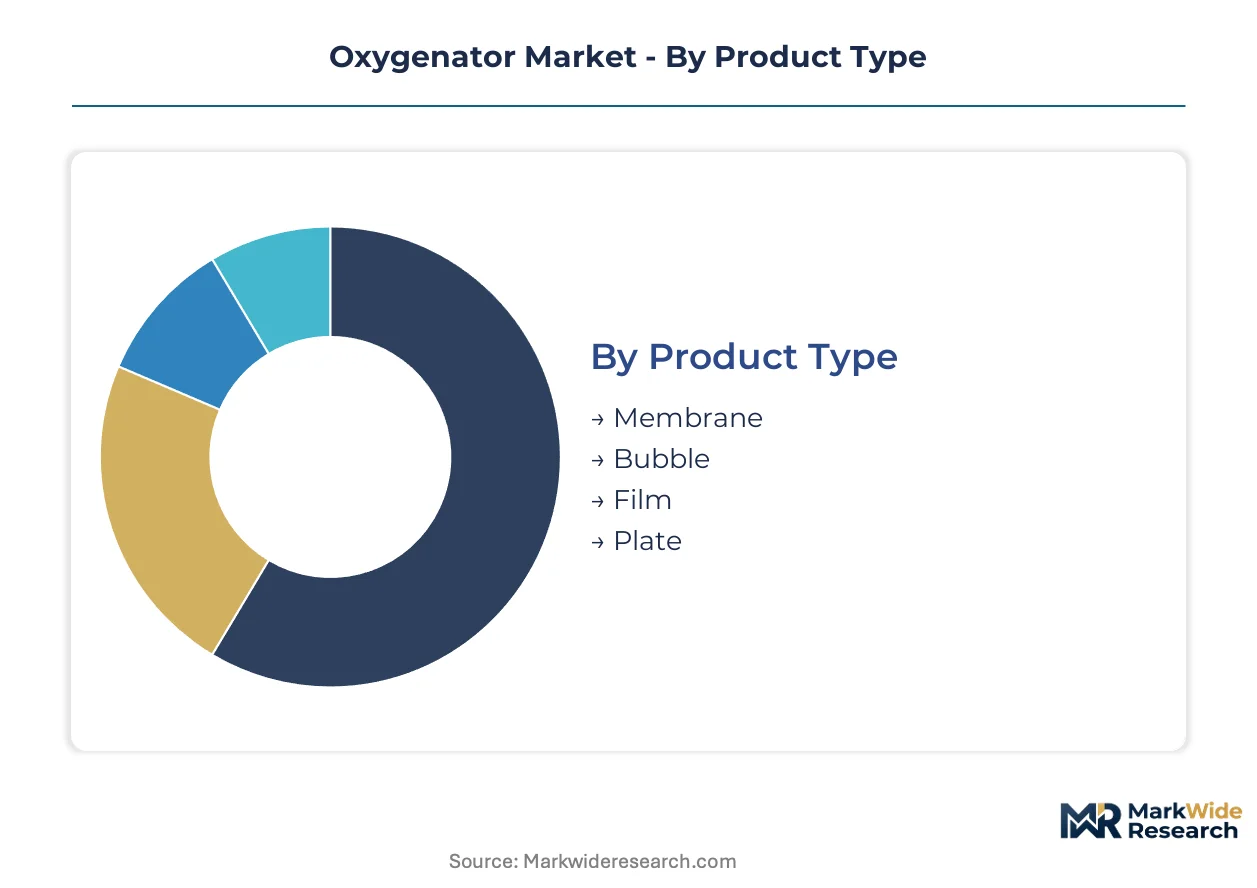
Oxygenator procurement patterns diverge sharply across clinical settings and technological specifications. Understanding these segment boundaries clarifies where membrane biocompatibility investments yield returns versus where cost minimization dominates purchasing decisions.
Product Type:
Material composition and gas exchange architecture define performance ceilings and reimbursement positioning.
- Membrane:Polypropylene hollow-fiber configurations with 2–4 square meter surface areas dominate prolonged perfusion. Academic medical centers in the United States are standardizing these for ECMO programs exceeding 48-hour duration.
- Bubble:Direct gas-blood contact designs persist in short-duration pediatric procedures. Lower capital requirements sustain procurement in cost-constrained hospital systems despite higher hemolysis rates.
- Film:Thin-sheet silicone membranes occupy niche applications requiring exceptional gas transfer efficiency. Specialty cardiac centers deploy these for complex aortic reconstructions.
- Plate:Parallel-plate configurations with limited priming volumes serve neonatal populations. Concentrated demand sits with pediatric cardiac surgery departments.
Mature deployment sits with Membrane oxygenators. Newer deployment is concentrated in Film configurations for specialized high-flow applications.
Technology:
Integration depth with monitoring systems and surface engineering sophistication separates pricing tiers.
- Microfluidics:Lab-on-chip architectures enable precise blood flow control at microliter scales. Research institutions are piloting these for organ preservation protocols prior to transplantation.
- Optical Sensors:Real-time oxygen saturation and hematocrit monitoring during perfusion commands premium positioning. High-volume United States academic centers mandate this capability for ECMO circuit management.
- Gas Exchange:Fundamental diffusion-based oxygenation without integrated monitoring represents the baseline tier. Cost-sensitive procurement in community hospital settings sustains this category.
- Membrane Technology:Surface-modified hollow-fiber systems with heparin or phosphorylcholine coatings reduce anticoagulant requirements. Steepest expansion trajectory is visible in cardiac surgery departments building extended perfusion capabilities.
Established infrastructure centers on Gas Exchange fundamentals. Capability investment is flowing fastest into Optical Sensors.
End User:
Capital intensity and clinical autonomy shape procurement authority and vendor relationship structures.
- Hospitals:Integrated delivery networks concentrate oxygenator purchasing across multi-faculty systems. ECMO program expansion at tertiary centers is restructuring supplier contracts toward volume-based frameworks.
- Clinics:Limited perfusion capabilities restrict demand to short-duration cardiac interventions. Outpatient surgical centers represent incremental volume for membrane oxygenator suppliers.
- Homecare:Portable ECMO configurations for bridge-to-transport or bridge-to-recovery are emerging. Regulatory clearance complexity limits commercial penetration.
- Research Labs:Ex vivo organ perfusion studies drive demand for specialized oxygenator configurations. University medical centers with transplant research programs anchor this segment.
Procurement maturity concentrates in Hospitals. Emerging demand formation is strongest in Research Labs.
Application:
Procedure duration and physiological complexity dictate membrane specifications and coating requirements.
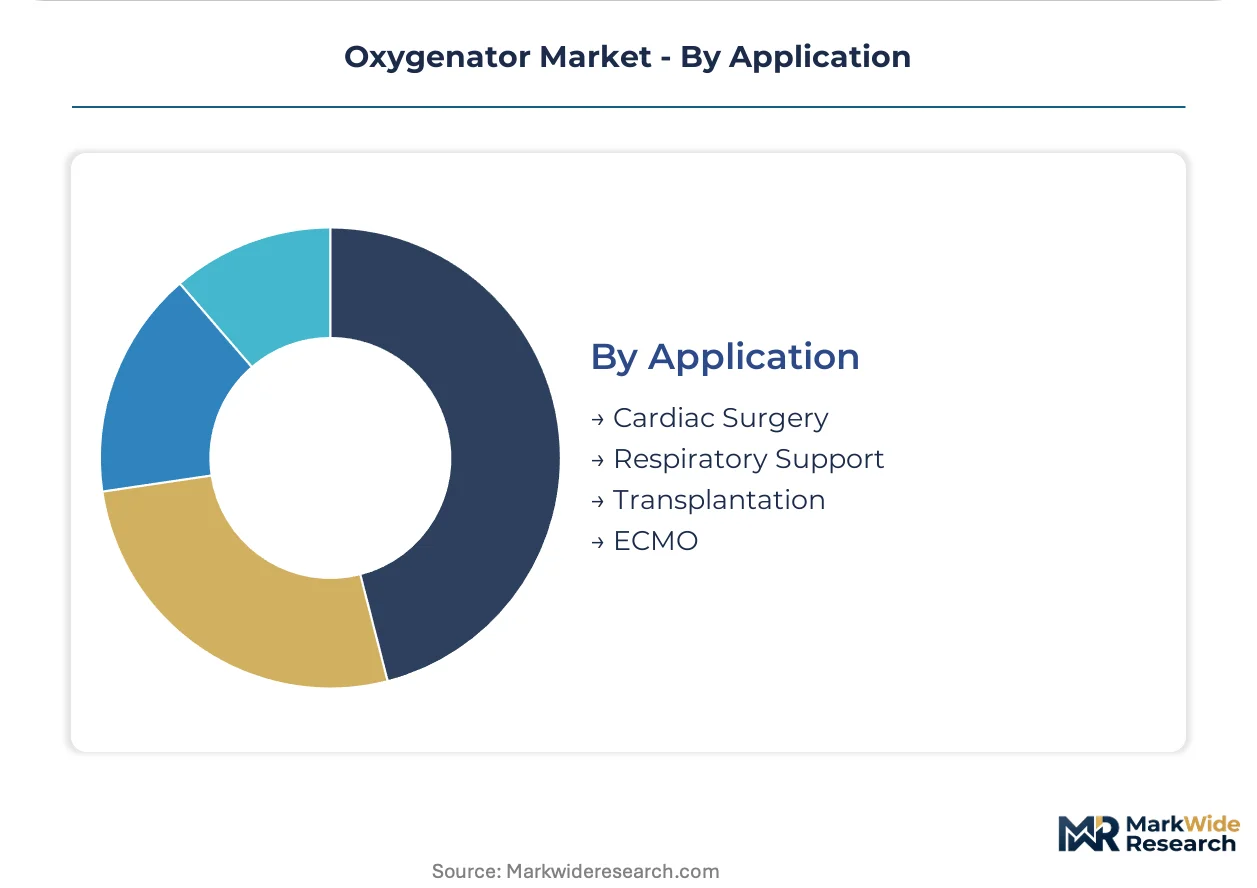
- Cardiac Surgery:Cardiopulmonary bypass for coronary artery bypass grafting and valve replacement constitutes the largest procedure volume. United States hospital networks are upgrading to surface-coated membranes for cases exceeding four hours.
- Respiratory Support:Acute respiratory distress syndrome management through extracorporeal carbon dioxide removal is gaining protocol adoption. Academic medical centers are establishing dedicated respiratory ECMO pathways.
- Transplantation:Ex vivo lung and heart perfusion for organ assessment and conditioning requires specialized oxygenator circuits. Organ procurement organizations are investing in transportable perfusion platforms.
- ECMO:Veno-arterial and veno-venous configurations for refractory cardiac and respiratory failure represent the fastest-climbing application. CMS reimbursement expansion is reducing hospital capital commitment risk for program establishment.
Volume concentration remains with Cardiac Surgery. Capability expansion is accelerating most rapidly in ECMO.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where ECMO program expansion at academic medical centers is restructuring procurement patterns. Hospital purchasing consortia are consolidating oxygenator supply across multi-facility health systems to extract volume-based pricing concessions.
United States
ECMO program investment at tertiary centers is accelerating membrane oxygenator procurement. The FDA's streamlined 510(k) cardiovascular device pathway shortens clearance timelines for next-generation designs. Major academic medical center clusters in Boston, New York, and Houston are standardizing surface-coated hollow-fiber systems for extended perfusion.
Germany
Cardiac surgery volume at university hospitals sustains membrane oxygenator demand for complex procedures. The EU Medical Device Regulation imposes stricter notified body conformity assessments, extending market access timelines versus prior directive-era pathways. Industrial concentration in Baden-Württemberg and Bavaria anchors specialized extracorporeal device manufacturing.
Japan
Aging demographics and rising cardiovascular disease prevalence expand cardiac surgery procedure volumes. PMDA regulatory frameworks govern device approval, with manufacturers navigating biocompatibility verification protocols aligned with ISO 10993 standards. Tokyo and Osaka metropolitan medical centers are upgrading to optical sensor-integrated oxygenator systems.
China
Hospital infrastructure investment and expanding cardiovascular surgical capacity drive membrane oxygenator procurement growth. NMPA medical device registration requirements shape commercialization sequencing for domestic and multinational suppliers. Yangtze River Delta medical device manufacturing corridors are developing hollow-fiber membrane production capabilities.
Brazil
Underpenetrated extracorporeal life support capacity presents expansion opportunity as cardiovascular surgical volumes rise. ANVISA medical device regulations govern import and commercialization pathways for oxygenator suppliers. São Paulo and Rio de Janeiro academic medical centers are establishing dedicated ECMO programs with concentrated procurement authority.
Oxygenator Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated medical technology conglomerates commanding scale advantages in membrane production while niche specialists retain position in coating technologies and pediatric configurations. The competitive terrain stratifies into three archetypes: diversified cardiovascular device conglomerates with captive oxygenator portfolios, focused extracorporeal system specialists, and regional contract manufacturers serving cost-sensitive procurement channels. Dominant competitive moves include backward integration into hollow-fiber membrane production and strategic technology licensing for surface modification chemistry.
Among diversified cardiovascular device conglomerates, Medtronic and Edwards Lifesciences exemplify scale-driven positioning through integrated manufacturing footprints and broad hospital contracting relationships. Getinge AB and LivaNova PLC occupy specialist positions concentrated in extracorporeal systems and coating technologies respectively. Terumo Corporation represents Asia-Pacific headquartered competition with established perfusion product lineages. Eurosets Srl and Xenios AG exemplify European specialist positioning navigating MDR compliance requirements.
| Leading Market Players |
|---|
| Medtronic |
| Terumo Corporation |
| Getinge AB |
| LivaNova PLC |
| Eurosets Srl |
| Nipro Medical Corporation |
| Edwards Lifesciences Corporation |
| Xenios AG |
| Chalice Medical Ltd |
| Others |
Supply Flow & Price Mechanics
Hospital purchasing consortia consolidation across United States integrated delivery networks is compressing supplier margins and forcing membrane manufacturers to absorb cost volatility from polypropylene feedstock markets. This demand-side concentration is reshaping how hollow-fiber oxygenator producers structure volume-based contracts and where they source specialty polymer inputs.
Pricing Analysis
High-volume academic medical center procurement commands standard-tier membrane oxygenators at compressed margins, while optical sensor-integrated configurations sustain premium positioning through differentiated monitoring capabilities. Price differentiation separates FDA 510(k)-cleared devices with heparin coatings from uncoated alternatives and bubble oxygenator economy tiers. Pricing pressure stems from GPO contract consolidation, with community hospitals exhibiting highest price sensitivity and ECMO program directors at tertiary centers prioritizing performance over unit cost.
Supply Chain Analysis
Specialty polypropylene hollow-fiber production rests on East Asian chemical manufacturers in Japan, South Korea, and China, with membrane extrusion and module assembly concentrated in United States and European medical device corridors. Raw material dependencies include medical-grade polypropylene resin, heparin coating compounds, and optical sensor components. Single-source vulnerability in specialty polymer supply creates exposure to logistics disruptions and tariff friction. Distribution runs through hospital GPOs and specialized cardiovascular device distributors serving cardiac surgery departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygenator market sits in a technology-transition phase as hollow-fiber membrane designs with integrated optical monitoring displace legacy silicone configurations and uninstrumented alternatives.
For Market Incumbents: Acquire hollow-fiber membrane production capabilities to secure polypropylene supply continuity against East Asian feedstock volatility. Deepen coating technology portfolios through phosphorylcholine surface modification licensing to defend against emerging specialists. Lock in multi-year GPO contracts at major United States academic medical center clusters before procurement consolidation accelerates further. For New Entrants and Emerging Players: Coating technology convergence presents entry leverage for specialized surface engineering firms targeting extended ECMO perfusion protocols. White-space concentration sits with pediatric plate oxygenator configurations and Latin American ECMO infrastructure buildout in Brazil and Mexico. Go-to-market positioning should emphasize perfusionist training partnerships to overcome specialist talent scarcity at newly established centers. For Investors and Strategic Acquirers: The window for entry favors coating technology specialists with ISO 10993 biocompatibility validation and notified body relationships under EU MDR frameworks. Long-term viability hinges on regulatory clearance velocity and hospital system penetration depth. Watch CMS reimbursement determinations for ECMO procedures as the critical inflection signal for hospital capital commitment to oxygenator inventory expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Captive polypropylene hollow-fiber supply insulates Medtronic and Getinge from East Asian feedstock volatility. |
| Optical Sensor Platform Development | Real-time hematocrit monitoring integration commands premium positioning at Houston and Boston academic medical centers. |
| EU MDR Notified Body Certification | Expanded clinical evidence packages delay European launches but create barrier against unvalidated competitors. |
| Hospital System Partnership Agreements | Multi-faculty GPO contracts consolidate procurement authority and lock out secondary suppliers. |
| Coating Technology Licensing | Heparin and phosphorylcholine surface modifications reduce anticoagulant requirements in prolonged ECMO runs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with perfusionists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Primary fieldwork covered cardiovascular device manufacturers and ECMO program directors at academic medical centers. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body assessments, CMS reimbursement determinations, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across manufacturer shipment records, hospital inventory systems, and GPO contract disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology integration depth, end-user capital intensity, and application procedure duration. CAGRs derived from fitted growth curves applied to hospital ECMO program expansion trajectories and cardiac surgery volume projections. Industry-specific inputs incorporated ISO 10993 biocompatibility validation timelines and FDA 510(k) clearance velocity assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian polypropylene supply, sudden CMS reimbursement contraction for ECMO procedures, and breakthrough alternatives to hollow-fiber gas exchange architecture. Forecasts reflect documented assumptions about regulatory pathway stability and hospital capital commitment continuity. A small set of named triggers warrants ongoing watch: FDA guidance shifts on cardiovascular device predicates, EU MDR implementation delays, and perfusionist training program expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Home Sleep Apnea Testing Devices Market