
 Security Services Market | 2026-2036
Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Security Services Market Analytics
Market Overview
Outsourced security provisioning is consolidating across enterprise and government buyers as organizations abandon fragmented in-house models for integrated vendor relationships. Allied Universal leverages its national guard-force footprint to anchor physical security contracts for Fortune 500 campuses. Securitas AB competes through technology-augmented guarding, blending patrol officers with remote monitoring infrastructure. IBM sustains cybersecurity leadership through its managed security services division, defending enterprise cloud and hybrid environments against advanced persistent threats.
Security services encompass the design, deployment, and ongoing management of protective measures spanning personnel, electronic systems, and digital infrastructure, typically governed by service-level agreements specifying response times, coverage hours, and incident escalation protocols. The primary commercial purpose centers on risk transfer—converting uncertain loss exposure into predictable operational expenditure while meeting insurance and regulatory compliance requirements. Man-guarding remains the largest revenue pool though margin compression from labor costs pushes vendors toward integrated solutions combining electronic security with on-site personnel. Cybersecurity represents the fastest-expanding segment as ransomware frequency and regulatory penalties escalate enterprise willingness to outsource threat detection and response.
The EU AI Act, GDPR, and the US FAA reauthorization provisions for critical infrastructure security collectively reshape procurement specifications and vendor qualification criteria across jurisdictions. NIST Cybersecurity Framework adoption by US federal contractors and state-level data breach notification laws further segment compliance obligations by customer type and geography. Stakeholders must monitor evolving biometric deployment restrictions and cross-border data transfer rules to anticipate which service bundles will carry premium pricing versus regulatory exclusion.
Market Dynamics
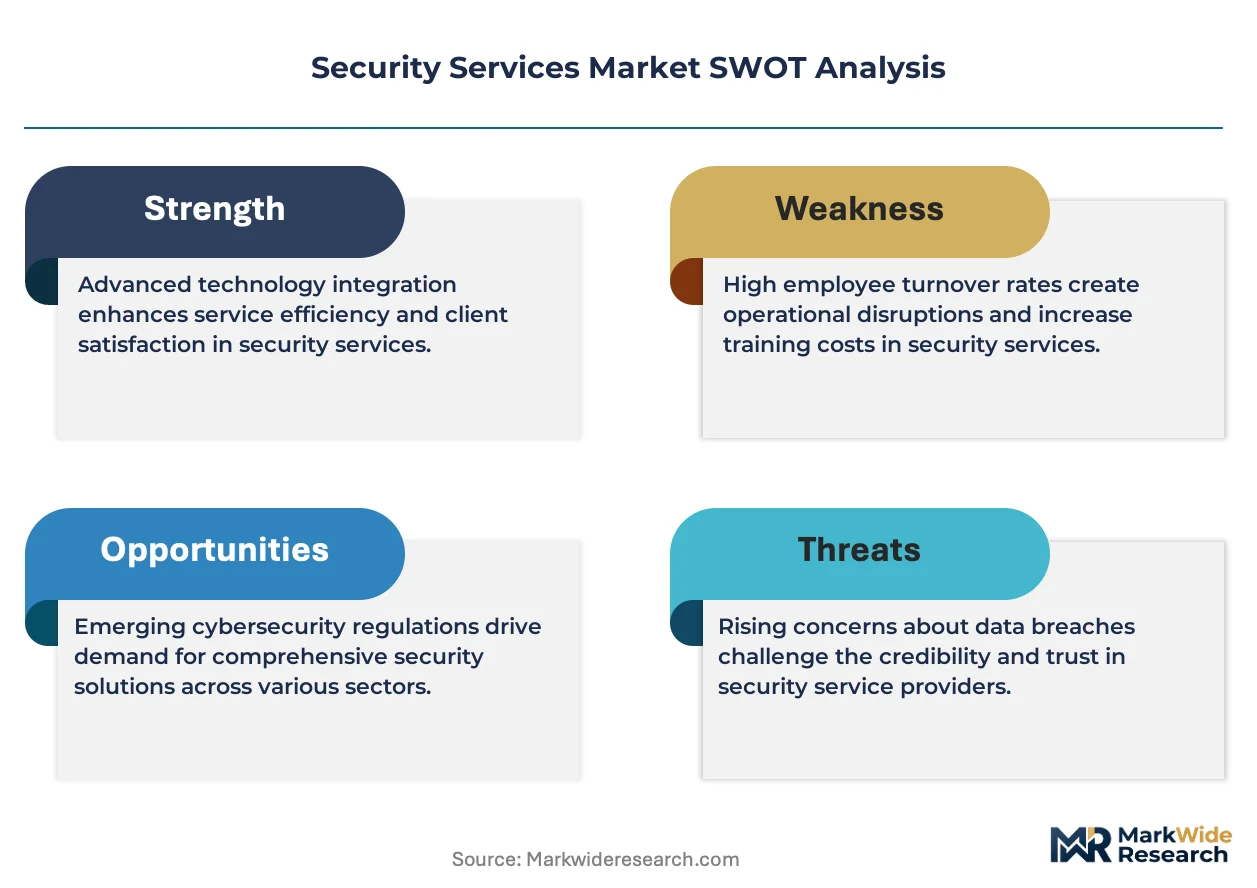
Labor cost inflation and biometric surveillance restrictions are compressing margins for pure man-guarding vendors while accelerating technology-augmented service bundling across enterprise accounts.
Growth Catalysts
- Critical infrastructure mandates:The US FAA reauthorization provisions mandate enhanced perimeter security for aviation facilities, driving contracted guard-force and electronic surveillance procurement at federally regulated sites.
- GDPR enforcement:European data protection authorities are imposing substantial penalties for inadequate cybersecurity incident response, compelling mid-market enterprises to outsource threat detection and breach containment to managed security service providers.
- Ransomware frequency:The surge in double-extortion attacks against healthcare and municipal systems is forcing risk-averse organizations to abandon self-managed security operations centers in favor of 24/7 vendor-monitored environments.
Market Restraints
- Wage compression:Guard-force labor costs in the United States and Germany are rising faster than contract escalation clauses permit, squeezing vendor margins and forcing service reductions.
- Biometric deployment friction:The EU AI Act's prohibited-practices list for real-time remote biometric identification in public spaces is forcing vendors to retrofit or abandon facial recognition deployments across European commercial properties.
- Insurance capacity constraints:Cyber insurance underwriters are tightening coverage terms and elevating minimum security control requirements, excluding smaller enterprises from affordable risk transfer options.
Strategic Opportunities
- India's smart city infrastructure:Municipal surveillance and integrated command-and-control center deployments across tier-1 and tier-2 cities present substantial contract opportunities for technology-augmented guarding providers.
- Converged physical-cyber offerings:Vendors blending on-site personnel with SOC-as-a-service capabilities are capturing premium pricing from financial services clients seeking unified risk visibility.
- US state-level data breach laws:The patchwork of notification and encryption mandates across California, New York, and Texas is creating compliance advisory service attach rates for regional security providers.
Industry Challenges
- Cleared personnel scarcity:Federal contractor security roles requiring security clearances face acute candidate shortages, extending time-to-fill metrics and elevating retention premiums.
- Legacy access control integration:Enterprises with decades-old physical access systems encounter prohibitive retrofit costs when connecting to modern cloud-based identity management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Services Market |
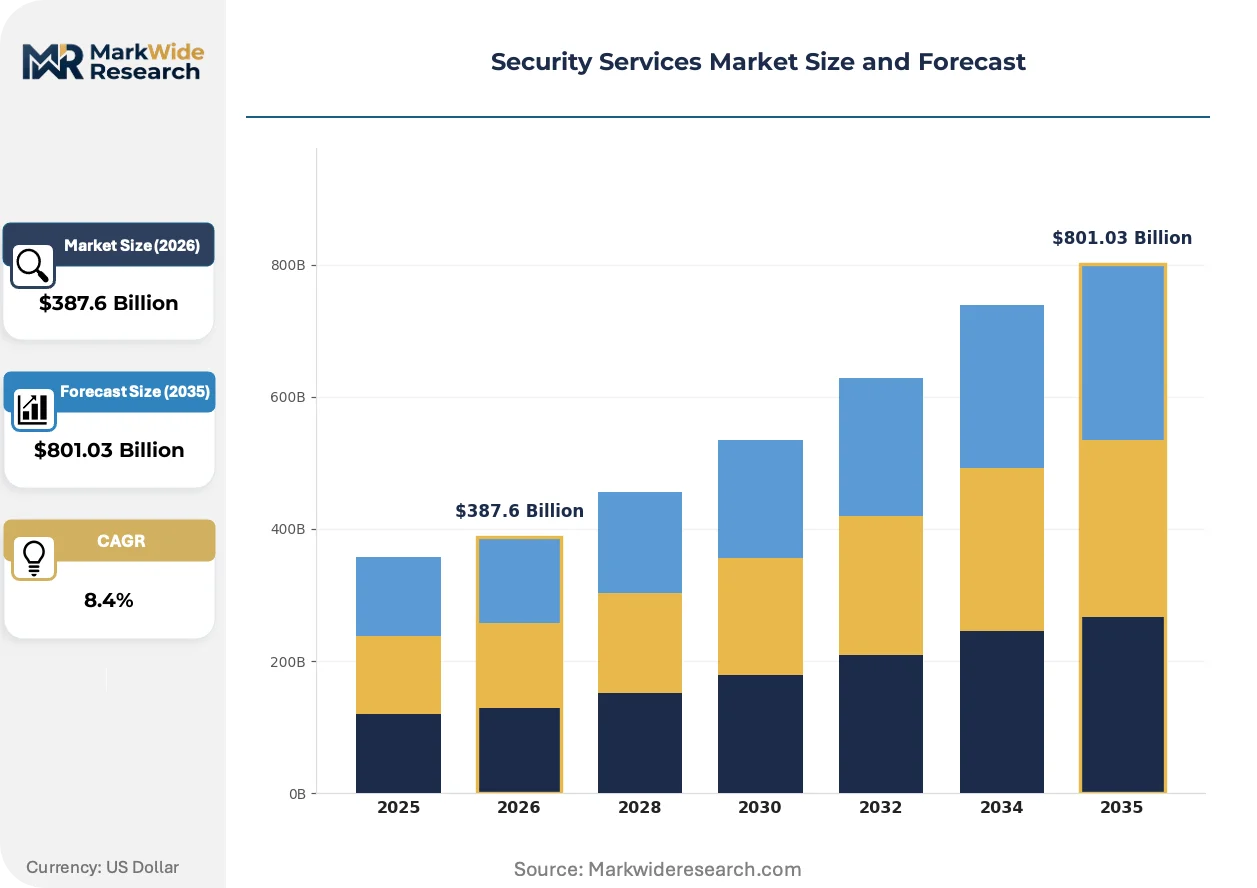
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $801.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Man-Guarding, Electronic Security, Cybersecurity, Integrated Solutions End User: Government, Commercial, Residential, Industrial Technology: Access Control, Surveillance Systems, Alarms, Biometrics Application: Event Security, Asset Protection, Risk Management, Personal Security |
| Companies Covered | IBM, Accenture, Securitas AB, Allied Universal, G4S plc, Cisco Systems, Inc., Microsoft Corporation, Check Point Software Technologies Ltd., LevelBlue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Services Market Evolving Landscape
Artificial intelligence is embedding across both physical and digital security service delivery, compressing response timelines while introducing new compliance complexities for vendors operating across multiple jurisdictions.
Drone-based perimeter surveillance is expanding into critical infrastructure protection, with oil terminals and power generation facilities deploying autonomous aerial patrols to supplement fixed camera networks. Energy sector buyers are adopting these systems fastest, driven by remote site accessibility challenges and insurance premium reductions. The technology is expanding into traditional man-guarding contracts by enabling smaller on-site teams to cover larger geographic footprints with real-time aerial visibility.
The EU AI Act's risk-based classification system for biometric and behavioral analytics is forcing vendors to re-engineer European product roadmaps and documentation practices. Systems designated as high-risk must undergo conformity assessments and maintain human oversight protocols, adding deployment friction and compliance cost. Commercial real estate operators in France and Germany are delaying facial recognition rollouts pending legal certainty, shifting investment toward non-biometric anomaly detection.
Enterprise buyers are consolidating vendor relationships through integrated facilities management contracts that bundle security with cleaning, maintenance, and reception services. This purchasing pattern concentrates contract value with multi-service providers and marginalizes standalone security specialists. The trend is most pronounced in the United States, where Fortune 500 campus operators seek single-accountability structures and reduced procurement administrative burden.
Security Services Market Segmentation
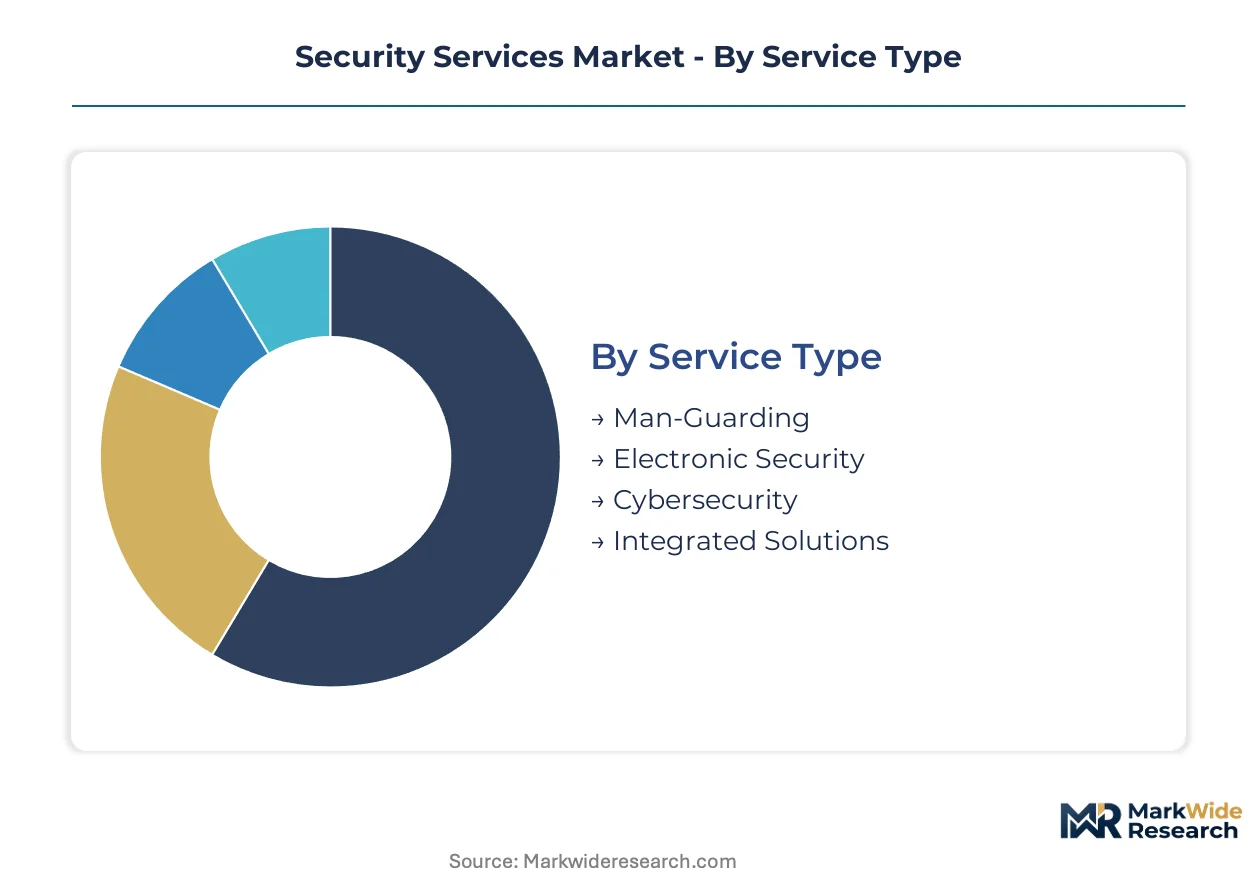
Security services segmentation reveals how procurement patterns diverge between legacy man-guarding contracts and technology-augmented bundles. Organizations now replace fragmented vendor relationships with integrated service tiers that consolidate physical and digital protection under unified accountability structures.
Service Type:
Replacement cycles accelerate as enterprises abandon siloed security models for converged vendor relationships that compress procurement overhead.
- Man-Guarding:On-site personnel deployment for perimeter control, access verification, and incident response remains the foundational revenue layer. Demand concentrates in United States commercial real estate and German industrial facilities where labor union agreements and insurance mandates sustain contract volumes despite margin pressure from wage inflation.
- Cybersecurity:Managed detection and response services, SOC-as-a-service, and threat intelligence subscriptions defend enterprise cloud environments. Financial services institutions in New York and healthcare systems across California represent the fastest-expanding customer base as ransomware frequency forces abandonment of self-managed security operations.
- Electronic Security:Remote monitoring, video surveillance, and intrusion detection systems operated from centralized command centers.
- Integrated Solutions:Bundled physical-digital offerings combining on-site personnel with remote monitoring infrastructure and cybersecurity advisory.
Volume placements concentrate in Man-Guarding; the faster expansion belongs to Cybersecurity.
End User:
Cost tier differentiation separates compliance-driven mandates from discretionary security expenditure across customer categories.
- Government:Federal, state, and municipal contracts covering critical infrastructure, defense facilities, and public safety operations. FAA-mandated perimeter upgrades at United States aviation facilities and EU critical infrastructure directives are accelerating procurement timelines for cleared guard-force and electronic surveillance at federally regulated sites.
- Commercial:Corporate campuses, retail chains, hospitality, and healthcare facilities seeking outsourced protection. Multi-tenant office complexes in London and Singapore are expanding contracted coverage as property managers transfer liability to specialized vendors.
- Residential:Gated communities, high-net-worth household protection, and concierge security services.
- Industrial:Manufacturing plants, logistics hubs, and energy terminals requiring specialized hazard response capabilities.
Government contracts anchor procurement volume; Commercial accounts are gaining share fastest through integrated facilities management bundling.
Technology:
Application context determines which technology layer dominates specific deployment scenarios.
- Surveillance Systems:Video analytics, thermal imaging, and AI-powered anomaly detection for continuous monitoring. Oil terminals in Texas and power generation facilities across Saudi Arabia are deploying drone-augmented aerial patrols to supplement fixed camera networks and reduce on-site headcount requirements.
- Biometrics:Facial recognition, fingerprint authentication, and behavioral analytics for identity verification. The EU AI Act's prohibited-practices list for real-time remote biometric identification in public spaces is forcing retrofit or abandonment across French and German commercial properties.
- Access Control:Credential-based entry management, visitor management systems, and cloud-connected identity platforms.
- Alarms:Intrusion detection, duress signaling, and environmental hazard alert systems.
Surveillance Systems command the largest installed base; Biometrics faces the steepest regulatory headwinds in European deployments.
Application:
Customer maturity and risk tolerance segment demand across protective use cases.
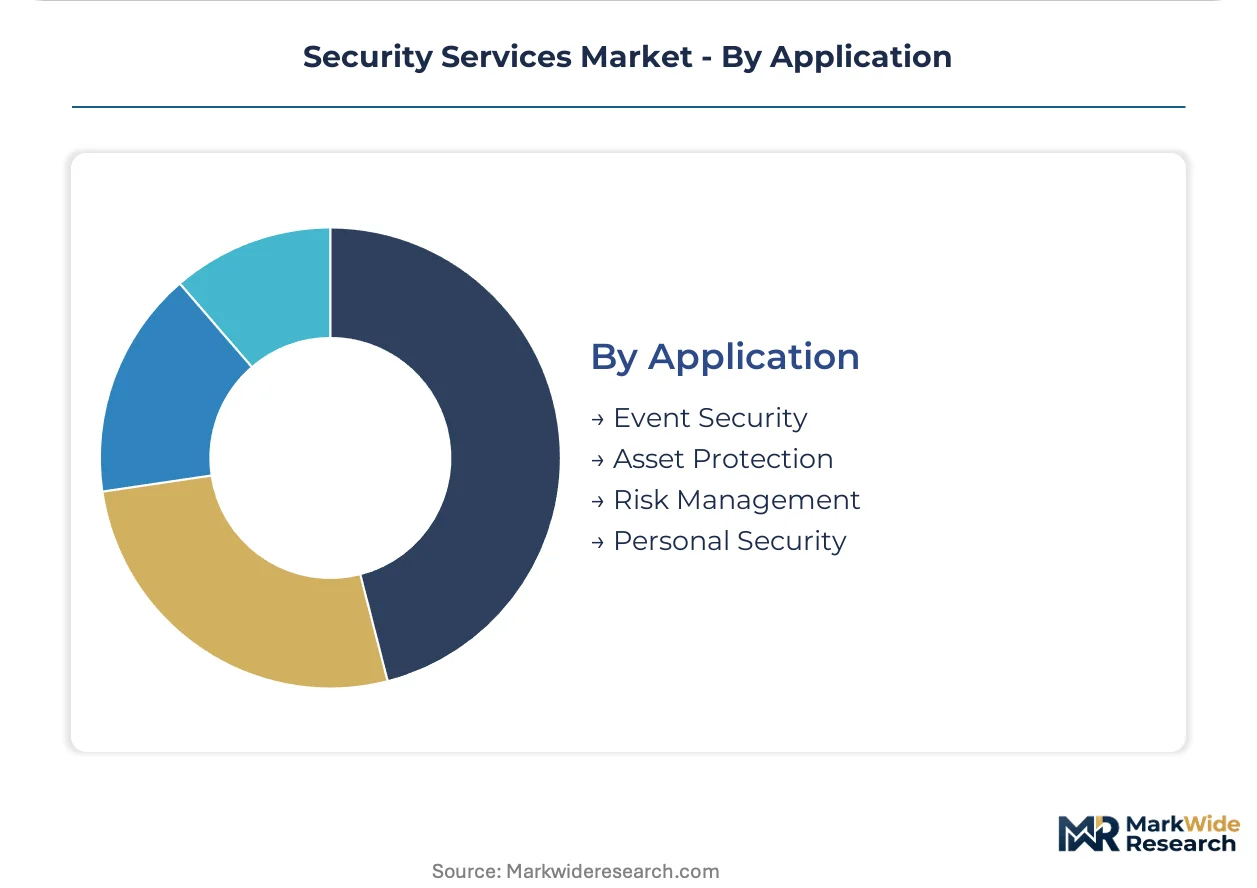
- Asset Protection:Safeguarding physical inventory, intellectual property, and digital infrastructure against theft or sabotage. Financial institutions in Switzerland and data center operators in Virginia are converging physical access control with cybersecurity monitoring to unify risk visibility.
- Risk Management:Advisory services, threat assessment, and compliance consulting for enterprise security governance. GDPR enforcement and United States state-level breach notification laws are creating attach-rate opportunities for compliance advisory alongside technical service delivery.
- Event Security:Temporary personnel deployment and crowd management for sporting events, conferences, and public gatherings.
- Personal Security:Executive protection, close protection details, and residential security details for high-risk individuals.
Asset Protection drives recurring contract value; Risk Management is climbing fastest as regulatory complexity elevates advisory attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise cybersecurity outsourcing and critical infrastructure protection mandates concentrate the heaviest demand, while European regulatory complexity and Asian smart city investments reshape regional competitive dynamics.
United States
FAA-mandated perimeter upgrades at aviation facilities and Fortune 500 campus consolidation drive contracted guard-force procurement. NIST Cybersecurity Framework adoption by federal contractors segments vendor qualification criteria. Dallas-Fort Worth and Atlanta metropolitan clusters anchor multi-tenant commercial real estate security expansion as property managers transfer liability to specialized vendors.
Germany
Industrial facility protection and labor union agreements sustain man-guarding contract volumes despite margin compression. EU AI Act prohibited-practices lists force retrofit of facial recognition deployments across commercial properties. The Rhine-Ruhr industrial corridor and Bavarian manufacturing hubs concentrate electronic security integration demand as enterprises modernize legacy access control systems.
United Kingdom
Multi-tenant office complexes in London expand contracted coverage amid insurance liability transfer trends. GDPR enforcement compels mid-market enterprises to outsource threat detection to managed security service providers. The London-Southeast corridor dominates integrated facilities management bundling as corporate campus operators seek single-accountability structures.
India
Municipal surveillance deployments across tier-1 and tier-2 cities present substantial contracts for technology-augmented guarding providers. PLI scheme incentives for domestic manufacturing indirectly elevate facility security requirements. The Delhi-NCR and Mumbai-Pune corridors anchor smart city command-and-control center rollouts with integrated physical-digital protection mandates.
Saudi Arabia
Oil terminal operators deploy drone-augmented aerial patrols to supplement fixed camera networks and reduce on-site headcount. Critical infrastructure protection mandates from the national oil company accelerate electronic surveillance procurement. The Eastern Province energy cluster and Riyadh metropolitan area concentrate perimeter security modernization budgets.
Security Services Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors abandon pure-play models for converged physical-digital offerings. The market exhibits tiered consolidation with multinational guard-force operators, technology-augmented specialists, and cybersecurity pure-plays occupying distinct competitive positions. Three strategic archetypes predominate: labor-intensive man-guarding incumbents, SOC-as-a-service platform providers, and integrated facilities management conglomerates. M&A activity and technology licensing partnerships represent the dominant competitive moves as vendors seek capabilities outside core competencies.
Within the integrated solutions tier, Allied Universal and Securitas AB exemplify the guard-force-to-technology pivot, while IBM anchors the cybersecurity-managed services archetype with cloud and hybrid environment defense capabilities. These three entities occupy positions spanning physical presence augmentation, remote monitoring infrastructure, and digital threat response.
| Leading Market Players |
|---|
| IBM |
| Accenture |
| Securitas AB |
| Allied Universal |
| G4S plc |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Check Point Software Technologies Ltd. |
| LevelBlue |
| Others |
Value Network & Pricing Analysis
Horizontal consolidation among guard-force operators anchors supply positioning while compressing pricing power for standalone specialists. Allied Universal and Securitas AB leverage national footprints to bundle man-guarding with electronic monitoring at rates pure-play vendors cannot match. This integration pattern forces smaller competitors toward niche cybersecurity or drone-augmented specialties where differentiation commands premium attach rates.
Pricing Analysis
Service-level agreement bundling distinguishes vendor tiers in this market. Three-tier pricing structure across premium, standard, and economy levels separates 24/7 SOC-as-a-service with guaranteed response times from basic patrol contracts. Certification under NIST Cybersecurity Framework and EU AI Act conformity assessments drive price differentiation between qualified and unqualified providers. Pricing pressure stems from wage inflation in United States and German guard-force labor outpacing contract escalation clauses. Mid-market commercial real estate buyers exhibit highest price sensitivity, while financial services institutions prioritize compliance-grade service bundles over cost minimization.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Saudi Arabia's localization programs are reshaping sourcing for surveillance hardware and command-center infrastructure. Component supply concentrates in China, Taiwan, and South Korea for camera sensors, edge-computing chipsets, and thermal imaging arrays. Raw material dependencies span rare-earth magnets for drone motors, lithium-ion cells for mobile patrol units, and optical-grade silicon for surveillance lenses. Single-source vulnerability in semiconductor fabrication creates procurement risk for vendors scaling AI-powered analytics. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and regional integrator networks for mid-market commercial properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as labor cost inflation and biometric compliance burdens force sub-scale operators toward acquisition or exit. Margin compression in pure man-guarding eliminates standalone viability for regional players lacking technology-augmented capabilities.
For Market Incumbents: Hedge against guard-force margin erosion by accelerating SOC-as-a-service platform investments and drone-augmented perimeter contracts. Acquire regional cybersecurity specialists to fill capability gaps in converged physical-digital offerings. Certification investment under EU AI Act high-risk system protocols creates defensible positioning against unqualified competitors in European commercial real estate.
For New Entrants and Emerging Players: Begin with India's smart city infrastructure segment where municipal surveillance tenders favor technology-augmented guarding providers over legacy operators. Target tier-2 city command-and-control center deployments as the most penetrable geography. Pursue joint-venture structures with established local integrators to bypass incumbent relationships and accelerate contract visibility.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated facilities management conglomerates seeking security capabilities. Long-term viability favors vendors with recurring SaaS revenue streams and cleared personnel pipelines for federal contractor roles. Watch FAA mandate implementation timelines at United States aviation facilities as inflection indicator for guard-force procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Converged Physical-Cyber Platform Launch | Unified SOC-as-a-service with drone-augmented guarding captures premium pricing from financial services clients in New York. |
| EU AI Act Conformity Assessment Investment | High-risk system certification enables continued biometric deployment in French and German commercial properties. |
| India Smart City Joint Venture | Municipal command-and-control center partnerships in Delhi-NCR establish technology-augmented guarding market presence. |
| Cleared Personnel Pipeline Expansion | Security clearance acquisition programs address federal contractor scarcity and anchor aviation facility contracts under FAA mandates. |
| Legacy Access Control Retrofit Partnership | Cloud-identity platform integrations with decades-old physical systems unlock mid-market enterprise upgrade cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with security operations directors, federal procurement officers, commercial real estate asset managers, and managed security service provider executives combined with secondary validation. Secondary sources encompassed FAA regulatory dockets, EU AI Act implementation guidance, NIST Cybersecurity Framework adoption reports, and customs records for surveillance equipment imports. Bottom-up contract value aggregation across service tiers reconciled with top-down market sizing from industry association revenue disclosures.
Data-stream reconciliation across guard-force deployment metrics, cybersecurity subscription bookings, and electronic security installation volumes informed the analytical framework. Segmentation dimensions modeled encompassed service type, end-user category, technology layer, and application context across the projection horizon. CAGRs derived from weighted average growth rates across segment-specific demand drivers including critical infrastructure mandates, ransomware frequency, and smart city investment cycles. Drone-augmented perimeter adoption curves and SOC-as-a-service penetration rates provided industry-specific forecast inputs.
Underlying measurement precision varies by segment; cybersecurity services carry tighter precision than man-guarding due to subscription billing transparency. Forecasts reflect assumptions regarding regulatory implementation timelines, labor cost trajectory, and technology substitution rates. Biometric deployment restrictions, insurance capacity constraints, and cleared personnel availability represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Europe Security Screening Market