
 Home Security Market | 2026-2036
Home Security Market Size, Share, and Industry Trends Forecast 2026-2036
Home Security Market Insights
Subscription-based leasing and hardware-as-a-service financing is reconfiguring capital requirements for new entrants, lowering upfront barriers while extending customer lifetime value horizons. ADT leverages its nationwide monitoring infrastructure to sustain recurring revenue density across professionally installed accounts. SimpliSafe competes through direct-to-consumer channels that minimize dealer overhead and accelerate unit economics. Ring anchors Amazon's ecosystem play, using delivery-integrated video doorbells to extend household touchpoints beyond traditional security boundaries.
Home security encompasses electromechanical and digital systems designed to detect unauthorized entry, environmental hazards, and occupancy anomalies through sensor arrays, control panels, and communication interfaces operating on RF, cellular, or IP backbones. These installations serve residential and small multi-family properties by triggering audible alarms, dispatching monitoring services, and enabling real-time remote verification. Surveillance cameras lead product type revenue due to recurring cloud storage attach rates and computer vision feature tiers. Wireless technology dominates new installations as mesh networking and battery-optimized protocols eliminate conduit and wiring labor. DIY installation captures the fastest growth trajectory among deployment modes, though professional installation retains margin concentration in integrated smart home contracts.
FCC governs radio frequency allocations for wireless sensors and cellular communicators, while UL standards mandate intrusion detection equipment performance and false alarm resistance. GDPR and state-level biometric privacy laws in Illinois, Texas, and Washington constrain facial recognition deployment in cloud-connected cameras, forcing architecture adjustments. Stakeholders must monitor evolving insurance premium incentives tied to verified alarm response protocols and the fragmentation of municipal permitting requirements for monitored systems.
Market Dynamics
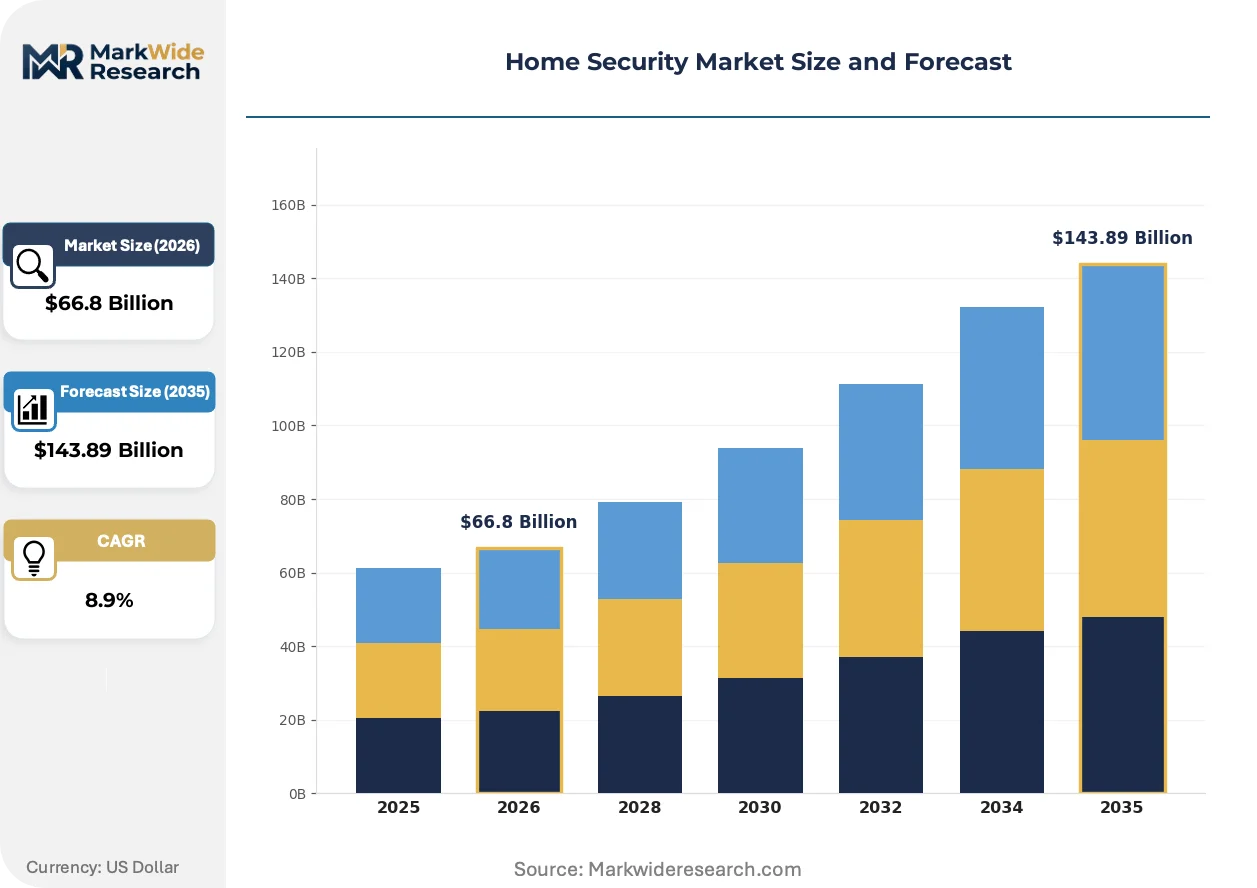
Wireless IoT protocols and AI-powered video analytics are compressing installation timelines and expanding remote monitoring capabilities across residential and multi-family deployments.
Growth Catalysts
- Cellular Communicator Mandates:FCC radio frequency allocations for wireless sensors enable nationwide coverage without landline dependencies. UL certification requirements for intrusion detection equipment accelerate professional monitoring attach rates.
- Institutional Landlord Scaling:Rental operators building smart property portfolios drive bulk procurement of integrated sensor arrays and cloud-connected control panels.
- Mesh Networking Protocols:Battery-optimized RF standards eliminate conduit labor and reduce installation crew requirements for retrofits.
Market Restraints
- Lithium Battery Supply Concentration:Wireless sensor manufacturers face input cost volatility tied to cathode material processing capacity in China.
- Biometric Privacy Friction:GDPR and Illinois BIPA constraints on facial recognition deployment force architecture adjustments for cloud-connected cameras.
- False Alarm Penalty Regimes:Municipal verified response protocols impose escalating fines that suppress monitoring service uptake in urban jurisdictions.
Strategic Opportunities
- Insurance Premium Incentives:Verified alarm response protocols in Texas and Florida create policyholder demand for professionally monitored systems.
- Hardware-as-a-Service Financing:Subscription-based leasing models lower upfront capital barriers for new entrants while extending customer lifetime value horizons.
- Computer Vision Convergence:Integration of edge AI with package detection and occupancy sensing opens adjacent revenue streams beyond intrusion detection.
Industry Challenges
- Low-Voltage Technician Scarcity:Professional installation networks face recruitment gaps for certified integrators capable of smart home ecosystem configuration.
- Municipal Permitting Fragmentation:Monitored system registration requirements vary by county and city, creating compliance overhead for national operators.
- Legacy Panel Integration:Retrofit deployments encounter protocol incompatibilities between proprietary RF ecosystems and open-standard mesh networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Security Market |
| Market Size in 2026 | $66.8 Billion |
| Market Size in 2035 | $143.89 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Alarms, Surveillance Cameras, Access Control Systems, Motion Detectors, Smart Locks Technology: Wireless, Wired, IP-Based, Cloud-Connected, Biometric Installation Type: DIY Installation, Professional Installation, Hybrid Installation, Retrofit Installation End User: Homeowners, Landlords, Property Managers, Rental Operators |
| Companies Covered | ADT, Ring, SimpliSafe, Vivint, Johnson Controls, Honeywell, Google Nest, Hikvision, Brinks Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Security Market Trends and Innovations
Edge computing architectures and on-device inference are redistributing processing loads from cloud data centers to local hardware. This shift alters cost structures, latency profiles, and data governance postures across the competitive landscape.
On-device AI accelerators in video doorbells and security cameras are rendering obsolete the latency penalties and bandwidth costs of continuous cloud upload streams. Property managers in multi-family developments deploy these units to reduce recurring cloud storage commitments. The architecture compresses operational expenditure while enabling real-time anomaly detection without internet dependency.
GDPR Article 35 data protection impact assessments now constrain biometric data retention policies for EU-deployed surveillance systems. Cloud service providers must architect region-specific data residency and automated deletion workflows. German and French operators face the strictest compliance timelines, accelerating investment in edge-only facial recognition alternatives.
Direct-to-consumer channel expansion disrupts traditional dealer networks that historically captured margin through installation markups. Self-install sensor kits with app-guided commissioning now capture first-time buyers who previously deferred purchase due to scheduling friction. This pattern concentrates in United States suburban markets where single-family penetration rates support scaled fulfillment infrastructure.
Home Security Market Segmentation
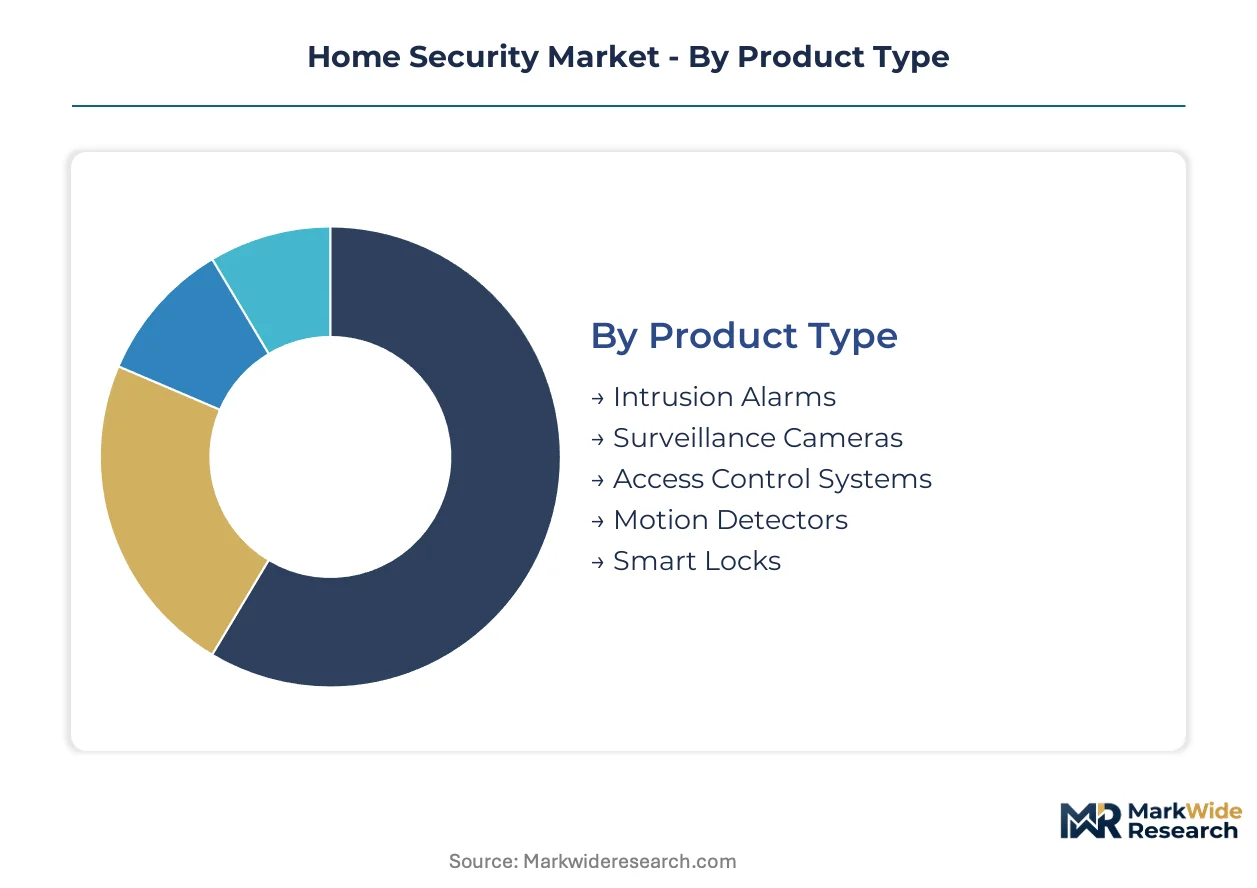
Segmentation in home security reveals divergent technology lifecycles and buyer sophistication levels. Wireless protocols and AI-enhanced cameras now command premium positioning, while legacy wired systems sustain replacement demand in established suburban markets.
Product Type:
Mature hardware categories coexist with emerging AI-augmented formats across residential deployments.
- Surveillance Cameras:Cloud-connected units with edge AI inference enable real-time anomaly detection without continuous bandwidth consumption. Demand concentrates among rental operators in Texas and Florida seeking insurance premium reductions through verified alarm protocols.
- Intrusion Alarms:Sensor arrays combining door contacts, glass-break detectors, and control panels form the foundational layer of monitored security systems. Homeowners in single-family suburban markets sustain volume through UL-certified professional monitoring attach rates.
- Access Control Systems:Keypad and credential readers manage entry permissions for multi-family properties.
- Motion Detectors:PIR and dual-technology sensors trigger alerts while minimizing false positives from pets.
- Smart Locks:Battery-powered deadbolts with remote access codes serve short-term rental operators.
Surveillance Cameras retain volume leadership; Smart Locks hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium biometric systems from mass-market wireless deployments.
- Wireless:Mesh RF protocols and cellular communicators eliminate landline dependencies and reduce retrofit labor. Institutional landlords in the United States drive bulk procurement for smart property portfolios.
- Cloud-Connected:IP-based architectures with centralized management platforms enable remote firmware updates and subscription revenue streams. Property managers prioritize these systems for operational expenditure compression across distributed holdings.
- Wired:Hardwired sensor loops sustain demand in new construction with pre-installed conduit.
- IP-Based:Ethernet-powered devices integrate with existing residential networking infrastructure.
- Biometric:Fingerprint and facial recognition modules face GDPR and Illinois BIPA compliance constraints.
Wireless technology captures the dominant installation share; Cloud-Connected systems are gaining share fastest among commercial buyers.
Installation Type:
Customer type determines deployment mode selection between convenience and integration depth.
- DIY Installation:Self-commissioning sensor kits with app-guided setup reduce scheduling friction for first-time buyers. Direct-to-consumer channels in United States suburban markets accelerate unit economics through eliminated dealer overhead.
- Professional Installation:Certified integrators configure ecosystem interoperability and smart home automation. Low-voltage technician scarcity constrains network expansion despite margin concentration in integrated contracts.
- Hybrid Installation:Self-installed core sensors with professional activation of monitoring services.
- Retrofit Installation:Wireless protocols overcome legacy panel incompatibilities in existing structures.
Professional Installation retains margin leadership; DIY Installation demonstrates the steepest volume climb.
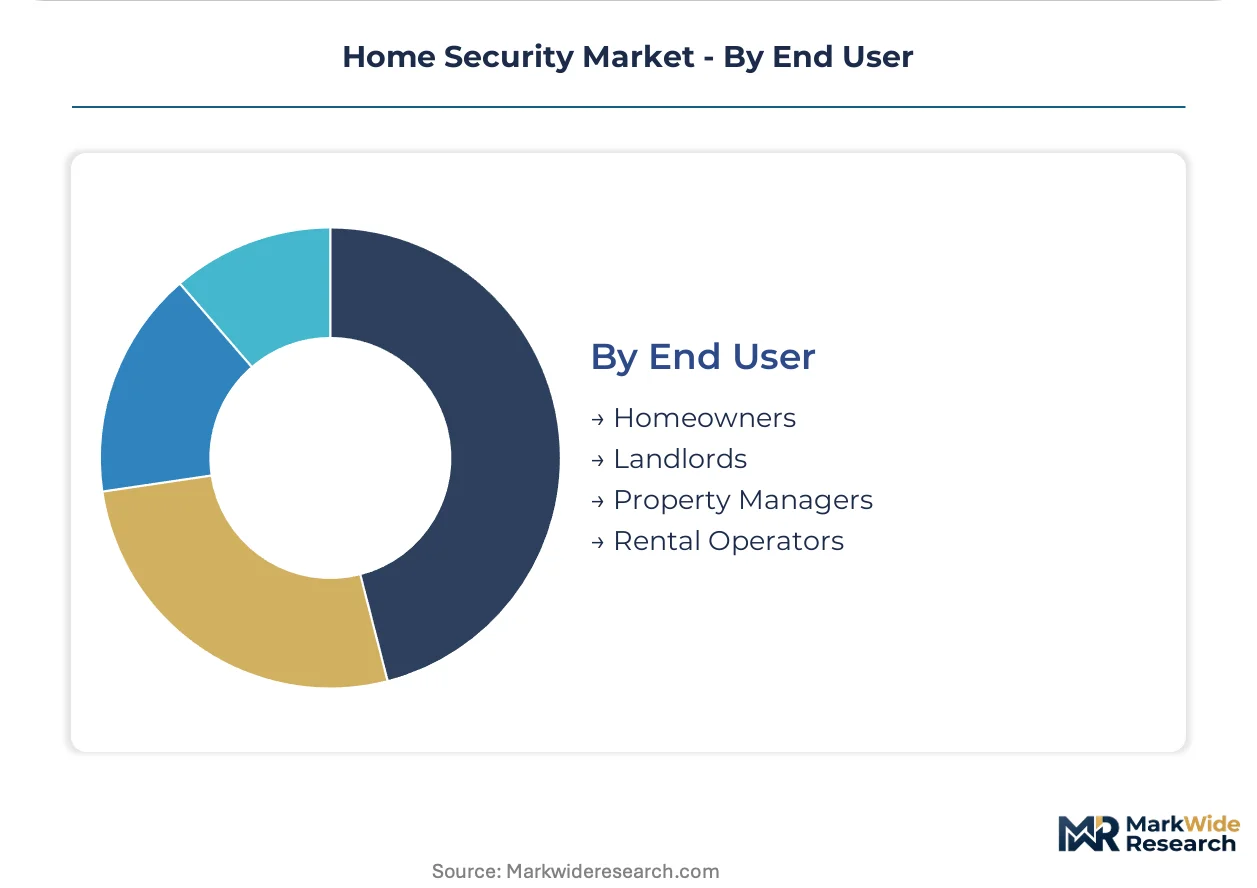
End User:
Application requirements differentiate residential owner-occupiers from portfolio-scale operators.
- Landlords:Institutional owners of multi-family assets procure integrated sensor arrays and cloud-connected control panels at scale. FCC cellular communicator mandates enable nationwide coverage without property-specific infrastructure.
- Rental Operators:Short-term and mid-term rental managers deploy smart locks and video doorbells for remote access management. Municipal permitting fragmentation creates compliance overhead for national platform expansion.
- Homeowners:Single-family residents prioritize intrusion detection with professional monitoring attach rates.
- Property Managers:Third-party management firms standardize on unified platforms across diverse holdings.
Landlords retain procurement volume leadership; Rental Operators exhibit the most rapid expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States operators extract premium pricing for professionally monitored systems, while German landlords face compressed margins under stricter GDPR compliance costs. This asymmetry redistributes investment flows toward jurisdictions with lighter biometric regulation and stronger insurance incentive frameworks.
United States
Single-family smart home penetration and multi-family property technology budgets drive procurement volume. FCC cellular communicator mandates enable nationwide coverage without landline infrastructure. Texas and Florida rental operators concentrate demand for verified alarm protocols that unlock insurance premium reductions.
Germany
GDPR Article 35 data protection impact assessments constrain biometric data retention for cloud-connected surveillance. German operators face the strictest compliance timelines in Europe, accelerating edge-only facial recognition alternatives. Berlin and Munich property managers prioritize region-specific data residency architectures.
China
MIIT wireless RF standards and GB certification requirements shape domestic sensor manufacturing. Shenzhen and Hangzhou industrial clusters supply battery-optimized mesh networking modules for export markets. NMPA-equivalent quality frameworks govern cellular communicator integration.
United Kingdom
Insurance premium incentives for verified alarm response protocols sustain professional monitoring attach rates. London and Southeast England multi-family developments drive cloud-connected control panel procurement. UK regulators align with GDPR biometric constraints while permitting edge AI deployment.
Japan
METI energy efficiency standards influence battery-optimized sensor design for residential retrofits. Tokyo and Osaka metropolitan areas concentrate demand for DIY installation kits with app-guided commissioning. JIS certification requirements maintain quality barriers for imported wireless equipment.
Home Security Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, cameras, and cellular modules. The vendor base separates into three strategic archetypes: nationwide monitoring infrastructure operators, direct-to-consumer hardware brands, and industrial conglomerates with building automation portfolios. Competitive moves concentrate on M&A for monitoring subscriber bases and technology licensing for edge AI video analytics.
Within the monitoring infrastructure tier, ADT and Brinks Home occupy positions sustained by recurring revenue density across professionally installed accounts. Among direct-to-consumer hardware specialists, SimpliSafe exemplifies the dealer-elimination model that accelerates unit economics through self-install sensor kits. Ring anchors Amazon's ecosystem play, using delivery-integrated video doorbells to extend household touchpoints beyond traditional security boundaries.
| Leading Market Players |
|---|
| ADT |
| Ring |
| SimpliSafe |
| Vivint |
| Johnson Controls |
| Honeywell |
| Google Nest |
| Hikvision |
| Brinks Home |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors from Shenzhen to Long Beach transmit lithium battery cost volatility directly into wireless sensor pricing, concentrating margin pressure on OEMs while enabling tiered pricing differentiation between mass-market DIY kits and professionally configured systems. This logistics artery shapes how supply concentration in Chinese cathode processing translates into downstream hardware-as-a-service financing structures.
Pricing Analysis
The customization-premium spread separates configured-to-order integrated systems from standard self-install kits by a factor reflecting UL certification tiers and smart home ecosystem interoperability depth. Subscription-based SaaS-tiered pricing dominates, with monthly monitoring fees anchoring lifetime value calculations while hardware margins compress on entry-level SKUs. Price differentiation hinges on certification level—UL-listed professional monitoring commands sustained premiums—and volume scale, with institutional landlords extracting bulk procurement discounts. Pricing pressure intensifies in the DIY tier as direct-to-consumer brands eliminate dealer markups. Rental operators exhibit the highest price sensitivity due to capex constraints, while single-family homeowners in Texas and Florida absorb premiums for verified alarm protocols that unlock insurance incentives.
Supply Chain Analysis
Supplier-financing facilities extended by Shenzhen-based battery cell manufacturers enable smaller sensor OEMs to manage working capital through 90-day payment terms, reducing liquidity barriers for new hardware entrants. Manufacturing concentrates in China, South Korea, and Vietnam, with Shenzhen and Hangzhou industrial clusters supplying mesh networking modules and Hangzhou specializing in edge AI silicon. Raw material dependencies center on lithium carbonate for battery cells, rare earth elements for RF components, and CMOS sensors for camera modules. Single-source vulnerability runs through Chinese cathode material processing capacity. Distribution runs through Amazon's fulfillment infrastructure for direct-to-consumer channels and ADT's dealer networks for professional installation accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional monitoring subscription attach rates are expanding faster than hardware unit growth, transforming capital deployment logic from equipment financing to recurring revenue infrastructure. This service-attach dynamic rewards players who front-load customer acquisition costs against extended lifetime value horizons.
For Market Incumbents: Entrench recurring revenue density by deepening vertical integration into cellular communicator manufacturing, reducing exposure to lithium battery supply volatility. Prioritize certification investment in UL-listed verified response protocols to defend margin position against DIY entrants exploiting direct-to-consumer channel economics. Channel control through exclusive dealer networks remains essential for smart home ecosystem lock-in.
For New Entrants and Emerging Players: Build out hardware-as-a-service financing capabilities targeting institutional landlords scaling smart property portfolios across Texas and Florida, the most penetrable geography-insurance incentive combination. Self-install sensor kits with app-guided commissioning offer the clearest white-space entry path, with municipal permitting fragmentation creating localized defensibility against national platform expansion.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with building automation portfolios seeking to divest non-core residential security assets, particularly those with dormant monitoring subscriber bases. Long-term viability hinges on recurring revenue conversion rates exceeding hardware depreciation cycles. The signal to watch is insurance premium incentive expansion into additional states, which would inflect professional monitoring attach rates and revalue subscriber base multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Video Analytics Integration | On-device inference reduces cloud storage commitments for multi-family property managers in Germany and France. |
| Cellular Communicator Manufacturing Scale-Up | FCC mandates for wireless backhaul create captive supply advantages for vertically integrated OEMs. |
| Hardware-as-a-Service Financing Launch | Subscription leasing lowers upfront barriers for rental operators while extending customer lifetime value horizons. |
| Insurance Partnership Expansion | Verified alarm protocol integration with Texas and Florida carriers drives professional monitoring attach rates. |
| Biometric Privacy-Compliant Architecture | Edge-only facial recognition alternatives satisfy GDPR Article 35 constraints in German and French deployments. |
Research Methodology
Operator-level perspectives from property technology directors at institutional landlords, monitoring service operations executives, low-voltage installation network managers, and insurance risk engineering specialists anchored the qualitative base. Primary interviews combined with secondary validation against FCC equipment authorization databases, UL certification registries, state-level biometric privacy legislation filings, and insurance industry loss cost data. Bottom-up unit economics modeling triangulated against top-down market sizing from cellular communicator shipment records and cloud storage revenue disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning product type, installation mode, technology protocol, and end-user archetype. CAGRs derived from installed base growth rates, replacement cycle assumptions, and attach rate trajectories for professional monitoring and cloud storage services. Forecast inputs incorporated FCC regulatory timelines for RF spectrum reallocation, lithium battery supply elasticity estimates, and municipal permitting requirement diffusion patterns.
Stress conditions across lithium carbonate price bands, cellular module lead time volatility, and biometric privacy regulatory expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smart home penetration curves and insurance incentive program adoption. Macroeconomic contraction, accelerated GDPR-style biometric restrictions in additional US states, or breakthroughs in solid-state battery chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Airport Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
Burglar Alarm Systems Market