
 Global Wireless Monitoring and Surveillance Market | 2026-2036
Global Wireless Monitoring and Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Monitoring and Surveillance Market Foresight
South Korea is narrowing its gap with Chinese manufacturers through government-backed semiconductor foundry investments and 5G-enabled surveillance testbeds. Hikvision leverages captive sensor fabrication to control cost structures across its wireless camera portfolio. Dahua Technology anchors its position through deep vertical integration into chipset design and edge-computing modules. Axis Communications differentiates via open-architecture protocols that simplify third-party software integration for enterprise buyers.
Wireless monitoring and surveillance encompasses sensor networks, transmission protocols, and edge-analytics platforms that collect, relay, and process data without physical cabling, typically operating across radio frequencies from sub-GHz to millimeter-wave bands with latency thresholds under 50 milliseconds for real-time security applications. The primary commercial purpose centers on enabling scalable oversight of distributed assets, perimeters, and environments where wired infrastructure proves impractical or cost-prohibitive. LoRaWAN dominates environmental monitoring deployments where ultra-low power consumption and kilometer-range transmission outweigh bandwidth needs. Wi-Fi and LTE compete aggressively in smart city and critical infrastructure segments where video throughput demands exceed unlicensed spectrum capacity. Drone-based systems within the deployment dimension attract disproportionate R&D allocation from defense and energy end users seeking mobile coverage of pipelines, borders, and remote facilities.
The EU AI Act, GDPR, and CE marking framework collectively mandate algorithmic transparency and data minimization for biometric-enabled wireless surveillance, forcing vendors to rearchitect on-device processing pipelines. The FCC in the United States and MIIT in China administer spectrum allocation rules that directly determine which transmission technologies gain commercial scale in their respective markets. Stakeholders must monitor evolving encryption certification requirements and spectrum auction outcomes to anticipate which technology-deployment combinations will secure regulatory clearance and procurement eligibility.
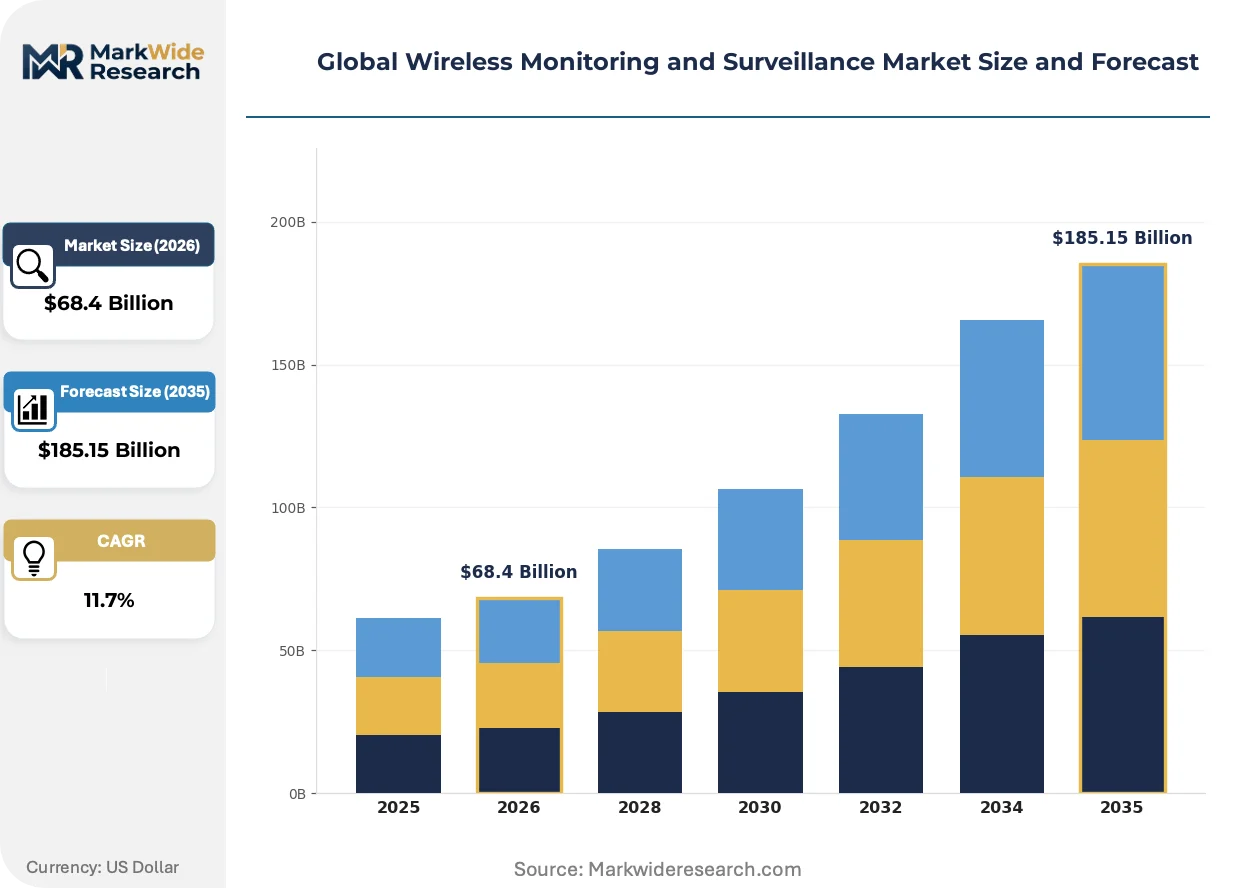
Market Dynamics
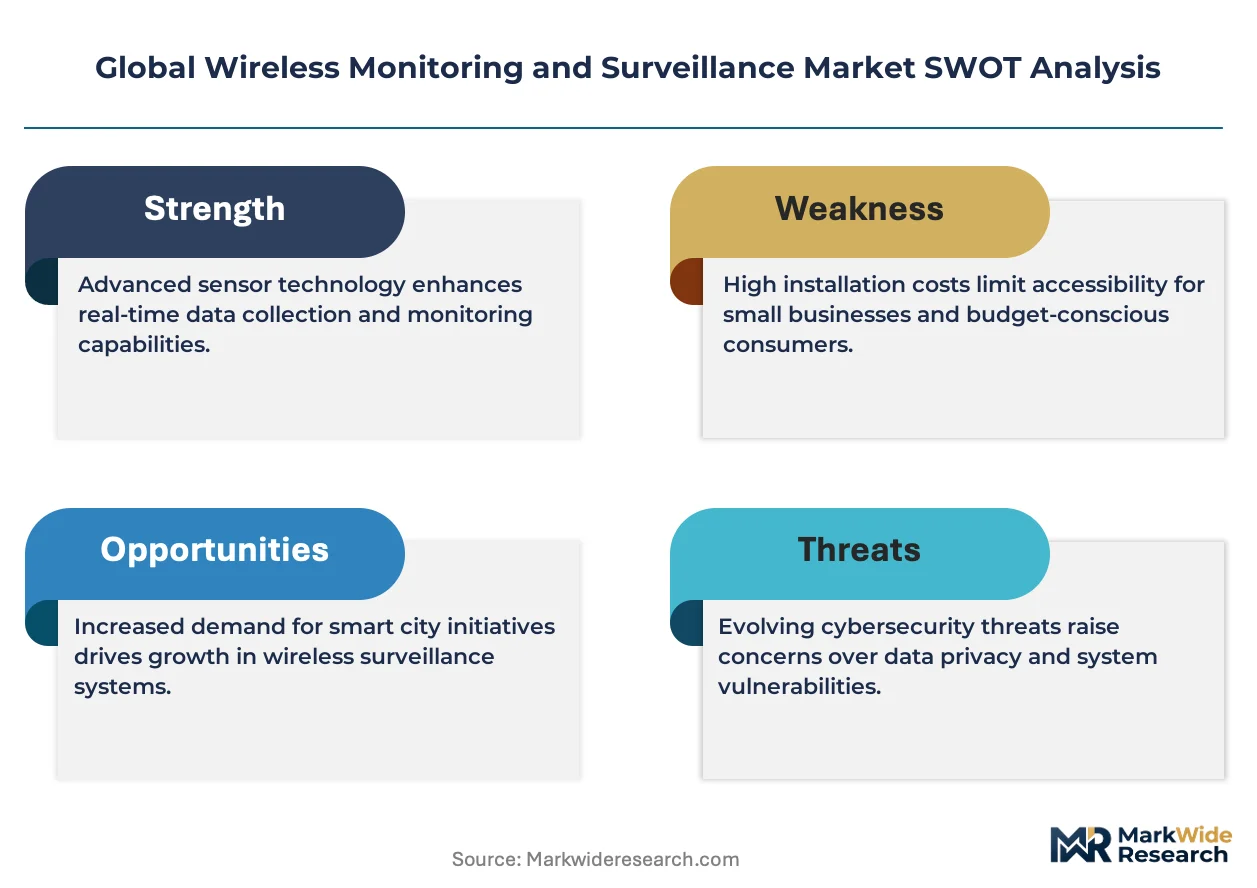
The EU AI Act's biometric surveillance restrictions are forcing vendors to relocate processing from cloud to edge, compressing hardware margins while expanding semiconductor content per unit.
Growth Catalysts
- Critical Infrastructure Protection Budgets:Germany, South Korea, and the United States are expanding perimeter security procurement for energy grids and transportation nodes.
- Encrypted Transmission Mandates:GDPR and EU AI Act compliance requirements accelerate demand for end-to-end encrypted wireless protocols in biometric-enabled deployments.
- Drone Platform Integration:NATO defense agencies are scaling procurement of unmanned aerial surveillance for border and pipeline monitoring applications.
Market Restraints
- Semiconductor Supply Concentration:Advanced RF chip fabrication concentrates in Taiwan and South Korea, creating geopolitical exposure for sensor module supply.
- Spectrum Licensing Friction:FCC and MIIT auction timelines delay commercial rollout of millimeter-wave surveillance networks in urban corridors.
- Power-Performance Tradeoff:LoRaWAN's bandwidth ceiling limits video analytics throughput, restricting deployment to low-fidelity sensor applications.
Strategic Opportunities
- India Smart City Deployments:TRAI's 5G spectrum allocation enables city-scale wireless surveillance testbeds in Mumbai and Delhi with localized data residency.
- Convergence of AI and Edge Computing:On-device inference chips reduce cloud dependency for real-time facial recognition in bandwidth-constrained environments.
- Subscription Service Models:Managed security service providers are bundling hardware, connectivity, and analytics into multi-year contracts for mid-market enterprises.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for sub-50 millisecond latency thresholds competes with consumer electronics for limited semiconductor design specialists.
- CE Marking Timeline Compression:EU AI Act algorithmic transparency documentation extends product certification cycles by 8-14 months for biometric-enabled devices.
- Legacy Analog Integration:Hybrid deployments requiring protocol bridges between IP-based wireless and coaxial infrastructure multiply deployment complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Monitoring and Surveillance Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, ZigBee, Bluetooth, LTE, Wi-Fi, LoRaWAN Application: Smart Cities, Critical Infrastructure, Wildlife Tracking, Perimeter Security, Asset Management, Environmental Monitoring End User: Government Agencies, Transportation Firms, Energy Providers, Research Institutions, Security Contractors Deployment: Fixed Installation, Mobile Platforms, Wearable Devices, Drone-Based Systems, Vehicular Integration |
| Companies Covered | Hikvision, Dahua Technology, Axis Communications, Bosch Security Systems, Honeywell, Hanwha Vision, Teledyne FLIR, Motorola Solutions, Zhejiang Uniview Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Monitoring and Surveillance Market Shifts & Advancements
Edge-native processing architectures are displacing cloud-reliant surveillance stacks, while regulatory fragmentation across major economies forces modular hardware designs.
Millimeter-wave radar modules with integrated AI inference engines are rendering obsolete camera-only perimeter detection in low-visibility environments. Oil and gas operators in the North Sea and Gulf of Mexico are deploying these units for 24-hour pipeline monitoring regardless of weather conditions. The shift is compressing demand for thermal imaging add-ons and reducing total sensor count per kilometer of protected infrastructure.
The EU AI Act's risk classification system for biometric identification imposes conformity assessment requirements that favor vendors with pre-certified edge processing pipelines. Manufacturers must document training data provenance and algorithmic decision logic prior to CE marking approval. German industrial security buyers now require EU AI Act compliance documentation as a gate criterion for tender participation, displacing vendors without European certification infrastructure.
Energy utilities are consolidating vendor relationships from point-product procurement to integrated platform contracts spanning sensors, connectivity, and analytics software. This consolidation favors suppliers with captive chipset design and managed network operations capabilities. The pattern is most pronounced in Texas and California, where critical infrastructure protection budgets now flow through three-year managed service agreements rather than annual capital expenditure cycles.
Global Wireless Monitoring and Surveillance Market Segmentation
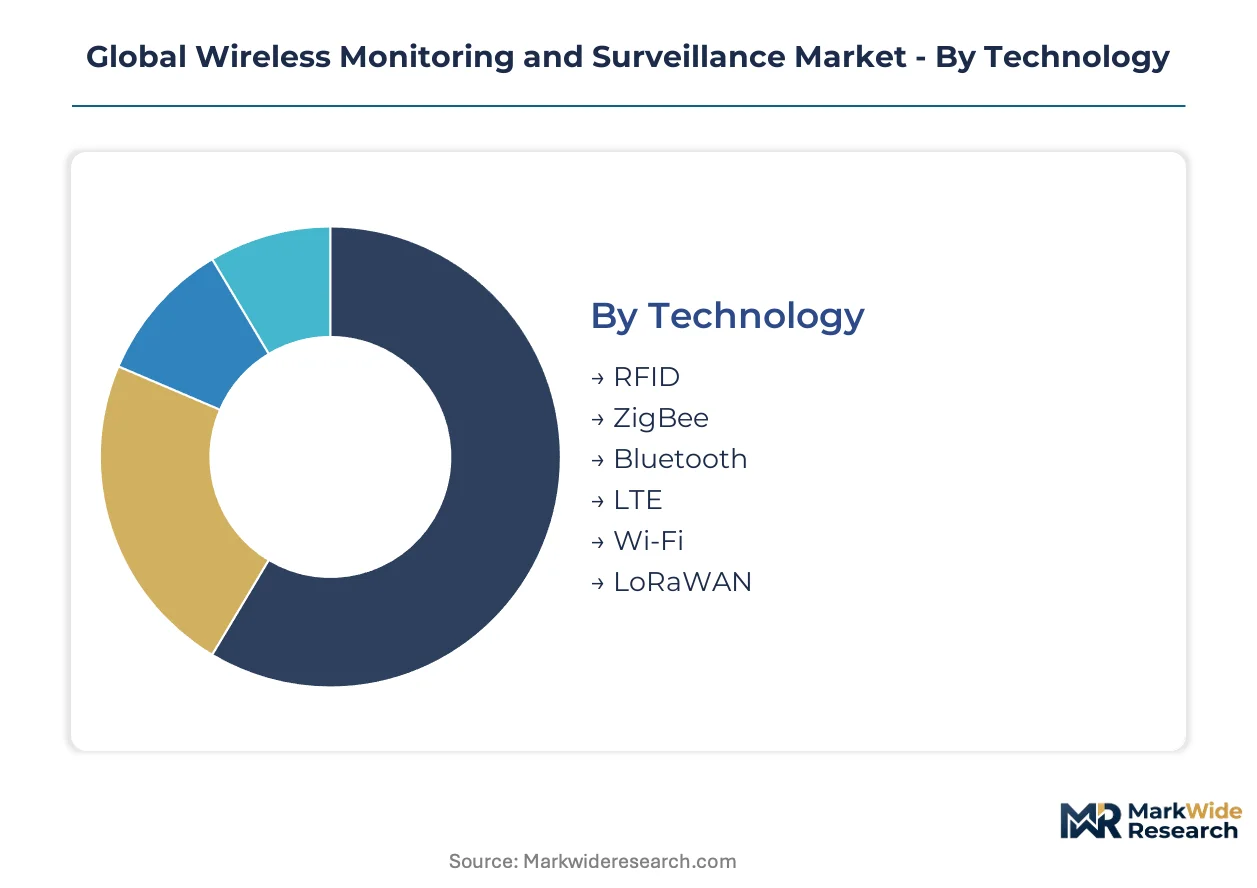
Technology selection determines power budgets, transmission range, and regulatory compliance pathways across wireless surveillance deployments. Application context shapes hardware specifications from sensor durability to encryption protocols. End user procurement patterns and deployment architecture choices further stratify vendor positioning and service model requirements.
Technology:
Cost tier differentiation separates licensed spectrum solutions from unlicensed alternatives, with direct implications for infrastructure investment and operational expenditure profiles.
- LTE:Licensed cellular spectrum delivers guaranteed quality-of-service for video-heavy critical infrastructure deployments. German energy utilities and South Korean transportation authorities prioritize LTE for pipeline and rail monitoring where bandwidth consistency outweighs subscription costs.
- LoRaWAN:Sub-GHz unlicensed operation enables decade-long battery life for distributed sensor grids. Environmental monitoring contracts across Texas oil fields and North Sea offshore platforms favor LoRaWAN for temperature and vibration sensing where data payloads remain small.
- Wi-Fi:High-throughput local area coverage dominates smart city video analytics in bandwidth-rich urban corridors.
- Bluetooth:Short-range proximity detection supports wearable personnel tracking and access control integrations.
- ZigBee:Mesh networking topology suits building automation and indoor asset location services.
- RFID:Passive and active tagging enables inventory and equipment tracking without continuous power draw.
LTE commands the established base in revenue terms. The steepest expansion runs through LoRaWAN as industrial IoT sensor counts multiply.
Application:
Volume concentration varies sharply by deployment scale, with city-wide installations generating sensor counts orders of magnitude above facility-level implementations.
- Smart Cities:Integrated traffic, public safety, and environmental sensing across municipal jurisdictions demands multi-protocol interoperability. Mumbai and Delhi testbeds under TRAI's 5G allocation are validating city-scale wireless surveillance architectures with localized data residency requirements.
- Critical Infrastructure:Perimeter and process monitoring for energy, water, and transportation assets requires hardened hardware and encrypted transmission protocols. GDPR and EU AI Act compliance mandates are accelerating procurement of edge-processing units for biometric-enabled access control at German power substations.
- Perimeter Security:Border and facility boundary protection combines radar, thermal, and video analytics with sub-50 millisecond alert latency.
- Environmental Monitoring:Air quality, water level, and seismic sensing prioritizes power efficiency over bandwidth across remote deployment locations.
- Asset Management:Real-time location tracking of high-value equipment and fleet vehicles reduces loss rates in logistics and construction.
- Wildlife Tracking:Collar-mounted sensors and camera traps support conservation biology with ultra-low power budgets and satellite backhaul.
Critical Infrastructure commands the established base through sustained defense and utility procurement. Smart Cities represents the fastest-growing trajectory as municipal digitization budgets expand.
End User:
Customer type determines procurement rhythm, with government tenders favoring multi-year framework agreements while commercial buyers prioritize operational flexibility.
- Government Agencies:Defense, border control, and law enforcement procurement emphasizes encrypted transmission and algorithmic transparency documentation. NATO member states are expanding drone-based surveillance platform procurement with CE marking and EU AI Act compliance as mandatory tender criteria.
- Energy Providers:Oil, gas, and electric utility deployments require explosion-proof hardware and 24/7 pipeline monitoring across remote geography. Texas and California utilities are consolidating vendor relationships into three-year managed service agreements spanning sensors, connectivity, and analytics.
- Transportation Firms:Rail, port, and logistics operators prioritize real-time cargo and vehicle tracking with integration into existing operations centers.
- Security Contractors:Private firms serving commercial and residential clients favor modular, rapidly deployable systems with subscription pricing.
- Research Institutions:Academic and environmental science users accept higher device complexity in exchange for open data formats and customization access.
Energy Providers command the established base through sustained critical infrastructure protection budgets. Government Agencies show the steepest expansion trajectory as defense and border security allocations rise.
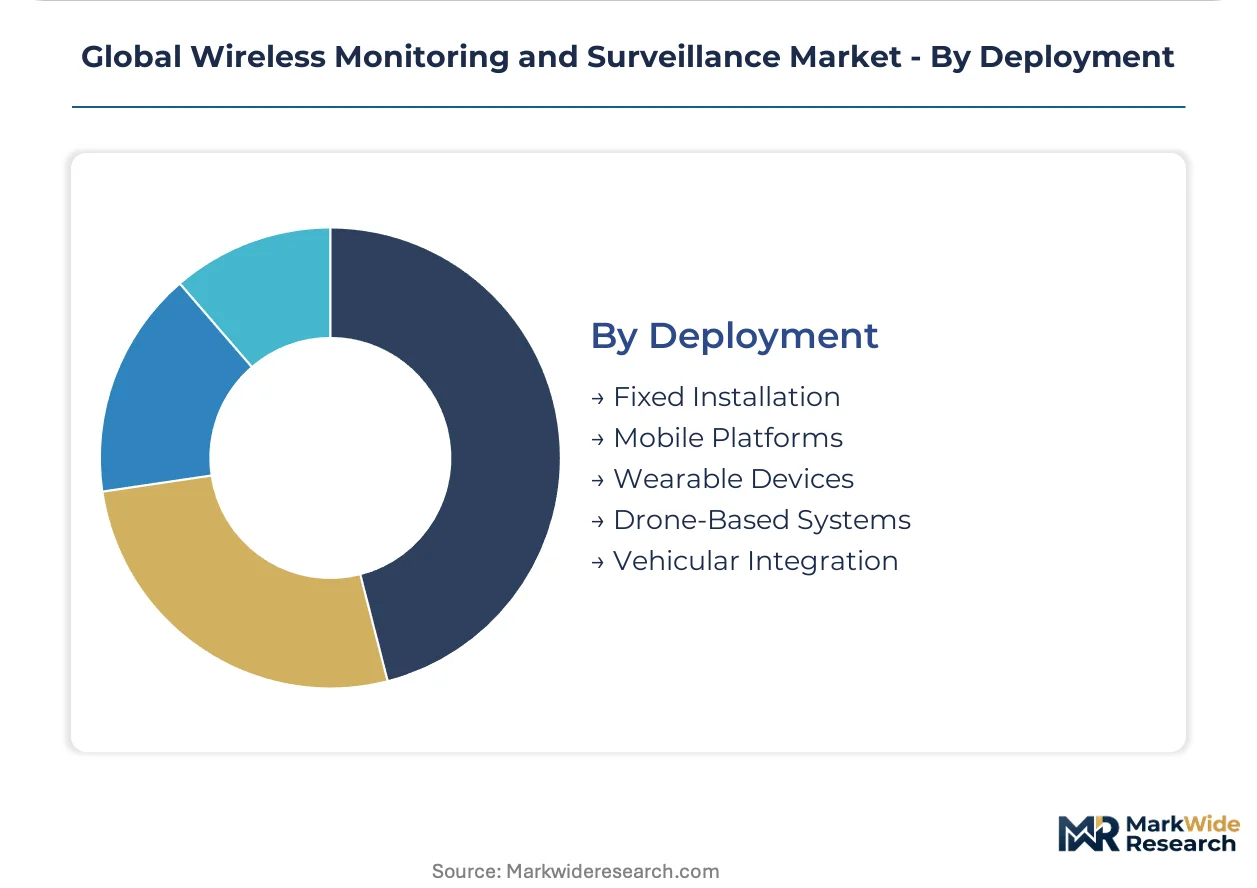
Deployment:
Margin structure differs by mobility requirement, with fixed installations benefiting from scale economies and mobile platforms commanding premium pricing for ruggedization and power management.
- Drone-Based Systems:Unmanned aerial platforms deliver rapid, reconfigurable coverage for border patrol, pipeline inspection, and emergency response. NATO defense agencies and North Sea oil operators are scaling procurement of aerial surveillance for terrain where fixed sensor placement proves impractical.
- Fixed Installation:Permanent mounting on buildings, towers, and infrastructure delivers lowest per-unit cost for long-term perimeter and facility monitoring.
- Mobile Platforms:Trailer-mounted and rapidly deployable units serve temporary event security and construction site monitoring.
- Vehicular Integration:Dashboard and roof-mounted systems extend surveillance coverage for patrol and fleet management applications.
- Wearable Devices:Body-worn cameras and biometric sensors support law enforcement and private security personnel with real-time situational awareness.
Fixed Installation commands the established base through volume deployment in commercial and industrial facilities. Drone-Based Systems show the steepest expansion trajectory as defense and energy end users prioritize mobile coverage flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced RF chip fabrication concentrates in Taiwan and South Korea, creating geographic dependencies that shape procurement strategies across defense and critical infrastructure sectors. National regulators in Germany, the United States, and South Korea are accelerating encrypted transmission mandates. Municipal testbeds in Mumbai, Seoul, and Austin validate divergent spectrum allocation approaches.
United States
Critical infrastructure protection budgets at Texas and California utilities are consolidating into multi-year managed service agreements. FCC spectrum auction timelines determine millimeter-wave surveillance network rollout schedules in urban corridors. Austin and Dallas energy operators deploy drone-based pipeline monitoring across Permian Basin geography.
Germany
Industrial security buyers now require EU AI Act compliance documentation as mandatory tender participation criteria. CE marking and algorithmic transparency mandates extend product certification cycles for biometric-enabled devices. Bavarian power substations prioritize edge-processing units for encrypted access control deployments.
South Korea
Government-backed semiconductor foundry investments narrow the manufacturing gap with Chinese sensor producers. TRAI-aligned 5G spectrum allocation enables city-scale surveillance testbeds with localized data residency requirements. Seoul metropolitan authorities validate millimeter-wave radar integration for smart city video analytics.
India
Smart city digitization budgets in Mumbai and Delhi drive multi-protocol interoperability requirements for integrated traffic and public safety sensing. TRAI's 5G spectrum allocation supports wireless surveillance testbeds with mandatory data localization. Maharashtra state utilities pilot LoRaWAN environmental grids for remote infrastructure monitoring.
China
MIIT spectrum administration rules determine which transmission technologies achieve commercial scale in domestic surveillance markets. Dual carbon goals and critical infrastructure protection priorities channel procurement toward low-power wide-area sensor networks. Shenzhen and Hangzhou industrial clusters concentrate edge-computing module production for regional supply.
Global Wireless Monitoring and Surveillance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in RF chipset and sensor fabrication. The vendor base stratifies across three tiers: defense-grade contractors with NATO certification infrastructure, industrial security platforms with captive semiconductor supply, and modular software-agnostic hardware suppliers. Strategic moves concentrate on backward integration into sensor fabrication and multi-year managed service contract capture.
Among Chinese manufacturers, Hikvision and Dahua Technology exemplify the vertically integrated archetype with captive control over cost structures and chipset design. Axis Communications occupies a position within the open-architecture tier, simplifying third-party software integration for enterprise buyers seeking protocol flexibility.
| Leading Market Players |
|---|
| Hikvision |
| Dahua Technology |
| Axis Communications |
| Bosch Security Systems |
| Honeywell |
| Hanwha Vision |
| Teledyne FLIR |
| Motorola Solutions |
| Zhejiang Uniview Technologies |
| Others |
Supply & Pricing Matrix
Taiwan Strait geopolitical exposure determines both pricing tier spreads and supply chain shape across RF chipset procurement, compressing margins for vendors without captive foundry relationships while inflating premiums for dual-sourced semiconductor architectures.
Pricing Analysis
EU AI Act dictates the pricing tier structure through algorithmic transparency documentation requirements. Pricing stratifies across premium, standard, and economy tiers based on CE marking grade and edge-processing certification level. Cost compression in the economy tier is intensifying because German industrial buyers now mandate EU AI Act compliance as a tender gate criterion. Energy utilities demonstrate lowest price sensitivity due to three-year managed service consolidation, while mid-market security contractors face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean foundries now stretch to 90-120 days for RF module vendors without captive fabrication. Advanced sensor production draws from Taiwan, South Korea, and Shenzhen manufacturing clusters. Raw material dependencies rest on silicon carbide substrates, millimeter-wave GaAs wafers, and encrypted firmware IP cores. Single-source vulnerability concentrates in TSMC's 7nm RF process nodes. Distribution runs through direct OEM supply agreements and managed security service provider channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through energy utility procurement consolidation into multi-year platform contracts, fragmenting pricing leverage for component-only vendors.
For Market Incumbents: Build certification moats through pre-validated EU AI Act edge-processing pipelines. Invest in captive semiconductor design to offset Taiwan foundry concentration risk. Secure three-year managed service agreements with Texas and California utilities before procurement windows close to modular competitors. For New Entrants and Emerging Players: Indian smart city deployments under TRAI's 5G allocation offer the most penetrable geographic entry point. Target LoRaWAN environmental monitoring for Maharashtra state utilities with localized data residency compliance. Pursue partnership-based go-to-market with established managed security service providers lacking in-house sensor fabrication. For Investors and Strategic Acquirers: Edge-native AI inference chip specialists with pre-certified EU AI Act pipelines represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance infrastructure rather than hardware cost advantage alone. Monitor FCC millimeter-wave auction timelines as an inflection indicator for urban surveillance network rollout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Chipset Design | Captive semiconductor production insulates margins from Taiwan foundry pricing volatility. |
| EU AI Act Pre-Certification Investment | Algorithmic transparency documentation accelerates CE marking for German tender participation. |
| Managed Security Service Partnership | Three-year platform contracts with Texas utilities lock in recurring revenue streams. |
| Millimeter-Wave Radar Module Launch | AI-integrated radar displaces thermal imaging for North Sea pipeline monitoring contracts. |
| Indian Smart City Testbed Entry | TRAI's 5G allocation enables Mumbai-scale deployments with mandatory data localization. |
Research Methodology
Operator-level perspectives from critical infrastructure security directors, semiconductor procurement leads at sensor OEMs, FCC regulatory affairs specialists, and EU AI Act compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, ETSI spectrum allocation records, EU Official Journal regulatory texts, and customs trade data for RF module imports. Bottom-up sensor deployment estimates and top-down defense procurement budget analysis were triangulated for volume reconciliation.
Scenario-bracketing framed optimistic, baseline, and constrained trajectories across the projection horizon. Segmentation dimensions modeled include transmission technology, deployment architecture, end-user procurement type, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle compression. Industry-specific inputs incorporated NATO drone platform procurement schedules and utility managed service contract conversion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed sensor platforms would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Middle East Manned Security Services Market