
 Europe People Screening Market | 2026-2036
Europe People Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe People Screening Market Insights
Cybersecurity talent scarcity across the EU is bifurcating vendor capabilities between integrated platform providers and point-solution specialists. Smiths Detection Group Ltd leverages its deep heritage in threat-detection hardware to sustain long-term contracts with British transport authorities. Rohde & Schwarz anchors its position through precision RF engineering that dominates millimeter-wave scanner calibration standards. CEIA competes aggressively on manufacturing scale, operating one of Europe's largest dedicated people-screening production facilities in Italy.
Europe people screening encompasses the hardware, software, and service systems deployed to detect concealed objects, verify identities, and assess behavioral risk in controlled-access environments, with millimeter-wave scanners typically operating at frequencies between 24 GHz and 300 GHz to achieve non-invasive full-body imaging at standoff distances of several meters. Its primary commercial purpose is to prevent weapons, explosives, and unauthorized materials from entering critical infrastructure while maintaining passenger throughput. Background checks within the service-type dimension remain the most mature revenue pool, whereas AI-powered analysis is expanding fastest as border agencies automate threat-flagging workflows. Among end users, government agencies command the largest installed base, though corporations are emerging as the fastest-growing buyer segment as workplace security protocols tighten across European headquarters.
GDPR constraints from EU data-protection authorities restrict how facial-recognition databases retain biometric templates, while the EU AI Act imposes risk-classification obligations on automated screening algorithms deployed in public spaces. CE marking under the EU's harmonized framework remains mandatory for electromagnetic equipment deployed in aviation and rail terminals. Stakeholders must monitor how emerging AI Act enforcement timelines interact with national procurement cycles to avoid stranded technology investments.
Market Dynamics
Millimeter-wave scanner deployment is bifurcating procurement strategies across European aviation and rail hubs, as transport authorities balance throughput velocity against GDPR-mandated data minimization protocols.
Growth Catalysts
- EU AI Act risk-classification mandates:Automated threat-flagging algorithms in public screening zones now face mandatory conformity assessments, accelerating replacement cycles for legacy rule-based detection systems.
- France's high-speed rail network expansion:SNCF and Eurostar terminal operators are procuring walk-through screening arches to maintain passenger flow during peak transit windows.
- Passive screening arrays:Standoff radar systems operating at 60-90 GHz enable concealed-object detection without physical pat-downs, reducing checkpoint staffing requirements at German aviation hubs.
Market Restraints
- GDPR biometric-template retention limits:Facial-recognition databases must purge templates within 72 hours for non-criminal screening contexts, degrading multi-session threat tracking capabilities.
- RF component supply concentration:Precision millimeter-wave sources and low-noise amplifiers concentrate among German and Swiss specialty foundries, exposing lead-time vulnerability.
- Millimeter-wave tissue-penetration physics:Current 24-300 GHz systems cannot reliably detect anomalies beneath dense clothing layers or within body cavities, creating persistent blind spots.
Strategic Opportunities
- Poland and Romania aviation infrastructure:Emerging Eastern European hubs lack mature screening footprints, presenting first-mover installation contracts as passenger volumes converge with Western European levels.
- Multimodal biometric fusion:Converging gait analysis with millimeter-wave scatter signatures enables behavioral-risk scoring without storing identifiable facial templates.
- CE marking harmonization under MDR:Medical-device-grade safety certifications for screening equipment open hospital and pharmaceutical-facility procurement channels previously blocked by liability concerns.
Industry Challenges
- AI-explainability engineering talent:Automated threat-flagging systems require algorithmic transparency documentation that exceeds current cybersecurity workforce supply across EU member states.
- Legacy X-ray baggage integration:New millimeter-wave body scanners must synchronize with existing hold-baggage explosives-detection systems through proprietary middleware, extending deployment timelines.
- CE-RED electromagnetic-compatibility certification:Radio-equipment directive testing for 5G-adjacent frequencies creates backlog at notified bodies, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe People Screening Market |
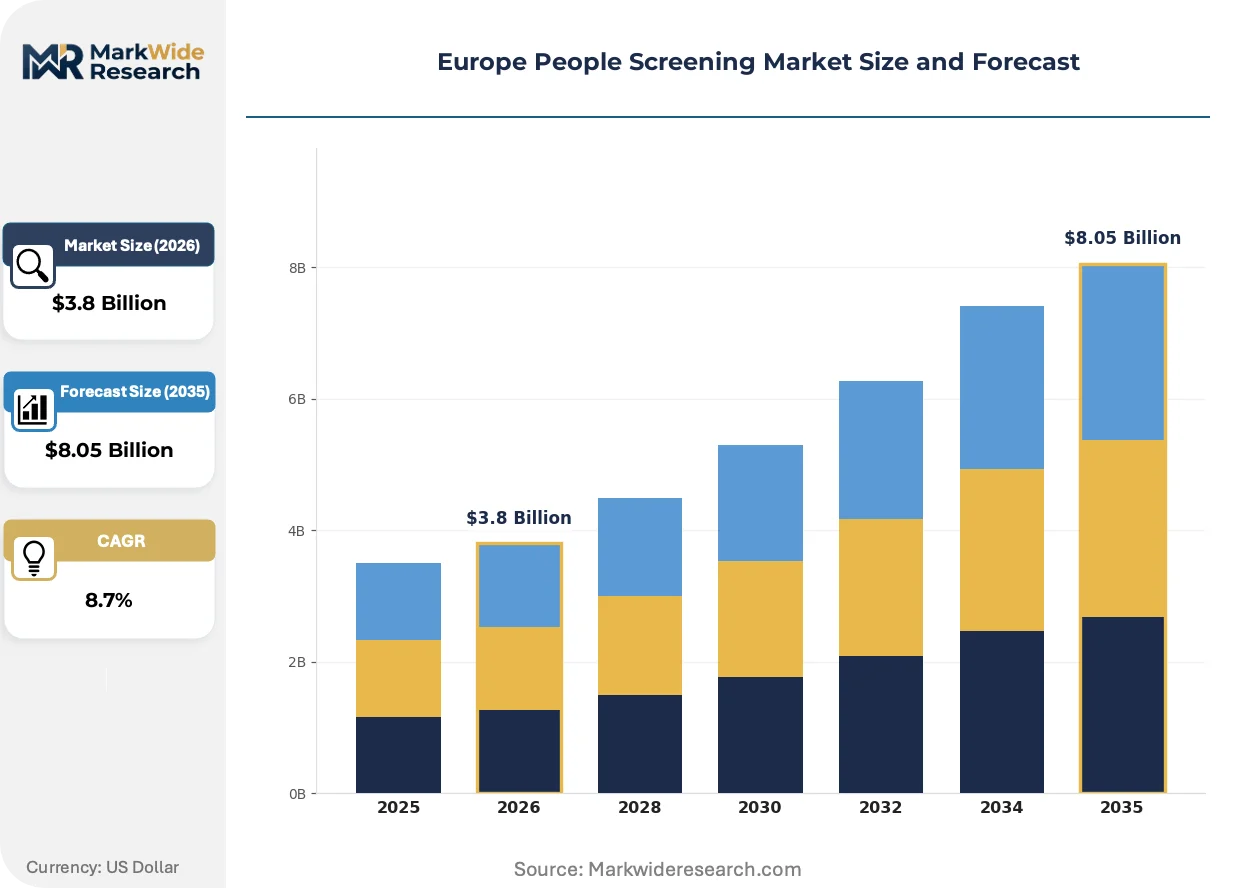
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Background Checks, Identity Verification, Criminal Record Checks, Employment Verification End User: Government Agencies, Corporations, Educational Institutions, Healthcare Providers Technology: Biometric Scanning, AI-Powered Analysis, Facial Recognition, Mobile Screening Solutions Compliance Standard: GDPR, ISO 27001, PCI DSS, Fair Credit Reporting Act |
| Companies Covered | Thruvision Ltd, LINEV Systems, Nuctech Company Limited, Smiths Detection Group Ltd, Rohde & Schwarz, OSI Systems, Leidos, 3DX-RAY, CEIA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe People Screening Market Trends and Innovations
Passive millimeter-wave imaging is displacing active scanning architectures, as European regulators tighten exposure limits for deliberate RF illumination of human subjects in public spaces.
Software-defined radio front-ends are bifurcating hardware procurement patterns. Transport authorities in Germany and the Netherlands now specify firmware-upgradable scanner platforms rather than fixed-function appliances. This architecture enables threat-library updates without physical hardware replacement, compressing vendor service-contract margins while extending equipment depreciation schedules.
GDPR enforcement timelines from CNIL and other EU data-protection authorities are accelerating anonymization-by-design mandates. Facial-recognition modules must now process biometric matches at the edge, with no central database retention. Screening-system vendors are responding with on-chip neural inference engines that eliminate cloud-dependent identity verification, most visibly in France's rail-terminal upgrade programs.
Subscription-based threat-intelligence feeds are displacing perpetual-license software sales. British and Italian airport operators now procure real-time pattern-recognition updates as operational expenditures rather than capital investments. This shift concentrates recurring revenue with integrated platform providers and squeezes point-solution specialists lacking sustained R&D pipelines.
Europe People Screening Market Segmentation
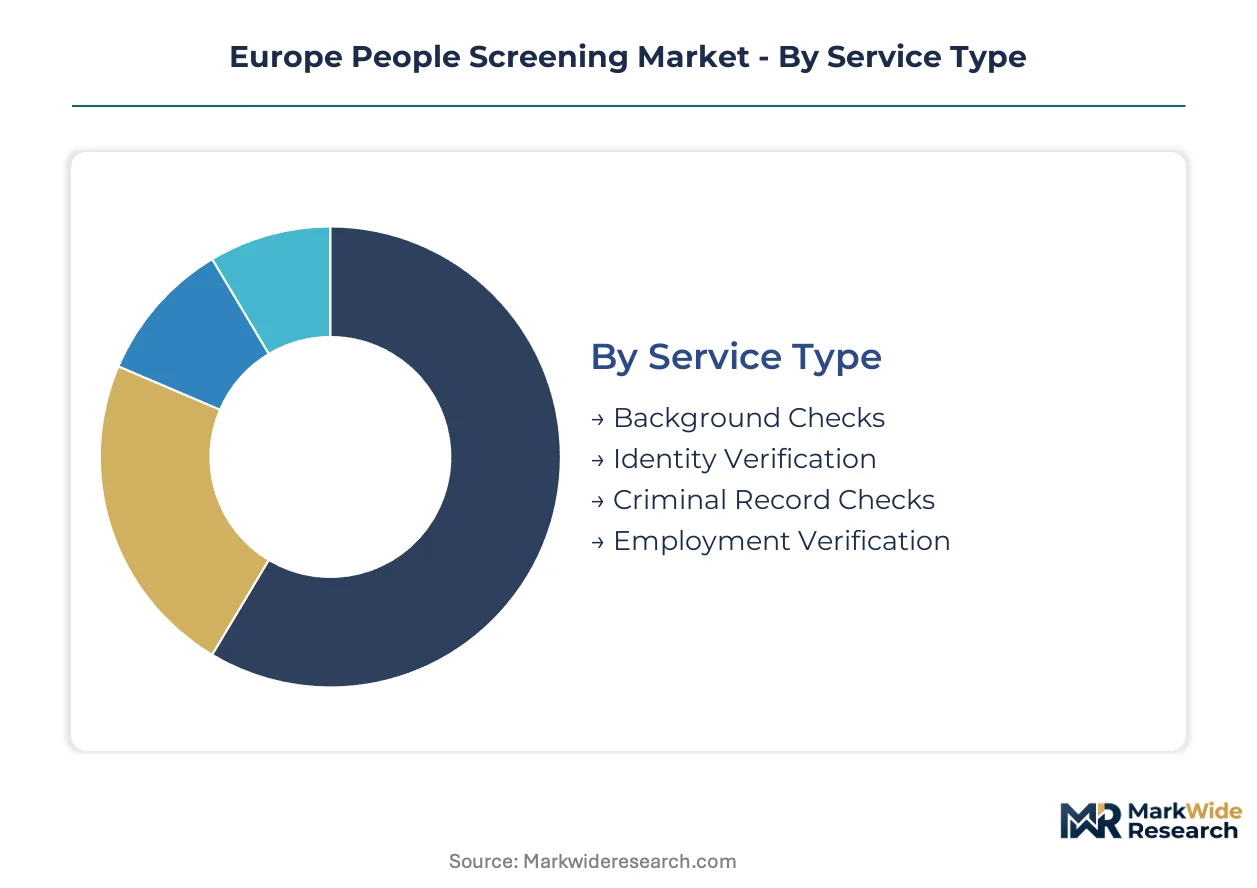
Procurement patterns across European aviation and rail terminals diverge sharply by segment, with GDPR and the EU AI Act imposing distinct compliance burdens on biometric versus non-biometric screening architectures. Vendors must align product roadmaps with divergent certification timelines and data-retention protocols governing each segment category.
Service Type:
GDPR's 72-hour biometric-template purge mandate creates asymmetric cost structures across verification modalities, favoring non-persistent screening methods in high-throughput environments.
- Background Checks:These services aggregate criminal, financial, and employment histories through centralized databases. German transport authorities and French rail operators rely on these checks for personnel vetting at critical infrastructure nodes, with contracts typically spanning multi-year frameworks.
- Identity Verification:Document-authentication and biometric-matching workflows that comply with EU AI Act risk-classification requirements. Demand concentrates at UK border crossings and Eurostar terminals where real-time passenger validation must balance speed against algorithmic transparency obligations.
- Criminal Record Checks:Police-clearance and judicial-database queries for high-security clearance positions.
- Employment Verification:Credential and work-history confirmation for contractor access to restricted zones.
Background Checks handle the majority of throughput; Identity Verification is expanding most quickly on share as border agencies automate passenger processing.
End User:
Customer procurement sophistication varies across institutional maturity, with government agencies demanding integrated platforms while corporate buyers prioritize modular point solutions.
- Government Agencies:National border forces, aviation security directorates, and transport police commands across Germany, France, and the UK. These entities specify CE-marked equipment with mandatory EU AI Act conformity assessments, driving replacement cycles for legacy rule-based detection systems at major hubs.
- Corporations:Multinational headquarters and financial institutions tightening physical-access protocols. Italian and Dutch corporate campuses are deploying mobile screening solutions for visitor management, bypassing the capital-intensity of fixed-installation millimeter-wave portals.
- Educational Institutions:University campuses and research facilities with controlled-access laboratories.
- Healthcare Providers:Hospital networks and pharmaceutical manufacturing sites requiring staff and visitor screening.
Government Agencies dominate installed base value; Corporations are climbing the fastest as workplace security protocols tighten.
Technology:
Hardware-software bundling economics favor integrated platform providers, while point-solution specialists compete on firmware-upgradable architectures that extend depreciation schedules.
- Biometric Scanning:Fingerprint, iris, and vascular-pattern recognition systems operating at the network edge to satisfy GDPR data-minimization requirements. German aviation hubs specify these for employee-access control, with templates processed on-device and purged per CNIL enforcement timelines.
- AI-Powered Analysis:Automated threat-flagging algorithms using millimeter-wave scatter signatures and behavioral pattern recognition. SNCF and British transport authorities are procuring these systems to reduce checkpoint staffing, though EU AI Act explainability mandates strain available engineering talent across member states.
- Facial Recognition:Template-matching systems constrained by 72-hour retention limits in non-criminal contexts.
- Mobile Screening Solutions:Portable millimeter-wave and biometric units for temporary checkpoints and event security.
Biometric Scanning commands the largest revenue pool; AI-Powered Analysis shows the steepest expansion trajectory as agencies automate threat workflows.
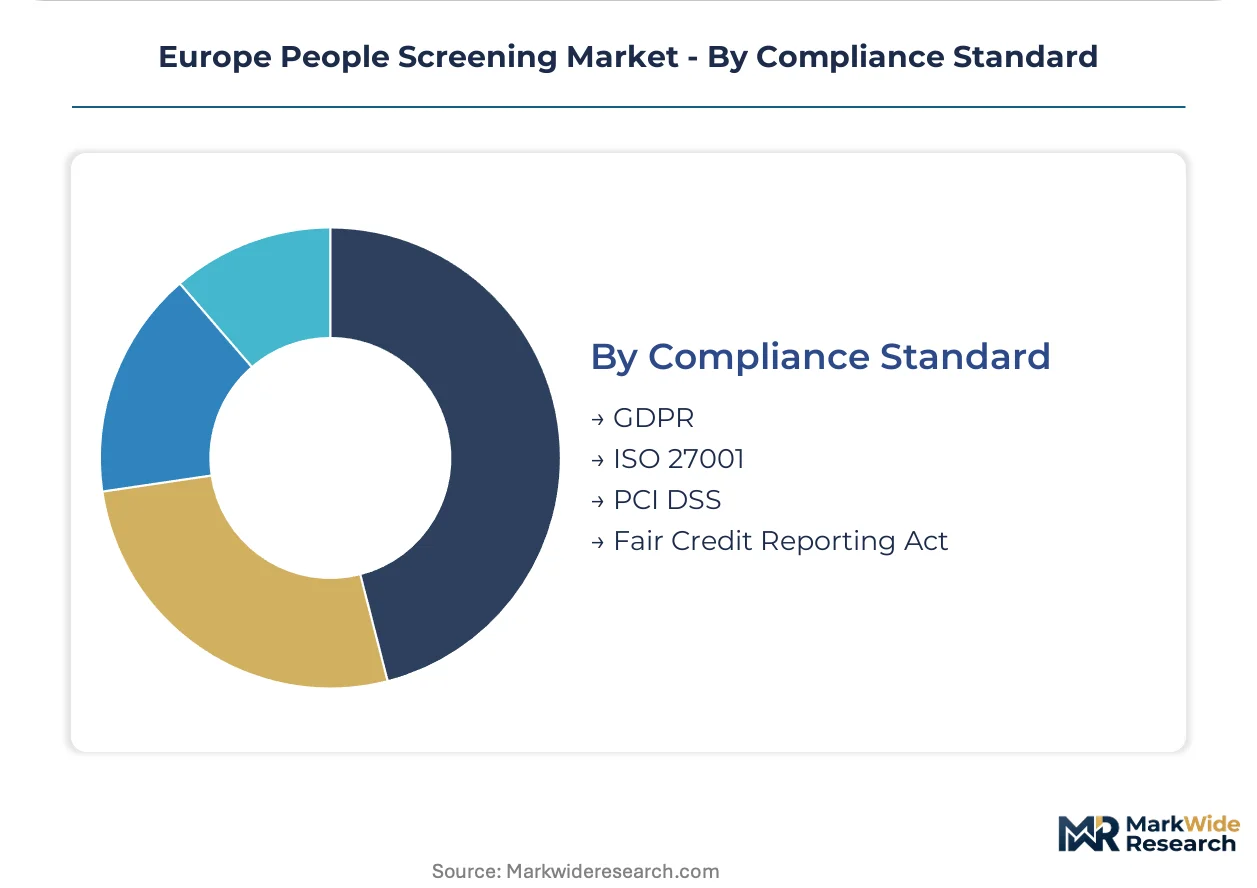
Compliance Standard:
Certification stacking requirements vary by deployment context, with aviation and rail terminals facing the most stringent multi-framework obligations.
- GDPR:The EU's data-protection regulation governs biometric-template retention, algorithmic transparency, and cross-border data transfers. French CNIL and German data-protection authorities enforce 72-hour purge mandates for facial-recognition databases in screening contexts, degrading multi-session threat-tracking capabilities.
- ISO 27001:Information-security management certification required by corporate and government procurement frameworks. Dutch and Belgian transport operators specify this for vendor qualification, particularly for cloud-connected screening platforms.
- PCI DSS:Payment-card industry standards for screening solutions integrating fare-collection or retail functions.
- Fair Credit Reporting Act:US-origin framework occasionally referenced by multinational corporations with transatlantic operations.
GDPR governs the broadest deployment base; ISO 27001 is gaining share fastest as cybersecurity requirements harden in procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors regulatory momentum across Germany, where federal aviation authorities drive procurement standards that cascade throughout the continent. France, the UK, Italy, and Poland each exhibit distinct deployment patterns shaped by national transport infrastructure priorities and data-protection enforcement timelines.
Germany
Fraport and Munich Airport authorities are expanding millimeter-wave scanner installations to process 90 million annual passengers. The Federal Office for Information Security enforces BSI baseline protection standards for biometric data processing at aviation hubs. Manufacturing clusters in Bavaria and Baden-Württemberg host precision RF component foundries supplying calibration systems for walk-through screening arches.
France
SNCF's €4 billion rail modernization program includes walk-through screening deployment at 15 high-speed terminal stations. CNIL enforces 72-hour biometric-template purge mandates that constrain facial-recognition retention across Paris Gare du Nord and Lyon Part-Dieu. The Île-de-France region concentrates system integration expertise serving both domestic rail and Eurostar cross-border checkpoints.
United Kingdom
Heathrow and Gatwick operators are replacing legacy X-ray portals with passive millimeter-wave arrays to reduce checkpoint staffing. The UK Information Commissioner's Office applies GDPR-equivalent constraints through the UK-GDPR framework post-Brexit. London's security-technology corridor hosts vendors specializing in edge-computing architectures that process biometric matches without cloud retention.
Italy
CEIA's manufacturing facility near Florence supplies screening arches to Mediterranean cruise terminals and domestic airports. The Garante per la Protezione dei Dati Personali enforces algorithmic transparency documentation for automated threat-flagging systems. Northern industrial clusters in Lombardy and Emilia-Romagna produce firmware-upgradable scanner platforms for corporate campus security deployments.
Poland
Chopin Airport and emerging regional hubs in Kraków and Gdańsk lack mature screening footprints, creating first-mover installation opportunities as passenger volumes approach Western European levels. The Polish Personal Data Protection Office aligns enforcement with EU AI Act timelines for automated decision-making systems. Warsaw's growing security-technology sector focuses on cost-optimized mobile screening units for temporary event deployments.
Europe People Screening Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European people screening market. The vendor base separates into integrated platform providers commanding long-term government contracts and point-solution specialists competing on firmware-upgradable architectures. Three strategic archetypes dominate: heritage defense-electronics conglomerates with precision RF engineering capabilities, manufacturing-scale specialists operating dedicated production facilities, and software-defined radio innovators compressing hardware replacement cycles. Competitive dynamics center on strategic partnerships with national transport authorities and portfolio diversification into medical-device-grade safety certifications.
Within the heritage defense-electronics tier, Smiths Detection Group Ltd and Rohde & Schwarz exemplify long-term contract anchoring through deep hardware heritage and RF calibration standard dominance. CEIA occupies a position representing manufacturing-scale competition through its dedicated Italian production facility. Thruvision Ltd sits within the passive-screening specialist archetype, reflecting software-defined radio front-end innovation that enables firmware-upgradable threat libraries without physical hardware replacement.
| Leading Market Players |
|---|
| Thruvision Ltd |
| LINEV Systems |
| Nuctech Company Limited |
| Smiths Detection Group Ltd |
| Rohde & Schwarz |
| OSI Systems |
| Leidos |
| 3DX-RAY |
| CEIA |
| Others |
Pricing and Supply Chain Analysis
Passive millimeter-wave arrays replacing active scanning architectures simultaneously concentrate procurement decisions among German and Swiss RF engineering clusters while compressing service-contract margins for vendors unable to offer firmware-upgradable platforms. This substitution dynamic redistributes value capture from hardware replacement cycles toward recurring threat-intelligence subscriptions, altering how transport authorities structure capital versus operational expenditures.
Pricing Analysis
German aviation hubs command 15-25% premiums over Polish and Romanian terminal procurements for equivalent millimeter-wave scanner specifications, reflecting divergent certification burdens and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies primarily by EU AI Act conformity assessment completion and GDPR edge-computing compliance. Cost compression in the standard tier intensifies because CE marking harmonization under MDR opens medical-device procurement channels previously blocked by liability concerns. Corporate campus buyers exhibit highest price sensitivity due to capital constraints, while government agencies prioritize certification completeness over unit economics.
Supply Chain Analysis
Inventory strategy across European screening equipment procurement favors just-in-time delivery for standardized millimeter-wave components, though strategic stockpiling persists for precision RF sources and low-noise amplifiers vulnerable to German and Swiss foundry lead-time volatility. Manufacturing concentration in Bavaria, Baden-Württemberg, and northern Italy draws from gallium arsenide substrates, precision machined waveguides, and neural inference chipsets. Single-source vulnerability concentrates in millimeter-wave calibration systems, where Rohde & Schwarz anchors technical standards. Distribution runs through national transport authority frameworks with multi-year service contracts, compressing spot-market opportunities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's people screening market approaches a platform-economics inflection as firmware-upgradable scanner architectures displace fixed-function appliances, rewarding vendors who control recurring threat-intelligence subscription revenue rather than one-time hardware margins. Interoperability mandates between millimeter-wave body scanners and legacy X-ray baggage systems intensify consolidation pressure among middleware providers.
For Market Incumbents: Shield long-term government contracts by accelerating backward integration into precision RF component manufacturing, reducing exposure to German and Swiss foundry bottlenecks. Deepen certification investment toward MDR medical-device pathways before liability-conscious hospital procurement committees finalize vendor qualification. Prioritize edge-computing R&D to satisfy CNIL and BSI data-localization mandates that degrade cloud-dependent competitors. For New Entrants and Emerging Players: Anchor in Poland and Romania aviation infrastructure gaps where passenger volume growth outpaces mature screening footprint deployment. Target mobile screening solutions for Italian and Dutch corporate campuses seeking capital-light visitor management alternatives to fixed-installation portals. Pursue firmware-upgradable platform partnerships with national rail operators replacing legacy rule-based detection systems under EU AI Act replacement cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform providers over point-solution specialists lacking sustained R&D pipelines. Long-term viability across the analysis window hinges on recurring revenue concentration rather than hardware replacement cyclicality. Monitor CE-RED electromagnetic-compatibility certification backlog resolution at notified bodies as inflection indicator for product launch velocity and vendor working capital stress.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Upgradable Platform Development | Enables threat-library updates without hardware replacement, extending depreciation schedules at German aviation hubs. |
| MDR Medical-Device Certification | Opens hospital and pharmaceutical-facility procurement channels previously blocked by liability concerns under CE marking. |
| Edge-Computing Architecture Investment | Satisfies GDPR 72-hour biometric-template purge mandates enforced by CNIL and German data-protection authorities. |
| RF Component Backward Integration | Reduces lead-time vulnerability from German and Swiss specialty foundries supplying precision millimeter-wave sources. |
| Subscription-Based Threat-Intelligence Feeds | Concentrates recurring revenue with integrated platform providers as British and Italian operators shift from perpetual licenses. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and transport authority procurement databases through bottom-up and top-down triangulation. Primary interviews engaged airport security directors, rail terminal operations managers, RF engineering specialists, and government procurement officers across Germany, France, the UK, Italy, and Poland. Secondary validation drew from EU AI Act implementation timelines, CE marking notification body records, GDPR enforcement decisions by CNIL and BSI, and SNCF infrastructure investment disclosures.
Segmentation dimensions modeled span service type, end user, technology, and compliance standard across the projection horizon, with additional granularity on firmware-upgradable versus fixed-function hardware architectures. CAGRs derive from installed base replacement cycle analysis, passenger throughput projections at aviation and rail hubs, and regulatory mandate enforcement timelines. Industry-specific forecast inputs incorporate EU AI Act conformity assessment completion rates and CE-RED electromagnetic-compatibility certification queue lengths at notified bodies.
Material uncertainties — GDPR enforcement intensity variations across member states, RF component supply disruptions, and EU AI Act explainability engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding transport authority budget continuity and passenger volume recovery trajectories. Revision becomes warranted when CE marking backlog duration or biometric-template retention rule changes cross thresholds that alter vendor product launch viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Radar Security Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Asia-Pacific Security Services Market