
 Drone Telematics Market | 2026-2036
Drone Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Telematics Market Foresight
Certified drone telemetry engineers is reorganizing competitive dynamics across the sector, with talent scarcity in embedded systems and RF communications pushing vendors toward automated platform architectures. Geotab leverages its automotive telematics heritage to extend sensor fusion capabilities into unmanned aerial fleets. Samsara dominates cloud-native fleet dashboards, while Trimble anchors high-precision GNSS integration for geospatial workflows.
Drone telematics encompasses the real-time acquisition, transmission, and analysis of flight telemetry data including position vectors, altitude resolution, IMU orientation, and power system status, typically sampled at 10-100 Hz for closed-loop flight control and post-mission analytics. The technology serves commercial operators by enabling predictive maintenance, geofence compliance, and operational audit trails across distributed fleets. Cloud-based deployment now captures the bulk of new enterprise subscriptions as operators prioritize elastic compute for AI-driven flight analytics. GPS technology leads hardware attach rates, though IMU modules are gaining traction in autonomous navigation stacks where centimeter-level dead reckoning matters. Delivery services represent the fastest-growing end-user vertical, driven by route-optimization requirements and payload integrity verification.
FAA Part 107 and forthcoming remote ID mandates shape product roadmaps, compelling manufacturers to bake broadcast capabilities into firmware layers before hardware ships. EASA's specific category framework and the EU AI Act's risk classification for autonomous systems add compliance overhead for vendors serving European operators. Stakeholders must weigh regulatory divergence against platform standardization bets as type certification requirements harden across jurisdictions.
Market Dynamics
FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations is compressing procurement cycles as precision agriculture operators scale fleet monitoring programs. Cloud-native architectures now dominate utility inspection deployments, forcing hardware vendors toward subscription revenue models.
Growth Catalysts
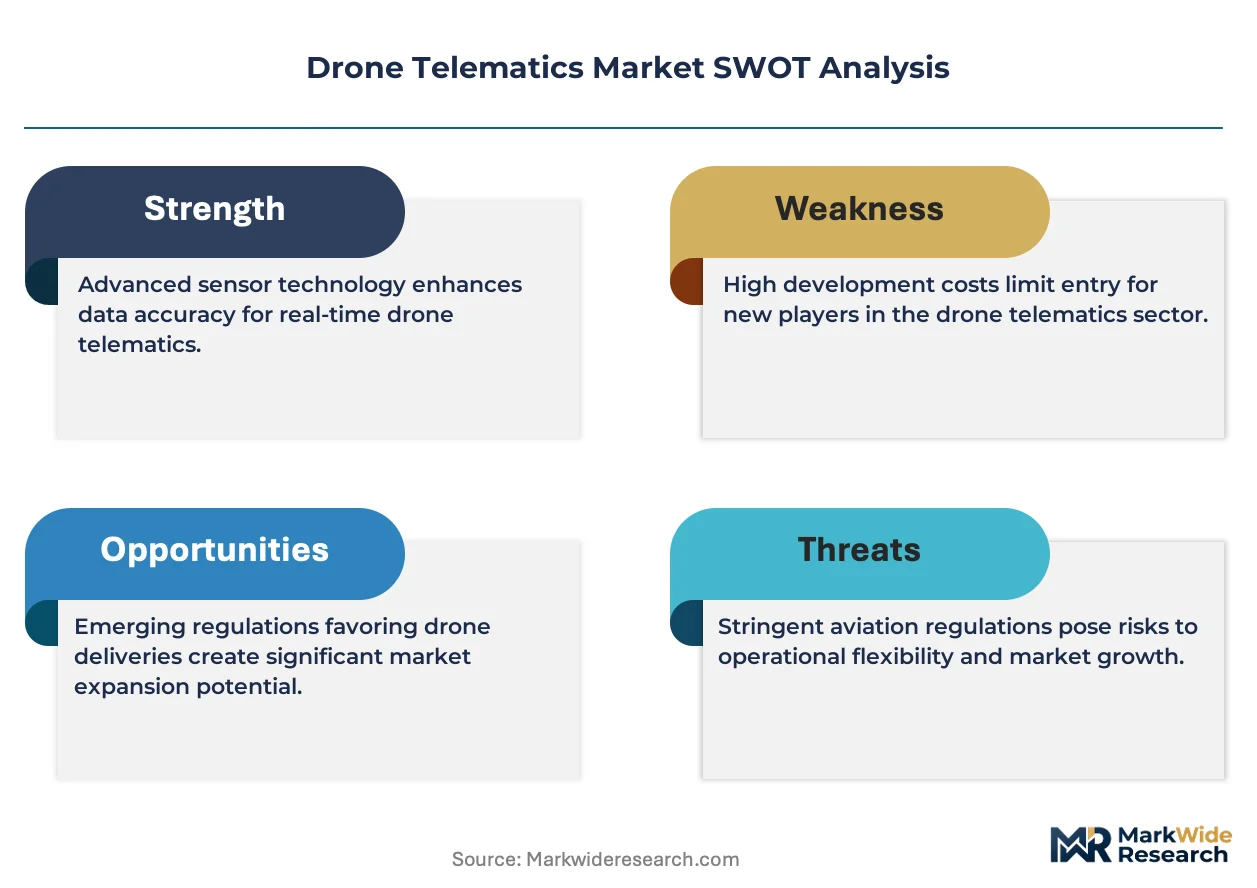
- BVLOS Regulatory Liberalization:FAA Part 107 waivers for extended range operations unlock commercial viability for pipeline and powerline inspection fleets. Operators in Texas and North Dakota are expanding multi-drone coordination programs.
- Remote ID Mandates:Broadcast telemetry requirements harden demand for integrated transponder modules. Manufacturers must embed firmware capabilities before hardware ships to avoid retrofit costs.
- AI-Driven Flight Analytics:Elastic cloud compute enables predictive maintenance algorithms sampled at 50-100 Hz. Agricultural cooperatives deploy these tools for irrigation scheduling and yield mapping.
Market Restraints
- RF Spectrum Congestion:C-band and ISM band saturation in urban corridors degrades telemetry link reliability. Operators face forced migration to licensed spectrum with higher equipment costs.
- Embedded Systems Talent Scarcity:Shortage of engineers proficient in real-time operating systems and RF communications pushes vendors toward automated platform architectures. Salaries for certified telemetry specialists have doubled in three years.
- EASA Certification Overhead:The specific category framework and EU AI Act risk classifications add compliance layers for vendors serving European operators. Type certification timelines extend 8-14 months.
Strategic Opportunities
- Last-Mile Delivery Integration:Route-optimization requirements and payload integrity verification create attach-rate expansion for telemetry suites. Logistics operators in Germany and the Netherlands pilot hub-to-doorstep autonomous networks.
- 5G Network Slicing:Ultra-reliable low-latency communication enables command-and-control handoff between cellular towers. South Korean carriers partner with drone manufacturers for dedicated aviation slices.
- Carbon Monitoring Contracts:Forestry and conservation agencies commission aerial methane and CO2 detection flights. Telemetry platforms must integrate hyperspectral sensor fusion for emissions quantification.
Industry Challenges
- Interoperability Fragmentation:Proprietary data protocols from Geotab, Samsara, and Trimble create integration friction for mixed-fleet operators. Customers demand standardized APIs for unified dashboarding.
- Post-Mission Analytics Latency:Edge computing limitations force tradeoffs between real-time decision-making and cloud-based model accuracy. Autonomous navigation stacks require sub-100ms IMU feedback loops.
- Cybersecurity Certification Delays:DO-326A airworthiness security standards and EU cybersecurity resilience requirements extend product development timelines. Firmware updates must pass airworthiness authority review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Telematics Market |
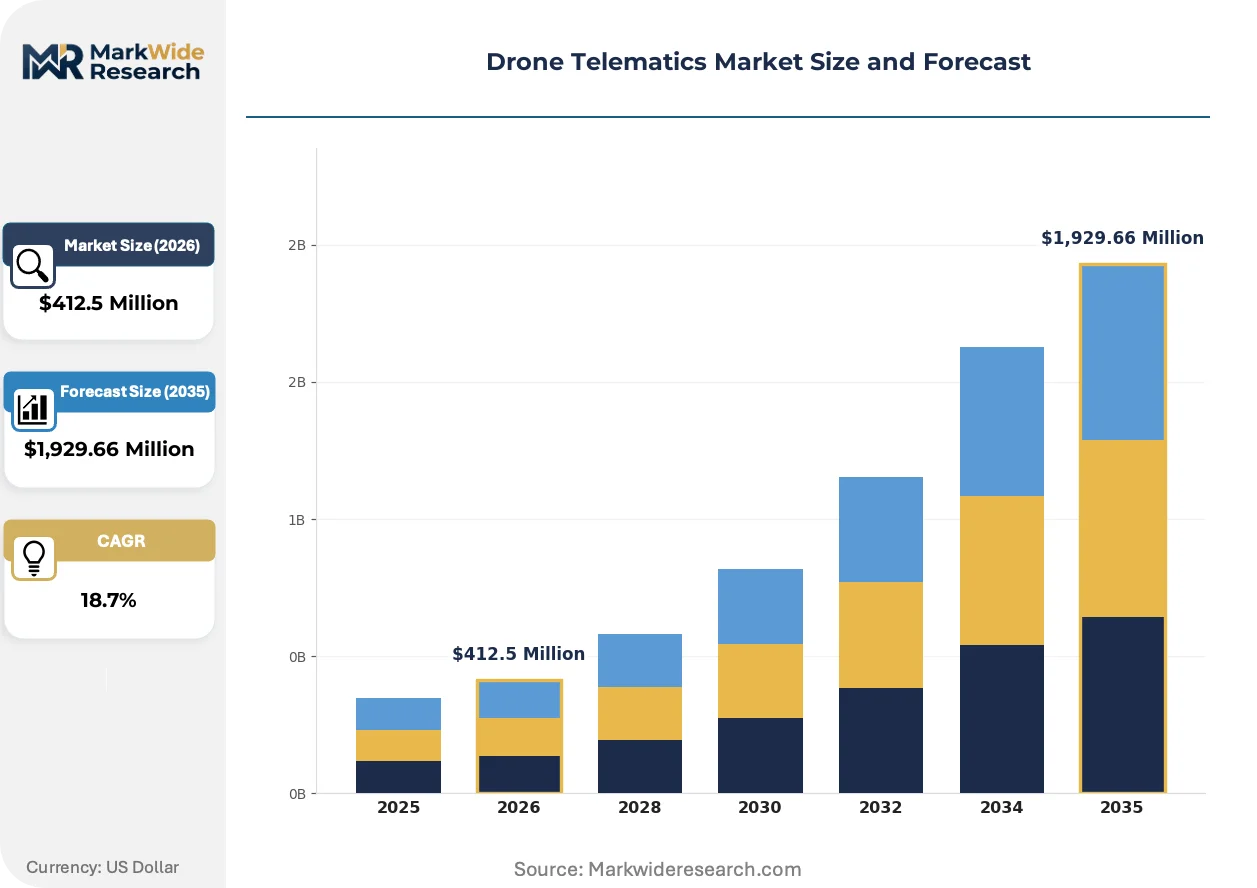
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, GLONASS, Barometric Altimeter, IMU Deployment: Cloud-Based, On-Premises, Hybrid, Private Network End User: Agriculture, Construction, Delivery Services, Emergency Services Application: Aerial Mapping, Infrastructure Inspection, Surveillance, Environmental Monitoring |
| Companies Covered | Motive, Azuga, Geotab, Omnitracs, Linxup, Verizon Connect, Trimble, Quartix, Samsara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Telematics Market Shifts & Advancements
Telemetry hardware architectures are fragmenting as specialized compute modules displace monolithic flight controllers. Regulatory mandates for broadcast positioning and remote identification are hardening firmware requirements before physical shipment.
Edge AI inference chips are decomposing traditional ground-station processing workflows. Autonomous navigation stacks in precision agriculture now embed neural accelerators for real-time obstacle detection. This compression eliminates latency to cloud servers during critical flight phases. Deere and Bayer crop science divisions demand on-board inference for immediate spraying adjustments.
EASA's specific category framework and the EU AI Act's risk classification for autonomous systems are reshaping product roadmaps. Manufacturers serving European operators must document algorithmic decision transparency and human oversight protocols. High-risk autonomous delivery flights face mandatory third-party conformity assessment before commercial deployment.
Subscription telemetry dashboards are displacing perpetual license sales in North American utility inspection programs. Elastic cloud compute contracts allow seasonal scaling for storm damage assessment fleets. Procurement teams at major power transmission operators now prioritize operational expenditure models over capital equipment ownership.
Drone Telematics Market Segmentation
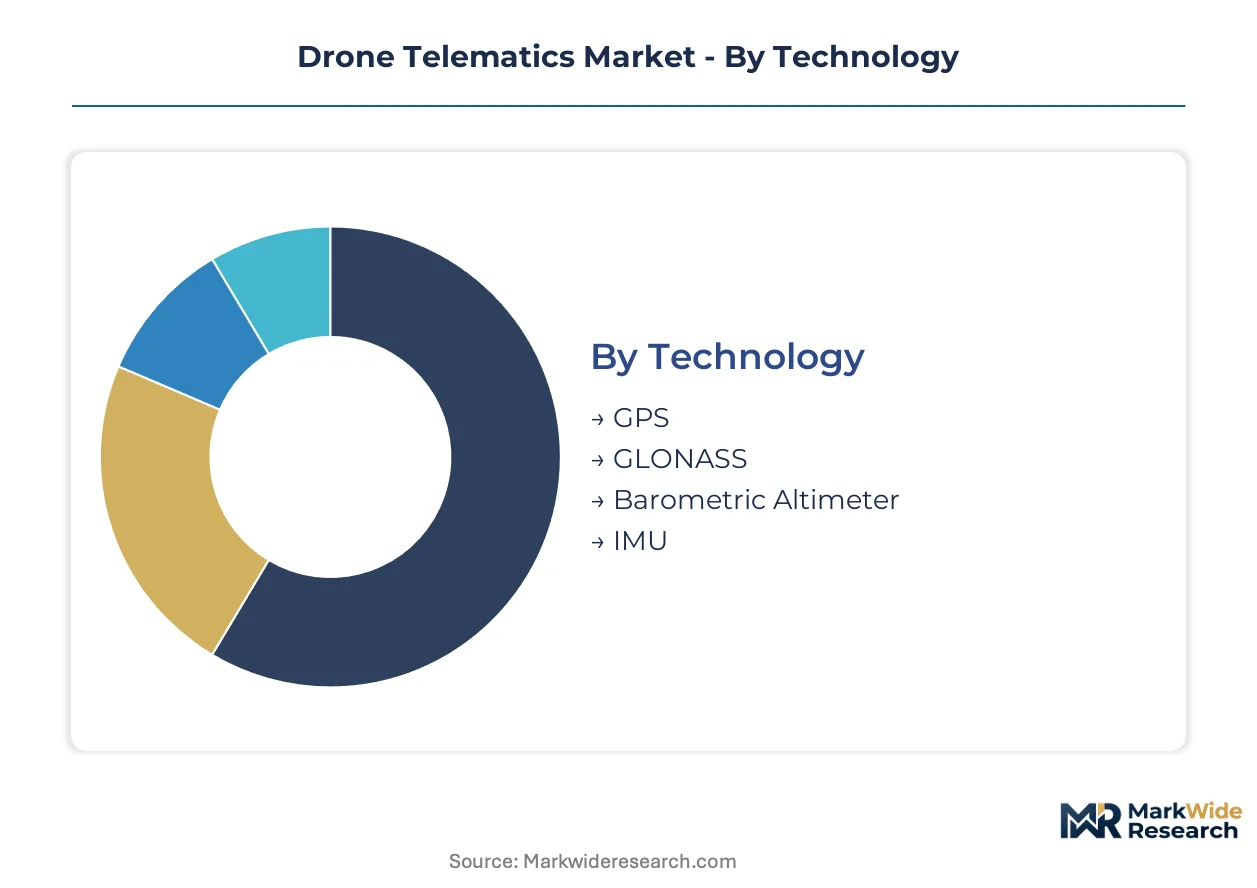
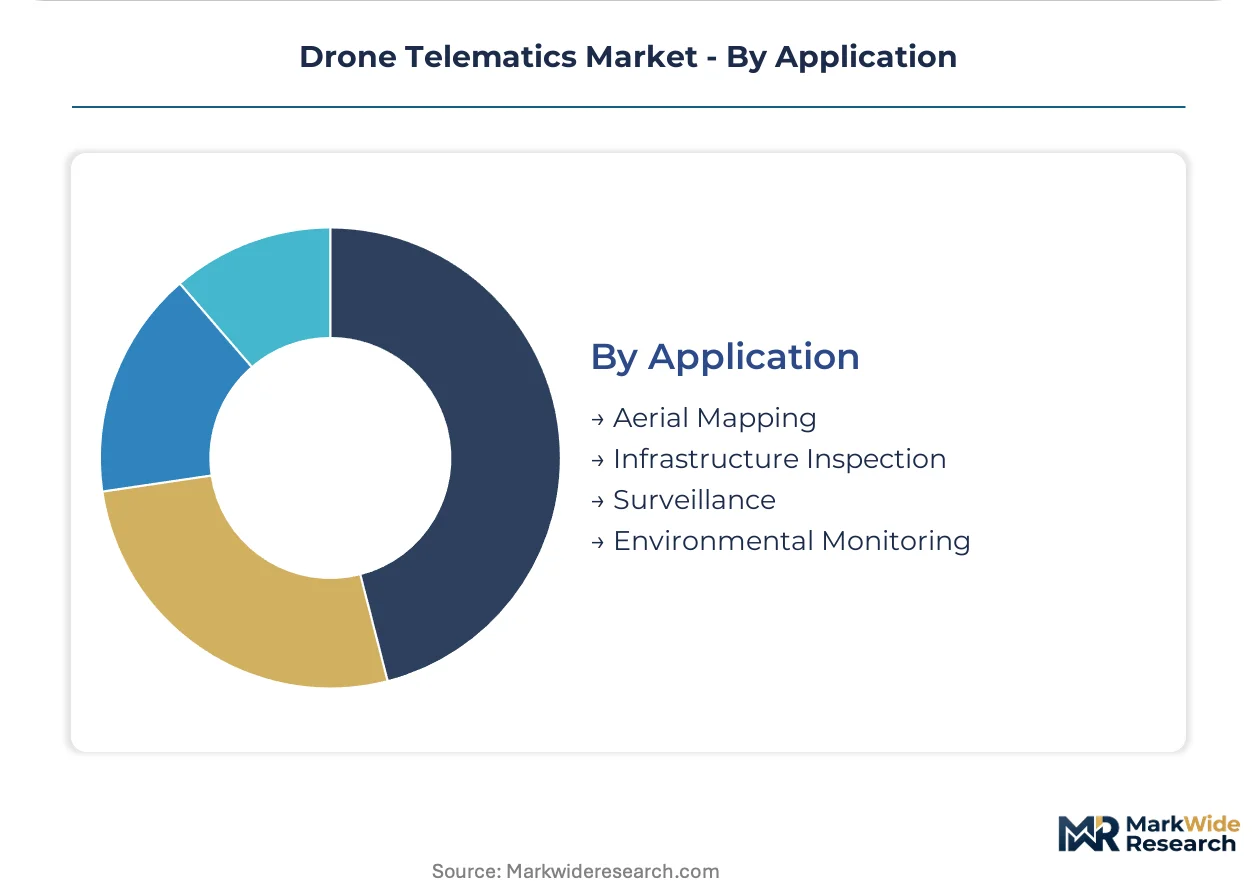
Drone telematics segmentation reveals distinct procurement patterns across regulatory environments. FAA Part 107 waivers and EASA specific category frameworks create divergent hardware requirements that reshape vendor product roadmaps. Understanding these technology-deployment-application linkages enables operators to match telemetry architectures against operational complexity and compliance overhead.
Technology:
FAA mandates for Remote ID broadcast capabilities and EASA algorithmic transparency requirements differentiate hardware attach rates across positioning and navigation modules.
- GPS:Multi-constellation receivers process L1/L2/L5 bands for meter-level accuracy in BVLOS corridors. Utility inspection fleets in Texas and North Dakota prioritize GPS-dominant stacks for powerline corridor mapping under extended-range waivers.
- IMU:Six-axis inertial measurement units sample angular rate and linear acceleration at 100 Hz for dead reckoning during GPS denial. Autonomous navigation stacks in precision agriculture embed IMU fusion for centimeter-level spraying adjustments where tree canopy blocks satellite signals.
- GLONASS:Russian constellation augmentation improves availability in high-latitude operations above 55 degrees north.
- Barometric Altimeter:MEMS pressure sensors deliver 10 cm resolution for terrain-following flight profiles.
Established volume favors GPS; emerging adoption favors IMU.
Deployment:
Cost tier differentiation separates enterprise-grade elasticity from captive infrastructure investments in regulated airspace operations.
- Cloud-Based:Elastic compute contracts enable seasonal scaling for storm damage assessment fleets. Major power transmission operators in the United States prioritize operational expenditure models that spin up analytics pipelines during emergency response windows.
- Private Network:Dedicated aviation slices through 5G network slicing deliver ultra-reliable low-latency command-and-control handoff. South Korean carriers partner with manufacturers for dedicated telemetry backhaul in urban delivery corridors.
- On-Premises:Air-gapped servers satisfy defense and critical infrastructure cybersecurity requirements.
- Hybrid:Edge-to-cloud orchestration balances real-time inference against post-mission model refinement.
Cloud architectures claim the majority of new enterprise subscriptions; private networks are climbing the fastest in regulated urban air mobility trials.
End User:
Application maturity and payload complexity separate high-frequency telemetry sampling requirements across commercial verticals.
- Delivery Services:Route-optimization algorithms and payload integrity verification demand 50-100 Hz telemetry streams for hub-to-doorstep autonomous networks. Logistics operators in Germany and the Netherlands pilot last-mile integration with real-time customer notification systems.
- Agriculture:Irrigation scheduling and yield mapping drive predictive maintenance deployments across cooperative fleets. Bayer and Deere divisions specify on-board neural accelerators for immediate agronomic adjustments.
- Emergency Services:Search-and-rescue operations require redundant telemetry links in terrain-blocked environments.
- Construction:Progress monitoring and volumetric surveying utilize lower-frequency logging for post-processing workflows.
Delivery services are gaining share fastest; agriculture maintains the deepest installed base.
Application:
Regulatory certification intensity and sensor fusion complexity create divergent margin structures across mission types.
- Infrastructure Inspection:Geofence compliance and operational audit trails for distributed fleets mandate persistent telemetry logging. Pipeline operators across the Permian Basin deploy cloud-native dashboards for corrosion monitoring under BVLOS waivers.
- Environmental Monitoring:Hyperspectral sensor fusion for methane and CO2 quantification requires calibrated telemetry timestamps. Forestry agencies in the Pacific Northwest commission aerial emissions detection with integrated atmospheric correction algorithms.
- Aerial Mapping:Photogrammetric block adjustments depend on precise exterior orientation parameters from integrated GNSS/IMU.
- Surveillance:Persistent stare operations prioritize link reliability over positional accuracy in border security deployments.
Infrastructure inspection anchors current procurement volumes; environmental monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Remote ID mandates and BVLOS waiver expansion anchor United States procurement patterns. European operators navigate EASA specific category frameworks and EU AI Act risk classifications. Asia-Pacific carriers pilot 5G network slicing for urban air mobility corridors.
United States
Precision agriculture operators in Texas and North Dakota scale multi-drone coordination programs under extended-range Part 107 waivers. FAA Remote ID broadcast requirements harden firmware capabilities before hardware shipment. Pipeline operators across the Permian Basin deploy cloud-native dashboards for corrosion monitoring under BVLOS permissions.
Germany
Logistics operators pilot last-mile autonomous networks with real-time customer notification systems. EASA specific category framework and EU AI Act algorithmic transparency requirements reshape product roadmaps. Forestry agencies in Bavaria commission aerial methane detection flights with integrated atmospheric correction.
China
MIIT spectrum allocation policies shape C-band telemetry link deployment in urban corridors. Dual carbon goals drive aerial emissions monitoring contracts for provincial environmental protection bureaus. Yangtze River Delta manufacturers embed neural accelerators for real-time obstacle detection in agricultural spraying fleets.
South Korea
Carriers partner with drone manufacturers for dedicated 5G aviation slices enabling ultra-reliable low-latency command-and-control handoff. National aviation authority type certification timelines compress for network-sliced urban delivery trials. Seoul Capital Area logistics operators demand 50-100 Hz telemetry streams for hub-to-doorstep autonomous networks.
Australia
Queensland mining operators deploy BVLOS inspection fleets for remote site surveillance with redundant telemetry links. Civil Aviation Safety Authority regulations mandate broadcast positioning capabilities for commercial operations above 250 grams. New South Wales emergency services integrate hyperspectral sensor fusion for bushfire detection missions.
Drone Telematics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in drone telematics. Automotive heritage players leverage sensor fusion capabilities while cloud-native entrants dominate subscription dashboard architectures. Telemetry hardware vendors and fleet management software providers represent distinct strategic archetypes. Competitive moves center on automated platform architectures and elastic compute contract structures.
Within the integrated tier, Geotab and Samsara occupy positions that exemplify divergent heritage advantages. Geotab represents automotive telematics extension into unmanned aerial fleets. Samsara anchors cloud-native fleet dashboard dominance. Trimble sits within the precision-geospatial specialist tier, anchoring high-precision GNSS integration for surveying workflows.
| Leading Market Players |
|---|
| Motive |
| Azuga |
| Geotab |
| Omnitracs |
| Linxup |
| Verizon Connect |
| Trimble |
| Quartix |
| Samsara |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts for 5G network slicing and cloud compute clusters lock in telemetry backhaul access while fixing operational expenditure visibility for fleet operators navigating FAA Part 107 waiver expansions. These structures bind hardware vendors to subscription revenue models and compress upfront equipment margins.
Pricing Analysis
North American utility inspection programs command 15-25% premiums over European agriculture deployments due to BVLOS certification requirements and elastic cloud scaling demands. Three-tier pricing structure across enterprise-grade, mid-market, and entry-level tiers separates FAA-compliant firmware stacks from basic GPS-logging modules. Pricing pressure stems from embedded systems talent scarcity doubling specialist salaries and forcing automation investments. Mid-market agriculture cooperatives exhibit highest price sensitivity; defense and critical infrastructure buyers show lowest.
Supply Chain Analysis
Strategic stockpiling of RF transceiver modules and neural accelerator chips dominates vendor inventory strategy ahead of Remote ID mandate deadlines and EASA certification windows. Component sourcing concentrates in Taiwan for edge AI inference silicon, South Korea for 5G modem chipsets, and China for MEMS pressure sensors and GPS receiver modules. Supply chain risk centers on single-source vulnerability for aviation-grade IMU fabrication. Distribution runs through specialized unmanned systems integrators and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone telematics sits in early-cycle expansion as FAA Part 107 waiver liberalization accelerates commercial fleet deployments beyond legacy visual-line-of-sight constraints.
For Market Incumbents: Compound sensor fusion capabilities through backward integration into IMU calibration facilities and RF communications firmware stacks. Defend position against cloud-native dashboard entrants by embedding predictive maintenance algorithms at the edge. Prioritize certification investment for EASA specific category frameworks ahead of EU AI Act enforcement timelines.
For New Entrants and Emerging Players: Anchor in carbon monitoring contracts for forestry and conservation agencies where hyperspectral telemetry integration remains underpenetrated. Target German and Dutch logistics operators piloting last-mile autonomous networks with 50-100 Hz streaming requirements. Pursue white-label firmware licensing to established automotive telematics vendors seeking aerial fleet extension.
For Investors and Strategic Acquirers: Telemetry hardware vendors with captive aviation certification pipelines represent the most defensible acquisition archetype. Frame long-term viability around Remote ID mandate compliance creating irreversible firmware attach rates. Watch BVLOS waiver approval velocity at FAA as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Aviation Certification Pipeline Investment | FAA Part 107 and EASA specific category approvals lock in hardware attach rates before competitors retrofit. |
| Edge AI Inference Chip Integration | Neural accelerators from NVIDIA and Qualcomm enable sub-100ms obstacle detection for autonomous navigation stacks. |
| 5G Network Slicing Partnership | South Korean carrier aviation slices deliver ultra-reliable command-and-control handoff in urban delivery corridors. |
| Subscription Dashboard Migration | Elastic cloud contracts at major power transmission operators displace perpetual license revenue models. |
| Hyperspectral Sensor Fusion Development | Methane detection algorithms for Pacific Northwest forestry agencies open environmental monitoring revenue streams. |
Research Methodology
Desk research of FAA waiver databases, EASA certification registries, and utility procurement disclosures preceded structured interviews with fleet operations managers at precision agriculture cooperatives, telemetry hardware engineering leads, and cloud infrastructure procurement officers at power transmission operators. Primary fieldwork validated attach rate assumptions for GPS and IMU modules across BVLOS and visual-line-of-sight deployments. Secondary sources included FCC spectrum allocation filings, SEC 10-K equipment revenue disclosures, and customs trade data for RF component imports. Bottom-up unit economics triangulated against top-down fleet expansion projections.
Variance decomposition across technology, deployment, end-user, and application segments drove analytical framework construction over the projection horizon. Modeled dimensions included positioning module type, cloud versus on-premises architecture, agriculture versus delivery verticals, and infrastructure inspection versus environmental monitoring missions. CAGRs derived from logistic adoption curves fitted to regulatory milestone timelines and fleet operator survey responses. Forecast inputs incorporated Remote ID mandate compliance deadlines and 5G network slicing deployment schedules.
Decision-makers should treat outputs as directional under assumptions of continued FAA waiver liberalization and stable C-band spectrum availability; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside EASA certification timeline assumptions. Revision becomes warranted when BVLOS waiver approval rates or embedded systems salary inflation cross thresholds that alter automation investment returns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Drone Data Services Market
UAV
GCC Drone Pilot Training Market
UAV
Global Drone Software Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Nano Drones Market
UAV
FPV Drone Goggles Market
UAV
North America Drone Software Market
UAV
Global Drone Analytics Market
UAV
Drone Roof Inspection Market
UAV
UAV Market
UAV
Micro Drone Market
UAV
Asia-Pacific Tactical UAV Market
UAV
Solar Powered Drones Market
UAV
Electric Glider Market
UAV
Home Security Drone Market
UAV
Fixed-Wing VTOL UAV Market