
 Aircraft Video Surveillance Systems Market | 2026-2036
Aircraft Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Video Surveillance Systems Market Analysis
High-definition CMOS sensor technology is expanding its share in aircraft video surveillance systems as operators replace legacy analog architectures to reduce weight and cabling complexity. Collins Aerospace leverages its integrated avionics portfolio to anchor positions across major commercial platforms. Thales Group competes through flight-certified camera modules that meet stringent DO-160 environmental standards. KID-Systeme GmbH specializes in compact embedded recording solutions tailored for regional jet configurations.
Aircraft video surveillance systems encompass cameras, digital video recorders, and networked monitoring infrastructure designed for airborne security and operational oversight. These systems typically operate across temperature ranges from minus 55 to plus 70 degrees Celsius and incorporate low-light enhancement for cabin and cargo bay visibility. IP-based technology leads installation trends as carriers migrate from coaxial to Ethernet backbone architectures that simplify maintenance and enable real-time ground streaming. Military Operations application demand is accelerating fastest among the four tracked segments, driven by ISR platform upgrades and unmanned aerial system integration requirements where thermal imaging capabilities command premium positioning.
FAA airworthiness directives and EASA certification specifications shape product development timelines and testing protocols for new entrants seeking OEM qualification. The EU AI Act introduces emerging compliance obligations for automated threat-detection algorithms deployed in passenger cabin monitoring. Stakeholders must evaluate how evolving cybersecurity standards from ISO and IEC will interface with existing RTCA DO-326A airworthiness security frameworks before committing to next-generation platform designs.
Market Dynamics
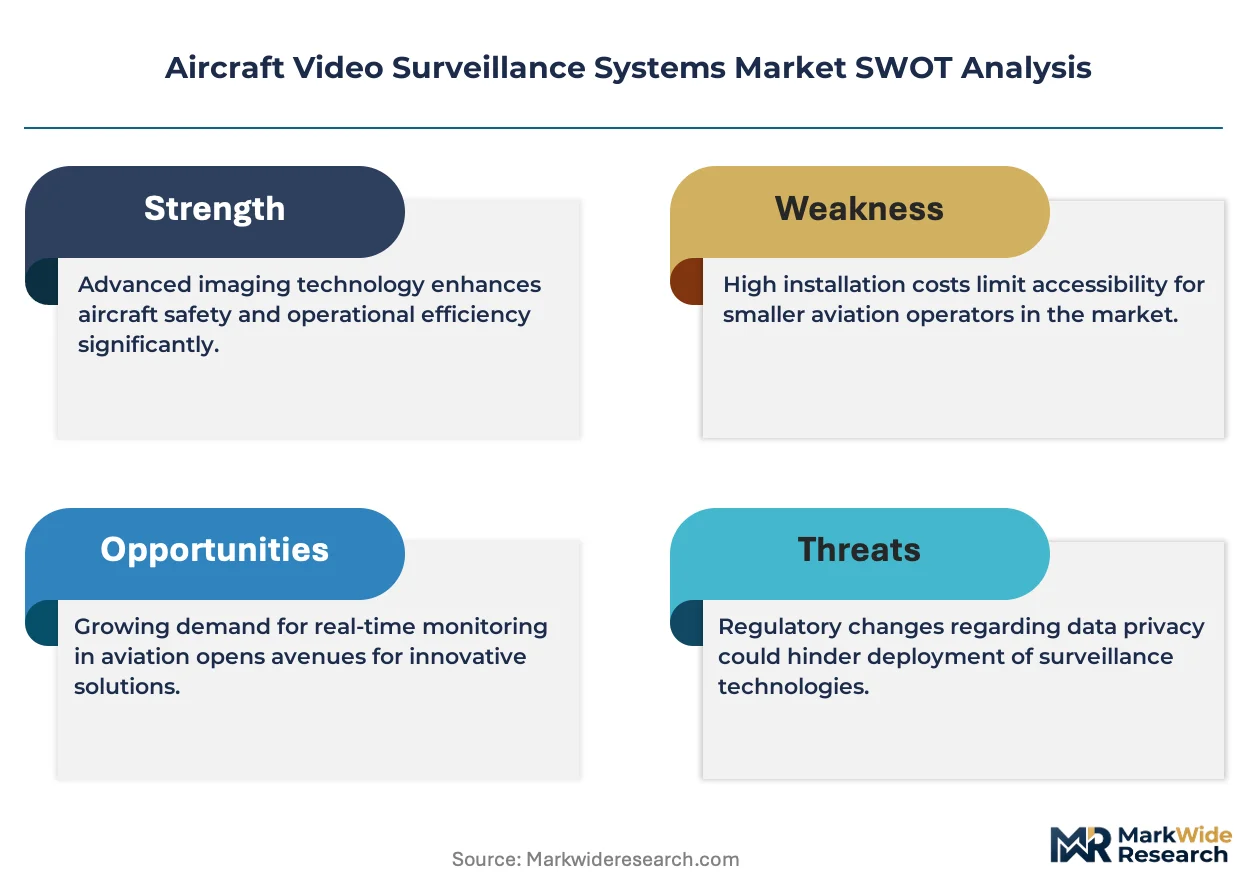
The transition from analog coaxial to IP-based Ethernet architectures is compressing installation timelines and maintenance burdens while expanding real-time ground connectivity capabilities for fleet operators.
Growth Catalysts
- FAA Flight Deck Security Mandates:Enhanced certification requirements for cockpit access monitoring are compelling carriers to upgrade surveillance infrastructure during scheduled heavy maintenance checks.
- CMOS Sensor Miniaturization:Reduced weight and power consumption compared to legacy CCD arrays are enabling retrofits on regional aircraft where payload margins are constrained.
- Military ISR Platform Modernization:Thermal imaging integration requirements for unmanned aerial systems are pulling advanced video processing capabilities into airborne surveillance supply chains.
Market Restraints
- DO-160 Environmental Testing Costs:Extended qualification cycles for temperature, vibration, and electromagnetic interference certification inflate development budgets for new entrants.
- Specialized Aerospace Semiconductor Supply:Concentration of radiation-hardened image sensor fabrication in limited foundry capacity creates input bottlenecks during demand surges.
- Legacy Analog Fleet Inertia:Narrow-body operators with deferred maintenance schedules face compressed installation windows that conflict with route utilization targets.
Strategic Opportunities
- India Civil Aviation Expansion:Low-cost carriers adding narrow-body capacity under the country's regional connectivity scheme present first-fit installation demand absent retrofit complexity.
- EU AI Act Automated Threat Detection:Compliance obligations for passenger cabin algorithmic monitoring are creating specification requirements that favor integrated hardware-software vendors.
- Edge Computing Convergence:Onboard video analytics processing is reducing bandwidth dependence for ground streaming while enabling faster incident response protocols.
Industry Challenges
- DO-326A Cybersecurity Integration:Airworthiness security frameworks demand specialized engineering talent scarce in traditional surveillance equipment supply bases.
- Retrofit Certification Parallelism:Supplemental type certificate approvals must synchronize with airframe maintenance schedules, compressing project management tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Video Surveillance Systems Market |
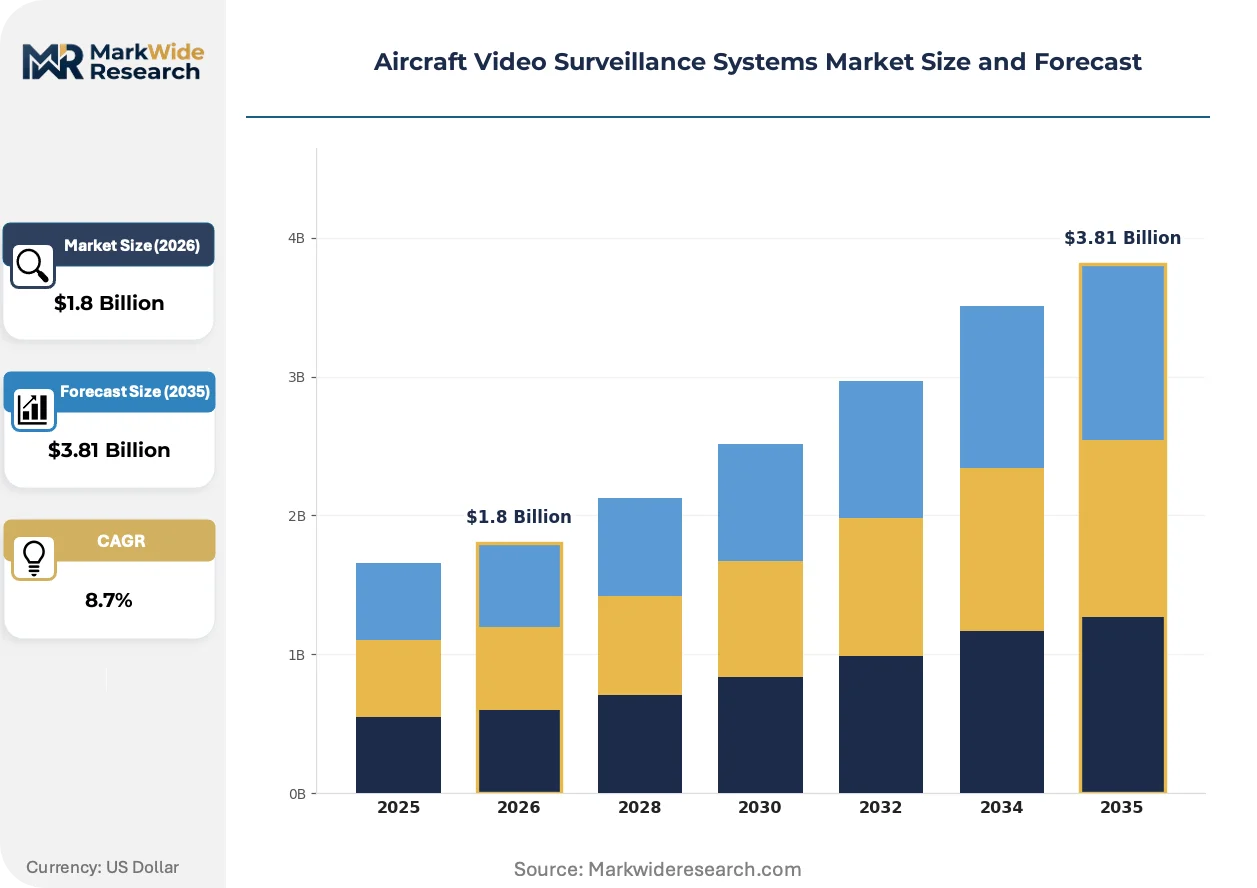
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog, IP-Based, HD, Thermal Application: Commercial Aviation, Military Operations, Cargo Transport, General Aviation Installation: Onboard, Ground-Based, Portable, Remote End User: Airlines, Government Agencies, Private Operators, Security Firms |
| Companies Covered | Latécoère, KID-Systeme GmbH, Collins Aerospace, Cabin Avionics, Thales Group, AD Aerospace Ltd., Global ePoint Inc., Teledyne Technologies Incorporated, Meggitt Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Video Surveillance Systems Market Emerging Trajectories
Compression of installation weight and cabling mass is enabling surveillance upgrades on aircraft categories previously excluded by payload economics. Three developments are restructuring competitive positioning.
Internet Protocol camera modules with Power-over-Ethernet delivery are rewriting the physical architecture of cabin monitoring systems. Low-cost carriers retrofitting narrow-body fleets are specifying these units to eliminate separate power harnesses. The technology is compressing installation labor hours and enabling incremental sensor additions without airframe rewiring.
The EU AI Act's algorithmic transparency requirements for automated passenger threat detection are mandating documentation standards for machine-learning training data. European operators are prioritizing surveillance vendors with established compliance pathways. The regulation is reshaping procurement evaluation criteria toward integrated hardware-software certification bundles.
Airlines are unbundling video surveillance maintenance from broader cabin systems contracts to capture specialized technical expertise. Third-party avionics service providers are displacing original equipment manufacturer service networks for post-warranty support. This pattern is most visible in the United States where major carriers operate dedicated technical operations centers.
Aircraft Video Surveillance Systems Market Segmentation
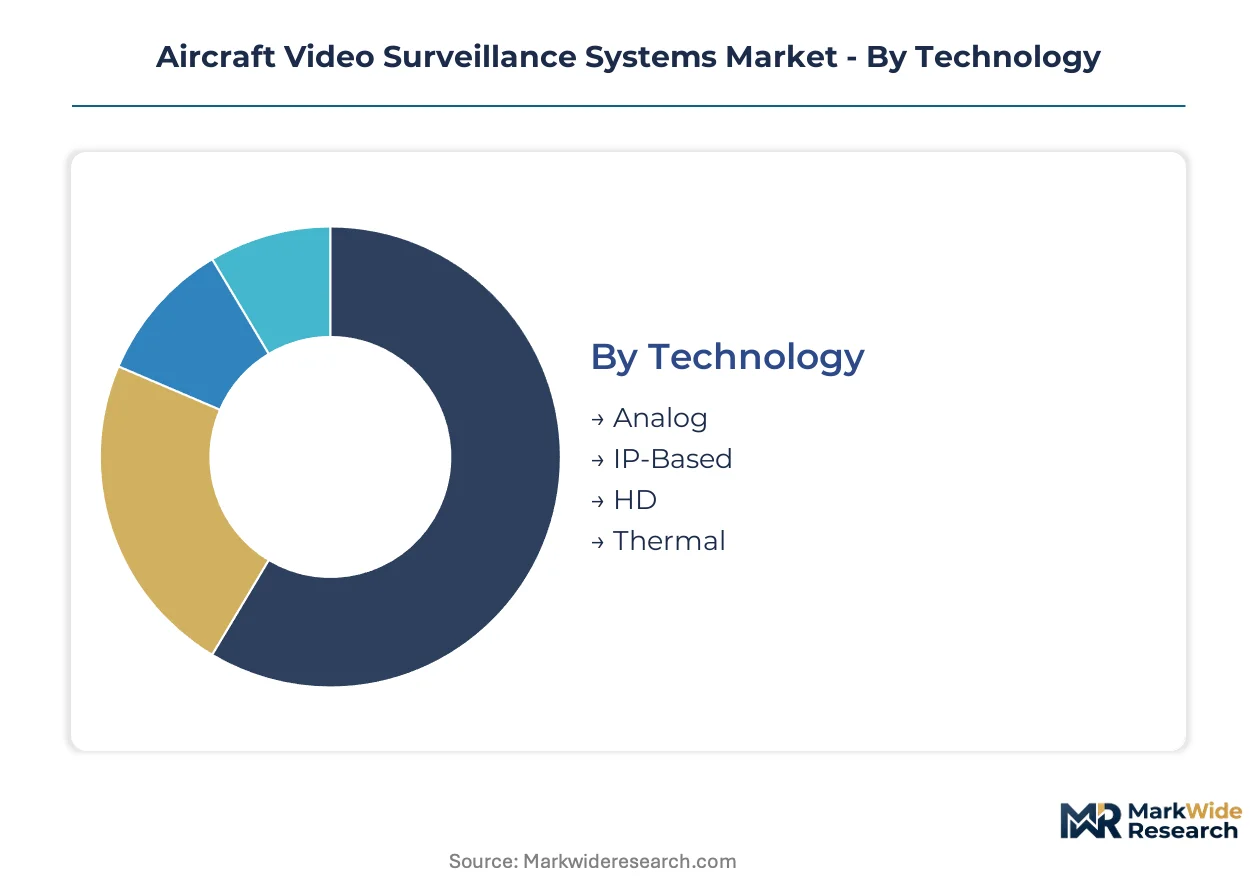
Segmentation in aircraft video surveillance systems reveals how technology choices cascade through certification requirements, installation economics, and operational use cases. Understanding these divides exposes where procurement budgets concentrate and where next-generation specifications are crystallizing.
Technology:
Sensor and transmission architectures concentrate supply among flight-qualified semiconductor vendors with DO-160 certification infrastructure.
- IP-Based:Ethernet backbone architectures with Power-over-Ethernet delivery eliminate separate power harnesses and enable incremental sensor additions without airframe rewiring. Demand concentrates in United States narrow-body retrofit programs where carriers seek reduced installation labor and real-time ground streaming capabilities.
- Thermal:Infrared imaging arrays operating across minus 55 to plus 70 degrees Celsius capture heat signatures for low-visibility cargo bay and military ISR applications. Military Operations in unmanned aerial system integration programs command premium positioning for these modules.
- Analog:Legacy coaxial architectures persist in deferred-maintenance narrow-body fleets where compressed installation windows conflict with route utilization targets.
- HD:High-definition CMOS sensor configurations reduce weight and cabling complexity compared to legacy CCD arrays.
Today's leader: IP-Based. Tomorrow's challenger: Thermal.
Application:
End-use environments impose distinct environmental qualification burdens and certification timelines.
- Military Operations:ISR platform upgrades and unmanned aerial system integration drive thermal imaging and advanced video processing requirements. Defense procurement cycles in the United States and European NATO members sustain long-term supply agreements with qualified vendors.
- Commercial Aviation:FAA flight deck security mandates compel cockpit access monitoring upgrades during scheduled heavy maintenance checks. Fleet operators in India and Southeast Asia present first-fit installation demand absent retrofit complexity.
- Cargo Transport:Automated threat-detection algorithms for freight monitoring face emerging EU AI Act compliance obligations for algorithmic transparency.
- General Aviation:Payload constraints and limited avionics budgets restrict adoption to high-net-worth owner-operators and fractional fleet programs.
Military Operations climbs the fastest; Commercial Aviation holds the volume base.
Installation:
Physical deployment mode determines maintenance contract structures and technical service provider relationships.
- Onboard:Permanent airframe-integrated systems with supplemental type certificate requirements that must synchronize with maintenance schedules. United States carriers increasingly unbundle surveillance maintenance from broader cabin systems contracts to capture specialized avionics expertise.
- Remote:Satellite-linked streaming architectures enabling ground-based monitoring without crew intervention. Demand emerging in unmanned cargo trials over the North Atlantic.
- Ground-Based:Fixed infrastructure at airport gates and maintenance facilities for pre-flight security screening.
- Portable:Temporary deployments for VIP transport and special mission aircraft requiring rapid reconfiguration.
Onboard dominates current revenue; Remote shows steepest expansion trajectory.
End User:
Procurement authority and budget cycles segment technical specification priorities and vendor relationship models.
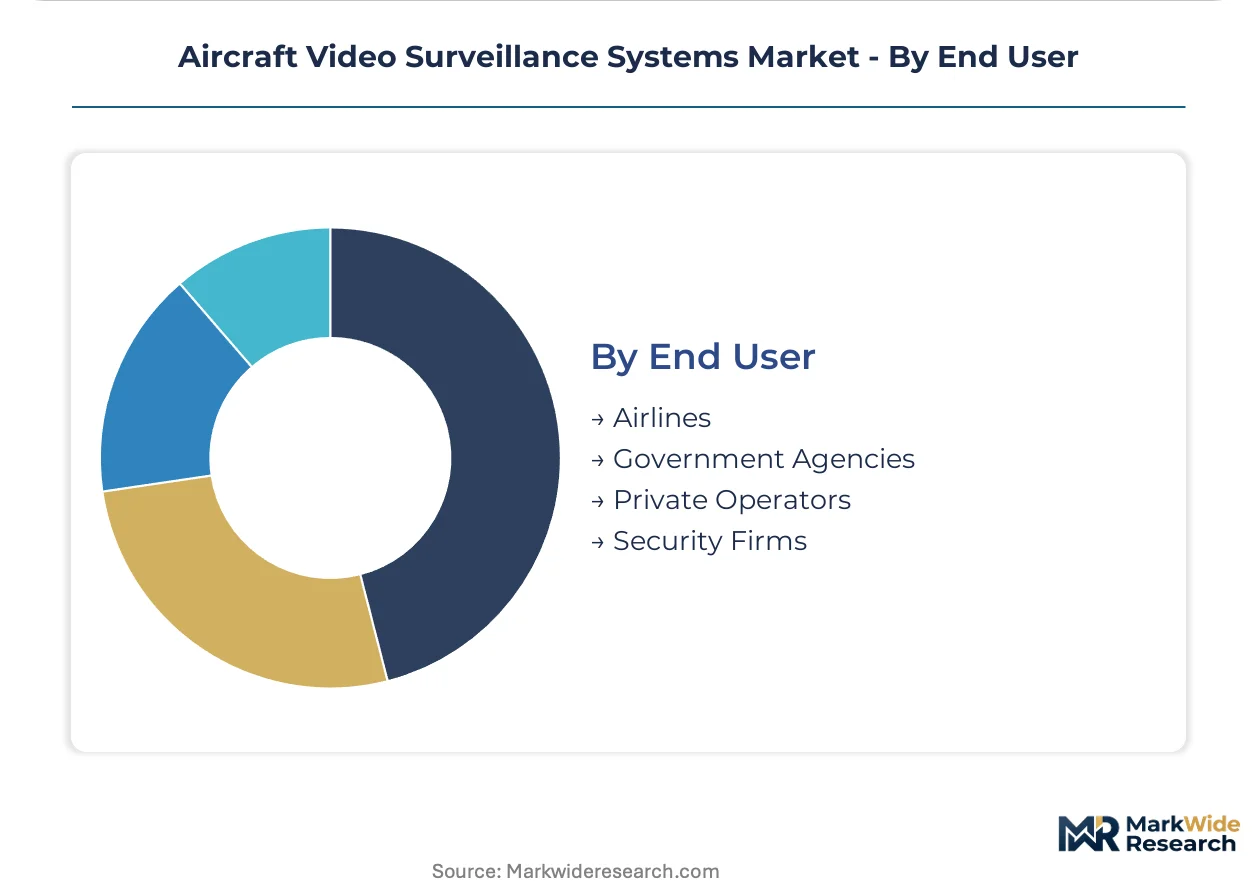
- Airlines:Fleet-wide standardization programs prioritize IP-based architectures with third-party post-warranty support. Major United States carriers operate dedicated technical operations centers displacing original equipment manufacturer service networks.
- Government Agencies:Defense and law enforcement procurement emphasizes thermal imaging and edge computing analytics with classified data handling protocols.
- Private Operators:Fractional ownership and charter fleets specify compact embedded recording solutions for regional jet configurations.
- Security Firms:Contracted airport perimeter and cargo screening services drive ground-based installation demand.
Airlines anchor current procurement; Government Agencies pull next-generation specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle-Tacoma aerospace corridor anchors procurement concentration for flight-qualified surveillance hardware, with major carriers operating dedicated technical operations centers that displace original equipment manufacturer service networks. FAA flight deck security mandates drive retrofit demand across narrow-body fleets. EASA certification specifications and the EU AI Act reshape procurement evaluation criteria toward integrated hardware-software bundles.
United States
Major carriers retrofit narrow-body fleets with IP-based surveillance architectures to capture real-time ground streaming capabilities. FAA mandates for enhanced cockpit access monitoring compel infrastructure upgrades during scheduled heavy maintenance checks. Dallas-Fort Worth and Atlanta technical operations centers unbundle surveillance maintenance from broader cabin systems contracts to secure specialized avionics expertise.
France
Defense procurement cycles sustain long-term supply agreements for thermal imaging modules serving ISR platform modernization. EASA certification specifications govern product development timelines for flight-qualified camera modules. Toulouse aerospace cluster concentrates integration activity for unmanned aerial system surveillance requirements.
Germany
Regional jet operators specify compact embedded recording solutions from specialized vendors serving constrained payload configurations. EU AI Act algorithmic transparency obligations for automated threat detection mandate documentation standards that reshape vendor selection criteria. Hamburg and Munich avionics engineering centers concentrate compliance engineering talent for emerging cybersecurity frameworks.
United Kingdom
Specialized aerospace semiconductor fabrication faces input bottlenecks during demand surges for radiation-hardened image sensors. CAA alignment with EASA certification specifications streamlines qualification pathways for domestic suppliers. Farnborough and Broughton industrial zones anchor flight-certified component manufacturing for export markets.
India
Low-cost carriers adding narrow-body capacity under the regional connectivity scheme present first-fit installation demand absent retrofit complexity. Bureau of Civil Aviation Security directives align with international standards for cabin monitoring systems. Bangalore and Hyderabad maintenance hubs develop surveillance integration capabilities for expanding domestic fleet requirements.
Aircraft Video Surveillance Systems Market Vendor Landscape
Global majors compete with regional champions across certification infrastructure and aftermarket service networks. The supplier base concentrates among flight-qualified avionics integrators with established DO-160 environmental testing capabilities and supplemental type certificate approval track records. Three archetypes dominate: integrated aerospace conglomerates with multi-platform avionics portfolios, specialized cabin surveillance vendors with compact embedded recording expertise, and defense-focused thermal imaging specialists serving ISR applications. Competitive moves center on strategic partnerships for cybersecurity compliance bundling and geographic expansion into Indian and Southeast Asian first-fit installation markets.
Within the integrated systems tier, Collins Aerospace and Thales Group exemplify multi-platform avionics positioning, while KID-Systeme GmbH occupies a specialized niche in regional jet configurations. These three anchors represent divergent scale and specialization strategies across commercial and military procurement channels.
| Leading Market Players |
|---|
| Latécoère |
| KID-Systeme GmbH |
| Collins Aerospace |
| Cabin Avionics |
| Thales Group |
| AD Aerospace Ltd. |
| Global ePoint Inc. |
| Teledyne Technologies Incorporated |
| Meggitt Plc |
| Others |
Supply Flow & Price Mechanics
Airline fleet standardization programs demanding DO-160-certified IP-based architectures are compressing supplier margins while forcing component vendors to absorb extended environmental qualification cycles. This procurement pressure concentrates pricing power among flight-qualified semiconductor foundries with established certification infrastructure.
Pricing Analysis
Input-cost pass-through from radiation-hardened CMOS sensor fabrication governs module pricing structures. Three-tier pricing separates flight-certified premium tiers from standard commercial aviation configurations and economy-grade regional jet offerings. Price differentiation centers on DO-160G environmental qualification tier and after-sales service bundling. Pricing pressure stems from carrier unbundling of surveillance maintenance contracts, which erodes OEM service revenue. Low-cost carriers in India exhibit highest price sensitivity, while defense procurement channels in the United States show lowest sensitivity due to thermal imaging performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for radiation-hardened image sensor wafer fabrication, while Germany and the United States concentrate flight-certified camera module assembly. The supply chain draws from specialized aerospace-grade semiconductor substrates, Ethernet PHY transceivers, and aluminum-housing thermal management components. Tariff exposure on Chinese-sourced passive electronics creates input cost volatility for cost-sensitive regional jet configurations. Distribution runs through OEM avionics integrators, third-party technical service providers, and direct airline technical operations center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by FAA and EASA regulatory mandates that compel systematic fleet upgrade cycles regardless of airline profitability cycles.
For Market Incumbents: Lock in aftermarket service contracts before carrier technical operations centers mature internal avionics expertise. Deepen backward integration into radiation-hardened sensor packaging to offset foundry concentration risk. Prioritize DO-326A cybersecurity certification investment as EU AI Act compliance obligations reshape procurement evaluation criteria. For New Entrants and Emerging Players: Direct-to-airline digital procurement platforms offer route access bypassing entrenched OEM service networks. Target India's regional connectivity scheme first-fit installations where retrofit complexity is absent and carrier procurement teams seek cost-optimized IP-based architectures. Position through compact embedded recording solutions tailored for constrained payload regional jet configurations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cabin surveillance vendors possessing EU AI Act algorithmic transparency documentation and established supplemental type certificate track records. The five-to-ten-year viability window favors acquisition targets with integrated hardware-software certification bundles rather than pure component suppliers. Watch for FAA flight deck security mandate expansion beyond narrow-body fleets as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Compliance Bundling | DO-326A certification investment aligns with EU AI Act algorithmic transparency requirements for automated threat detection. |
| Regional Jet Configuration Specialization | Compact embedded recording solutions capture payload-constrained demand from expanding India connectivity schemes. |
| Third-Party Service Network Expansion | Technical operations center partnerships displace OEM maintenance contracts for post-warranty surveillance support. |
| Thermal Imaging Module Development | Defense ISR platform modernization in NATO member states sustains long-term supply agreement premiums. |
| Edge Computing Analytics Integration | Onboard video processing reduces bandwidth dependence for real-time ground streaming capabilities. |
Methodological Framework
Bottom-up airline fleet modeling reconciled against top-down avionics supplier tracking forms the analytical core of this study. Primary interviews with fleet engineering directors, avionics procurement managers, DO-160 testing laboratory technical leads, and supplemental type certificate approval specialists combined with secondary validation from FAA airworthiness directive filings, EASA certification specification databases, airline fleet planning disclosures, and customs records for flight-qualified camera module trade flows. Triangulation between installation demand projections and semiconductor foundry capacity allocation data ensures statistical integrity.
Input-output matrix framing connects CMOS sensor unit economics, Ethernet infrastructure deployment rates, and thermal imaging module production capacity to end-use segmentation outputs across commercial aviation, military operations, cargo transport, and general aviation channels. Modeled dimensions span technology architecture, application environment, installation mode, and procurement authority. CAGRs derive from fitted adoption curves calibrated against regulatory mandate implementation timelines and fleet replacement cycles. Forecast inputs include airline narrow-body retrofit scheduling patterns and unmanned aerial system integration program funding authorizations.
Regulatory mandate delay, foundry capacity constraints, and carrier deferral of heavy maintenance checks are the dominant revision risks that could compress or extend projected installation timelines. Forecasts reflect documented assumptions about certification pathway durations and procurement budget allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Under-Vehicle Surveillance Market