
 Global Night Vision System and Driver Monitoring System Market | 2026-2036
Global Night Vision System and Driver Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Night Vision System and Driver Monitoring System Market Intelligence
The bundling of night vision and driver monitoring systems into unified advanced driver-assistance systems (ADAS) packages is recalibrating OEM procurement strategies. Robert Bosch GmbH leverages its extensive electronics portfolio to offer integrated solutions. Continental AG competes on the strength of its sensor fusion technologies. Valeo differentiates through its specialization in optical and camera-based systems, securing its position with key European automakers.
Night vision and driver monitoring systems are integrated automotive safety technologies designed to enhance driver perception and alertness. These systems utilize thermal cameras or infrared sensors operating in the 8-14 micrometer wavelength to detect pedestrians and obstacles, while internal cameras track driver eye movement and head position. Within the technology landscape, active night vision systems are gaining traction in premium passenger cars. For end users, demand from OEMs for factory-fitted units continues to dominate the market over aftermarket installations.
Regulatory frameworks are a significant market accelerator, with the EU's General Safety Regulation mandating advanced driver systems. Similarly, guidelines from the US National Highway Traffic Safety Administration (NHTSA) and China's GB standards for vehicle safety are compelling automakers to standardize these features. Component suppliers must now decide whether to specialize in sensor technology or develop complete, integrated system-level solutions for automakers.
Market Dynamics
The convergence of night vision and driver monitoring into unified ADAS packages, driven by stringent global safety regulations, is the central force shaping the market. This mandate-driven integration compels automakers to adopt these systems, transforming them from luxury features to standard equipment.
Growth Catalysts
- Regulatory Mandates:The EU's General Safety Regulation and similar directives from the US NHTSA and China's GB standards require advanced safety systems, making driver monitoring and night vision essential for new vehicle type-approvals.
- Commercial Vehicle Safety:Demand within the commercial vehicles segment for systems that monitor driver fatigue and enhance visibility during night-time operation is a significant growth vector, aimed at reducing accidents and improving fleet safety.
- Manufacturing Concentration:China's position as a dominant automotive manufacturing hub creates concentrated demand, with both domestic and international OEMs integrating these systems to meet local standards and export requirements.
Market Restraints
- High System Cost:The significant cost of components, particularly thermal cameras and infrared sensors, creates a price barrier for adoption in economy and mid-range passenger vehicles, limiting volume outside the premium segment.
- Technical Performance Limits:System effectiveness can be diminished by adverse weather conditions such as heavy rain, snow, or fog, which can impair sensor performance and lead to reliability concerns among end users.
- Integration Complexity:Integrating these advanced systems into diverse vehicle electrical and electronic architectures presents a substantial technical hurdle, requiring significant R&D investment and validation time for automakers and Tier 1 suppliers.
Strategic Opportunities
- Sensor Fusion Development:A clear opportunity exists in developing platforms that fuse data from night vision, driver monitoring, radar, and LiDAR to create more comprehensive and reliable situational awareness for higher levels of autonomous driving.
- Aftermarket Fleet Solutions:The large existing global fleet of commercial vehicles without factory-fitted systems represents a target market for aftermarket solutions, especially for logistics companies seeking to upgrade safety and comply with insurance requirements. *Emerging Market Penetration: Automotive markets in India and Brazil, which are strengthening vehicle safety standards, offer long-term growth potential as consumer and regulatory demand for ADAS features increases.
Industry Challenges
- Data Privacy and Security:The collection of biometric data by driver monitoring systems raises significant privacy concerns and creates cybersecurity vulnerabilities, requiring robust data protection and encryption protocols to gain consumer trust.
- Lack of Standardization:Divergent regional standards for system performance, testing protocols, and data formats create design and compliance complexity for suppliers operating across multiple geographic markets.
- Software Integration Burden:The operational challenge of ensuring seamless software integration and interoperability between the monitoring systems and a vehicle's central ADAS domain controller is a major resource drain for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Night Vision System and Driver Monitoring System Market |
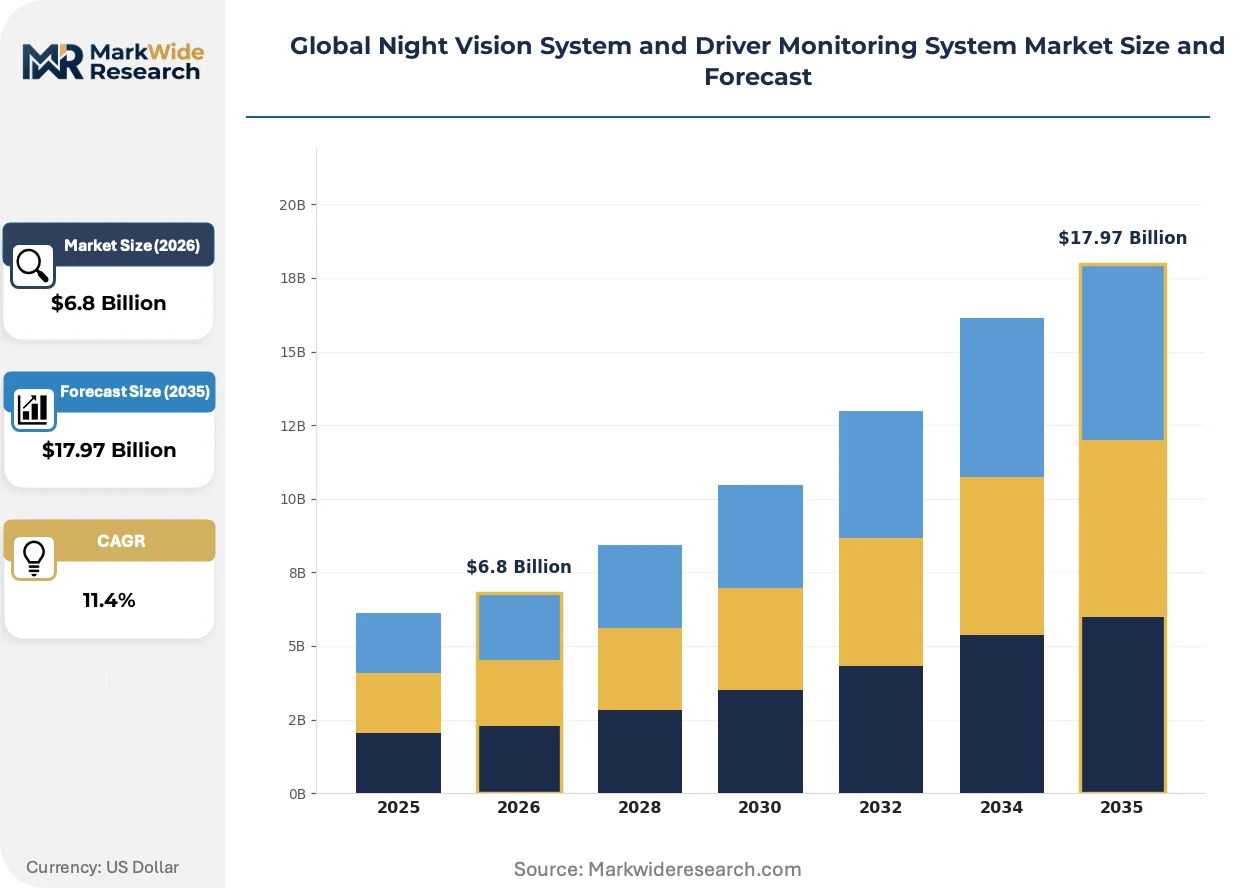
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cameras, Infrared Sensors, Radar Systems, Optical Devices Technology: Active Night Vision, Passive Night Vision, Driver Monitoring, Lane Departure Warning End User: OEMs, Aftermarket, Fleet Management, Commercial Vehicles Application: Passenger Cars, Trucks, Buses, Two-wheelers |
| Companies Covered | Aisin Seiki Co., Ltd., Valeo, Omron Corporation, Magna International Inc., Denso Corporation, Robert Bosch GmbH, Continental AG, Autoliv Inc., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Night Vision System and Driver Monitoring System Market Strategic Shifts & Innovations
System integration and sensor fusion define the market's technological trajectory. The evolution is from discrete, single-function components toward intelligent, interconnected safety platforms that provide a holistic view of the vehicle's external environment and the driver's internal state.
Active night vision systems, which utilize near-infrared illuminators and cameras, are a key technological development. This technology is being adopted by automakers in the premium passenger car segment to provide high-resolution, real-time images of the road ahead. As manufacturing scales and component costs fall, this advanced capability is expanding into mid-range vehicle platforms, differentiating them on safety.
China's GB standards for vehicle safety are becoming a powerful influence on system design and deployment. These national standards increasingly compel automakers to include driver monitoring systems to mitigate risks associated with driver fatigue, especially in commercial vehicles. Consequently, the long-haul trucking segment is experiencing a rapid design-in cycle for compliant systems to meet domestic regulations.
Automakers are fundamentally altering their sourcing strategies for safety technologies. The procurement model is shifting from buying individual sensors toward acquiring pre-integrated, validated system-level solutions from a smaller pool of strategic Tier 1 suppliers. This change favors vendors with deep expertise in both hardware and software integration and is most prominent among European OEMs standardizing their ADAS platforms.
Global Night Vision System and Driver Monitoring System Market Segmentation
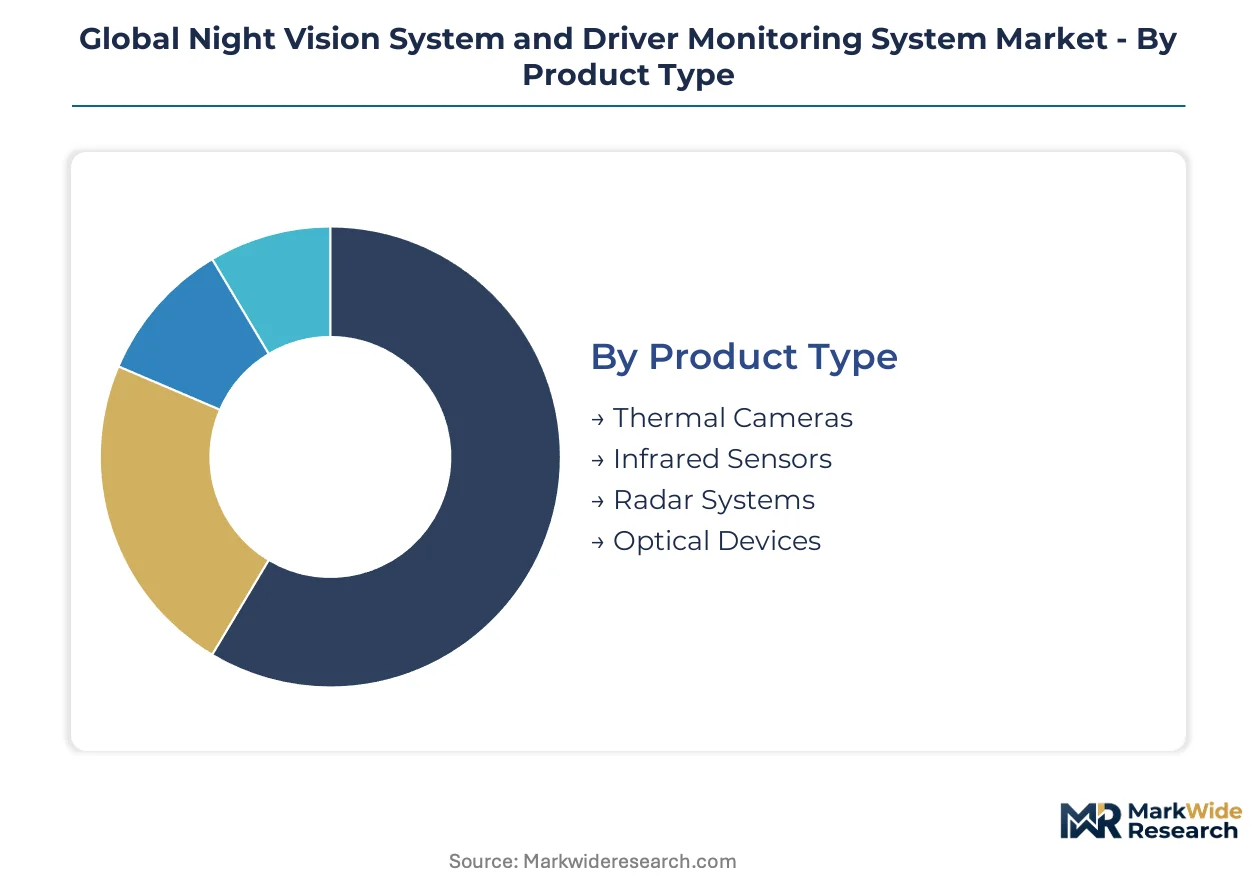
The global night vision system and driver monitoring system market categorizes solutions based on their core components, operational principles, target users, and vehicle applications. This breakdown elucidates where technological innovation and regulatory compliance converge.
Product Type:
Supply chain concentration for night vision and driver monitoring systems primarily revolves around specialized component manufacturing for sensor technologies. These elements dictate system performance.
- Thermal Cameras:These devices detect heat signatures from objects and living beings, operating within the 8-14 micrometer wavelength for clear low-light images. Demand heavily concentrates in premium passenger cars for enhanced pedestrian detection.
- Infrared Sensors:Utilizing infrared light to illuminate the road, these sensors capture reflections for detailed images, effective for obstacle detection. OEMs integrate these into ADAS packages to meet European safety requirements.
- Radar Systems:Radar systems emit radio waves to measure object distance, speed, and angle. Automakers use these for adaptive cruise control functions.
- Optical Devices:Optical devices include visible-light cameras and image processing units capturing visual data. Automakers widely deploy these for lane keeping assistance.
Thermal Cameras absorb the bulk of installed capacity for enhanced night vision; Infrared Sensors are expanding most quickly in response to ADAS mandates.
Technology:
The technological landscape differentiates systems by their operational mechanisms and primary safety functions, impacting integration into vehicle architectures.
- Active Night Vision:These systems employ near-infrared illuminators to actively light up the road, capturing reflections with a camera for a high-resolution image. Premium passenger cars in Germany feature this capability.
- Driver Monitoring:Internal cameras track driver eye movement, head position, and alertness, issuing warnings for fatigue or distraction. Global commercial vehicle fleets rapidly integrate these for enhanced safety regulations.
- Passive Night Vision:Relying on ambient thermal radiation, passive systems detect heat emitted by objects, displaying a thermal image without external illumination. This offers a cost-effective solution for basic night-time visibility.
- Lane Departure Warning:Utilizing forward-facing cameras, this technology monitors road markings and alerts drivers if the vehicle drifts. Many new vehicles in China include this feature.
Demand for Driver Monitoring remains foundational, while Active Night Vision demonstrates significant upward momentum in luxury vehicle segments.
End User:
The market segments by the direct customer for these systems, reflecting distinct procurement channels and product customization. Each category has unique demand drivers.
- OEMs:Original Equipment Manufacturers integrate night vision and driver monitoring systems directly into new vehicle production lines as factory-fitted components. This segment represents the largest volume due to regulatory mandates.
- Commercial Vehicles:This segment encompasses heavy-duty trucks, buses, and logistics fleets adopting these systems to enhance driver safety, reduce accident rates, and improve operational efficiency. Demand is driven by fleet safety.
- Aftermarket:This segment includes independent installers and consumers integrating systems into existing vehicles. Retrofit solutions cater to older vehicles seeking modern safety.
- Fleet Management:Fleet management companies procure systems to monitor driver behavior and vehicle performance across their operational fleet. Telematics integration is a key requirement.
The landscape is dominated by OEMs, with Commercial Vehicles showing notable expansion driven by fleet safety initiatives.
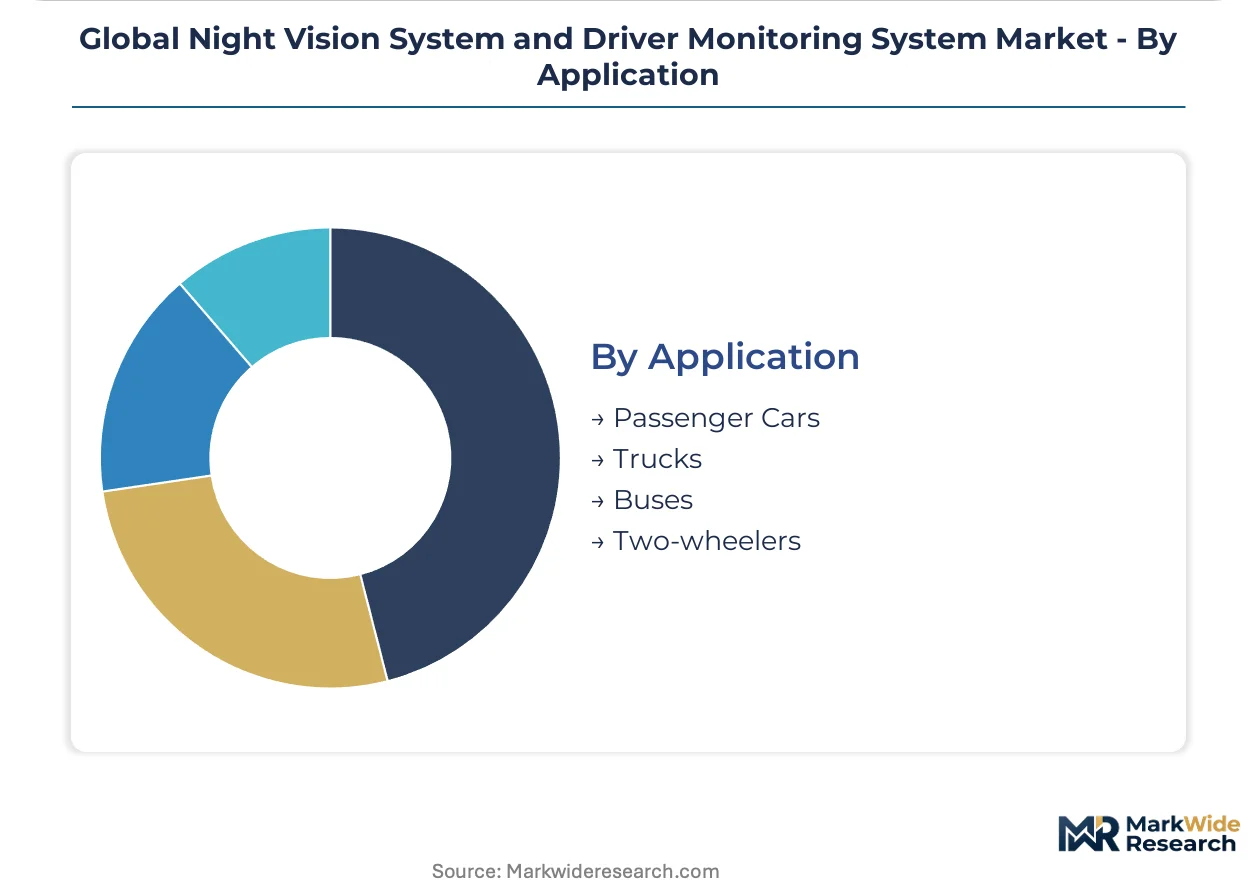
Application:
Segmentation by application highlights how night vision and driver monitoring systems are tailored for specific vehicle types. Each category presents unique operational challenges.
- Passenger Cars:This category includes sedans, SUVs, and luxury vehicles, where night vision and driver monitoring systems enhance occupant safety and driving comfort. Premium models in Germany often feature thermal imaging.
- Trucks:Heavy-duty and medium-duty trucks utilize these systems to improve visibility during night driving and monitor driver fatigue over extended shifts. China's GB standards compel integration.
- Buses:Public and private buses employ these technologies to ensure driver alertness and enhance passenger safety during urban and intercity routes. European public transport operators are adopting solutions.
- Two-wheelers:This emerging application explores compact night vision and driver monitoring solutions for motorcycles and scooters. Focus is on rider perception and fatigue detection, with research in Japan.
Passenger Cars account for the largest share in terms of installed units, and Trucks are experiencing accelerated integration due to safety compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global night vision and driver monitoring system market exhibits a clear divide between manufacturing hubs and regions with strong regulatory demand. China anchors significant production capacity and domestic consumption due to its dominant automotive sector. European markets also drive innovation through stringent safety mandates for new vehicles.
China
Demand for night vision and driver monitoring systems in China is driven by its dominant automotive manufacturing sector. China's GB standards for vehicle safety compel automakers to integrate these advanced features into new vehicles. Shanghai and other major automotive clusters are rapidly designing in compliant systems for both domestic and export models.
Germany
German automakers prioritize active night vision systems for premium passenger cars, enhancing driver perception and safety. The EU's General Safety Regulation mandates advanced driver assistance systems, accelerating integration across vehicle types. Stuttgart and Munich automotive R&D centers lead development for integrated ADAS platforms.
United States
US demand for driver monitoring and night vision systems stems from a focus on reducing road fatalities and improving vehicle safety. Guidelines from the US National Highway Traffic Safety Administration (NHTSA) encourage widespread ADAS adoption. Detroit's automotive industry is adapting vehicle architectures to standardize these safety technologies.
India
India's automotive market presents long-term growth potential for ADAS features as safety standards strengthen across the country. The Bureau of Indian Standards (BIS) is progressively updating vehicle safety norms, influencing local manufacturing. Chennai and Pune are emerging as key hubs for integrating advanced safety systems into new vehicle designs.
Japan
Japanese automotive manufacturers focus on integrating advanced driver assistance systems, including night vision, for enhanced safety and comfort. The Ministry of Economy, Trade and Industry (METI) supports research into new mobility technologies. Tokyo and Nagoya are centers for developing compact night vision solutions, including for two-wheelers.
Global Night Vision System and Driver Monitoring System Market Key Industry Players
The competitive structure tilts toward integrated system providers leveraging extensive electronics portfolios. The market features a blend of large, diversified Tier 1 suppliers and specialized sensor technology developers focusing on specific components. Strategic archetypes include comprehensive ADAS solution providers, offering end-to-end integration, and niche component specialists, focusing on advanced thermal or infrared sensing. Companies are actively pursuing portfolio diversification and strategic partnerships to offer complete system-level solutions, adapting to OEM sourcing shifts.
Among established automotive suppliers, Robert Bosch GmbH, a German engineering and electronics company, exemplifies a diversified giant offering integrated solutions for ADAS, from hardware to software. Continental AG, another German-based automotive technology company, anchors the sensor fusion segment with its extensive R&D capabilities and component expertise. Japanese-based Denso Corporation also occupies a position as a major Tier 1 supplier, focusing on advanced safety systems and thermal management for global automakers. These entities represent the trend towards providing pre-integrated, validated system offerings that meet stringent regulatory requirements.
| Leading Market Players |
|---|
| Aisin Seiki Co., Ltd. |
| Valeo |
| Omron Corporation |
| Magna International Inc. |
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Autoliv Inc. |
| Visteon Corporation |
| Others |
Cost & Logistics Intelligence
Captive supply of specialized components anchors both the supply position and pricing power for integrated ADAS solution providers. This vertical integration strategy influences market entry barriers for new participants.
Pricing Analysis
Cost-down pressure on thermal cameras accelerates because manufacturing scales and component costs fall, particularly impacting mid-range passenger car segments. The dominant pricing structure remains per-unit transactional, though long-term contracts with OEMs are common. Price differentiation stems from sensor performance capabilities and certification levels for safety regulations. Commercial vehicle fleets exhibit high price sensitivity, prioritizing cost-effectiveness, while premium passenger car OEMs are less sensitive, valuing advanced features.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of infrared sensors and thermal cameras, primarily concentrated in Germany, Japan, and China. The supply chain relies heavily on optical components and semiconductor chips as key inputs. Logistics chokepoints, particularly for advanced chipsets, pose a structural risk to production schedules. Distribution runs through a direct-to-OEM model for factory-fitted systems, with a smaller channel for aftermarket retrofit solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The night vision and driver monitoring market is in a technology-transition phase, with integrated ADAS platforms displacing discrete safety components. This shift demands strategic realignment across the value chain.
For Market Incumbents: Cement core market share by deepening vertical integration into advanced sensor manufacturing, particularly for 8-14 micrometer thermal cameras. This counters margin pressure from increasing OEM procurement consolidation. Invest in R&D for AI-driven sensor fusion algorithms to maintain technological leadership against emerging software-centric entrants. Expand global manufacturing capacity in China to meet local GB standards and export requirements.
For New Entrants and Emerging Players: A price-point gap exists between premium factory-fitted systems and basic aftermarket solutions, creating an entry opportunity for cost-effective driver monitoring units. Target the commercial vehicle segment in India and Brazil, which are strengthening safety standards. Focus on robust, easy-to-install aftermarket fleet solutions with subscription-based telematics integration as a key go-to-market angle. Develop specialized systems for two-wheelers, an underpenetrated application with unique safety needs.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated ADAS solution providers with strong software capabilities and established OEM relationships. The market demonstrates long-term viability over the next decade, driven by mandatory safety regulations and autonomous driving advancements. Acquisition targets should be niche component specialists in sensor technology with proprietary intellectual property or strong regional market penetration. Watch for widespread adoption of Level 3 autonomous driving features as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Sensor Fusion R&D | Enhances situational awareness for higher levels of autonomous driving and meets advanced safety mandates. |
| Expand Commercial Vehicle Offerings | Addresses growing demand for driver fatigue monitoring in logistics fleets and improves operational safety. |
| Secure Long-Term OEM Contracts | Provides revenue stability and reinforces market position against new entrants in the passenger car segment. |
| Invest in Active Night Vision Production | Scales technology adoption in mid-range passenger cars as component costs decrease and demand rises. |
| Develop Data Privacy Compliant Solutions | Builds consumer trust and ensures adherence to stringent global regulations for biometric data collection. |
Research Approach
Document review covered automotive industry reports, regulatory filings from NHTSA and the EU, and academic research, complemented by interviews with Tier 1 supplier executives, OEM platform engineers, and fleet managers. This primary research gathered insights on technology roadmaps and procurement strategies. Secondary validation utilized vehicle production databases and trade association publications. A bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Market volume and value outputs were generated through a robust analytical framework, modeling demand across the analysis window. Segmentation dimensions included product type, technology, end user, application, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected adoption rates. Key forecast inputs included evolving safety mandates and vehicle production forecasts for major automotive hubs.
Underlying measurement precision varies by segment; passenger cars and commercial vehicles carry tighter precision than two-wheelers. Forecasts reflect assumptions regarding regulatory timelines and technological advancements. Geopolitical events and raw material supply disruptions could revise these projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Coastal Surveillance Systems Market