
 Middle East and Africa Video Surveillance Market | 2026-2036
Middle East and Africa Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Video Surveillance Market Insights
High-definition and AI-enabled analytics tiers is bifurcating the Middle East and Africa Video Surveillance Market into premium specification segments and cost-optimized alternatives. Hangzhou Hikvision Digital Technology Co. Ltd anchors its regional position through deep manufacturing scale and localized distribution partnerships across Gulf states. Axis Communications AB differentiates through edge-computing camera architectures that reduce bandwidth costs for remote oil-field deployments. Dahua Technology Co. Ltd competes aggressively on total cost of ownership, leveraging captive component supply to undercut rivals in price-sensitive African markets.
Video surveillance in this context denotes networked camera systems capturing, transmitting, and storing visual data for real-time monitoring and forensic analysis, typically operating at resolutions from two to eight megapixels with frame rates between fifteen and thirty frames per second. These systems serve primary commercial purposes including loss prevention, access control verification, and operational safety compliance across critical infrastructure and public spaces. IP technology now leads installed base expansion as analog infrastructure ages out of Gulf state government tenders, while cloud-based architectures represent the fastest-growing deployment model by eliminating on-premise server capital expenditure. Thermal cameras command disproportionate margin pools in the product mix due to their specialized sensor requirements and limited supplier base serving desert climate and perimeter intrusion applications.
Saudi Arabia's National Cybersecurity Authority and South Africa's POPIA framework jointly shape vendor compliance burdens, mandating data localization, encryption standards, and audit trails that favor established suppliers with dedicated regional legal resources. The UAE's Emirates Authority for Standardization and Metrology enforces product certification requirements that filter out uncertified equipment from federal procurement channels. Stakeholders must monitor accelerating regulatory fragmentation across Gulf and sub-Saharan jurisdictions to determine whether centralized regional product platforms or country-specific compliance variants offer superior capital efficiency.
Market Dynamics
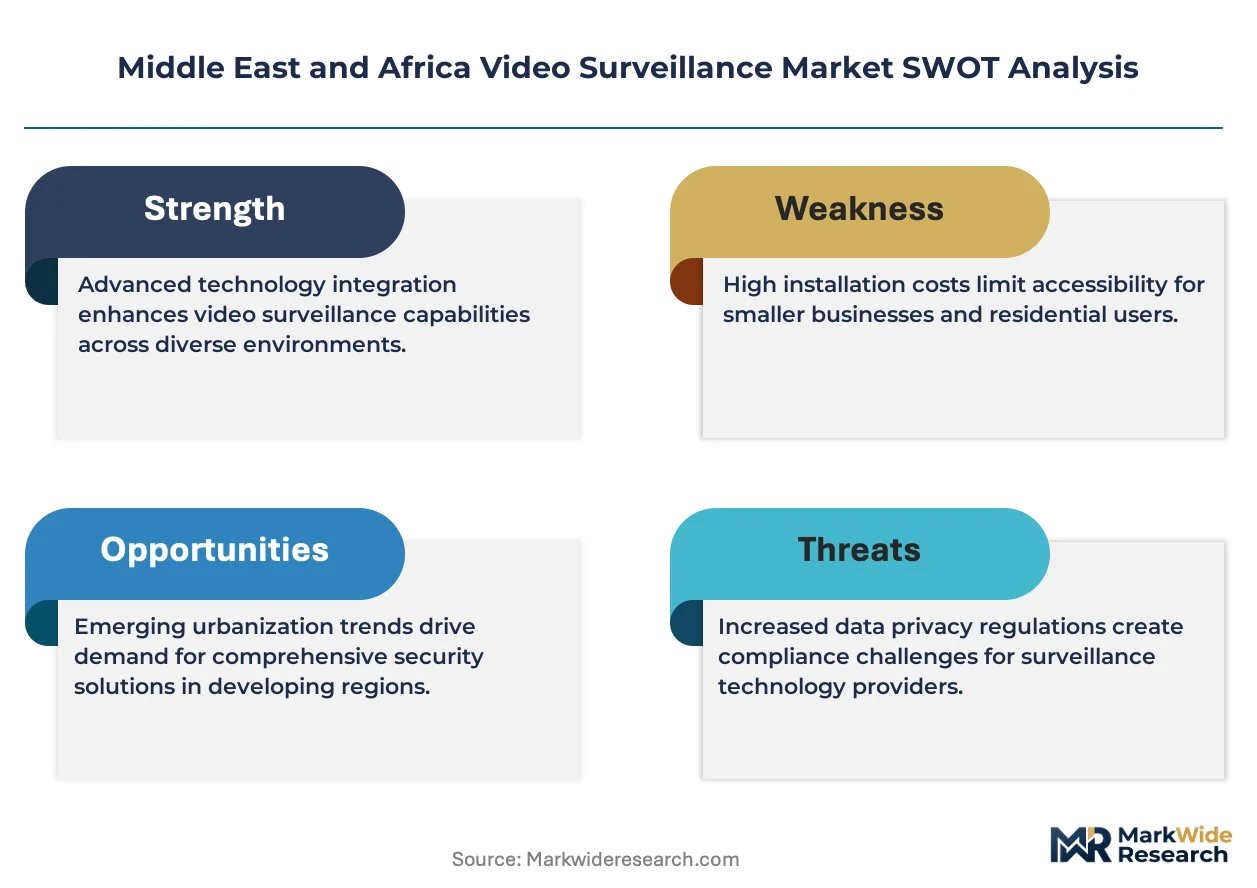
The Middle East and Africa Video Surveillance Market is bifurcating around AI-enabled edge analytics, with Gulf state infrastructure budgets pulling premium IP architectures while African public-sector tenders compress toward cost-optimized alternatives. This tension between performance tiers and price floors is restructuring vendor go-to-market strategies across the region.
Growth Catalysts
- Saudi smart city mandates:Riyadh's giga-project pipeline is specifying facial recognition-capable camera networks for urban management, creating dedicated procurement channels for AI-integrated hardware.
- POPIA encryption requirements:South Africa's data protection framework is mandating hardware-level encryption and access logging, filtering tenders toward compliant suppliers with regional legal infrastructure.
- Thermal perimeter deployments:Desert climate conditions and critical energy infrastructure protection needs are concentrating demand for heat-sensing cameras in UAE and Kuwait oil-field installations.
Market Restraints
- Sensor supply concentration:Thermal imaging sensor fabrication concentrates among a limited supplier base, creating margin pressure and lead-time volatility for perimeter-security specialists.
- Sub-Saharan power inconsistency:Unreliable grid infrastructure in rural African markets limits continuous-recording system viability, constraining addressable market for always-on IP architectures.
- Import duty stacking:Multiple customs regimes across Gulf Cooperation Council and East African Community jurisdictions fragment landed cost predictability for multi-country distributors.
Strategic Opportunities
- Nigeria's banking sector modernization:Tier-1 financial institutions in Lagos and Abuja are specifying centralized video management platforms, opening premium-tier penetration in a historically price-driven market.
- Cloud-managed service models:Subscription-based architectures are eliminating upfront server capital requirements, expanding access for mid-sized retail and hospitality operators across Morocco and Egypt.
- UAE federal certification pathways:Emirates Authority for Standardization and Metrology compliance is creating a quality filter that rewards established vendors with dedicated regional certification resources.
Industry Challenges
- Multi-jurisdiction data localization:Divergent sovereignty requirements across Saudi Arabia, South Africa, and UAE are forcing product platform fragmentation or expensive country-specific compliance variants.
- Legacy analog integration complexity:Hybrid deployment scenarios requiring coaxial-to-IP bridge equipment are extending installation timelines and inflating project management costs for government tenders.
- Cybersecurity skill scarcity:Hardened network configuration and firmware update management capabilities remain concentrated among specialized systems integrators, constraining scalable deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Video Surveillance Market |
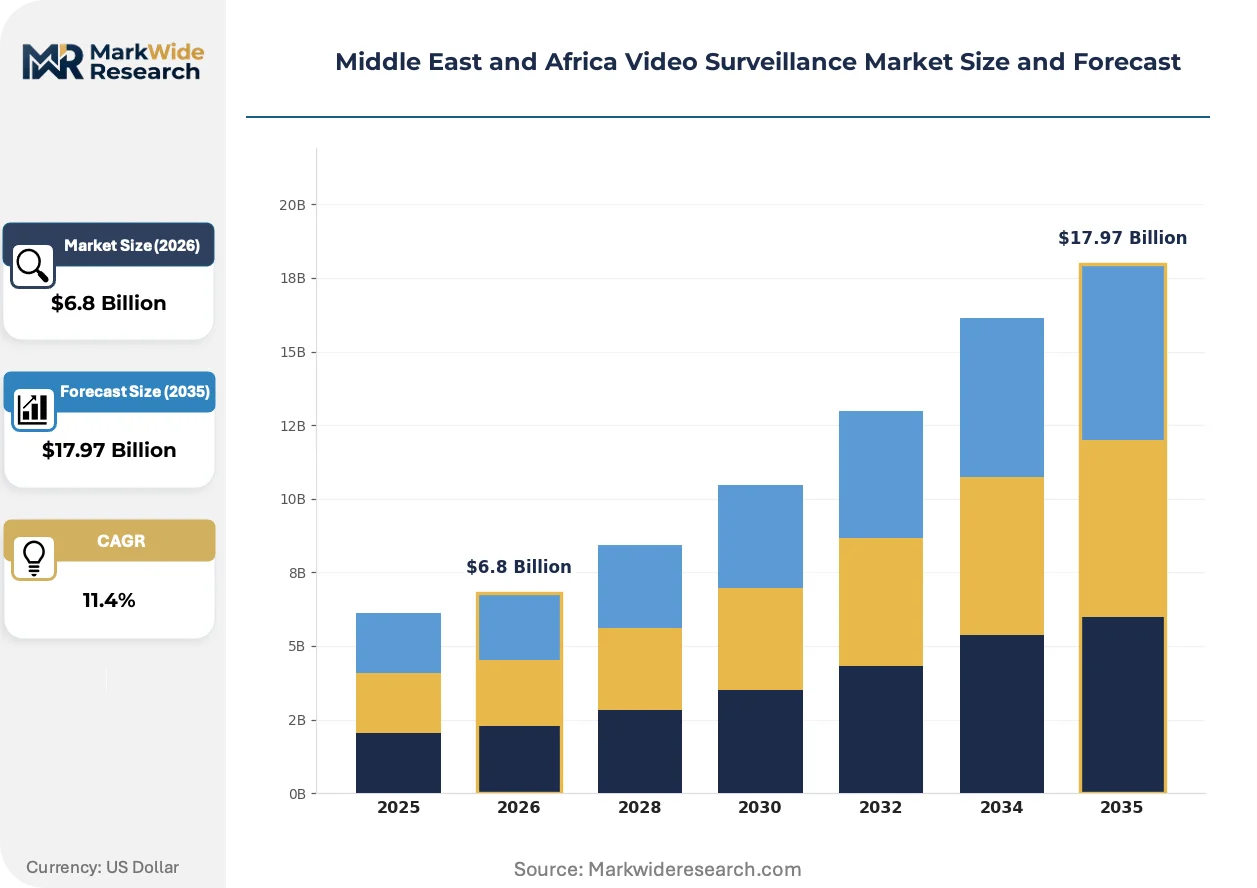
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Thermal Cameras Technology: Analog, IP, Wireless, Cloud-Based Application: Traffic Monitoring, Retail Surveillance, Industrial Security, Building Management End User: Government, Transportation, Healthcare, Education |
| Companies Covered | Axis Communications AB, Bosch Security Systems, Honeywell International Inc., Hangzhou Hikvision Digital Technology Co. Ltd, Panasonic Corporation, Hanwha Vision, Dahua Technology Co. Ltd, Motorola Solutions Inc., Zhejiang Uniview Technologies Co. Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Video Surveillance Market Trends and Innovations
Edge-computing camera architectures are compressing bandwidth requirements and enabling real-time analytics without centralized server dependency. This shift is restructuring hardware specifications and procurement evaluation criteria across the region's video surveillance value chain.
Deep-learning inference chips embedded directly at the camera node are supplanting centralized video analytics servers in bandwidth-constrained deployments. Remote oil-field operators in Kuwait and onshore extraction sites in Saudi Arabia are specifying these architectures to reduce satellite or microwave backhaul costs. The technology is compressing total infrastructure expenditure for perimeter intrusion detection while raising hardware unit value capture at the edge.
South Africa's POPIA framework and Saudi Arabia's National Cybersecurity Authority guidelines are jointly mandating audit trails, encryption standards, and data localization for visual surveillance systems. These compliance burdens are filtering federal and enterprise procurement toward vendors with dedicated regional legal and certification infrastructure. Cloud-managed service providers are responding by establishing in-country data residency architectures to maintain eligibility for government tenders.
Subscription-based video surveillance-as-a-service is displacing capital-intensive on-premise server purchases among mid-market retail and hospitality operators. Moroccan and Egyptian buyers are prioritizing operational expenditure models that bundle hardware, connectivity, and remote monitoring into monthly fees. This preference shift is compressing traditional distributor margins while opening recurring revenue streams for platform operators with financing capabilities.
Middle East and Africa Video Surveillance Market Segmentation
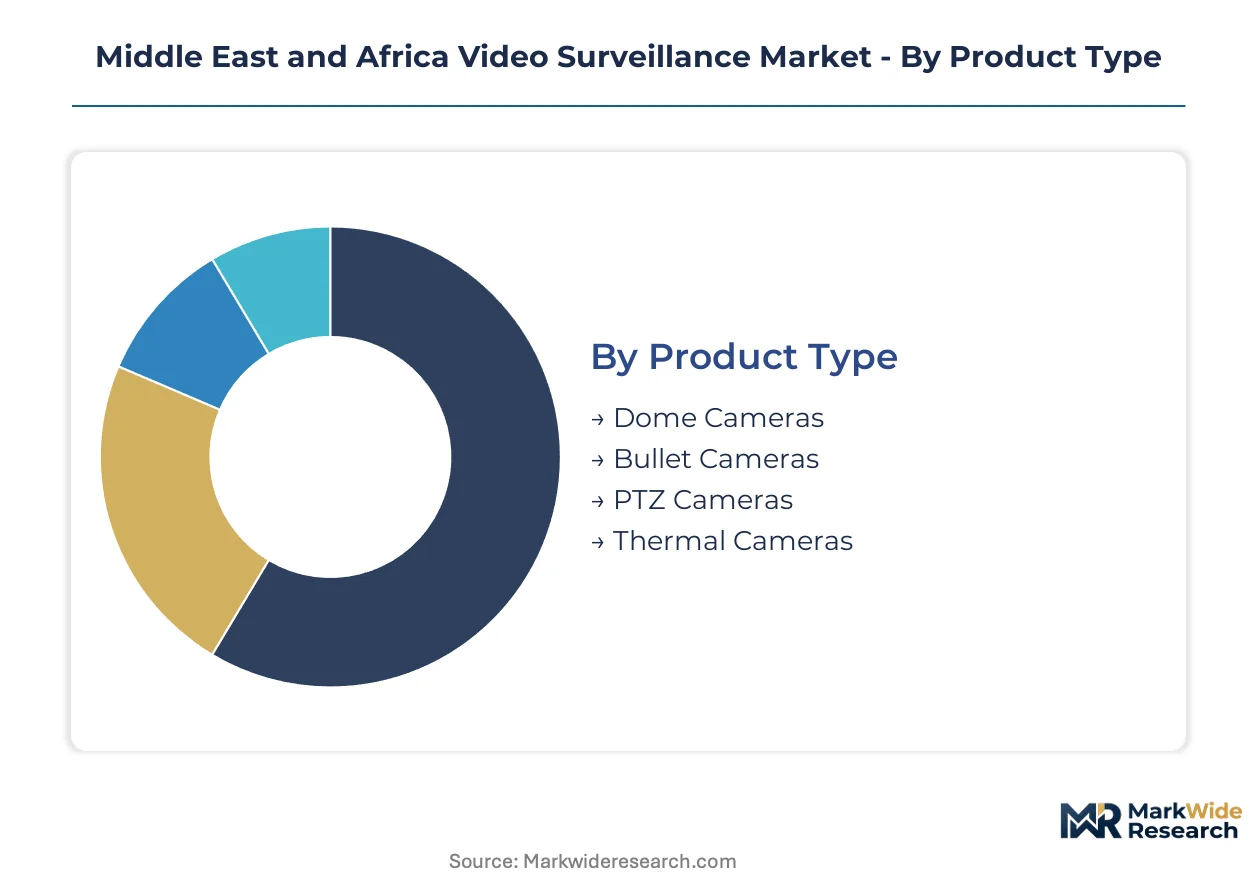
Video surveillance procurement patterns across the Middle East and Africa diverge sharply between Gulf state premium infrastructure budgets and African cost-optimized tenders. Segment boundaries reflect this bifurcation, with technology and product choices tracking available capital expenditure and regulatory compliance capacity.
Product Type:
Dome cameras concentrate in UAE and Saudi interior deployments where aesthetic integration matters. Bullet cameras dominate African perimeter installations where weather resistance outweighs form factor. PTZ and thermal variants track oil-funded security budgets.
- Dome Cameras:Hemispherical housings enclose varifocal lenses for discreet indoor positioning. Demand clusters in Dubai and Riyadh retail complexes where architectural blending overrides pure functionality. UAE federal certification requirements filter uncertified suppliers from this premium tier.
- Bullet Cameras:Cylindrical weather-sealed enclosures mount externally on walls and poles. Nigerian banking sector modernization in Lagos and Abuja is specifying these for branch perimeter coverage, opening premium penetration in a historically price-driven market.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-controlled area coverage. Saudi giga-project security specifications.
- Thermal Cameras:Uncooled microbolometer sensors detect heat signatures through darkness and dust. Kuwait and Saudi oil-field perimeter protection.
Dome cameras command the established base. The steepest expansion runs through thermal cameras.
Technology:
Technology choices split across infrastructure maturity and backhaul economics. IP architectures displace analog in Gulf government tenders while wireless and cloud models address African connectivity constraints.
- Analog:Coaxial-cable transmission of composite video signals persists in legacy system extensions. Sub-Saharan power inconsistency limits continuous-recording viability for always-on architectures in rural African markets.
- IP:Ethernet-delivered digital video streams at resolutions up to eight megapixels. Riyadh smart city mandates specify facial recognition-capable networks, creating dedicated procurement channels for AI-integrated hardware.
- Wireless:Microwave or cellular backhaul eliminates trenching requirements for remote sites. Moroccan and Egyptian mid-market retail adoption.
- Cloud-Based:Subscription architectures eliminate on-premise server capital expenditure. Nigerian and Kenyan hospitality operators.
Analog systems retain the installed base. Cloud-based deployments are climbing the fastest as operational expenditure models displace capital purchases.
Application:
Application segmentation tracks end-user risk profiles and regulatory oversight intensity. Traffic monitoring carries federal mandate weight; retail surveillance responds to loss prevention economics.
- Traffic Monitoring:License plate recognition and incident detection on arterial road networks. Dubai and Riyadh smart city infrastructure projects.
- Retail Surveillance:Point-of-sale oversight and shopper flow analytics. South African POPIA encryption requirements mandate hardware-level protection for consumer-facing deployments.
- Industrial Security:Perimeter intrusion detection for critical infrastructure. UAE and Kuwait energy installations.
- Building Management:Integrated access control and occupancy monitoring. Egyptian and Moroccan commercial real estate.
Industrial security holds the revenue concentration. Traffic monitoring is gaining share fastest through Gulf state urban modernization budgets.
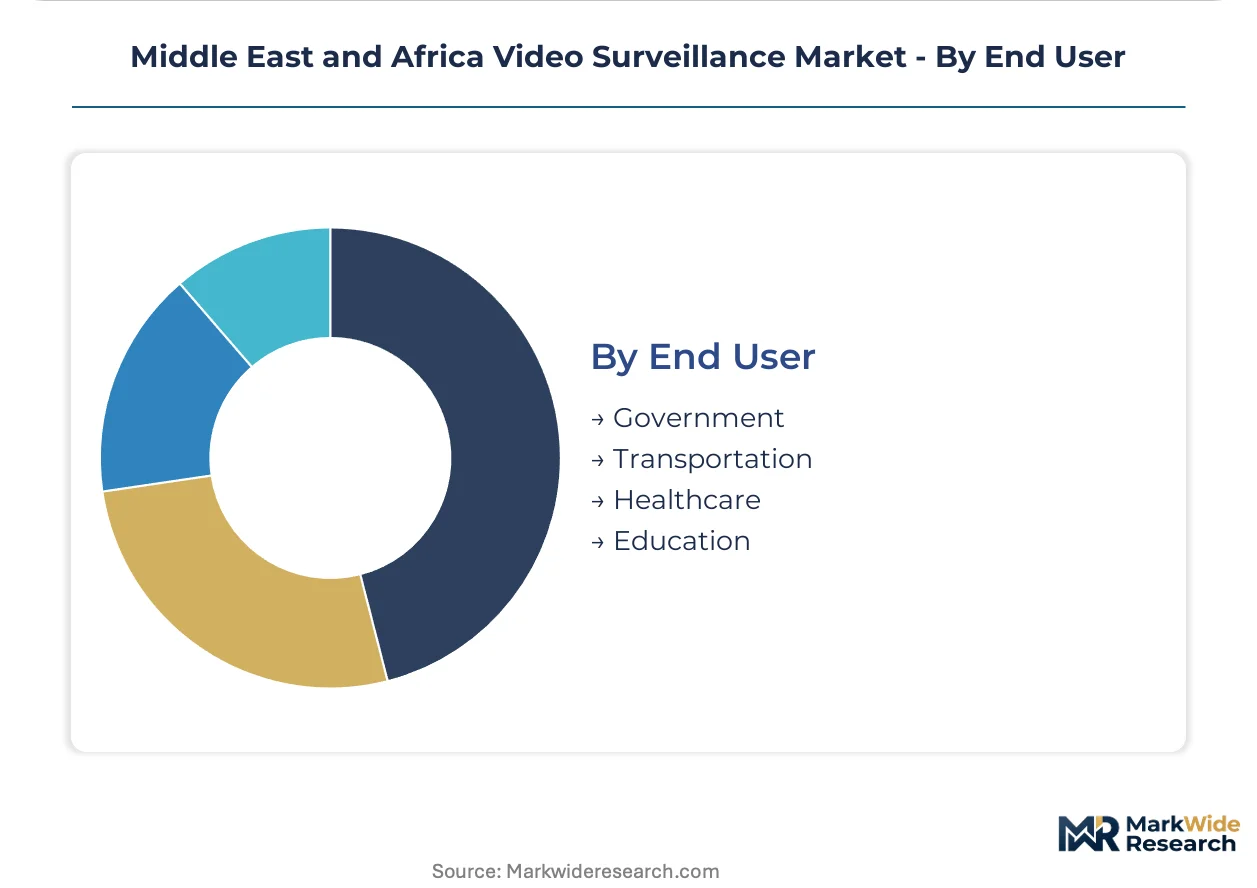
End User:
End-user segmentation reflects procurement authority structures and compliance burden capacity. Government tenders carry certification requirements that filter supplier pools; healthcare and education operate under tighter budget constraints.
- Government:Federal and municipal security infrastructure with mandatory data localization. Saudi National Cybersecurity Authority and South Africa POPIA frameworks jointly shape vendor compliance burdens.
- Transportation:Airport, seaport, and rail network surveillance with customs integration requirements. UAE federal certification pathways.
- Healthcare:Patient safety and pharmaceutical storage monitoring. Saudi and South African data protection mandates.
- Education:Campus safety and access control for schools and universities. Egyptian and Moroccan public sector tenders.
Government procurement commands the established base. Healthcare is expanding most quickly through regulatory compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates among Chinese and Korean component suppliers serving Gulf state procurement channels. Distribution partnerships anchor regional presence for equipment vendors. Local compliance infrastructure determines tender eligibility across divergent regulatory regimes.
United Arab Emirates
Dubai's smart city infrastructure pipeline specifies facial recognition-capable IP camera networks for urban management. Emirates Authority for Standardization and Metrology certification requirements filter uncertified equipment from federal procurement channels. Abu Dhabi's energy sector concentrates thermal camera deployments for critical infrastructure perimeter protection.
Saudi Arabia
Riyadh's giga-project security mandates are creating dedicated procurement channels for AI-integrated hardware with edge-computing architectures. The National Cybersecurity Authority guidelines mandate data localization and encryption standards for visual surveillance systems. Eastern Province oil-field operators specify heat-sensing cameras for desert climate perimeter intrusion detection.
South Africa
POPIA data protection framework mandates hardware-level encryption and access logging for consumer-facing retail deployments. Johannesburg's banking sector modernization is specifying centralized video management platforms for branch security. Cape Town's commercial real estate cluster is adopting cloud-based architectures to eliminate on-premise server capital expenditure.
Nigeria
Lagos and Abuja tier-1 financial institutions are driving premium-tier penetration in a historically price-driven market. The country's national data protection regulator is developing compliance frameworks for financial sector surveillance systems. Port Harcourt's energy infrastructure corridor is deploying bullet cameras for perimeter coverage.
Egypt
Cairo's hospitality and retail operators are prioritizing subscription-based video surveillance-as-a-service models. Government tenders for public sector education and healthcare facilities operate under tighter budget constraints than Gulf state counterparts. Alexandria's commercial port is integrating customs requirements into transportation surveillance specifications.
Middle East and Africa Video Surveillance Market Competitive Landscape
Concentration sits with diversified electronics conglomerates and specialized security equipment manufacturers. The vendor base spans three tiers: premium IP architecture specialists, cost-optimized volume suppliers, and cloud-managed service platform operators. Competitive moves center on regional certification infrastructure investment and localized distribution partnership formation.
Among Chinese equipment manufacturers, Hangzhou Hikvision Digital Technology Co. Ltd and Dahua Technology Co. Ltd represent scale-driven archetypes with captive component supply chains. Axis Communications AB exemplifies the premium-tier specialist position through edge-computing camera architectures. These three anchors illustrate the bifurcation between manufacturing-scale competition and technology-differentiated positioning across Gulf and African markets.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Security Systems |
| Honeywell International Inc. |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Panasonic Corporation |
| Hanwha Vision |
| Dahua Technology Co. Ltd |
| Motorola Solutions Inc. |
| Zhejiang Uniview Technologies Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for thermal imaging sensors from uncooled microbolometer suppliers concentrate pricing power among a handful of fabrication houses, compressing margins for perimeter-security specialists while amplifying cost pass-through to Gulf state energy operators.
Pricing Analysis
POPIA and the National Cybersecurity Authority dictate the pricing tier structure across the Middle East and Africa Video Surveillance Market. Three-tier pricing stratifies across AI-integrated edge architectures, standard IP networks, and cost-optimized analog alternatives. Certification grade and after-sales service bundling separate premium Gulf state tenders from price-sensitive African public-sector awards. Cost compression in the standard tier intensifies as Dahua and Hikvision leverage captive component supply. Sub-Saharan government buyers exhibit highest price sensitivity; Saudi giga-project operators show lowest.
Supply Chain Analysis
China and South Korea anchor CMOS sensor and deep-learning inference chip fabrication for regional camera manufacturers. Uncooled microbolometer arrays for thermal variants draw from limited U.S. and European specialist foundries. Supply chain risk centers on single-source vulnerability for desert-rated housing materials and precision motor assemblies. Distribution runs through Dubai-based logistics hubs serving Gulf Cooperation Council states, with Lagos and Johannesburg anchoring sub-Saharan fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-computing camera architectures and cloud-managed service models are disrupting traditional capital-intensive procurement across the Middle East and Africa Video Surveillance Market, with POPIA and Saudi cybersecurity mandates accelerating compliance-driven vendor consolidation.
For Market Incumbents: Consolidate certification infrastructure across Emirates Authority for Standardization and Metrology, Saudi National Cybersecurity Authority, and South Africa POPIA pathways to filter tender eligibility. Deepen backward integration into thermal sensor supply or secure long-term offtake agreements with microbolometer fabricators to defend margin position against lead-time volatility.
For New Entrants and Emerging Players: UAE federal certification fast-tracks offer the most penetrable entry vector for cloud-native platform operators lacking legacy analog installed base. Target Egyptian and Moroccan mid-market hospitality operators prioritizing subscription-based operational expenditure models. Partner with regional systems integrators possessing hardened network configuration capabilities to overcome cybersecurity skill scarcity.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because divergent data localization mandates across Saudi Arabia, South Africa, and UAE favor vendors with dedicated regional legal infrastructure over centralized product platforms. Watch for POPIA enforcement intensity and Saudi giga-project procurement velocity as inflection signals determining whether compliance-scale or manufacturing-scale archetypes capture superior returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Certification Infrastructure Investment | Emirates Authority for Standardization and Metrology compliance filters uncertified suppliers from federal tenders. |
| Edge-Computing Architecture Development | Kuwaiti oil-field operators specify on-camera inference to reduce satellite backhaul expenditure. |
| Cloud-Managed Service Platform Launch | Moroccan and Egyptian retail operators prioritize subscription models eliminating server capital requirements. |
| Backward Integration into Thermal Sensor Supply | Limited microbolometer fabricator base creates margin pressure for perimeter-security specialists. |
| Localization Partnership with Systems Integrators | Cybersecurity skill scarcity concentrates deployment capability among specialized regional integrators. |
Research Methodology
A standing panel of security systems integrators, government procurement officers, and video management platform engineers provided ongoing calibration for demand assumptions across the analysis window. Primary interviews with thermal camera specialists, cloud service architects, and regulatory compliance consultants combined with secondary validation against Emirates Authority for Standardization and Metrology certification databases, Saudi National Cybersecurity Authority guideline releases, and South Africa Information Regulator enforcement notices. Bottom-up shipment estimates triangulated against top-down infrastructure budget allocations from Riyadh giga-projects and Dubai smart city tenders.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for cloud infrastructure, customs records for camera equipment imports, and project development databases for Gulf state critical infrastructure awards. Segmentation modeling spanned product type, technology architecture, application vertical, and end-user procurement authority. CAGRs derived from regression analysis of historical deployment trajectories and elasticity-adjusted demand curves across bandwidth-constrained and premium infrastructure markets. Forecast inputs incorporated POPIA compliance cost estimates and thermal sensor supply lead-time volatility.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf state modernization budgets and stable sub-Saharan power grid expansion; material deviation in either would warrant model refresh. Specific risks include accelerated regulatory fragmentation requiring country-specific product variants, and thermal sensor supply disruption extending procurement timelines. Recalibration cycles align with material shifts in Saudi giga-project award schedules and South Africa POPIA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Security Camera Software Market