
 Japan Surveillance Analog Camera Market | 2026-2036
Japan Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Surveillance Analog Camera Market Insights
Japanese domestic manufacturers is pivoting toward hybrid coaxial-IP architectures to preserve installed-base revenue. Panasonic Holdings leverages its vertical manufacturing footprint to sustain cost discipline across bullet and dome variants. Sony anchors premium positioning through broadcast-derived image sensor expertise. Hanwha Vision competes on price-adjusted feature density for municipal transit contracts.
A surveillance analog camera converts continuous optical scenes into electrical signals transmitted via coaxial cable, typically employing CCD or CMOS sensors with composite video output at 540-700 TV lines resolution for real-time security monitoring. Dome cameras dominate indoor retail deployments where vandal resistance and discreet positioning matter, while bullet cameras lead outdoor perimeter applications across government facilities. PTZ cameras command premium positioning in transportation hubs requiring operator-directed coverage, though infrared technology integration is displacing conventional low-light configurations in warehouse and residential settings.
METI establishes equipment efficiency benchmarks that filter procurement eligibility for public surveillance tenders, while JIS standards govern environmental sealing and electromagnetic compatibility for outdoor installations. Japan's national police agency protocols mandate encrypted transmission pathways that hybrid analog-digital architectures must satisfy. Stakeholders must weigh replacement-cycle timing against municipal budget consolidation pressures and the interoperability claims of competing infrastructure upgrade paths.
Market Dynamics
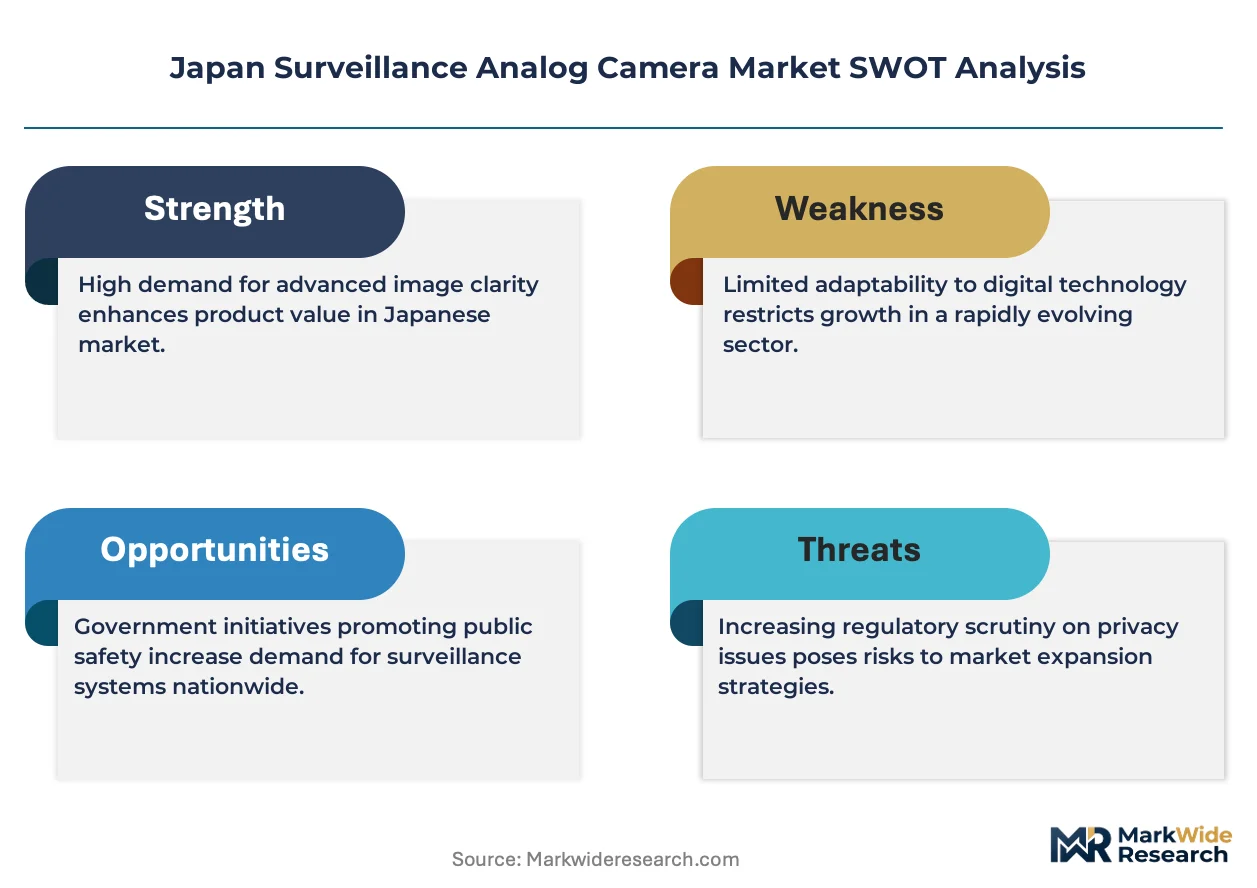
Hybrid coaxial-IP architectures dominate vendor roadmaps as Japanese infrastructure owners balance sunk-cost preservation against METI efficiency mandates, creating a bifurcated procurement environment where legacy compatibility and digital upgrade paths compete for capital allocation.
Growth Catalysts
- Transportation legacy mandates:Japan's national police agency protocols require encrypted transmission pathways that hybrid analog-digital systems uniquely satisfy, sustaining demand across Osaka-Kobe transit corridors.
- METI efficiency benchmarks:Equipment procurement eligibility for public tenders now filters through energy-performance standards, directing municipal budgets toward compliant analog-hybrid configurations.
- Industrial retrofit waves:Warehouse and manufacturing facilities in the Keihin industrial zone are replacing aging coaxial networks while retaining analog endpoints to minimize rewiring costs.
Market Restraints
- CMOS sensor supply concentration:Domestic production capacity for broadcast-grade image sensors remains captive to Sony's sensor fabs, creating single-source vulnerability for premium analog variants.
- IP substitution economics:Pure network camera TCO advantages in greenfield installations erode analog's addressable market, particularly in commercial real estate developments.
- JIS certification timelines:Environmental sealing and electromagnetic compatibility testing cycles extend product launch windows by 8-14 months, compressing revenue recognition for new dome and bullet releases.
Strategic Opportunities
- Kansai airport expansion:Kansai International and Itami airport security upgrades specify vandal-resistant dome configurations with analog backup pathways for redundancy compliance.
- Infrared convergence:Integration of thermal imaging sensors into conventional analog housings opens warehouse perimeter applications previously requiring separate night-vision systems.
- Municipal maintenance outsourcing:Prefecture-level governments are unbundling surveillance system O&M from capital procurement, creating recurring revenue streams for equipment-embedded service contracts.
Industry Challenges
- Coaxial technician scarcity:Broadcast and telecom industries compete for the same installer base, driving wage inflation for legacy cable termination and signal troubleshooting skills.
- Hybrid integration complexity:Municipal IT departments lack expertise bridging analog matrix switchers with IP video management platforms, extending deployment timelines and acceptance testing phases.
- Interoperability certification costs:Third-party validation of analog-digital gateway compatibility against police agency encryption standards requires six-figure testing investments per product line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Surveillance Analog Camera Market |
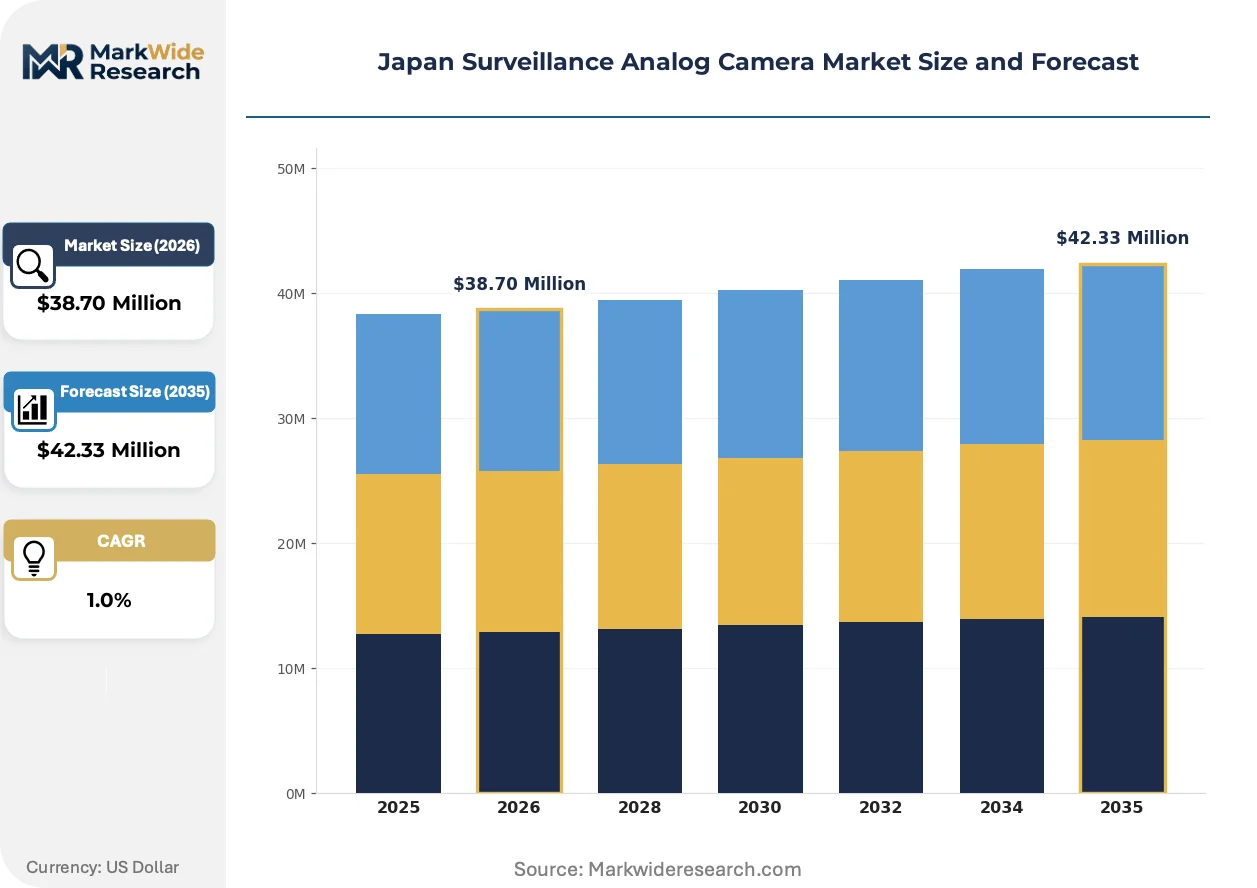
| Market Size in 2026 | $38.70 Million |
| Market Size in 2035 | $42.33 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, C-Mount Cameras Technology: Coaxial, IP Hybrid, Wireless, Infrared End User: Retail Stores, Government Agencies, Transportation Hubs, Residential Areas Installation: Indoor, Outdoor, Ceiling Mount, Wall Mount |
| Companies Covered | Tescom Japan, CP PLUS, Hangzhou Hikvision Digital Technology, Zhejiang Uniview Technologies, Sony, Dahua Technology, Panasonic Holdings, Shenzhen Sunell Technology, Hanwha Vision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Surveillance Analog Camera Market Trends and Innovations
Japanese surveillance infrastructure is undergoing a managed transition where analog endpoints persist as edge devices while backhaul and storage migrate to digital architectures, reshaping vendor R&D priorities and municipal procurement evaluation criteria.
Hybrid signal processors are consolidating discrete analog-to-digital conversion functions into single-chip architectures that preserve coaxial cable investments while enabling IP-based analytics. Railway operators in the Tokyo metropolitan area are deploying these processors in station platforms to maintain existing cable runs while adding passenger-counting algorithms. This consolidation is compressing the market for standalone encoder boxes and forcing component suppliers to integrate directly into camera module designs.
METI's 2024 revision to Top Runner equipment standards tightened standby power thresholds for continuously operating surveillance devices, disqualifying conventional analog power supplies from new public tenders. Manufacturers are responding with switched-mode designs that cut phantom load consumption by 40-60 percent. Bullet camera variants for perimeter applications face the steepest redesign costs due to heating element integration for cold-climate operation.
Municipal buyers are fragmenting procurement decisions between facilities management teams controlling capital budgets and IT security offices mandating network compliance, extending sales cycles and requiring dual-value-proposition selling. System integrators in the Chubu region report 30-40 percent longer evaluation periods as these stakeholders negotiate analog retention versus full-IP conversion. Prefecture-level police departments are mediating these disputes through technical specification templates that explicitly permit hybrid architectures.
Japan Surveillance Analog Camera Market Segmentation
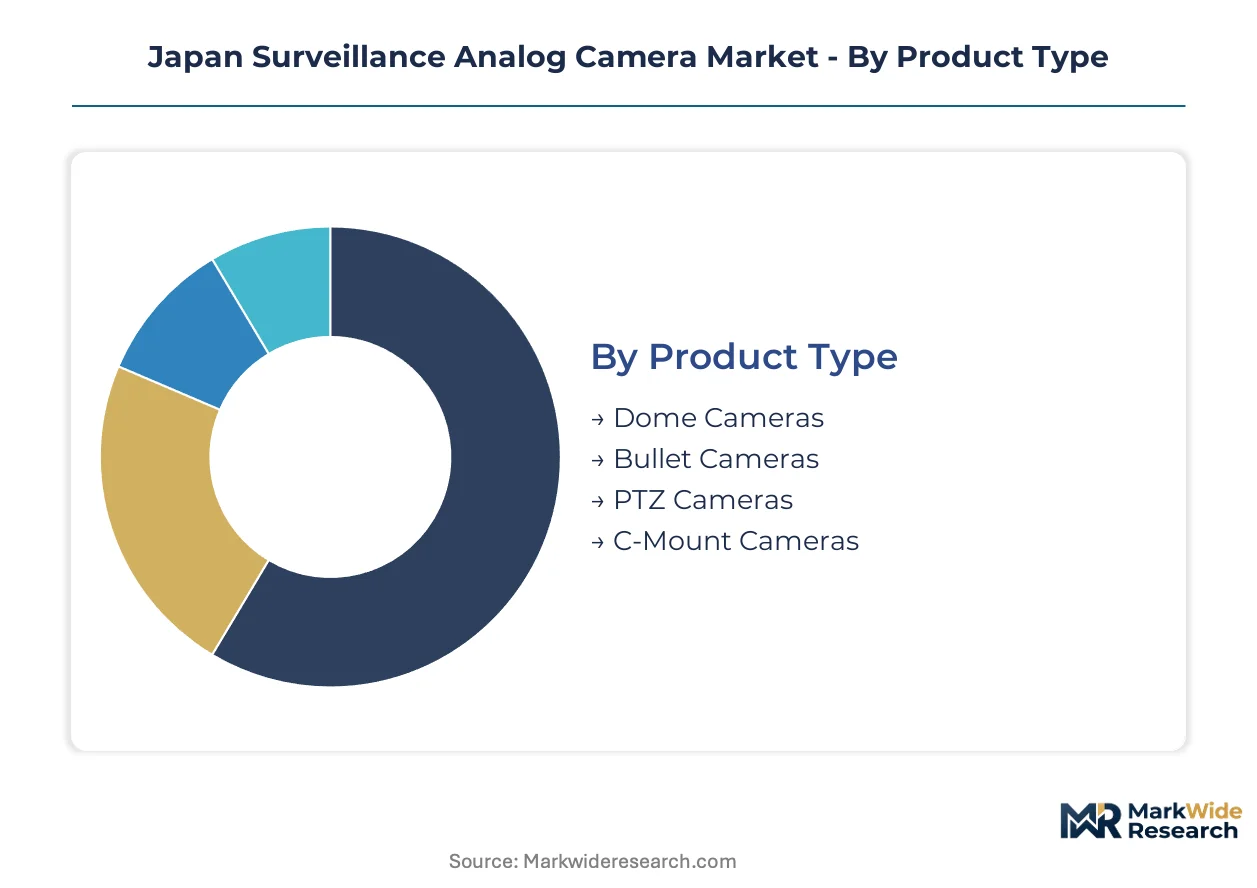
Japan's surveillance analog camera market segments along four intersecting dimensions that determine procurement patterns. Product form factors and transmission technologies dominate vendor positioning, while end-user verticals and installation environments shape specification requirements across municipal and private deployments.
Product Type:
Dome cameras embed directly into ceiling infrastructure for discreet indoor monitoring, while bullet cameras mount externally as standalone perimeter sentinels; PTZ and C-mount variants occupy specialized niches requiring operator control or lens interchangeability.
- Dome Cameras:Vandal-resistant housings with 360-degree coverage capability suit high-traffic retail environments in Osaka's commercial districts. Demand concentrates in department store refurbishment projects where METI efficiency mandates drive replacement of aging fixed-position units.
- Bullet Cameras:Weather-sealed cylindrical enclosures with integrated infrared illumination dominate Keihin industrial zone perimeter installations. Osaka-Kobe corridor infrastructure owners specify these for legacy coaxial retention during security upgrades.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-directed coverage at Kansai International Airport transit platforms.
- C-Mount Cameras:Interchangeable lens systems serve broadcast-originated surveillance applications requiring focal length flexibility.
Dome cameras lead volumes today; bullet cameras are gaining share fastest in industrial retrofit waves.
Technology:
Transmission architectures segment by infrastructure investment depth, from pure coaxial preservation through hybrid signal conversion to wireless bypass and infrared night-vision integration.
- Coaxial:Traditional composite video transmission over RG-59/RG-6 cabling persists in legacy government facilities where full rewiring costs are prohibitive. Tokyo metropolitan railway operators retain coaxial endpoints to preserve cable investments while upgrading backhaul.
- IP Hybrid:Single-chip analog-to-digital processors enable IP analytics over existing coaxial runs. Municipal transit authorities in the Chubu region deploy these to satisfy police agency encryption protocols without infrastructure replacement.
- Wireless:RF transmission modules serve temporary deployment scenarios and heritage building installations where cable routing is restricted.
- Infrared:Thermal imaging sensor integration extends low-light functionality for warehouse perimeter monitoring.
Coaxial maintains installed-base dominance; IP hybrid configurations show steepest expansion trajectory as METI efficiency benchmarks filter procurement.
End User:
Demand concentration varies by sector-specific regulatory exposure, with government and transportation verticals bound by police agency protocols while retail and residential buyers prioritize cost containment.
- Retail Stores:Loss prevention departments in Tokyo and Osaka shopping districts drive dome camera procurement for discrete customer monitoring. Prefecture-level fire safety codes mandate coverage density that sustains analog endpoint demand during store renovations.
- Government Agencies:National police agency encryption standards require hybrid architectures for facility security. Municipal building managers in the Kansai region balance JIS certification requirements against budget consolidation pressures.
- Transportation Hubs:Railway operators and airport authorities specify redundant analog backup pathways for regulatory compliance.
- Residential Areas:Condominium management associations in suburban Tokyo prefectures select cost-optimized bullet configurations for perimeter monitoring.
Government agencies anchor procurement value; retail stores are expanding most quickly as consumer-facing security investments recover.
Installation:
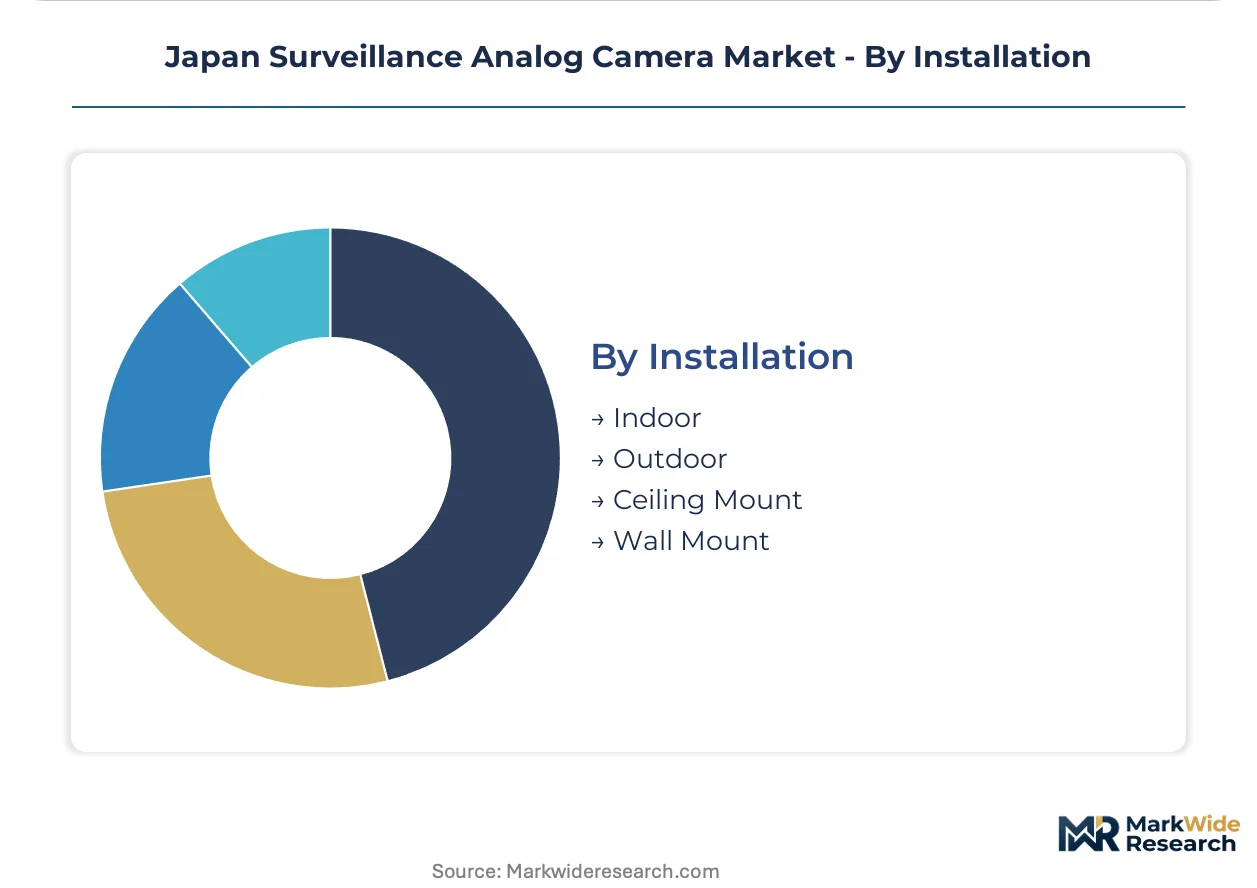
Mounting configurations determine environmental sealing requirements and cabling topology, with indoor-ceiling and outdoor-wall deployments representing distinct specification regimes.
- Indoor:Climate-controlled environments permit lighter housing designs with passive thermal management. Ceiling-recessed dome installations dominate Osaka commercial retrofit projects.
- Outdoor:IP66+ sealing and heating elements withstand Japan's humidity and temperature extremes. Bullet cameras with wall-mount brackets serve Keihin industrial perimeter applications.
- Ceiling Mount:Suspended infrastructure integration requires vandal-resistant dome housings with concealed cable routing.
- Wall Mount:Vertical surface attachment suits perimeter corridors and loading dock monitoring at warehouse facilities.
Outdoor installations command premium pricing; ceiling mount configurations are climbing the fastest as interior retail refurbishment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's surveillance analog camera demand diverges sharply from South Korea's IP-native procurement patterns, with Japanese infrastructure owners prioritizing coaxial retention over full-digital conversion. This structural preference shapes sub-regional deployment intensity across Japan's major industrial corridors.
Kanto/Tokyo
Tokyo Metropolitan railway operators and Narita/Haneda airport authorities sustain demand for hybrid analog-digital architectures to preserve legacy cable investments. METI's 2024 Top Runner standby power standards filter procurement eligibility for municipal transit security tenders. The Greater Tokyo Area concentrates PTZ camera deployments at Shinjuku and Shibuya station platforms where police agency encryption protocols mandate redundant transmission pathways.
Kansai/Osaka
Osaka-Kobe industrial corridor retrofit projects drive bullet camera volumes for perimeter security at Keihin zone manufacturing facilities. JIS environmental sealing requirements govern outdoor installations across Hyogo prefecture warehouse complexes. Kansai International and Itami airports specify vandal-resistant dome configurations with analog backup compliance for aviation security redundancy.
Chubu/Nagoya
Nagoya municipal transit authorities deploy IP-hybrid processors to satisfy encrypted transmission mandates without infrastructure replacement. Prefecture-level police departments mediate procurement disputes between facilities management and IT security offices through technical specification templates. The Chubu region reports extended evaluation cycles as hybrid architecture acceptance testing prolongs deployment timelines.
Kyushu
Fukuoka prefecture government facilities balance JIS certification costs against budget consolidation pressures for security system upgrades. Industrial manufacturers in Kitakyushu retain coaxial endpoints during factory automation retrofits to minimize production downtime. Kyushu Electric Power substations specify infrared-integrated analog housings for perimeter monitoring in remote facility locations.
Hokkaido
Sapporo municipal buildings face steep bullet camera redesign costs due to cold-climate heating element integration under METI efficiency benchmarks. Hokkaido prefecture police protocols emphasize encrypted hybrid architectures for regional government facility security. Sapporo New Chitose Airport maintains analog backup pathways for winter-weather operational resilience in aviation surveillance systems.
Japan Surveillance Analog Camera Market Competitive Landscape
Japanese producers anchor domestic supply for legacy-compatible architectures; Chinese and South Korean specialists hold price-adjusted positions in municipal transit and industrial retrofit segments. The vendor base stratifies across three tiers: domestic incumbents with vertical manufacturing footprints, regional challengers competing on feature density, and offshore suppliers penetrating cost-sensitive procurement. Two dominant competitive moves define positioning: backward integration into sensor fabrication to secure broadcast-grade component supply, and strategic partnerships with system integrators to bridge analog-IP deployment complexity.
Within the domestic incumbent tier, Panasonic Holdings and Sony occupy positions shaped by manufacturing scale and broadcast-derived technical heritage respectively. Sony exemplifies premium-tier positioning through captive image sensor production. Panasonic Holdings represents integrated manufacturing discipline across form factor variants. Hanwha Vision sits within the regional challenger archetype, competing on price-adjusted specifications for municipal contracts. Chinese specialists Hangzhou Hikvision Digital Technology and Dahua Technology anchor offshore supply for cost-optimized bullet and dome configurations in private-sector industrial deployments.
| Leading Market Players |
|---|
| Tescom Japan |
| CP PLUS |
| Hangzhou Hikvision Digital Technology |
| Zhejiang Uniview Technologies |
| Sony |
| Dahua Technology |
| Panasonic Holdings |
| Shenzhen Sunell Technology |
| Hanwha Vision |
| Others |
Pricing and Supply Chain Analysis
METI's 2024 Top Runner standby power standards gate qualified supply and premium-tier pricing access by disqualifying conventional analog power supplies from public tenders while rewarding compliant switched-mode designs with procurement eligibility and margin protection.
Pricing Analysis
Capacity additions in China's sensor component sector are reshaping price floors for economy-tier bullet and dome configurations. Pricing stratifies across premium broadcast-grade variants from Sony's captive sensor fabs, standard JIS-certified municipal configurations, and economy-tier private-sector imports. Cost compression in the economy tier intensifies because Chinese manufacturers compete on feature-adjusted pricing for industrial retrofit contracts. Municipal transit authorities show least price sensitivity due to encryption compliance mandates, while condominium management associations in suburban Tokyo prefectures drive hardest bargain negotiations.
Supply Chain Analysis
JIS environmental sealing and electromagnetic compatibility certifications gate component sourcing for outdoor installations, extending qualification timelines for new product releases. Image sensor supply concentrates in Japan through Sony's domestic fabrication, South Korea via Samsung's sensor division, and China's growing CMOS foundry base. Raw material dependencies include broadcast-grade silicon wafers, coaxial cable copper conductors, and infrared LED phosphor substrates. Single-source vulnerability in premium sensor supply creates procurement risk for dome and PTZ variants targeting aviation security applications. Distribution runs through system integrators serving prefecture-level government facilities and direct OEM relationships with railway operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where hybrid architecture mandates from Japan's national police agency protocols sustain replacement-cycle demand regardless of broader technology transitions.
For Market Incumbents: Lock in municipal transit relationships through embedded service contracts that bundle maintenance with equipment refresh cycles. Deepen backward integration into switched-mode power supply production to satisfy METI efficiency benchmarks without margin erosion. Defend against Chinese price competition by emphasizing police agency encryption certification and JIS environmental sealing as non-replicable qualifications. For New Entrants and Emerging Players: Enter via prefecture-level maintenance outsourcing contracts where facilities management teams seek vendor transitions independent of capital procurement decisions. Target Kyushu and Hokkaido regional governments where budget consolidation pressures create openings for cost-optimized bullet camera configurations. Pursue system integrator partnerships that bridge analog-IP deployment complexity for municipal IT departments lacking hybrid expertise. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with police agency certification relationships because municipal procurement fragmentation prevents national vendor consolidation. The five-to-ten year viability window rests on infrastructure replacement cycles rather than technology obsolescence. Target acquisition candidates with embedded service contract revenue streams and JIS testing laboratory relationships. Watch Kansai airport expansion timelines as inflection indicator for premium dome and PTZ demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Signal Processor Integration | Single-chip analog-to-digital consolidation preserves coaxial investments while enabling IP analytics for railway operators. |
| JIS Certification Investment | Environmental sealing qualification extends product launch windows but gates access to outdoor perimeter installations. |
| Embedded Service Contract Bundling | Prefecture-level O&M unbundling creates recurring revenue streams independent of capital budget cycles. |
| Infrared Sensor Convergence | Thermal imaging integration opens warehouse perimeter applications previously requiring separate night-vision systems. |
| System Integrator Partnership | Channel relationships bridge analog-IP deployment complexity that municipal IT departments cannot resolve internally. |
Research Methodology
Multiple input streams — procurement officer interviews at prefecture-level governments, technical director discussions with railway operators, and secondary validation against METI equipment registry data — were reconciled through bottom-up and top-down triangulation. Primary engagement covered municipal transit authorities in Kanto, Kansai, and Chubu regions; facilities management teams at Keihin industrial zone warehouses; and system integrators serving aviation security applications. Secondary sources included JIS standard revision documentation, national police agency protocol amendments, and customs records for analog camera component imports.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass product form factor, transmission architecture, end-use vertical, and installation environment. CAGRs were derived from replacement-cycle timing analysis against municipal budget consolidation patterns and infrastructure upgrade path selection. Industry-specific forecast inputs incorporated METI Top Runner standby power threshold revisions and police agency encryption protocol enforcement intensity.
Inputs from prefecture-level procurement databases and railway operator capex disclosures were available through the study window; gaps in condominium association private procurement records introduce uncertainty bands in residential segment estimates. Forecasts reflect assumptions regarding hybrid architecture acceptance timelines and coaxial technician labor market conditions. A model refresh is warranted upon material change in METI efficiency benchmark enforcement or national police agency protocol amendments affecting encryption pathway requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market