
 Europe Video Surveillance Storage Market | 2026-2036
Europe Video Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Surveillance Storage Market Insights
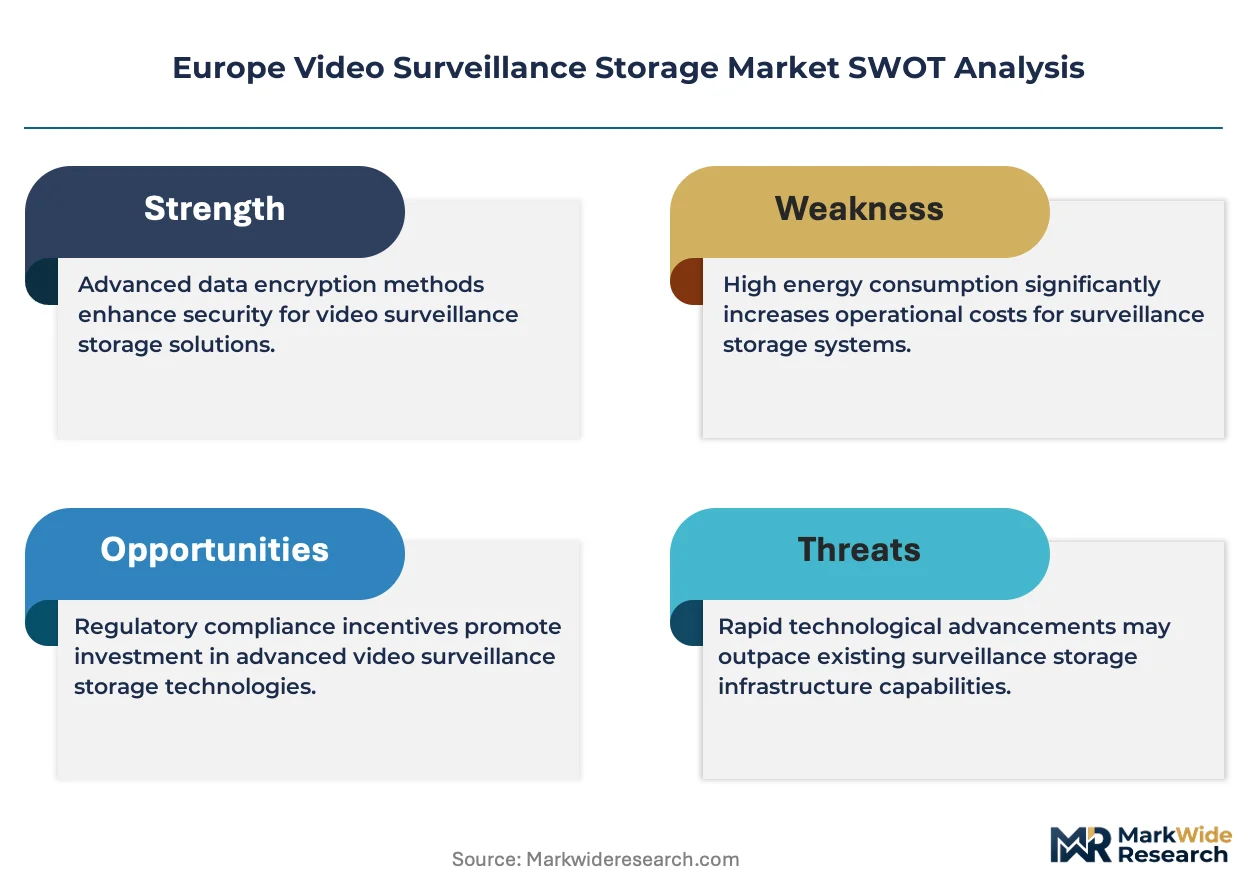
CE marking under the EU's Radio Equipment Directive is unwinding competitive access for non-compliant storage vendors. Dell Technologies Inc. leverages its enterprise server footprint to anchor large-scale surveillance deployments across European government datacenters. Seagate Technology specializes in surveillance-optimized HDD architectures that sustain write-intensive workloads for continuous video ingestion. Bosch Security Systems navigates GDPR-aligned encryption requirements to differentiate its on-premises storage offerings for law enforcement clients.
Europe video surveillance storage encompasses disk arrays, network-attached systems, and cloud repositories architected for sequential write throughput exceeding 300 MB/s per camera stream, with retention policies spanning 30 to 90 days for forensic admissibility. NVR deployments dominate municipal and mid-tier installations where latency constraints preclude cloud egress, while cloud storage segments capture fastest expansion among retail chains operating multi-country footprints. Hybrid deployment models concentrate margin pools by bridging on-premises buffering with tiered cloud archival for compliance-driven retention.
GDPR mandates from the European Data Protection Board, the EU AI Act's biometric surveillance prohibitions, and EN 50132 video surveillance standards collectively dictate encryption, retention limits, and audit trail specifications across member states. The EU Green Deal's datacenter efficiency targets are pressuring storage vendors to demonstrate power consumption metrics before public sector procurement. Stakeholders must monitor how the EU's forthcoming Data Act provisions on cloud portability reshape hybrid storage procurement terms across continental police forces and transport authorities.
Market Dynamics
The EU AI Act's biometric surveillance prohibitions are forcing storage architects to redesign retention workflows and encryption layers across European law enforcement and municipal deployments. This regulatory pressure is compressing legacy infrastructure replacement cycles while elevating compliance-ready hardware procurement.
Growth Catalysts
- Smart City Mandates:German municipalities are expanding centralized video ingestion hubs for urban traffic management and public safety monitoring, driving petabyte-scale storage tenders.
- GDPR Forensic Retention:The European Data Protection Board's guidelines on lawful processing are extending video retention windows for criminal investigations, expanding archival capacity requirements.
- Critical Infrastructure Protection:France's energy and transport operators are hardening perimeter surveillance with redundant storage clusters to meet EN 50132-7 availability standards.
Market Restraints
- NAND Flash Cost Volatility:Solid-state storage for edge analytics nodes remains exposed to memory chip pricing swings, compressing margin on SSD-based NVR configurations.
- CE Marking Compliance Burden:Non-compliant vendors face exclusion from public sector procurement under the Radio Equipment Directive, concentrating supply among established European channels.
- Cloud Latency Constraints:Real-time facial recognition at the edge precludes pure cloud architectures for law enforcement, limiting hybrid adoption in time-sensitive applications.
Strategic Opportunities
- Eastern European Modernization:Polish and Romanian municipal governments are consolidating legacy analog systems into IP-based storage networks, opening greenfield deployment windows.
- EU Green Deal Procurement:Datacenter efficiency mandates are creating preference for power-optimized HDD arrays and liquid-cooled storage enclosures in public tenders.
- Edge-to-Cloud Tiering:Retail chains operating across multiple EU member states are adopting automated lifecycle policies that buffer high-resolution streams locally before cost-optimized cloud archival.
Industry Challenges
- Encryption Key Management Complexity:GDPR-mandated encryption at rest and in transit is forcing integrators to deploy hardware security modules, extending deployment timelines and certification overhead.
- Interoperability with Legacy VMS:Proprietary video management software from incumbent security vendors creates integration friction for third-party storage platforms, complicating multi-vendor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Surveillance Storage Market |
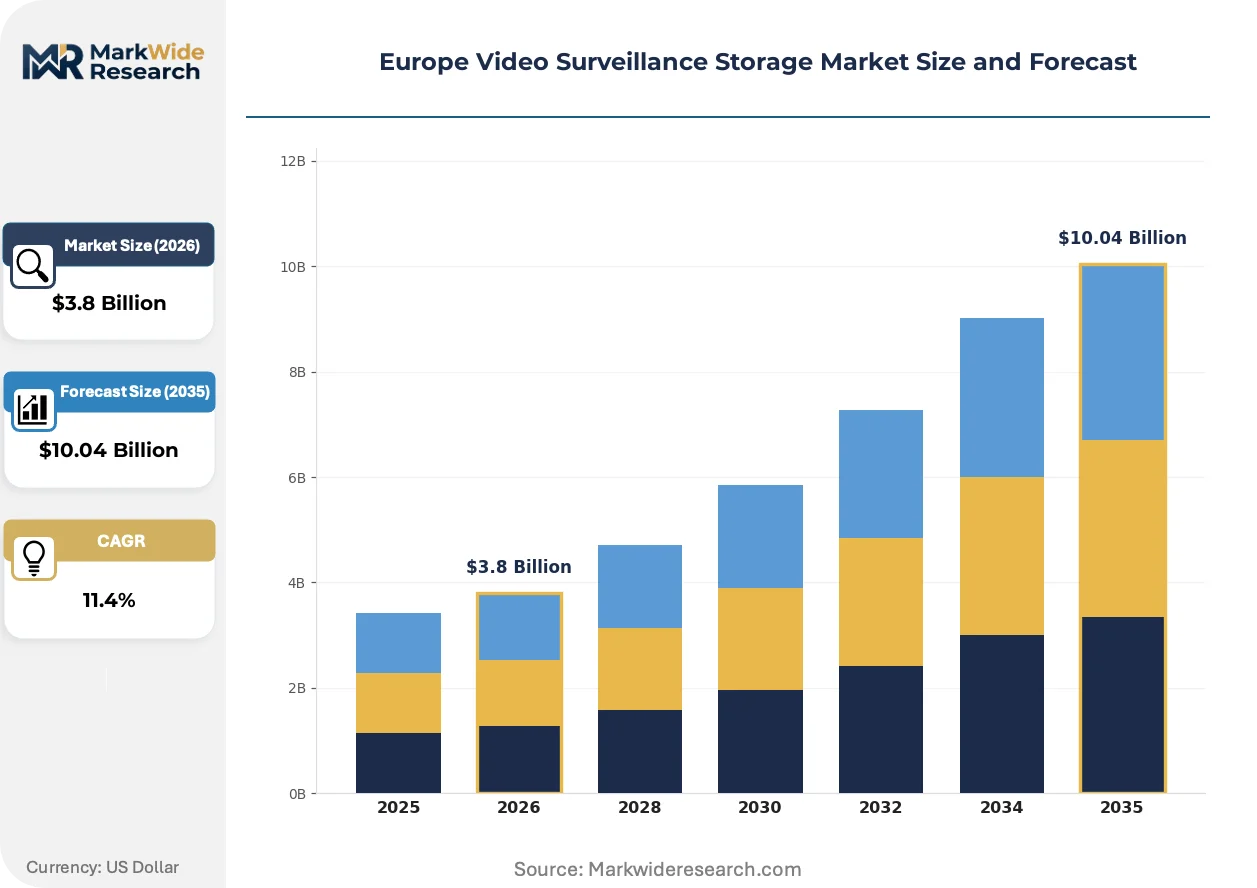
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NVR, SAN, DAS, Cloud Storage Deployment: On-Premises, Hybrid, Off-Site, Cloud-Based End User: Retail, Transportation, Government, Healthcare Storage Medium: HDD, SSD, Tape, Flash |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dell Technologies Inc., Huawei Technologies Co., Ltd., AXIS Communications, Bosch Security Systems, Dahua Technology Co., Ltd., NetApp Inc., Seagate Technology, Hanwha Vision Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Surveillance Storage Market Trends and Innovations
Storage architectures are bifurcating between high-density edge appliances and centralized cloud repositories, with software-defined layers abstracting hardware differences. This shift is compressing traditional NVR vendor margins while elevating data orchestration capabilities.
High-capacity surveillance-optimized hard disk drives are miniaturizing physical footprints while sustaining 550 TB annual workload ratings. Mid-tier municipal buyers in Spain and Italy are adopting 16-bay compact enclosures for street-level deployments. This density compression is displacing rack-scale alternatives in space-constrained traffic control centers and reducing cooling overhead.
The EU AI Act's Article 5 prohibitions on real-time biometric identification in public spaces are mandating audit-trail logging and purpose-limitation controls in storage software. Vendors must now demonstrate technical measures for automated deletion and access logging to qualify for law enforcement contracts. French and German police procurement frameworks are embedding these requirements as mandatory technical specifications.
Consolidated buying by multi-country retail operators is compressing vendor negotiation cycles and unbundling installation services from hardware procurement. Large supermarket chains are negotiating direct storage supply agreements with manufacturers, bypassing regional security integrators. This disintermediation is most visible in the Benelux region where centralized procurement hubs serve cross-border outlet networks.
Europe Video Surveillance Storage Market Segmentation
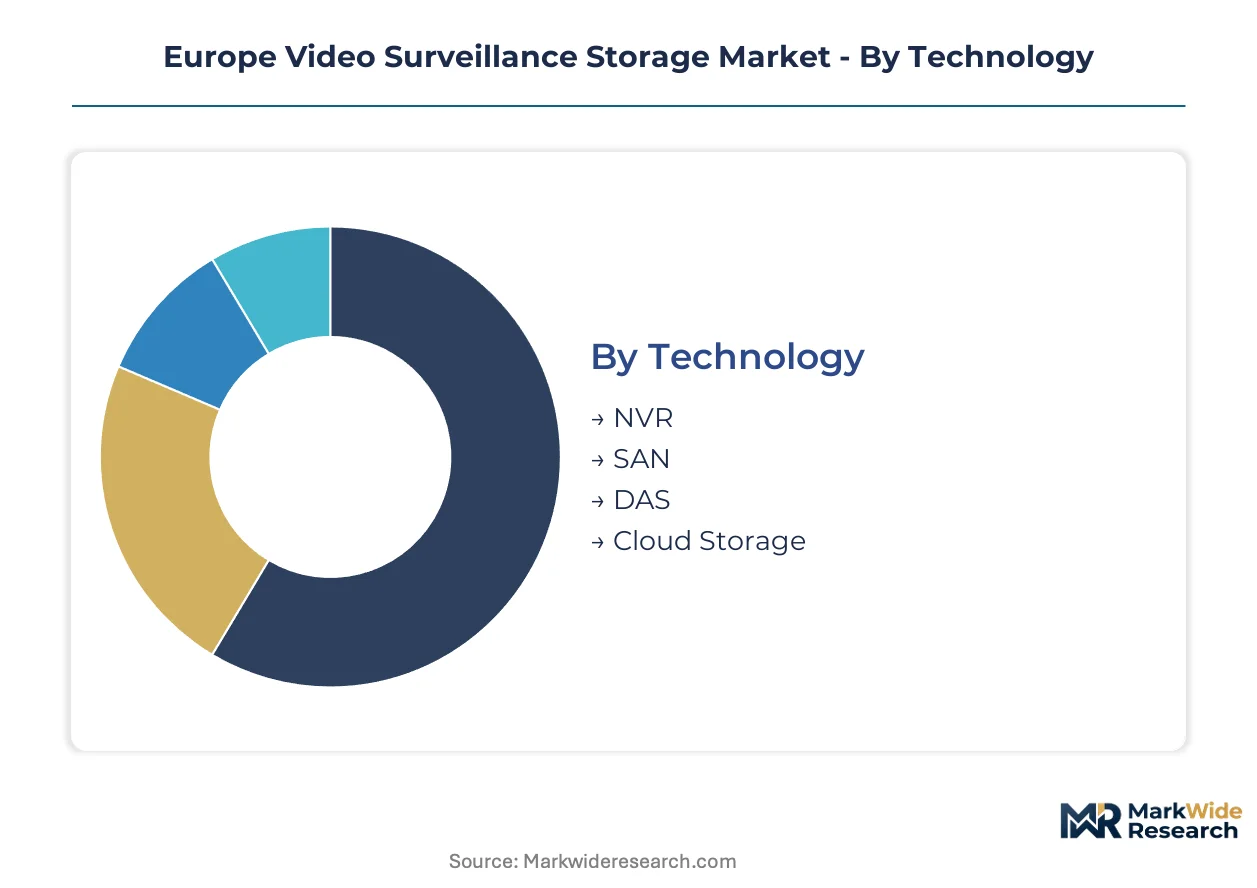
Storage architects across Europe must navigate divergent workload profiles when specifying video surveillance infrastructure. Each segment exhibits distinct substitution pressures from adjacent technologies and competing deployment models.
Technology:
Cloud storage architectures exert substitution pressure on traditional on-premises appliances, though latency constraints preserve niche dominance for edge-resident systems.
- NVR:Network video recorders integrate video management software with direct-attached storage in hardened enclosures rated for 24/7 operation. German municipal traffic authorities specify NVR clusters for street-level deployments where sub-100ms retrieval latency is mandatory for incident response.
- Cloud Storage:Hyperscale repositories with automated tiering and geo-redundancy serve multi-country retail operators. French supermarket chains negotiate direct supply agreements to bypass regional integrators, compressing procurement cycles while demanding GDPR-aligned encryption key escrow.
- SAN:Fibre Channel and iSCSI arrays consolidate camera feeds from distributed edge nodes into centralized pools for analytics workloads.
- DAS:Direct-attached configurations persist in legacy analog-to-IP migration projects across Polish municipal deployments.
NVR retains volume leadership across European municipal procurement; cloud storage holds the steepest expansion curve among cross-border retail operators.
Deployment:
Cost tier stratification separates premium hybrid architectures from economy-focused pure-cloud alternatives, with mid-market buyers gravitating toward buffered edge configurations.
- Hybrid:Edge buffering with automated cloud archival balances latency against compliance retention. EN 50132-7 availability requirements for French critical infrastructure operators mandate redundant local clusters with asynchronous replication to secondary sites.
- On-Premises:Fully air-gapped installations serve law enforcement agencies subject to EU AI Act biometric surveillance restrictions. German state police forces specify on-premises encryption with hardware security modules to satisfy GDPR forensic admissibility standards.
- Cloud-Based:Pure SaaS consumption models eliminate capital expenditure for mid-tier healthcare clinics in Spain and Italy.
- Off-Site:Colocated secondary storage addresses disaster recovery mandates without full cloud dependency.
On-premises deployments dominate public sector tenders; hybrid configurations are climbing fastest among transportation authorities modernizing legacy networks.
End User:
Application-specific retention policies and resolution requirements fragment procurement specifications across verticals.
- Government:Municipal and national security agencies operate the most stringent compliance frameworks. The EU AI Act's Article 5 prohibitions force storage software vendors to demonstrate automated deletion and purpose-limitation controls to qualify for French and German police contracts.
- Transportation:Airports, railways, and urban transit operators require 90-day minimum retention with sub-second failover. Operators in the Benelux region consolidate multi-country outlet networks through centralized procurement hubs serving cross-border surveillance requirements.
- Retail:Loss prevention and liability documentation drive petabyte-scale deployments with 30-day standard retention.
- Healthcare:Patient privacy regulations constrain camera placement while mandating encrypted archival for incident investigation.
Government verticals command the highest compliance premiums; transportation is gaining share fastest as infrastructure hardening accelerates.
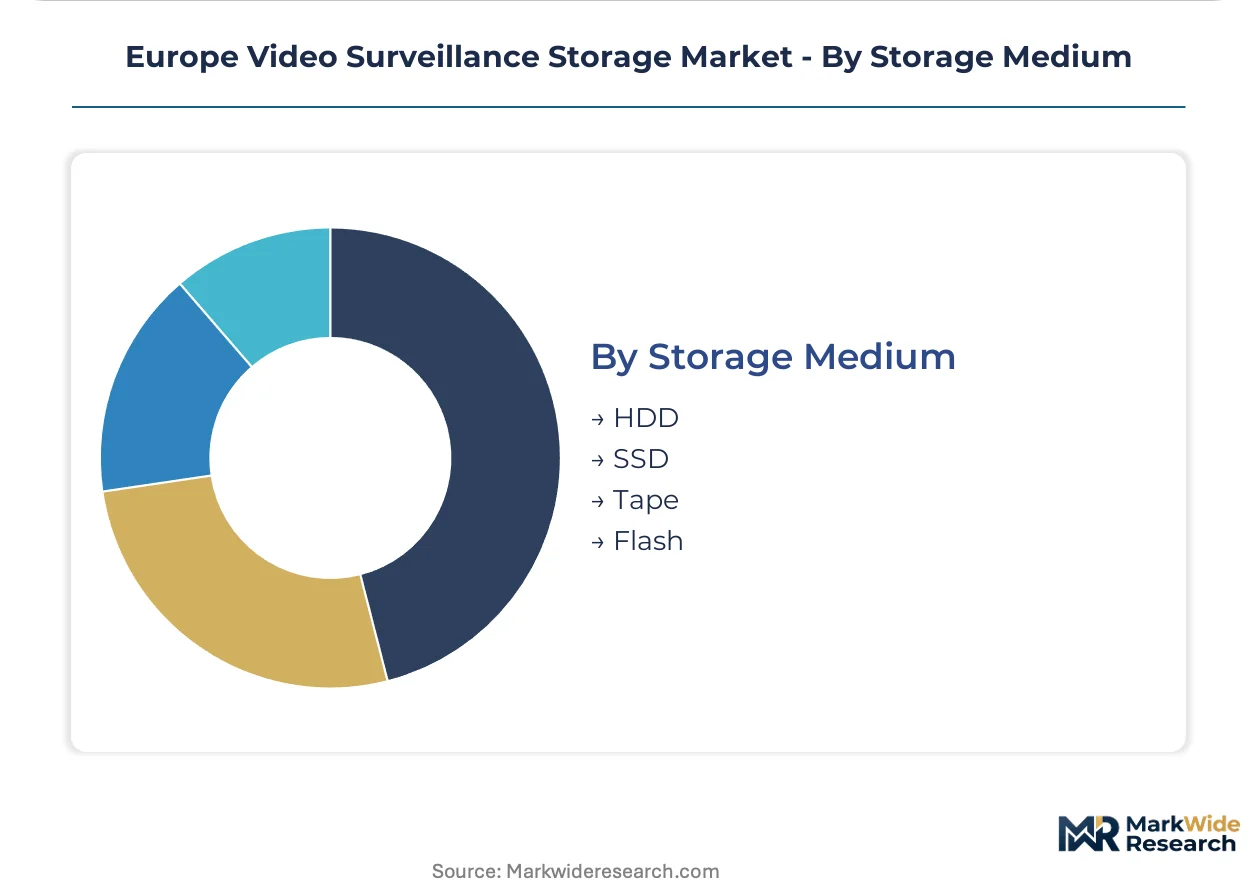
Storage Medium:
Supply concentration in NAND flash foundries versus HDD manufacturing creates divergent cost volatility exposures for procurement planners.
- HDD:Surveillance-optimized hard disk drives sustain 550 TB annual workload ratings with sequential write throughput exceeding 300 MB/s per stream. Mid-tier municipal buyers in Spain and Italy adopt 16-bay compact enclosures, displacing rack-scale alternatives in space-constrained traffic control centers.
- SSD:Solid-state storage enables edge analytics nodes for real-time facial recognition where law enforcement latency constraints preclude disk-based retrieval. NAND flash cost volatility compresses margins on SSD-based NVR configurations.
- Flash:High-endurance NAND serves mobile surveillance units in Romanian and Polish border patrol applications.
- Tape:Linear tape file system archives provide cost-optimized cold storage for multi-year regulatory retention in energy sector perimeter surveillance.
HDD arrays retain volume leadership across municipal and mid-tier installations; SSD configurations are expanding most quickly in time-sensitive law enforcement edge deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European procurement for video surveillance storage clusters around government security mandates, critical infrastructure hardening, and retail chain consolidation. Buyer archetypes span municipal police forces, transport operators, and multi-country supermarket networks.
Germany
Smart city deployments in Berlin and Munich are driving petabyte-scale tenders for traffic management hubs. The EU AI Act's biometric surveillance prohibitions force state police forces to specify on-premises encryption with hardware security modules. Bavarian municipalities lead adoption of 16-bay compact NVR enclosures for street-level surveillance.
France
Critical infrastructure operators at Charles de Gaulle Airport and SNCF rail networks mandate 90-day retention with sub-second failover under EN 50132-7 standards. The CNIL enforces GDPR-aligned encryption key escrow for cloud storage procurement. Île-de-France police frameworks embed automated deletion controls as mandatory technical specifications.
United Kingdom
London's Metropolitan Police and transport authorities are modernizing legacy analog networks into IP-based storage architectures. The Information Commissioner's Office guidelines extend video retention windows for criminal investigations. Midlands manufacturing clusters are adopting hybrid edge-to-cloud tiering for perimeter surveillance.
Poland
Municipal governments in Warsaw and Kraków are consolidating analog systems into centralized IP storage networks. National funds for public safety modernization are opening greenfield deployment windows. Border patrol applications in eastern regions deploy mobile surveillance units with flash-optimized storage.
Spain
Mid-tier municipal buyers in Barcelona and Madrid are adopting compact HDD enclosures to displace rack-scale alternatives in space-constrained traffic centers. Healthcare clinics in Catalonia pursue pure SaaS consumption models to eliminate capital expenditure. Andalusian energy sector operators deploy tape archives for multi-year regulatory retention.
Europe Video Surveillance Storage Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with enterprise storage divisions and specialized surveillance-optimized hardware vendors. Market structure exhibits moderate consolidation with tiered competition across premium enterprise arrays, mid-tier NVR appliances, and cost-optimized edge devices. Strategic archetypes include server-to-storage integrated suppliers, surveillance-dedicated drive manufacturers, and security-systems integrators with captive storage offerings. Dominant competitive moves encompass geographic expansion through local channel partnerships and portfolio diversification into software-defined orchestration layers.
Within the diversified technology tier, Dell Technologies Inc. and Huawei Technologies Co., Ltd. occupy positions spanning enterprise server footprints through edge appliance portfolios. Surveillance-optimized storage specialists include Seagate Technology, which exemplifies the dedicated drive manufacturing archetype with workload-rated HDD architectures. Hangzhou Hikvision Digital Technology Co., Ltd. represents the security-systems integrator model, anchoring end-to-end deployment capabilities from camera through retention infrastructure. Bosch Security Systems sits within the European-headquartered compliance-focused segment, differentiated by GDPR-aligned encryption positioning for law enforcement clients.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dell Technologies Inc. |
| Huawei Technologies Co., Ltd. |
| AXIS Communications |
| Bosch Security Systems |
| Dahua Technology Co., Ltd. |
| NetApp Inc. |
| Seagate Technology |
| Hanwha Vision Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU's Radio Equipment Directive gates vendor qualification while simultaneously stratifying procurement tiers across European public sector tenders. This dual function compresses margin pools for non-compliant suppliers while elevating price premiums for certified hardware in law enforcement and critical infrastructure deployments.
Pricing Analysis
Cost-plus contracts with NAND flash indexation dominate SSD-based NVR configurations, exposing integrators to memory chip pricing volatility. Three-tier pricing structure across enterprise-grade encryption, mid-tier municipal specifications, and economy-focused edge appliances reflects certification depth and after-sales service bundling. Cost compression in mid-tier HDD arrays is intensifying because Polish and Romanian municipalities consolidate analog-to-IP migrations. Retail chains operating multi-country footprints exhibit lowest price sensitivity due to centralized procurement scale, while Spanish healthcare clinics pursuing pure SaaS models show highest elasticity.
Supply Chain Analysis
Strategic stockpiling of surveillance-optimized HDDs prevails among German municipal authorities buffering against component lead time uncertainty, while just-in-time procurement characterizes cloud storage tier negotiations. Manufacturing concentrates in China, Thailand, and Malaysia for drive assembly, with controller silicon sourcing from Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for high-capacity platter substrates. Distribution runs through authorized security integrators in France and Germany, direct manufacturer agreements in the Benelux retail sector, and public procurement frameworks for police and transport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified hardware security module integration represents the critical capability gap separating compliant from excluded vendors in European law enforcement tenders. This scarcity concentrates margin capture among incumbents with pre-certified encryption architectures.
For Market Incumbents: Consolidate channel control through exclusive distribution partnerships with German municipal procurement hubs. Deepen backward integration into surveillance-optimized HDD controller design to offset NAND flash cost volatility. The EU AI Act's biometric surveillance prohibitions threaten legacy software architectures; certification investment in automated deletion controls defends position in French and German police frameworks. For New Entrants and Emerging Players: Anchor in Eastern European greenfield modernization, specifically Polish municipal analog-to-IP consolidation and Romanian border patrol mobile surveillance. The most penetrable entry point lies in compact 16-bay HDD enclosures for space-constrained Spanish and Italian traffic centers. A compliance-first go-to-market angle—pre-integrating GDPR-aligned encryption and hardware security modules—bypasses incumbent certification timelines. For Investors and Strategic Acquirers: The EU AI Act's Article 5 enforcement reshapes the acquisition landscape by devaluing real-time biometric storage stacks while elevating audit-trail software vendors. Long-term viability favors targets with forensic admissibility certification spanning multiple member states. The signal to watch is EN 50132-7 availability standard adoption rates among French critical infrastructure operators as a proxy for premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Integration | GDPR forensic admissibility requirements in German state police tenders mandate HSM pre-certification. |
| Edge-to-Cloud Tiering Automation | Benelux retail chains demand lifecycle policies bridging local buffering with cost-optimized archival. |
| Surveillance-Optimized HDD Development | 550 TB annual workload ratings differentiate Seagate's position in write-intensive municipal deployments. |
| GDPR-Aligned Encryption Escrow | CNIL enforcement in France requires cloud storage vendors to demonstrate key escrow technical measures. |
| Liquid-Cooled Storage Enclosure Launch | EU Green Deal datacenter efficiency targets create preference in public sector procurement specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across municipal procurement officers, critical infrastructure security directors, video management software architects, and surveillance storage hardware engineers. Secondary validation drew from EN 50132 standard documentation, EU AI Act regulatory filings, European Data Protection Board guidelines, hyperscaler datacenter efficiency disclosures, and customs trade data for storage component flows. Bottom-up installation unit estimates triangulated against top-down infrastructure spending allocations across member states.
Across the analysis window, the forecasting framework modeled technology substitution dynamics between NVR, cloud, SAN, DAS, and hybrid deployments; segmentation by storage medium including HDD, SSD, flash, and tape; and end-use verticals spanning government, transportation, retail, and healthcare. CAGRs were derived from regression against smart city infrastructure budgets, GDPR retention policy evolution, and retail chain cross-border expansion patterns. Inputs included municipal tender award data and critical infrastructure operator capex disclosures.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement trajectory and continued NAND flash supply normalization; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as biometric surveillance prohibition scope interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Video Surveillance Software Market