
 Connected Enterprise Video Surveillance Solutions Market | 2026-2036
Connected Enterprise Video Surveillance Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Enterprise Video Surveillance Solutions Market Outlook
Healthcare facility security is pivoting toward integrated video analytics platforms that unify patient flow monitoring with access control. Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor manufacturing to dominate price-sensitive enterprise tenders across Asia-Pacific. Bosch Security Systems differentiates through German-engineered edge-computing cameras that process analytics locally without cloud dependency. Honeywell International Inc. anchors its position via building-automation integration, selling surveillance as a module within broader facility management contracts.
Connected enterprise video surveillance solutions encompass networked camera hardware, video management platforms, and analytics software that transmit, store, and analyze visual data across IP-based infrastructure with resolutions typically ranging from 2MP to 8MP and frame rates optimized for motion detection. These systems serve primary commercial purposes including theft prevention, operational oversight, safety compliance verification, and forensic investigation support. IP cameras and video management software capture the dominant margin pool as enterprises abandon analog infrastructure, while cloud-based deployment models are expanding fastest among mid-market buyers seeking subscription flexibility over capital-intensive NVR installations. AI Analytics technology segments command premium positioning where behavioral recognition and anomaly detection justify per-camera software licensing fees.
The EU AI Act and GDPR constrain facial recognition deployments across European commercial settings, forcing vendors to offer anonymization-by-design architectures or forfeit market access. In the United States, FCC equipment authorization requirements and state-level biometric privacy laws in Illinois and Texas fragment compliance obligations for multi-national deployments. China's MIIT cybersecurity review and GB standards mandate local data residency for critical infrastructure operators, creating divergent product roadmaps. Stakeholders must monitor whether regulatory fragmentation hardens into incompatible technical standards or whether modular compliance architectures emerge as a competitive differentiator.
Market Dynamics
The EU AI Act's prohibition on real-time biometric identification in public spaces is forcing vendors to rearchitect facial recognition pipelines, while smart city procurement across Southeast Asia accelerates demand for networked camera density.
Growth Catalysts
- Smart City Infrastructure Mandates:Southeast Asian governments are bundling video surveillance into urban digitalization tenders, with Bangkok, Jakarta, and Ho Chi Minh City issuing multi-thousand-camera contracts.
- GDPR-Compliant Anonymization:The EU AI Act's risk-classification framework is creating pull for privacy-preserving analytics that process footage without storing biometric identifiers.
- Manufacturing Corridor Modernization:India's Dedicated Freight Corridor and industrial zones in Gujarat and Tamil Nadu are replacing analog systems with IP-based enterprise platforms.
Market Restraints
- Semiconductor Supply Concentration:Image sensor fabrication concentrates in Taiwan and South Korea, exposing camera OEMs to geopolitical supply disruptions.
- Cloud Latency Constraints:Real-time edge analytics requirements in critical infrastructure limit pure-cloud deployment models despite subscription appeal.
- FCC Equipment Authorization Friction:Multi-national deployments face fragmented compliance as US state-level biometric laws in Illinois and Texas impose additional layers beyond federal requirements.
Strategic Opportunities
- Healthcare Integration White Space:Hospital systems are unifying patient flow monitoring with access control, creating demand for video-analytics platforms that bridge security and operational efficiency.
- Mid-Market Subscription Pivot:Cloud-based VSaaS models are penetrating buyers previously priced out of capital-intensive NVR installations.
- Edge-AI Convergence:On-camera inference chips from Qualcomm and Ambarella are enabling behavioral recognition without cloud dependency, opening GDPR-compliant European contracts.
Industry Challenges
- Cybersecurity Skill Scarcity:Enterprise IT departments lack personnel to harden IP camera networks against botnet infiltration and lateral movement attacks.
- Legacy Analog Migration Complexity:Hybrid environments strain video management software compatibility, forcing costly middleware or full infrastructure replacement.
- Interoperability Certification Delays:ONVIF Profile T compliance testing bottlenecks product launches for manufacturers seeking multi-vendor ecosystem integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Enterprise Video Surveillance Solutions Market |
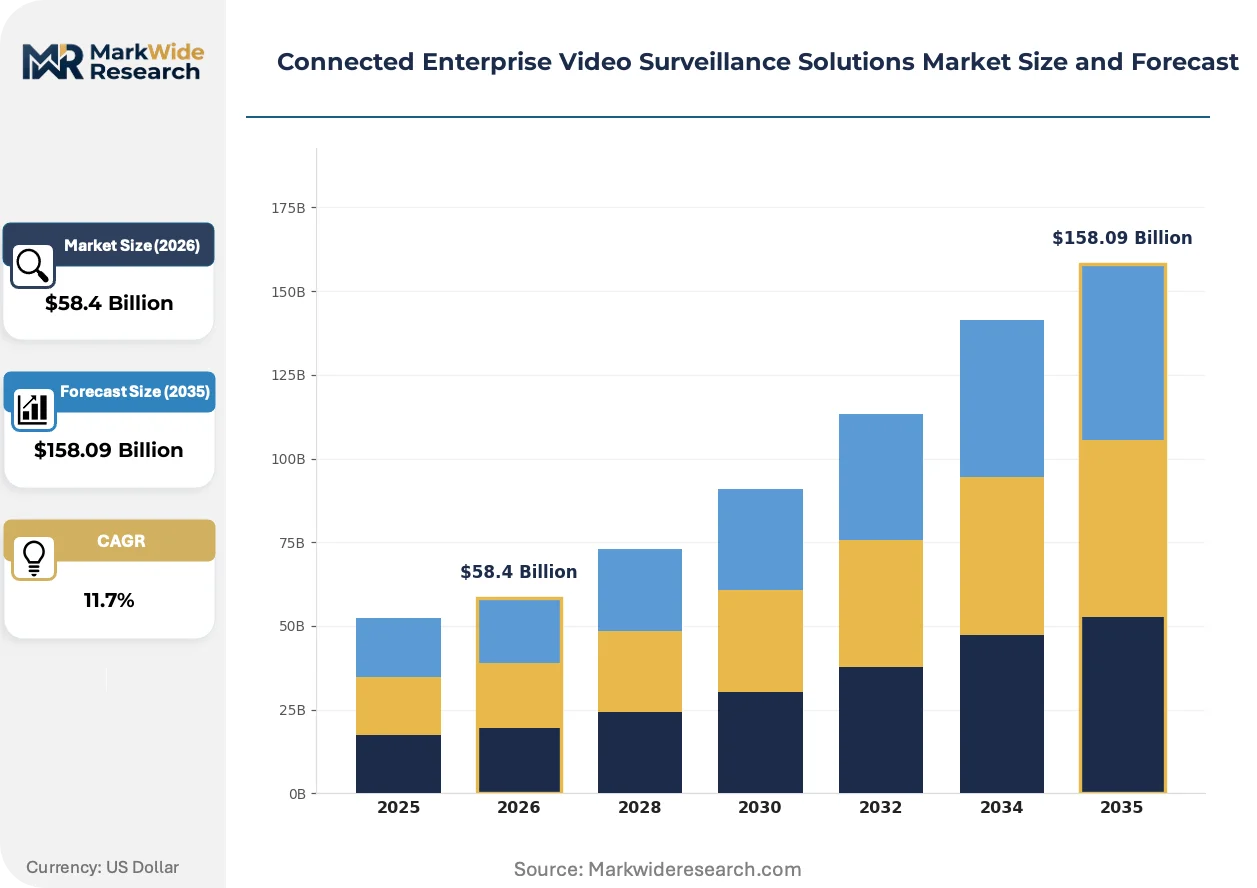
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $158.09 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Analog Cameras, Video Management Software, NVR Systems Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Retail, Healthcare, Transportation, Government Technology: AI Analytics, Wireless, HD Video, IoT Integration |
| Companies Covered | Hikvision Digital Technology Co., Ltd., Bosch Security Systems, Honeywell International Inc., Axis Communications AB, Hanwha Techwin Co., Ltd., Motorola Solutions, Inc., Dahua Technology Co., Ltd., Genetec Inc., VIVOTEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Enterprise Video Surveillance Solutions Market Strategic Shifts
Edge computing architectures are displacing centralized processing as the dominant design paradigm, while regulatory pressure on biometric data reshapes software roadmaps and procurement criteria across enterprise verticals.
AI-powered video analytics is expanding into predictive maintenance applications beyond security, with manufacturing facilities deploying thermal-overlay cameras to detect equipment overheating before failure. Automotive plants in Germany and electronics assembly lines in South Korea are piloting these systems at scale. The technology is expanding into operational technology budgets previously separate from security expenditure, compressing the traditional vendor-customer boundary.
The EU AI Act's risk-based classification system entered force in August 2024, prohibiting real-time remote biometric identification in publicly accessible spaces for law enforcement and commercial purposes alike. Vendors must now offer anonymization-by-design architectures or forfeit European market access. Healthcare and retail deployments in France, Germany, and the Netherlands are most affected, with buyers demanding compliance documentation before contract signature.
Enterprise buyers are consolidating vendor relationships around building-automation platforms that embed surveillance as a module rather than procuring standalone security systems. Honeywell and Johnson Controls are capturing this demand by bundling cameras with HVAC and access control under single master agreements. Facility management outsourcing contracts in US commercial real estate and Middle Eastern hospitality developments are the primary venues where this pattern is visible.
Connected Enterprise Video Surveillance Solutions Market Segmentation
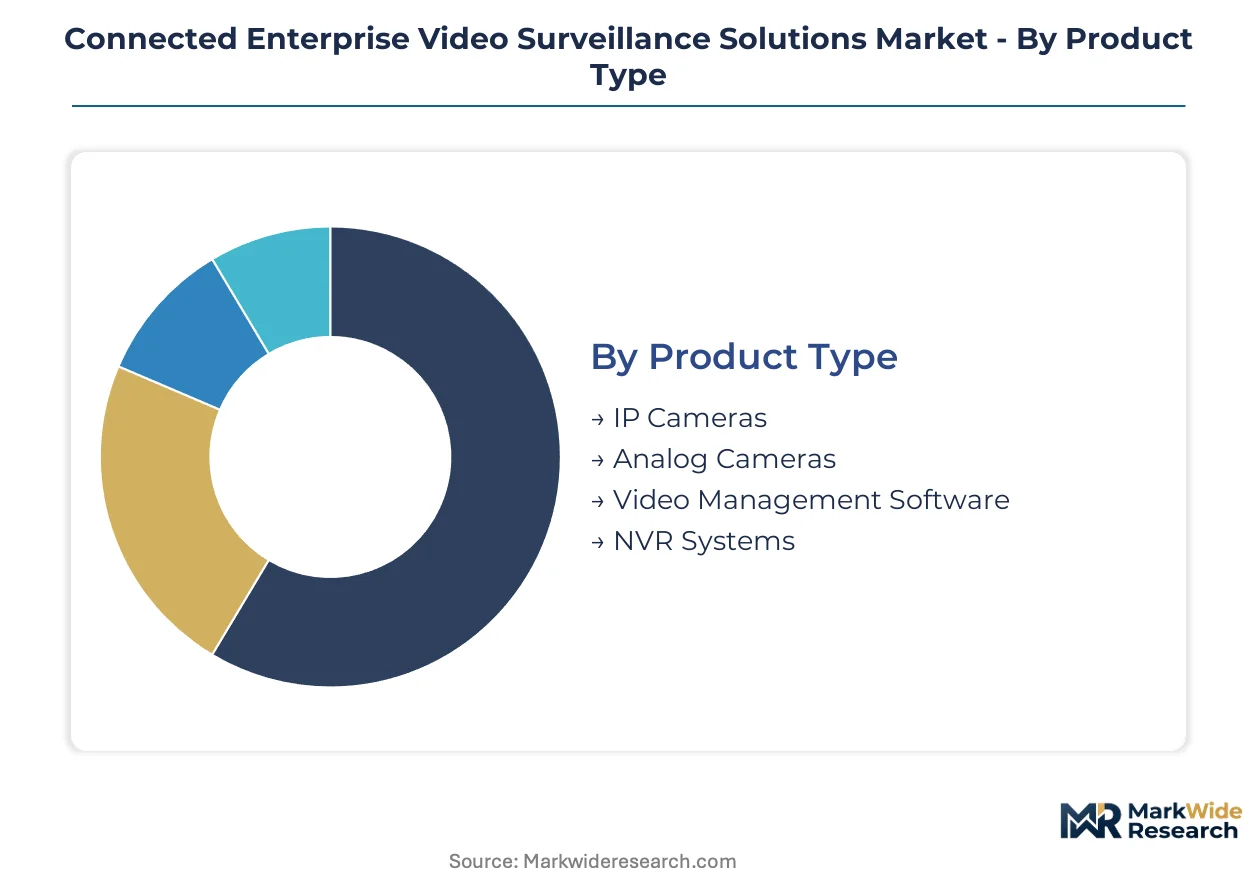
Segmentation in video surveillance reveals how procurement priorities split between capital-intensive hardware refresh cycles and software-centric operational platforms. Buyers increasingly bundle purchasing decisions across product, deployment, and technology layers rather than treating cameras as standalone commodities.
Product Type:
Image sensor fabrication concentrates in Taiwan and South Korea, creating divergent margin structures across hardware categories.
- IP Cameras:Network-enabled devices with 2MP to 8MP resolution and Power-over-Ethernet connectivity. Manufacturing corridor modernization in India's Gujarat and Tamil Nadu industrial zones is accelerating replacement of legacy analog infrastructure with these systems.
- Video Management Software:Centralized platforms for multi-camera feed aggregation, storage orchestration, and user permission management. Mid-market buyers in Southeast Asian smart city tenders are selecting these solutions for subscription flexibility over capital-intensive NVR procurement.
- Analog Cameras:Coaxial-cable systems with limited resolution scalability and no native analytics capability. Remaining demand concentrates in price-sensitive small commercial installations where infrastructure replacement costs deter IP migration.
- NVR Systems:Dedicated hardware appliances for local video storage and playback management. Critical infrastructure operators in Germany and France specify these for air-gapped deployments meeting GDPR data residency requirements.
Today's leader: IP Cameras. Tomorrow's challenger: Video Management Software.
Deployment Model:
Cost tier stratification separates enterprise capital budgets from mid-market operational expenditure preferences.
- Cloud-based:VSaaS delivery eliminating on-site server infrastructure through subscription pricing. US commercial real estate and Middle Eastern hospitality developments are adopting these models under facility management outsourcing contracts.
- Hybrid:Architectures combining local edge storage with cloud analytics and remote management. EU AI Act compliance requirements are pulling healthcare systems in France and the Netherlands toward these configurations for biometric data control.
- On-premises:Fully localized infrastructure with no external data transmission. China's MIIT cybersecurity review mandates this model for critical infrastructure operators under GB standards data residency rules.
- Managed Services:Third-party operation of surveillance infrastructure under long-term service agreements. Thailand and Indonesia smart city authorities are bundling these into urban digitalization tenders.
Cloud-based configurations are climbing the fastest among deployment options. On-premises retains dominance in regulated critical infrastructure.
End User:
Application-specific compliance requirements reshape feature prioritization across vertical procurement.
- Healthcare:Integrated platforms unifying patient flow monitoring with access control and HIPAA-compliant audit trails. Hospital systems in Germany and the Netherlands demand anonymization-by-design architectures under EU AI Act risk classifications.
- Government:Multi-thousand-camera networked systems for urban monitoring and public safety. Bangkok, Jakarta, and Ho Chi Minh City procurement is accelerating density expansion across Southeast Asian smart city mandates.
- Retail:Loss prevention and customer behavior analytics with POS integration. Illinois and Texas biometric privacy laws are fragmenting compliance obligations for multi-national retail chains operating in the United States.
- Transportation:Real-time monitoring for passenger safety and infrastructure security. India's Dedicated Freight Corridor is deploying these systems for cargo tracking and perimeter protection.
Healthcare integration requirements are expanding fastest. Government volume anchors current procurement value.
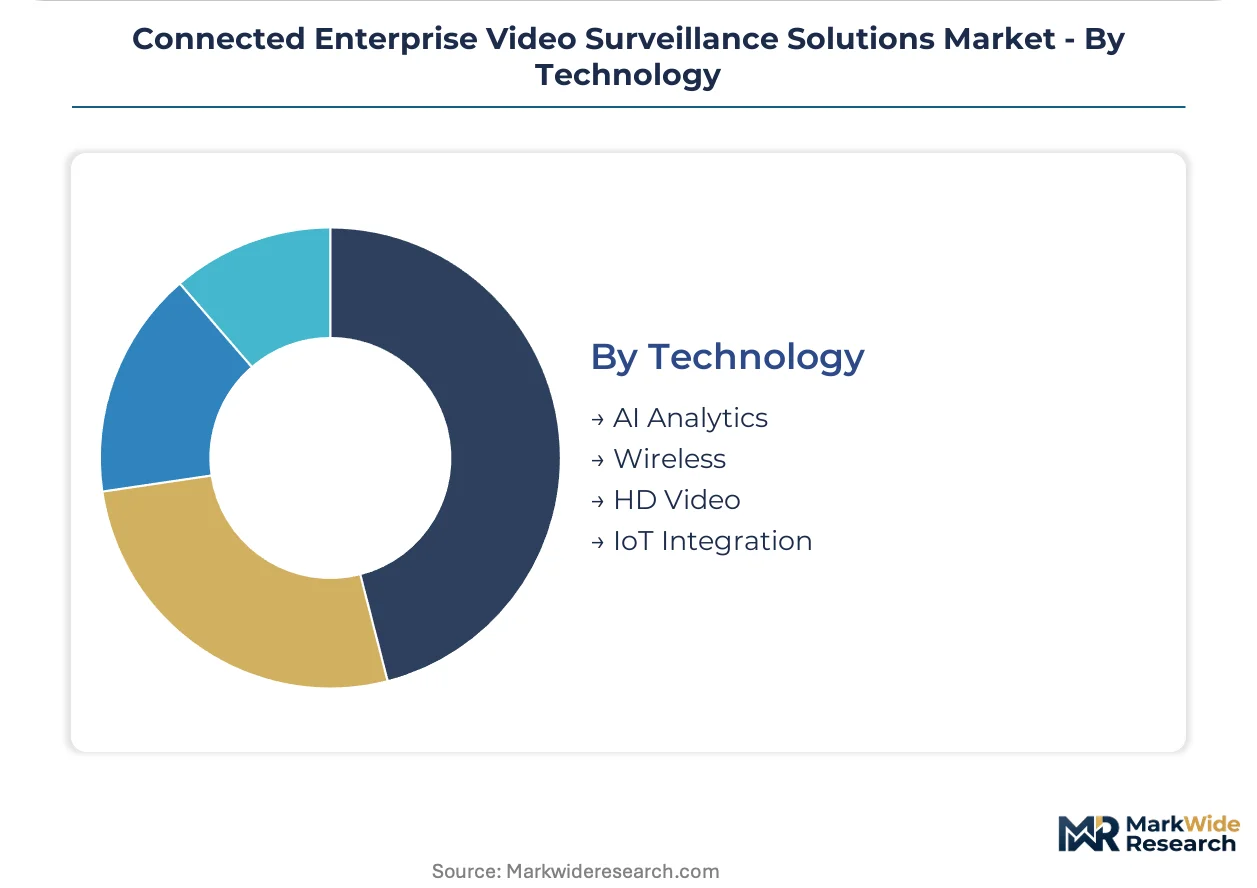
Technology:
Maturity gradients separate established video capture standards from emerging inference capabilities.
- AI Analytics:Behavioral recognition and anomaly detection algorithms enabling predictive alerts. Qualcomm and Ambarella on-camera inference chips are enabling GDPR-compliant European contracts without cloud dependency.
- HD Video:High-definition capture standards from 1080p through 4K resolution. Automotive plants in Germany and electronics assembly lines in South Korea are piloting thermal-overlay variants for equipment failure prediction.
- Wireless:Wi-Fi and cellular transmission eliminating structured cabling requirements. Deployment concentrates in retrofit scenarios where conduit installation is prohibitively disruptive.
- IoT Integration:API connectivity with access control, HVAC, and building automation platforms. Honeywell and Johnson Controls are capturing this demand through bundled facility management contracts.
AI Analytics commands premium positioning. IoT Integration represents the steepest expansion trajectory as building automation consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps are redistributing procurement patterns across jurisdictions, with EU AI Act enforcement pushing some analytics workloads toward jurisdictions with lighter biometric processing restrictions while manufacturing-driven demand concentrates in corridors with infrastructure modernization mandates.
United States
Critical infrastructure operators and commercial real estate developers drive enterprise camera density expansion. FCC equipment authorization requirements and Illinois BIPA biometric privacy laws fragment compliance obligations for multi-state deployments. Data center clusters in Northern Virginia and Dallas-Fort Worth anchor demand for perimeter surveillance with edge analytics.
Germany
Automotive plants and precision manufacturing facilities deploy thermal-overlay cameras for predictive maintenance beyond security applications. GDPR and EU AI Act risk-classification frameworks mandate anonymization-by-design architectures for behavioral recognition systems. Industrial zones in Bavaria and Baden-Württemberg lead facility security modernization programs.
China
MIIT cybersecurity review and GB standards enforce local data residency for critical infrastructure operators, creating divergent product roadmaps from Western markets. Smart city density in Yangtze River Delta and Pearl River Delta metropolitan clusters sustains multi-thousand-camera procurement volumes. Domestic vendors capture public sector tenders through compliance alignment.
India
Manufacturing corridor modernization along the Dedicated Freight Corridor and industrial zones in Gujarat and Tamil Nadu accelerates analog-to-IP infrastructure replacement. PLI scheme incentives for electronics manufacturing attract component assembly investments supporting camera OEM supply chains. Facility security upgrades outpace legacy system maintenance spending.
Indonesia
Urban digitalization mandates in Jakarta and Surabaya bundle video surveillance into smart city infrastructure tenders with managed service components. Government procurement prioritizes networked camera density for public safety applications. Mid-market subscription models penetrate buyers previously excluded by capital-intensive NVR requirements.
Connected Enterprise Video Surveillance Solutions Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing facility management outsourcing contracts while component-focused suppliers serve price-sensitive tender markets. The vendor base organizes around three archetypes: sensor-integrated hardware specialists, software-centric analytics platforms, and building-automation bundlers. Capacity expansion in edge-AI chipsets and strategic partnerships between camera OEMs and semiconductor foundries represent dominant competitive moves.
Among Asia-Pacific hardware specialists, Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. occupy positions exemplifying vertically integrated manufacturing scale, while Bosch Security Systems represents European-engineered edge-computing differentiation. Honeywell International Inc. anchors the building-automation integration archetype, bundling surveillance modules within broader facility management contracts to capture commercial real estate and hospitality procurement.
| Leading Market Players |
|---|
| Hikvision Digital Technology Co., Ltd. |
| Bosch Security Systems |
| Honeywell International Inc. |
| Axis Communications AB |
| Hanwha Techwin Co., Ltd. |
| Motorola Solutions, Inc. |
| Dahua Technology Co., Ltd. |
| Genetec Inc. |
| VIVOTEK Inc. |
| Others |
Value Chain & Pricing Dynamics
Smart city procurement authorities in Southeast Asia anchor pricing power through multi-thousand-camera tenders that reward volume-scaled unit economics. Subscription-based VSaaS models are compressing upfront project margins while expanding lifetime value capture through recurring software licensing.
Pricing Analysis
Distributor margins in the mid-market channel layer compress pricing by 15-25 points before systems reach facility management contractors. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered edge-AI cameras from Asia-Pacific OEM offerings and white-label alternatives. Cost compression in the analog replacement tier intensifies because India's manufacturing corridor buyers prioritize capex minimization over analytics capability. Government procurement teams exhibit lowest price sensitivity due to compliance documentation requirements, while small commercial installers in Indonesia remain most elastic.
Supply Chain Analysis
Engineering talent scarcity in Taiwan and South Korea constrains image sensor foundry expansion despite capacity investment announcements. Semiconductor fabrication draws from 300mm wafer supply concentrated in Hsinchu and Pyeongtaek, with specialized optical lens assembly tethered to Chinese coastal manufacturing zones. Single-source vulnerability runs through Sony and OmniVision sensor supply allocations to tier-one camera OEMs. Distribution runs through regional systems integrators who bundle installation with hardware procurement for enterprise end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected enterprise video surveillance market compounds steadily as regulatory mandates across the EU, China, and US force infrastructure refresh cycles regardless of economic cyclicality.
For Market Incumbents: Anchor market position through backward integration into edge-AI chip supply from Qualcomm and Ambarella, securing allocation priority during semiconductor supply shocks. Deepen certification investment for EU AI Act anonymization-by-design architectures to defend against European software-centric entrants. Prioritize channel control via exclusive distribution agreements with building-automation integrators in US commercial real estate and Middle Eastern hospitality developments. For New Entrants and Emerging Players: Begin with healthcare facility management outsourcing contracts in France and the Netherlands, where HIPAA-equivalent compliance requirements create incumbent-switching friction for generalist security vendors. Target mid-market VSaaS penetration in Thailand and Indonesia smart city tenders, where subscription flexibility outweighs brand preference. Deploy direct-to-facility-manager sales motion bypassing traditional security distributor markups. For Investors and Strategic Acquirers: Building-automation conglomerates are the most active acquirer in this space, seeking video analytics capabilities to embed within HVAC and access control master agreements. Five-to-ten year viability rests on software licensing recurring revenue exceeding hardware depreciation cycles. Monitor ONVIF Profile T certification backlog as inflection indicator for ecosystem integration readiness among target acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chipset Partnership | Qualcomm and Ambarella inference silicon enables GDPR-compliant behavioral recognition without cloud dependency. |
| EU AI Act Compliance Certification | Anonymization-by-design documentation unlocks French and German healthcare procurement previously closed to biometric analytics. |
| VSaaS Platform Launch | Subscription pricing penetrates Indonesia and Thailand mid-market buyers excluded by capital-intensive NVR requirements. |
| Building-Automation Integration | Honeywell-style bundling with HVAC contracts captures US commercial real estate facility management outsourcing. |
| Manufacturing Corridor Localization | India PLI scheme incentives attract component assembly supporting Gujarat and Tamil Nadu facility security modernization. |
Study Parameters
Multiple input streams — primary interviews with security systems integrators, facility management procurement directors, and edge-AI semiconductor product managers; secondary validation through FCC equipment authorization databases, EU AI Act implementation guidance, and smart city tender documentation — were reconciled through bottom-up and top-down triangulation. Hospital purchasing committees in Germany and the Netherlands, plus government procurement officers in Bangkok and Jakarta, provided deployment-scale calibration. Customs records for image sensor trade flows and ONVIF certification registries supplied secondary anchor points.
Data-stream reconciliation across product type, deployment model, end-user vertical, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates cross-referenced with replacement cycle timing and software attach-rate assumptions. Edge-AI chipset availability timelines and GDPR compliance cost curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor foundry operations and unilateral biometric privacy legislation in additional US states beyond Illinois and Texas. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and supply chain normalization. Material deviation in EU AI Act penalty implementation or MIIT cybersecurity review expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
United States Surveillance IP Camera Market