
 AI CCTV Market | 2026-2036
AI CCTV Market Size, Share, and Industry Trends Forecast 2026-2036
AI CCTV Market Analysis
The EU AI Act is rebalancing procurement criteria for public surveillance systems across European cities, forcing vendors to demonstrate algorithmic transparency and bias mitigation. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor-to-cloud architecture to sustain cost leadership in high-volume municipal contracts. Bosch Security Systems differentiates through German-engineered cybersecurity certifications that anchor premium positioning in critical infrastructure segments. Axis Communications AB specializes in open-platform software development, competing on interoperability rather than proprietary lock-in.
AI CCTV denotes networked camera systems embedding machine learning inference engines at the edge or in centralized servers, typically processing video streams at 30 frames per second with resolutions from 2MP to 8MP for automated object classification and anomaly alerting. These systems serve commercial and governmental buyers seeking to replace passive recording with predictive security orchestration. Fixed cameras dominate volume shipments in retail and banking due to low per-unit cost and deterministic coverage patterns, while thermal cameras command margin premiums in perimeter defense and industrial fire-prevention applications. Cloud storage adoption is accelerating fastest among mid-tier hospitality and logistics operators lacking capital for on-premise server farms.
The U.S. FDA regulates biometric data collection in healthcare-adjacent surveillance settings, while the FCC governs wireless transmission protocols for outdoor IP surveillance networks. China's SAMR enforces GB standards for facial recognition accuracy and data retention limits that shape product roadmaps for domestic champions. Stakeholders must monitor divergent regulatory timelines for algorithmic auditing mandates, as compliance fragmentation threatens to bifurcate product architectures between privacy-stringent and permissive jurisdictions.
Market Dynamics
Edge AI chip miniaturization is compressing on-camera processing latency below 50 milliseconds, eliminating centralized server dependency for real-time threat detection and rewiring municipal procurement specifications toward distributed architectures.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in China, Singapore, and the UAE are embedding facial recognition-enabled surveillance into urban command centers, creating recurring hardware refresh cycles.
- EU AI Act compliance requirements:Algorithmic transparency and bias mitigation rules are forcing vendors to invest in explainable AI tooling, raising barriers for non-compliant suppliers and consolidating contract awards among certified providers.
- Thermal imaging convergence:Perimeter defense operators in critical infrastructure are integrating thermal sensors with AI analytics for fire-prevention and intrusion detection, expanding addressable use cases beyond visible-spectrum monitoring.
Market Restraints
- Sensor supply concentration:CMOS image sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing camera OEMs to geopolitical disruption and capacity allocation constraints.
- GDPR-derived data retention limits:European privacy frameworks cap storage durations for biometric footage, compressing recurring revenue from cloud archival services and forcing shorter hardware replacement cycles.
- Legacy analog infrastructure:Banking and retail segments in emerging markets retain coaxial cable deployments, delaying IP camera conversion and fragmenting addressable demand.
Strategic Opportunities
- Mid-tier hospitality cloud migration:Hotels and logistics operators lacking on-premise server capital are adopting subscription-based video management platforms, opening recurring revenue streams for platform vendors.
- Healthcare-adjacent biometric surveillance:FDA guidelines for patient monitoring systems are creating compliant product categories that bridge security and clinical observation functions.
- Industrial fire-prevention retrofit:Thermal AI cameras are penetrating manufacturing facilities for predictive maintenance, displacing standalone temperature sensors in high-risk chemical and energy processing environments.
Industry Challenges
- Algorithmic auditing talent scarcity:Compliance with EU AI Act and China's SAMR GB standards requires specialized machine learning engineers capable of documenting bias testing protocols, constraining vendor scaling velocity.
- Interoperability certification timelines:ONVIF and IEC 62676 conformance testing creates six-to-nine month product launch delays, compressing first-mover advantages in fast-moving municipal tenders.
- Cybersecurity hardening costs:German BSI and U.S. NIST frameworks mandate encrypted firmware and secure boot architectures, adding non-recurring engineering overhead that disadvantages price-competitive entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI CCTV Market |
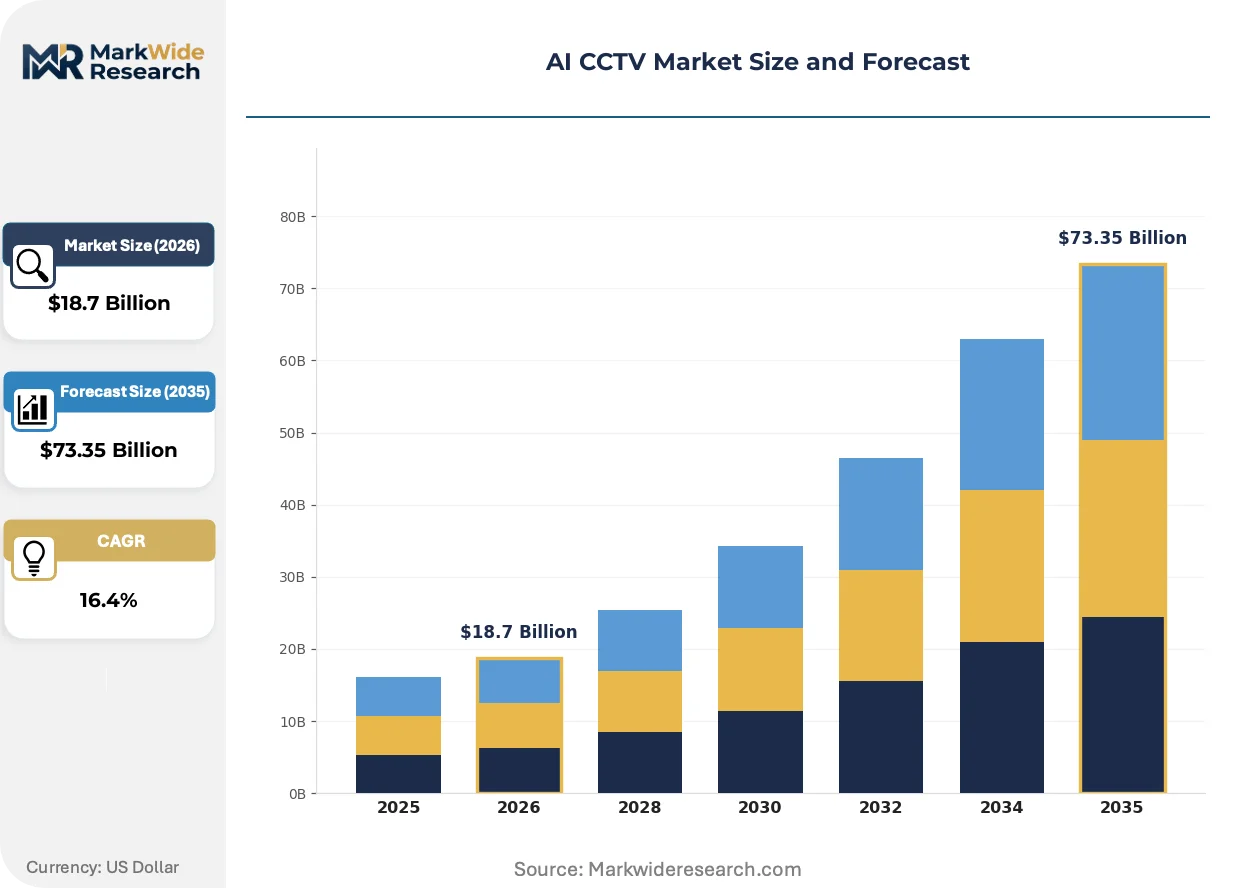
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
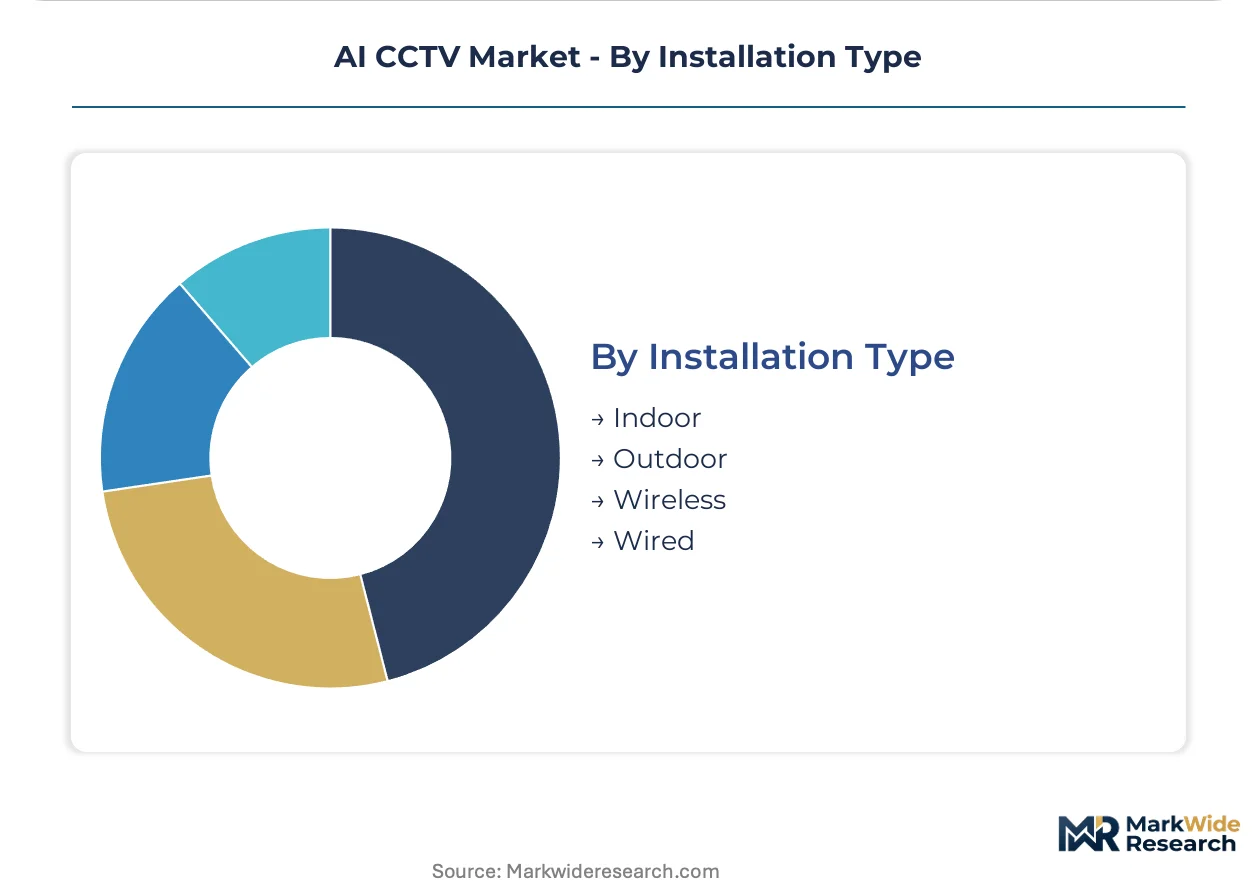
| Segmentation | Product Type: Fixed Cameras, PTZ Cameras, Thermal Cameras, Dome Cameras Technology: Image Recognition, Motion Detection, IP Surveillance, Cloud Storage End User: Retail, Transportation, Government, Hospitality Installation Type: Indoor, Outdoor, Wireless, Wired |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Bosch Security Systems, Axis Communications AB, Hanwha Vision, Avigilon Corporation, FLIR Systems, Panasonic Corporation, Uniview Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI CCTV Market Emerging Trajectories
Video analytics architectures are fragmenting from monolithic platforms into composable inference engines, enabling buyers to mix specialized algorithms without vendor lock-in and reshaping competitive differentiation toward software modularity rather than hardware specifications.
Neural processing units for computer vision are modularizing into swappable camera modules, allowing municipal operators to upgrade inference capabilities without replacing lens and sensor assemblies. Police departments and transportation authorities are piloting this approach to extend hardware lifecycles. The shift is compressing capital expenditure cycles while expanding recurring software licensing revenue for platform vendors.
China's SAMR enforcement of GB standards for facial recognition accuracy is mandating retraining of deployed models against domestic demographic datasets, forcing multinational vendors to maintain parallel algorithm versions. Industrial consequence includes bifurcated product roadmaps and duplicated validation costs. Domestic champions leverage regulatory alignment to accelerate municipal contract capture against foreign competitors facing compliance lag.
Buyer preference is rotating from perpetual-license video management software toward consumption-based analytics subscriptions, unbundling storage from intelligence layers. Mid-tier logistics and hospitality operators in Southeast Asia are driving this transition, prioritizing operational expenditure predictability over capital ownership. Channel partners are restructuring compensation around recurring revenue shares rather than hardware margin splits.
AI CCTV Market Segmentation
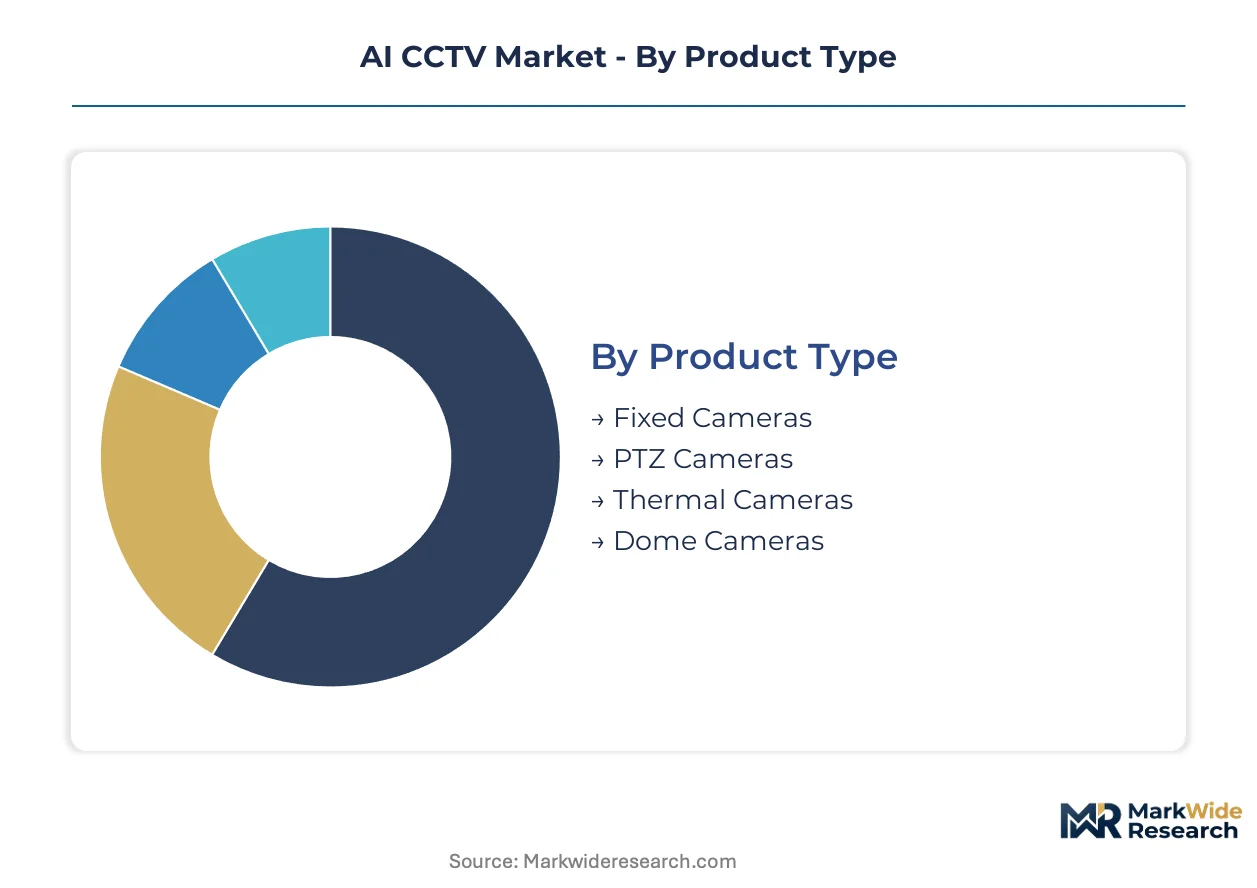
Segmentation in AI CCTV reveals how procurement priorities diverge across buyer archetypes. Municipal governments prioritize thermal imaging for perimeter defense, while retail chains optimize for fixed-camera density and cloud storage economics.
Product Type:
Buyers differentiate by coverage pattern requirements and environmental conditions rather than price alone.
- Fixed Cameras:Stationary units with deterministic field-of-view deliver lowest per-unit cost for banking and retail shelf monitoring. Demand concentrates in China's municipal contracts where Hikvision and Dahua compete on volume.
- Thermal Cameras:Infrared sensors detect heat signatures independent of visible light, enabling fire-prevention in chemical processing facilities and intrusion detection at critical infrastructure perimeters. Operators in the UAE and Saudi Arabia pay margin premiums for these capabilities in desert environments with extreme temperature differentials.
- PTZ Cameras:Pan-tilt-zoom mechanisms allow remote operator control over wide areas, serving transportation hubs requiring active surveillance.
- Dome Cameras:Vandal-resistant enclosures with 360-degree coverage protect against tampering in high-risk public spaces.
Volume sits with fixed cameras; growth tilts toward thermal cameras.
Technology:
Architecture choices determine latency, storage economics, and regulatory compliance burdens.
- Image Recognition:Convolutional neural networks classify objects within video frames at 30 frames per second, enabling facial identification and license plate reading. China's SAMR enforces GB standards accuracy thresholds that reshape model training for domestic deployment.
- Cloud Storage:Subscription-based video archival eliminates capital expenditure for on-premise server farms, accelerating adoption among mid-tier hospitality operators in Singapore and Thailand lacking IT infrastructure.
- Motion Detection:Pixel-change algorithms trigger recording only during activity, reducing bandwidth and storage requirements for low-traffic zones.
- IP Surveillance:Networked digital transmission replaces analog coaxial systems, though legacy banking infrastructure in India and Brazil delays conversion timelines.
Installed base favors motion detection; expansion runs through cloud storage.
End User:
Sector-specific risk profiles dictate feature prioritization and compliance frameworks.
- Government:Municipal command centers integrate facial recognition with urban management platforms, subject to EU AI Act algorithmic transparency mandates in European deployments.
- Retail:Loss prevention teams prioritize fixed-camera density and behavioral analytics for shoplifting detection.
- Transportation:Airports and rail networks require PTZ coverage with FCC-governed wireless transmission protocols for outdoor IP networks in the United States.
- Hospitality:Hotels balance guest privacy expectations against liability coverage, driving cloud-based solutions with shorter data retention cycles.
Procurement scale concentrates with government; hospitality climbs the fastest.
Installation Type:
Physical deployment constraints shape hardware specifications and total cost of ownership calculations.
- Outdoor:Weather-sealed enclosures with IP67 ratings withstand temperature extremes and moisture, commanding price premiums over indoor equivalents.
- Indoor:Controlled environments allow lighter enclosures and shorter cable runs, minimizing installation labor.
- Wireless:Wi-Fi and cellular backhaul eliminate trenching costs for remote perimeter locations, though FCC spectrum allocation affects reliability in the United States.
- Wired:Ethernet and fiber connections deliver guaranteed bandwidth for high-resolution streams in data-intensive applications.
Deployment volume favors indoor wired; outdoor wireless gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest concentration of AI CCTV manufacturing and municipal deployment, with facial recognition systems saturating urban command centers across the Pearl River Delta corridor.
China
Hangzhou and Shenzhen municipal governments are embedding edge AI cameras into smart city infrastructure at scale. SAMR enforces GB standards for facial recognition accuracy thresholds. The Yangtze River Delta corridor concentrates domestic champion manufacturing and export logistics.
United States
Transportation authorities in Chicago and Los Angeles are piloting thermal AI cameras for perimeter defense and intrusion detection. The FCC governs wireless transmission protocols for outdoor IP surveillance networks. Silicon Valley hosts the primary cluster of edge AI chip design firms supplying camera OEMs.
Germany
Industrial operators in the Ruhr region are deploying thermal AI systems for predictive maintenance and fire prevention in chemical processing facilities. The BSI mandates encrypted firmware and secure boot architectures for critical infrastructure certification. Bavaria hosts precision engineering clusters supplying cybersecurity-hardened camera enclosures.
United Arab Emirates
Dubai and Abu Dhabi municipal command centers are procuring facial recognition-enabled surveillance for urban management platforms. MOHAP coordinates data governance frameworks for biometric collection in healthcare-adjacent settings. Desert climate conditions command margin premiums for thermal imaging capabilities.
Singapore
Mid-tier hospitality operators are accelerating cloud storage adoption for video management platforms lacking on-premise server capital. The Personal Data Protection Commission shapes retention limits for biometric footage. The city-state functions as a regional distribution hub for Southeast Asian procurement networks.
AI CCTV Market Vendor Landscape
Premium-margin players sit above commodity-margin players across cybersecurity certification and algorithmic transparency dimensions. The vendor base stratifies into three tiers: domestic champions with vertically integrated sensor-to-cloud architectures, European specialists competing on interoperability and regulatory compliance, and scale-driven Asian manufacturers optimizing for municipal volume contracts. Two dominant competitive moves are reshaping positioning: modular neural processing unit upgrades that extend hardware lifecycles, and subscription-based analytics licensing that unbundles intelligence from storage layers.
Within the domestic champion tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. represent archetypal vertically integrated players with cost leadership in high-volume municipal contracts. Bosch Security Systems occupies a position exemplifying German-engineered cybersecurity certification for critical infrastructure premium positioning. Axis Communications AB anchors the open-platform interoperability segment, competing on software modularity rather than proprietary lock-in.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Bosch Security Systems |
| Axis Communications AB |
| Hanwha Vision |
| Avigilon Corporation |
| FLIR Systems |
| Panasonic Corporation |
| Uniview Technologies |
| Others |
Supply Flow & Price Mechanics
Machine learning engineer concentration in Shenzhen and Hangzhou compresses algorithmic auditing labor costs for domestic champions, widening pricing spreads between EU AI Act-compliant premium tiers and volume-oriented municipal contracts.
Pricing Analysis
Outcome-based pricing anchors municipal command center deployments, with contracts tied to incident detection throughput rather than camera counts. Three-tier pricing structure across premium, standard, and economy levels separates BSI-certified cybersecurity packages from basic edge AI configurations. Pricing pressure stems from cloud storage commoditization among mid-tier hospitality operators. Government buyers exhibit lowest price sensitivity; Southeast Asian logistics operators demonstrate highest.
Supply Chain Analysis
CMOS image sensor supply rests on Taiwanese and South Korean foundry capacity, with Sony and Samsung anchoring fabrication for 2MP to 8MP resolutions. Edge AI chip design draws from Silicon Valley and Shenzhen engineering clusters. Geopolitical disruption around Taiwan Strait logistics presents single-source vulnerability. Distribution runs through Shenzhen export hubs for Southeast Asian procurement networks and Dubai for Middle Eastern municipal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around algorithmic transparency compliance, with EU AI Act certification costs forcing sub-scale vendors toward exit or acquisition.
For Market Incumbents: Anticipate regulatory fragmentation by maintaining parallel model versions for GDPR-stringent and SAMR-aligned jurisdictions. Deepen backward integration into edge AI chip design to defend margin position against modular neural processing unit suppliers. Prioritize ONVIF conformance testing investment to compress six-to-nine month certification timelines.
For New Entrants and Emerging Players: Begin with mid-tier hospitality cloud migration in Thailand and Vietnam, where capital constraints favor subscription-based video management platforms. Target industrial fire-prevention retrofit segments in chemical processing facilities lacking thermal AI coverage. Pursue channel partnerships with regional systems integrators rather than direct municipal sales.
For Investors and Strategic Acquirers: Re-rating potential sits with open-platform software specialists given buyer preference rotation toward interoperability over proprietary lock-in. Long-term viability favors vendors with recurring analytics subscription revenue exceeding hardware attachment rates. Watch EU AI Act enforcement timelines as consolidation catalyst signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Neural Processing Unit Deployment | Extends hardware lifecycles for municipal operators while expanding software licensing revenue. |
| EU AI Act Compliance Certification | Creates procurement barriers that consolidate contract awards among algorithmic transparency leaders. |
| Cloud Storage Platform Migration | Captures recurring revenue from mid-tier hospitality operators lacking on-premise server capital. |
| Thermal Imaging Convergence | Penetrates perimeter defense and industrial fire-prevention applications beyond visible-spectrum monitoring. |
| Open-Platform Interoperability Investment | Differentiates against Hikvision and Dahua proprietary lock-in for European critical infrastructure. |
Methodological Framework
Document review covered customs trade databases, SEC filings from camera OEMs, and SAMR GB standard documentation, complemented by interviews with municipal procurement officers, edge AI chip design engineers, and channel distribution partners. Secondary validation drew from FCC spectrum allocation records, EU AI Act implementation guidance, and ONVIF conformance testing protocols. Bottom-up shipment estimates triangulated against top-down smart city infrastructure budget allocations.
Segment-level projections across product type, technology architecture, end-user sector, and installation environment fed into analytical framework spanning the projection horizon. CAGRs derived from regression against historical municipal contract award velocity and cloud storage adoption curves. Model inputs incorporated edge AI chip miniaturization timelines and thermal sensor cost curves.
Underlying measurement precision varies by segment; government procurement data carries tighter precision than emerging market hospitality estimates. Forecasts reflect assumptions around regulatory enforcement timelines and foundry capacity allocation. Geopolitical disruption, algorithmic auditing talent scarcity, and GDPR-derived data retention limit revisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
North America Crawler Camera System Market