
 Japan Surveillance Storage Market | 2026-2036
Japan Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Surveillance Storage Market Insights
Japan's Act on the Protection of Specially Designated Secrets is expanding the compliance burden for contractors handling classified surveillance data, forcing upgrades to encrypted, tamper-evident storage architectures. Toshiba Corporation leverages its vertically integrated NAND flash production to dominate enterprise-grade SSD deployments in defense-adjacent installations. Fujitsu sustains its position through proprietary data resilience software that integrates with legacy government IT backbones. NEC Corporation anchors municipal smart city projects in Tokyo and Fukuoka with edge-computing storage nodes designed for low-latency video analytics.
Japan surveillance storage encompasses disk arrays, solid-state modules, network video recorders, and cloud-resident repositories engineered to ingest, index, and preserve continuous video streams at throughput rates exceeding multiple gigabits per second. These systems employ RAID configurations, erasure coding, and wear-leveling algorithms to ensure data integrity across multi-year retention mandates typical of criminal evidence and infrastructure security applications. HDD configurations still occupy the bulk of petabyte-scale archives due to favorable cost-per-terabyte economics, while SSD segments lead in edge deployments where vibration tolerance and rapid random access prove decisive. IP-based technology installations outpace analog legacy systems as municipalities phase out coaxial infrastructure in favor of Power-over-Ethernet camera networks.
PMDA guidelines for pharmaceutical manufacturing facilities indirectly shape surveillance storage specifications through GMP-aligned audit trail requirements, while METI's cybersecurity framework for critical infrastructure imposes network segmentation and access logging standards on storage vendors. JIS standards for information security management systems further constrain product design, particularly for healthcare end users managing patient-visible camera feeds in clinical environments. Stakeholders must monitor how impending amendments to Japan's Personal Information Protection Act will redefine consent mechanisms for biometric data retention, as this will recalibrate storage tiering strategies and purge automation timelines across retail and transportation deployments.
Market Dynamics
METI's cybersecurity framework for critical infrastructure is compressing procurement cycles for encrypted storage architectures, forcing vendors to pre-certify systems before municipal smart city tenders close. This regulatory pressure is reshaping how defense contractors and transportation authorities evaluate petabyte-scale retention systems.
Growth Catalysts
- Smart city infrastructure mandates:Tokyo and Osaka municipal governments require edge-computing storage nodes for real-time facial recognition analytics in public transit hubs.
- Act on the Protection of Specially Designated Secrets:Defense contractors must deploy tamper-evident encrypted archives for classified surveillance data retention.
- Power-over-Ethernet camera networks:IP-based installations are displacing coaxial infrastructure, driving demand for network-attached storage with multi-gigabit throughput.
Market Restraints
- NAND flash supply concentration:Domestic production capacity constraints limit SSD availability for vibration-tolerant edge deployments.
- Energy cost volatility:Data center cooling expenses for petabyte-scale HDD farms strain municipal operating budgets in prefectures with aging grid infrastructure.
- JIS certification timelines:Information security management system approvals delay product launches by 8-14 months for healthcare storage vendors.
Strategic Opportunities
- Kyushu semiconductor corridor:Fukuoka's emerging fab cluster offers captive NAND supply for surveillance SSD production.
- Personal Information Protection Act amendments:Impending biometric data consent rules will automate purge workflows, creating demand for tiered storage with policy-driven deletion.
- Healthcare-retail convergence:Patient-visible camera systems in clinical environments require HIPAA-aligned audit trails that pharmaceutical manufacturers now specify for GMP compliance.
Industry Challenges
- Legacy IT backbone integration:Government agencies operate decades-old mainframe environments that resist API-based storage management protocols.
- Erasure coding expertise gap:Few systems engineers possess deep familiarity with distributed redundancy algorithms for multi-site disaster recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Surveillance Storage Market |
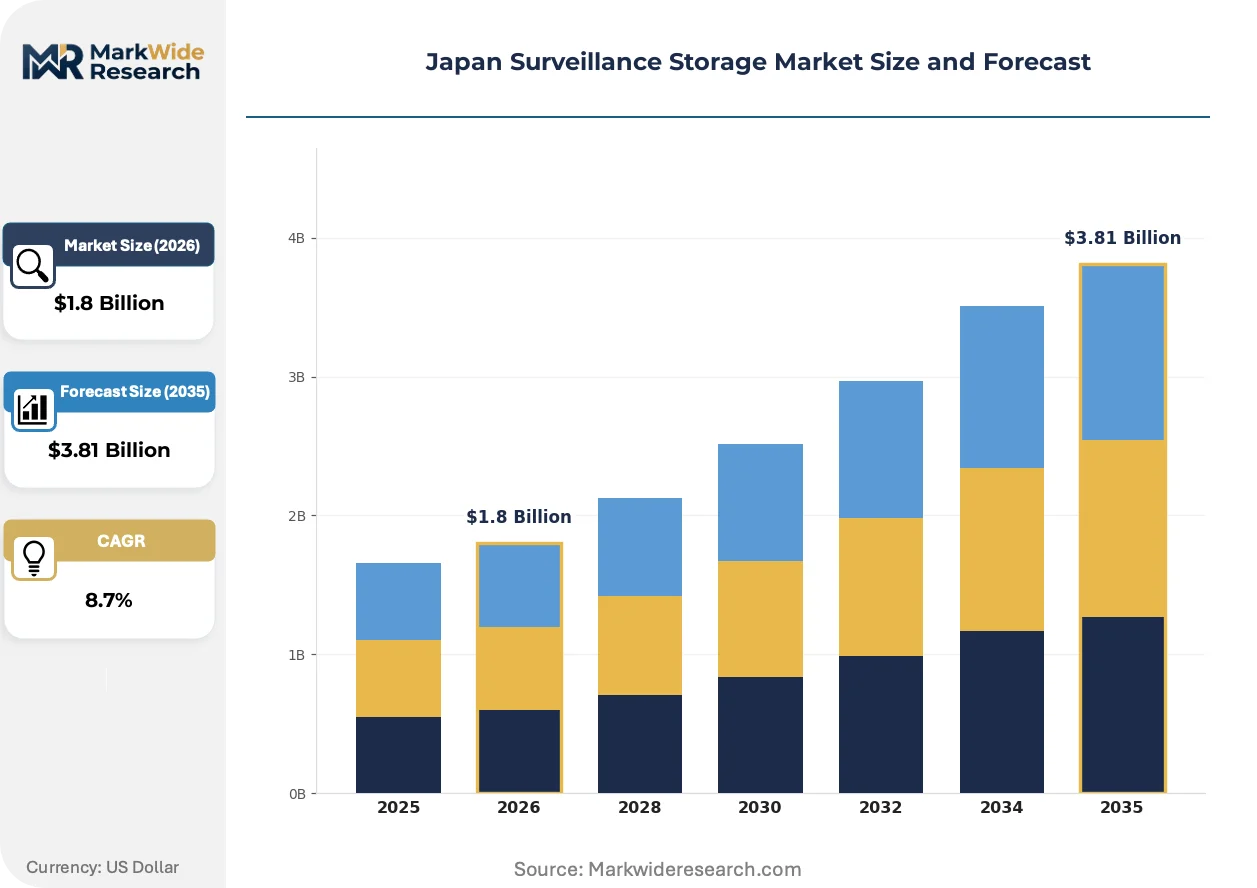
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NVR, HDD, SSD, Cloud Storage Technology: IP-based, Analog, Hybrid, Wireless End User: Retail, Government, Healthcare, Transportation Installation: On-premises, Hosted, Managed, DIY |
| Companies Covered | Hitachi, Ltd., Fujitsu, Toshiba Corporation, Axis Communications, Seagate Technology Holdings plc, NEC Corporation, Panasonic Holdings Corporation, Hikvision, Sony Group Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Surveillance Storage Market Trends and Innovations
Storage architectures are fragmenting between centralized petabyte archives and distributed edge nodes, with software-defined layers bridging the divide. Vendors now compete on data resilience algorithms rather than hardware specifications alone.
Computational storage drives with in-situ video analytics processing are unifying ingestion and indexing functions within the storage layer itself. Railway operators in Hokkaido and Kansai are piloting these modules for sub-second threat detection on rolling stock. This compression of the analytics pipeline is eliminating separate GPU server tiers at remote edge locations.
PMDA guidelines for pharmaceutical manufacturing facilities now mandate GMP-aligned audit trails that cascade into surveillance storage specifications. Facility operators must demonstrate tamper-proof retention of cleanroom monitoring footage for batch release decisions. Healthcare end users in Osaka and Tokyo are responding by pre-qualifying vendors against combined PMDA-JIS compliance checklists before tender submission.
Consumption patterns in municipal procurement are rotating from capital purchase toward performance-based service agreements. Prefecture governments in Chubu and Tohoku now specify uptime guarantees and retrieval latency SLAs rather than raw capacity. This shift is most visible in transportation authority tenders, where operating lease structures for storage infrastructure now outnumber outright equipment purchases by a widening margin.
Japan Surveillance Storage Market Segmentation
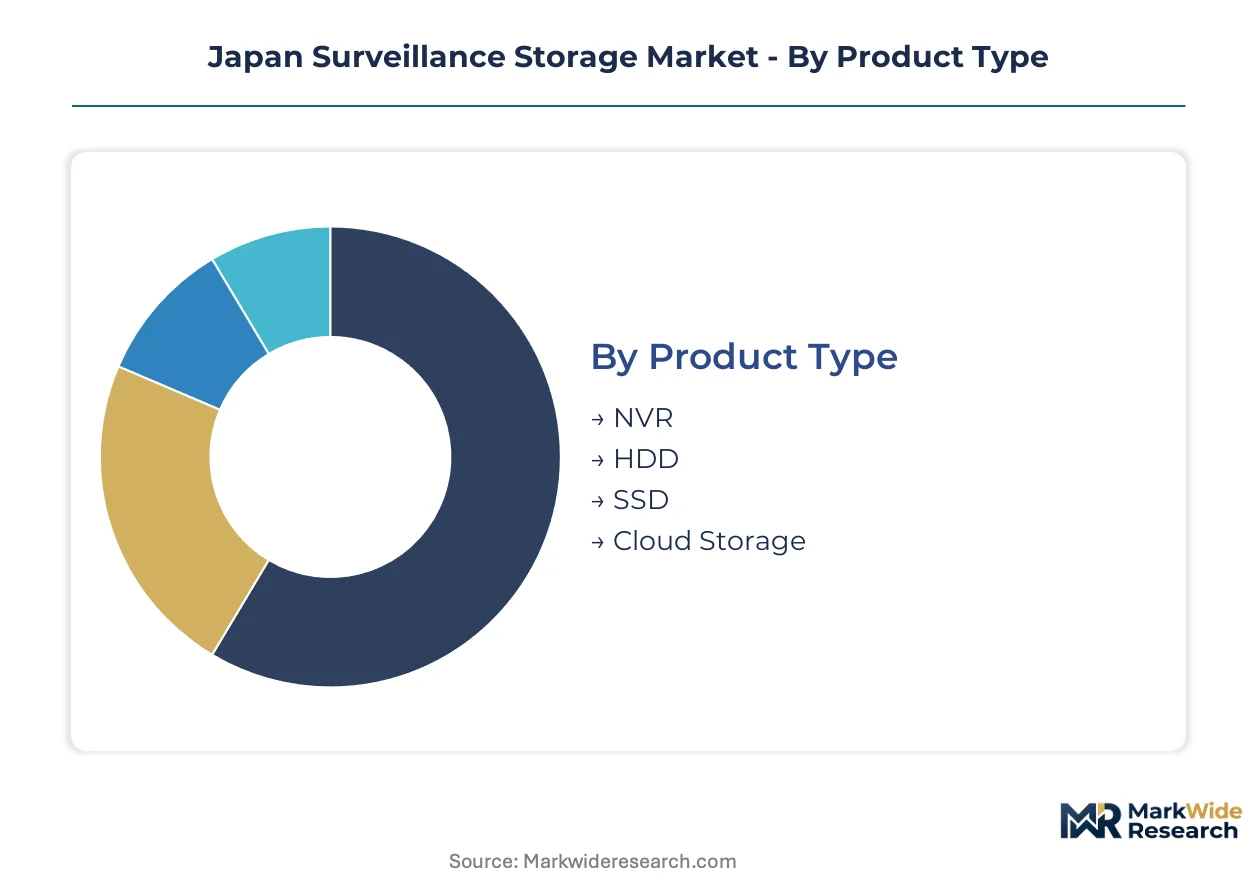
Japan's surveillance storage market fragments across hardware media, network protocols, vertical applications, and deployment models. Each dimension carries distinct capital requirements, compliance burdens, and integration complexity that shape vendor positioning and municipal procurement strategies.
Product Type:
HDD and SSD deployments demand the heaviest upfront capital outlays, driven by petabyte-scale capacity requirements and edge-computing node density in smart city infrastructure.
- NVR:Network video recorders consolidate encoding, storage, and playback functions in purpose-built appliances optimized for multi-channel camera ingestion. Municipal transportation authorities in Tokyo and Osaka specify NVR clusters for subway hub monitoring, where centralized management reduces field technician dispatch costs.
- HDD:Hard disk arrays dominate petabyte-scale archival installations through favorable cost-per-terabyte economics and proven longevity in continuous-write environments. Prefecture data centers operating under METI cybersecurity guidelines deploy RAID-configured HDD farms for multi-year evidence retention mandated by criminal procedure codes.
- SSD:Solid-state modules command premium positioning in vibration-intolerant edge locations and rapid-retrieval applications.
- Cloud Storage:Cloud-resident repositories enable consumption-based scaling for retail chains with seasonal surveillance intensity fluctuations.
HDD absorbs the bulk of installed capacity; SSD is expanding most quickly.
Technology:
IP-based and hybrid architectures concentrate deployment momentum where legacy coaxial infrastructure reaches end-of-life, while analog systems persist in budget-constrained rural municipalities.
- IP-based:Power-over-Ethernet camera networks transmit digital streams directly to network-attached storage, eliminating analog-to-digital conversion bottlenecks. Smart city tenders in Fukuoka and Sapporo mandate IP-native storage backbones for facial recognition analytics requiring uncompressed video fidelity.
- Analog:Coaxial-based systems survive in legacy government facilities where fiber retrofit costs exceed replacement timelines.
- Hybrid:Mixed analog-digital architectures bridge upgrade cycles for transportation authorities with phased camera refresh schedules.
- Wireless:Cellular and Wi-Fi backhaul configurations serve temporary surveillance deployments and remote infrastructure monitoring.
IP-based technology claims the dominant share of new procurements; hybrid configurations show steepest expansion trajectory in mid-tier municipal budgets.
End User:
Government and transportation verticals drive the largest contract values, while healthcare compliance requirements impose the most stringent certification overhead on storage vendors.
- Government:Defense contractors and intelligence agencies operate under Act on the Protection of Specially Designated Secrets mandates requiring tamper-evident encrypted archives with multi-site redundancy. These installations specify FIPS-aligned modules and air-gapped backup tiers that extend procurement cycles.
- Transportation:Railway operators and airport authorities demand edge-computing storage nodes with sub-second retrieval for real-time threat detection on rolling stock and passenger concourses. Hokkaido and Kansai operators pilot computational storage drives that unify ingestion and analytics processing.
- Retail:Convenience chains and department stores deploy tiered storage with automated purge workflows aligned to Personal Information Protection Act biometric consent requirements.
- Healthcare:Pharmaceutical manufacturers specify PMDA-aligned audit trail capabilities for cleanroom monitoring footage supporting batch release decisions.
Government verticals absorb the bulk of installed capacity; healthcare is climbing the fastest as GMP compliance cascades into surveillance specifications.
Installation:
On-premises and managed service models concentrate in critical infrastructure where data sovereignty and latency constraints outweigh cloud economics.
- On-premises:Dedicated storage infrastructure within facility boundaries satisfies METI cybersecurity framework network segmentation requirements for critical infrastructure operators. Defense-adjacent contractors reject off-premise alternatives for classified surveillance data.
- Managed:Third-party operated storage with uptime guarantees and retrieval latency SLAs is displacing capital purchases in Chubu and Tohoku prefecture tenders. Transportation authorities favor operating lease structures that transfer obsolescence risk to vendors.
- Hosted:Colocation arrangements serve mid-tier retailers seeking geographic redundancy without self-managed data center investments.
- DIY:Self-installed configurations persist in small commercial deployments with limited channel counts and minimal compliance exposure.
On-premises installations retain the dominant footprint; managed services are gaining share fastest as municipal procurement rotates toward performance-based agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's special economic zones for data infrastructure concentrate petabyte-scale storage investments across Tokyo and surrounding prefectures. METI's cybersecurity framework for critical infrastructure directs procurement toward encrypted, air-gapped archives in these designated technology corridors.
Kanto
Tokyo Metropolitan Government's smart city tenders mandate edge-computing storage nodes with sub-second retrieval for facial recognition analytics in Shinjuku and Shibuya transit hubs. The Act on the Protection of Specially Designated Secrets compels defense contractors in the region to deploy tamper-evident encrypted archives. Yokohama's Kanagawa Science Park hosts clustered HDD farms serving multi-year evidence retention for prefecture data centers.
Kansai
Osaka's municipal infrastructure projects require high-capacity storage systems for real-time threat detection across subway and rail networks. METI guidelines for critical infrastructure impose network segmentation standards on storage deployments in the prefecture. Kyoto's pharmaceutical corridor applies PMDA-aligned audit trail specifications to surveillance storage for cleanroom monitoring footage.
Chubu
Nagoya's transportation authorities favor managed service agreements with uptime guarantees over capital purchases for storage infrastructure. The region's prefecture governments specify retrieval latency SLAs rather than raw capacity in tenders. Toyota's surrounding industrial cluster generates demand for vibration-tolerant SSD modules in manufacturing facility surveillance.
Kyushu
Fukuoka's emerging semiconductor fab cluster offers captive NAND supply for surveillance SSD production targeting edge deployments. Municipal smart city projects in the city specify low-latency video analytics storage for public safety applications. Kumamoto's industrial parks attract storage vendors seeking proximity to upstream flash memory production.
Hokkaido
Railway operators across the northern island pilot computational storage drives unifying ingestion and analytics processing for rolling stock surveillance. JIS certification requirements for information security management systems delay product launches for healthcare storage vendors in Sapporo. The region's harsh climate conditions favor SSD deployments over HDD arrays in remote infrastructure monitoring.
Japan Surveillance Storage Market Competitive Landscape
Japanese producers anchor the domestic tier; international specialists hold positions in component supply and specialized analytics hardware. The vendor base splits between vertically integrated domestic conglomerates and focused technology providers from neighboring Asian markets and Western economies. Three archetypes dominate: NAND flash-integrated domestic manufacturers, software-resilience specialists, and edge-computing node designers. Capacity expansion in Kyushu's semiconductor corridor and strategic partnerships for international technology licensing represent the primary competitive vectors reshaping positioning.
Within the domestic integrated tier, Toshiba Corporation exemplifies captive supply chain control through its NAND flash production operations. Fujitsu occupies a position emphasizing proprietary data resilience software for legacy government IT environments. NEC Corporation represents the edge-computing specialization archetype through its municipal smart city project engagements in Tokyo and Fukuoka.
| Leading Market Players |
|---|
| Hitachi, Ltd. |
| Fujitsu |
| Toshiba Corporation |
| Axis Communications |
| Seagate Technology Holdings plc |
| NEC Corporation |
| Panasonic Holdings Corporation |
| Hikvision |
| Sony Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Power-over-Ethernet camera network rollouts across Tokyo and Osaka municipal transit systems simultaneously compress hardware procurement costs and concentrate NAND flash demand among domestic producers with captive fabrication capacity. This technology transition rewards vendors with backward integration into upstream memory production while penalizing pure-play assemblers exposed to spot-market component volatility.
Pricing Analysis
Short lead-time premiums of 15-25% apply to encrypted storage systems pre-certified under METI cybersecurity guidelines, while spot inventory of non-compliant HDD arrays trades at depressed levels. Three-tier pricing structure across premium, standard, and economy levels separates FIPS-aligned defense contractor installations from municipal transportation deployments and small commercial DIY configurations. Pricing pressure stems from municipal budget constraints in prefectures with aging electrical infrastructure facing elevated data center cooling costs. Transportation authorities exhibit highest price sensitivity due to operating lease migration, while defense-adjacent contractors absorb premiums for air-gapped, tamper-evident architectures mandated by the Act on the Protection of Specially Designated Secrets.
Supply Chain Analysis
Specialized cleanroom technicians and semiconductor process engineers remain scarce in Kyushu's emerging Fukuoka fab cluster, constraining captive NAND supply expansion for surveillance SSD production. Manufacturing concentrates in Japan, South Korea, and Taiwan, with raw material dependencies spanning silicon wafers, rare earth elements for magnet assemblies, and specialized epoxy resins for PCB encapsulation. Single-source vulnerability in advanced lithography equipment creates supply chain risk for sub-15nm flash memory nodes. Distribution runs through authorized systems integrators serving government and critical infrastructure verticals, with direct OEM relationships dominating high-volume municipal tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
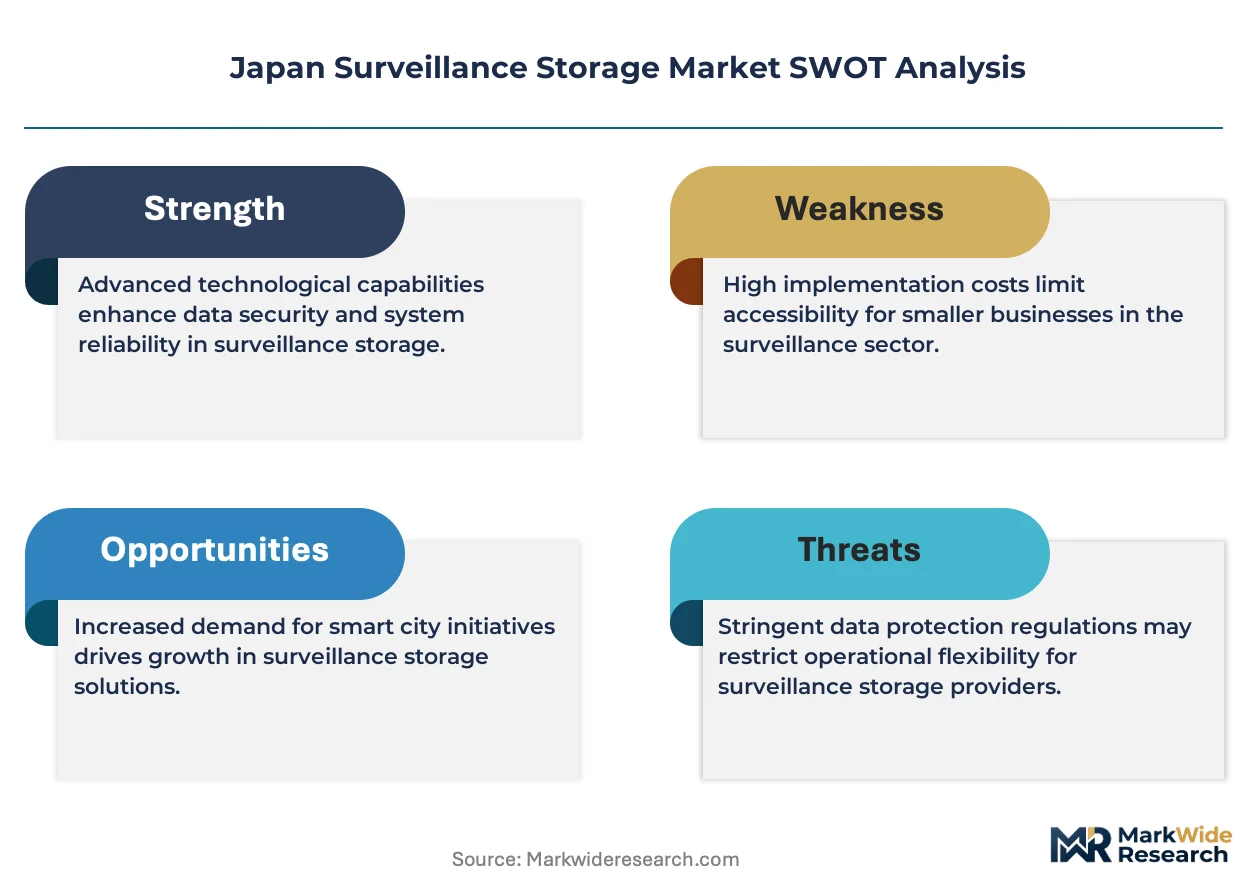
Japan's surveillance storage market functions as a cost-of-compliance arena where METI cybersecurity framework certification creates a barrier-to-entry moat that rewards pre-qualified incumbents and excludes speculative entrants lacking regulatory patience capital.
For Market Incumbents: To counter computational storage drive substitution by railway operators in Hokkaido and Kansai, accelerate firmware development for in-situ video analytics processing and secure JIS information security management system pre-approval for healthcare-facing product lines. Backward integration into NAND flash supply through Kyushu corridor partnerships or captive fab offtake agreements secures margin protection against spot-market volatility. For New Entrants and Emerging Players: Municipal smart city project system integrators represent the most accessible channel for unproven vendors, particularly in Chubu and Tohoku prefectures where managed service procurement models reduce capital barrier to trial. Target mid-tier transportation authorities with hybrid analog-digital upgrade cycles, offering phased migration financing and retrieval latency SLAs that incumbent hardware vendors rarely underwrite. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to domestic conglomerates seeking software-resilience capabilities for legacy government IT integration. Long-term viability hinges on regulatory certification durability rather than raw capacity economics. Watch for amendments to Japan's Personal Information Protection Act governing biometric data retention as the signal for tiered storage automation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Storage Drive Development | Unifies ingestion and analytics processing for Hokkaido railway threat detection pilots. |
| METI Cybersecurity Pre-Certification | Compresses municipal procurement cycles and excludes non-compliant vendors from Tokyo tenders. |
| Kyushu NAND Supply Partnership | Captures captive flash memory production from Fukuoka's emerging semiconductor corridor. |
| JIS Information Security Certification | Enables healthcare storage product launches in Osaka and Tokyo clinical environments. |
| Managed Service Operating Lease Structure | Aligns with Chubu and Tohoku prefecture procurement rotation toward performance-based agreements. |
Research Methodology
Independent corroboration across storage systems procurement officers at municipal transportation authorities, cybersecurity compliance leads at defense contractors, and technical directors at pharmaceutical manufacturing facilities underwrites the qualitative findings. Secondary validation drew from METI policy circulars, JIS standards documentation, PMDA GMP inspection records, and prefecture government tender disclosures. Bottom-up capacity estimates from NAND flash production facilities triangulate against top-down surveillance camera deployment statistics across Japan's designated smart city zones.
Comparable-period anchoring to historical municipal procurement cycles and defense infrastructure refresh timelines established the forecast window baseline. The analytical framework segments across hardware media, network protocol architecture, vertical application, and deployment model dimensions throughout the projection horizon. CAGRs derive from installed base evolution curves adjusted for technology substitution rates between HDD archival and SSD edge deployments. Forecast inputs incorporate METI cybersecurity framework amendment schedules and anticipated Personal Information Protection Act biometric consent rulemakings.
Caveats apply where NAND flash supply disruptions, energy cost volatility affecting prefecture data center operations, or accelerated legacy IT backbone replacement timelines could materially shift the outlook. Forecasts embed assumptions regarding regulatory implementation pacing and municipal budget continuity that warrant monitoring. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Security Camera Software Market