
 Germany Surveillance Analog Camera Market | 2026-2036
Germany Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Surveillance Analog Camera Market Insights
IP67-rated outdoor specification tiers is redrawing procurement priorities among German municipal buyers. Bosch Security Systems Incorporated leverages its Stuttgart engineering base to dominate ruggedized analog enclosures for rail and traffic applications. Dahua Technology Co Ltd anchors its position through deep distribution partnerships with German systems integrators serving mid-tier commercial accounts. Axis Communications AB specializes in bridging analog-to-digital migration pathways, sustaining relevance as customers phase infrastructure gradually.
Germany surveillance analog cameras capture continuous video signals through coaxial cable transmission without digital encoding, typically operating at 700 TVL to 960H resolution with PAL signal format standardized for European broadcast compatibility. Dome cameras and bullet cameras occupy distinct installation niches, with dome formats commanding premium positioning in retail and banking environments where vandal resistance and discreet positioning matter. Outdoor installation types generate higher replacement velocity as weathering degrades coaxial connectors and housing seals faster than indoor equivalents.
Germany's Federal Data Protection Commissioner and BSI (Federal Office for Information Security) enforce strict data handling protocols that limit cloud-connected analog deployments, preserving on-premise storage architectures. KBA guidelines for traffic monitoring infrastructure mandate minimum image retention periods that analog systems satisfy cost-effectively. Stakeholders must weigh BDSG compliance costs against the capital avoidance of full IP migration when evaluating refresh cycles for existing coaxial plant.
Market Dynamics
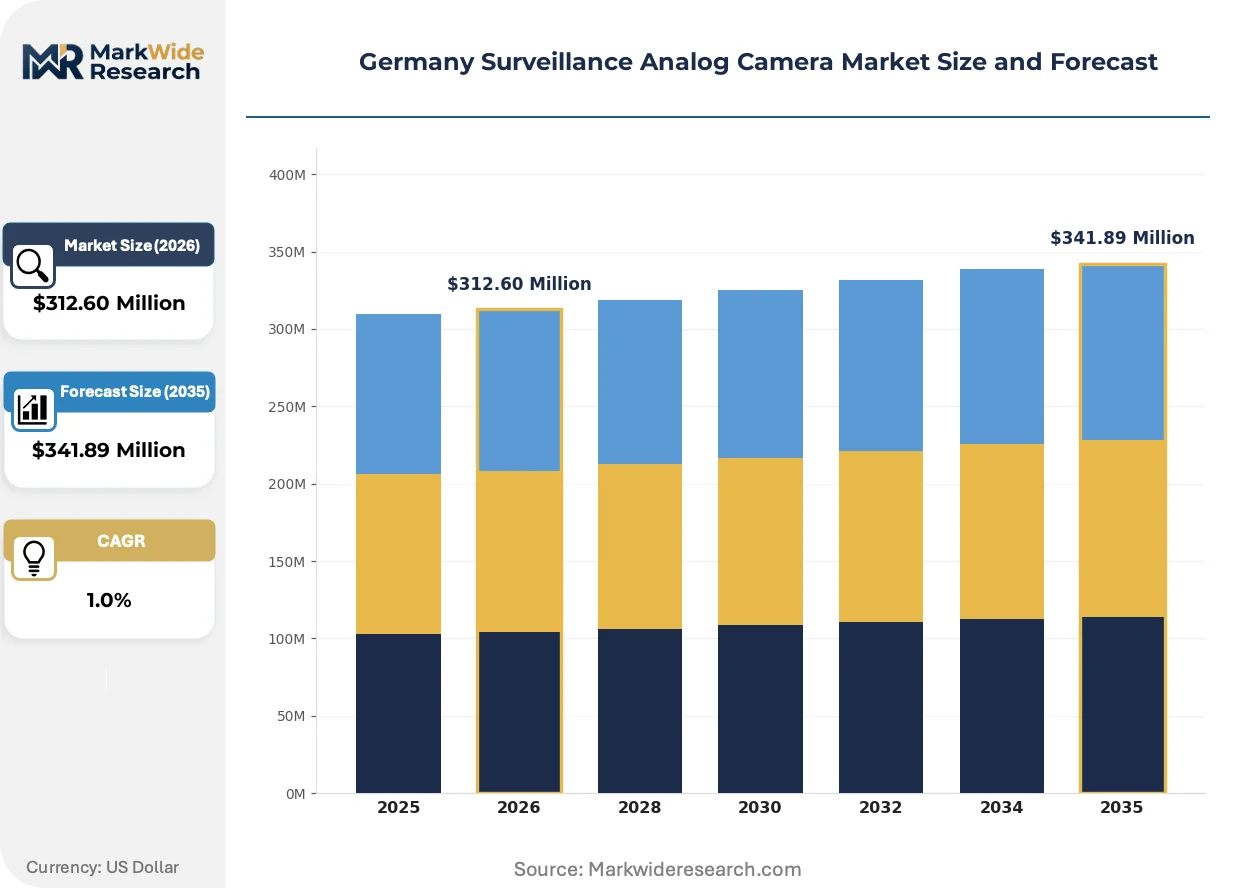
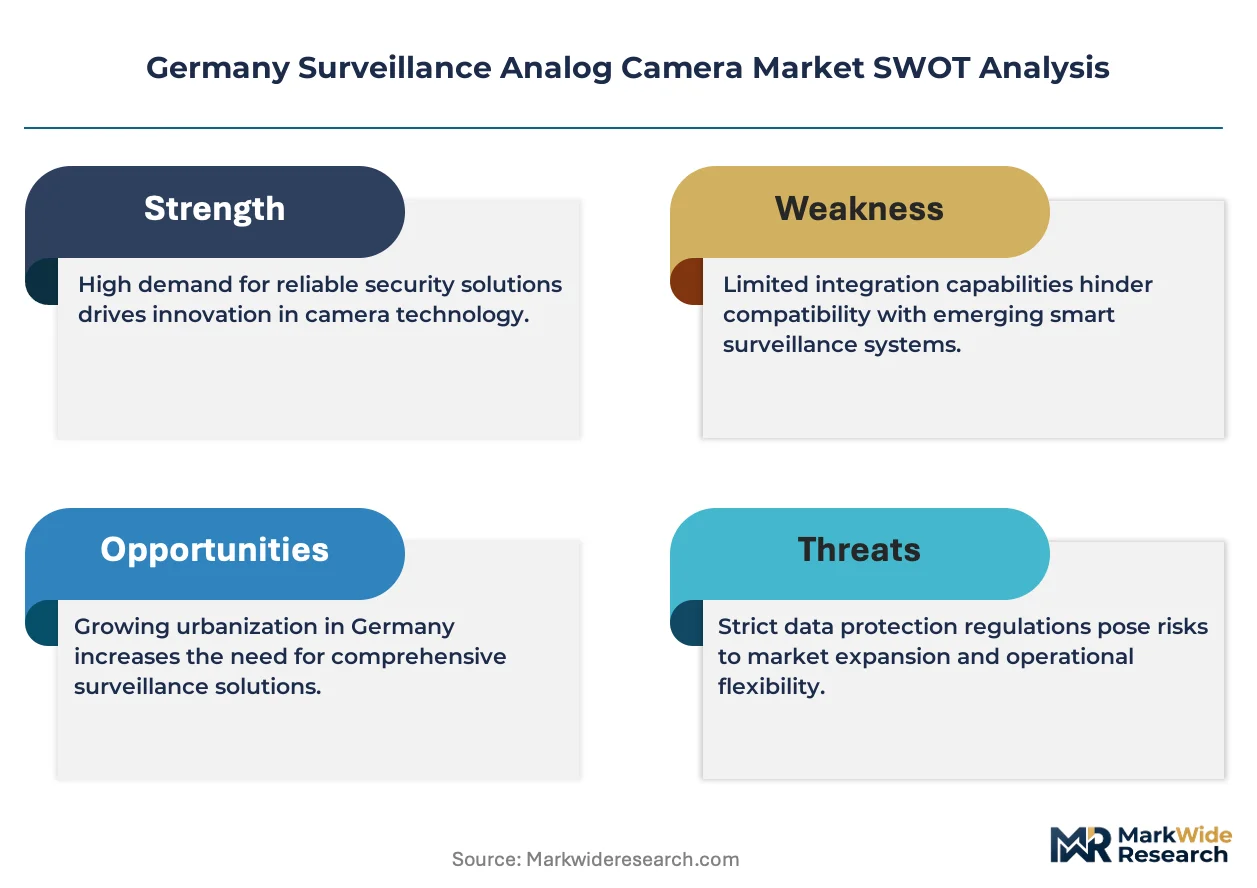
The Germany surveillance analog camera market navigates a forced transition between legacy coaxial infrastructure and IP-based alternatives, with BDSG compliance costs and hybrid migration pathways defining capital allocation decisions for municipal and industrial buyers.
Growth Catalysts
- KBA traffic monitoring mandates:Federal guidelines for road infrastructure require minimum image retention periods that analog systems fulfill at lower total cost of ownership than full IP replacements.
- Industrial zone hybrid architectures:Manufacturing facilities across North Rhine-Westphalia and Bavaria maintain analog-digital coexistence to protect sunk coaxial plant investments while adding selective IP capabilities.
- Municipal infrastructure refresh cycles:City operators face mounting pressure to upgrade aging surveillance networks without triggering full-scale fiber reconstructions.
Market Restraints
- Copper and coaxial cable input volatility:Raw material cost swings for shielded cable assemblies compress margin predictability for enclosure manufacturers.
- BSI data handling protocols:Strict federal information security requirements limit cloud-connected analog deployments, constraining remote management feature development.
- IP camera substitution acceleration:Declining unit costs for networked alternatives erode the total-cost advantage of analog refreshes in greenfield installations.
Strategic Opportunities
- Rail and traffic ruggedization demand:Stuttgart-centered engineering capabilities position domestic suppliers for Deutsche Bahn platform and station upgrades requiring IP67-rated outdoor housings.
- Retail banking vandal-resistant dome segment:Discreet positioning requirements in branch security create sustained demand for specialized analog form factors during phased migrations.
- Systems integrator channel consolidation:Deep distribution partnerships with mid-tier commercial integrators offer pathway to capture fragmented municipal procurement.
Industry Challenges
- Coaxial-to-Ethernet skill transition:Installation and maintenance workforce lacks parallel competency in both legacy PAL signal troubleshooting and IP configuration protocols.
- BDSG compliance documentation burden:Data protection impact assessments for analog deployments impose administrative overhead that elongates sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Surveillance Analog Camera Market |
| Market Size in 2026 | $312.60 Million |
| Market Size in 2035 | $341.89 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, C-mount Cameras Installation Type: Indoor, Outdoor, In-ceiling, Wall-mounted Technology: Analog, HD-CVI, HD-TVI, AHD End User: Retail, Government, Transportation, Education |
| Companies Covered | Bosch Security Systems Incorporated, Dahua Technology Co Ltd, Hangzhou Hikvision Digital Technology Co Ltd, Panasonic Corporation, Johnson Controls Inc, Axis Communications AB, Honeywell Security Group, Hanwha Vision Co Ltd, FLIR Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Surveillance Analog Camera Market Trends and Innovations
Technology convergence and regulatory recalibration are compressing the operational lifespan of pure analog architectures while opening hybrid migration pathways. Buyers increasingly prioritize enclosure durability and signal bridging capabilities over resolution specifications.
HD-over-coax signal transmission is supplanting traditional composite video in retrofit applications. Municipal traffic departments and industrial security managers adopt TVI and CVI formats to extract 1080p resolution from existing cable plant. This bridging technology is supplanting immediate IP migration by deferring infrastructure replacement costs while delivering acceptable image quality for identification-grade surveillance.
BDSG amendments and BSI technical guidelines are tightening data localization requirements for surveillance systems. On-premise storage architectures gain preference over cloud-connected alternatives as operators seek to minimize cross-border data transfer compliance exposure. German municipal procurement specifications now explicitly favor edge-recording analog configurations that eliminate external network dependencies.
Specification sheets increasingly emphasize Mean Time Between Failures and seal integrity ratings over resolution metrics. Buyers in outdoor-heavy segments prioritize connector corrosion resistance and housing IP ratings. North Rhine-Westphalia industrial facilities lead this behavioral pivot, treating camera longevity as primary total-cost determinant rather than pixel count.
Germany Surveillance Analog Camera Market Segmentation
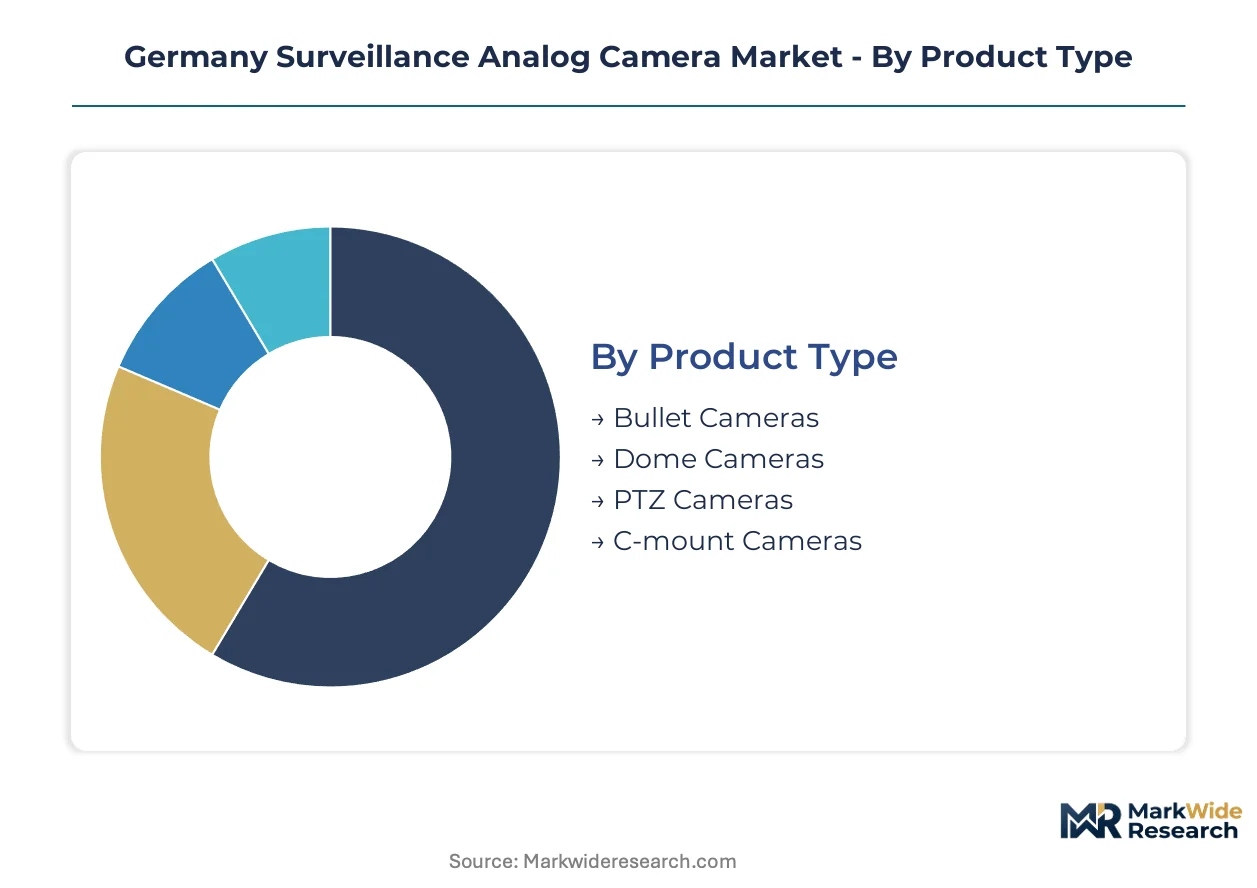
German procurement specifications under BDSG and KBA guidelines create distinct performance tiers across analog camera categories. Municipal infrastructure operators and industrial security managers prioritize different technical attributes based on compliance exposure and installation environment.
Product Type:
BDSG vandal-resistance mandates and KBA image retention requirements split procurement priorities across form factors, with rail and banking applications driving divergent enclosure specifications.
- Bullet Cameras:Cylindrical housings with fixed or varifocal lenses deliver weather-resistant surveillance for perimeter monitoring. North Rhine-Westphalia manufacturing facilities favor these units for loading dock and perimeter coverage where coaxial cable runs already exist.
- Dome Cameras:Hemispherical enclosures with vandal-resistant polycarbonate domes enable discreet positioning in retail banking branches. Bavarian financial institutions specify these for ATM vestibules where BDSG-compliant on-premise storage architectures must integrate with existing analog infrastructure.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms support Deutsche Bahn platform surveillance under KBA traffic monitoring guidelines.
- C-mount Cameras:Interchangeable lens systems serve specialized industrial inspection applications in precision manufacturing zones.
Bullet cameras handle the majority of throughput in industrial retrofit projects; dome cameras are expanding most quickly in banking compliance refreshes.
Installation Type:
Cost tier differentiation separates premium outdoor specifications from economy indoor deployments, with IP67 ratings commanding substantial price premiums in municipal traffic applications.
- Indoor:Standard housings without environmental sealing serve climate-controlled retail and education environments. These installations avoid the connector corrosion issues that degrade outdoor coaxial terminations, extending operational lifespan in Bavarian school districts and municipal office buildings.
- Outdoor:IP67-rated enclosures with gasket-sealed cable entries withstand temperature cycling and precipitation exposure. Stuttgart-centered rail infrastructure projects under Deutsche Bahn specifications mandate these units for platform edge monitoring where Mean Time Between Failures determines total cost of ownership.
- In-ceiling:Recessed mounting preserves architectural aesthetics in premium commercial environments.
- Wall-mounted:Surface brackets enable rapid retrofit deployment in legacy infrastructure upgrades.
Outdoor installations generate the highest replacement velocity due to weathering degradation; in-ceiling mounting is gaining share fastest in retail banking branch redesigns.
Technology:
Migration pathway maturity determines technology selection, with hybrid signal formats enabling resolution upgrades without coaxial plant replacement.
- Analog:Traditional composite video at 700 TVL to 960H resolution operates over standard coaxial infrastructure with PAL signal format. Municipal operators in aging infrastructure zones maintain these systems to avoid triggering full fiber reconstructions that would trigger BDSG compliance reviews.
- HD-CVI:High Definition Composite Video Interface transmits 1080p signals over existing cable plant. North Rhine-Westphalia industrial facilities adopt this format to extract identification-grade imagery from sunk coaxial investments while deferring IP migration costs.
- HD-TVI:Transport Video Interface provides alternative HD-over-coax encoding with broader interoperability.
- AHD:Analog High Definition offers competitive HD transmission for cost-sensitive commercial accounts.
Traditional analog handles the majority of installed base maintenance; HD-CVI is climbing the fastest as manufacturing facilities pursue hybrid migration pathways.
End User:
Customer type dictates procurement channel and specification stringency, with government and transportation segments imposing certification requirements that commercial buyers bypass.
- Retail:Branch security and loss prevention operations prioritize discreet dome form factors with vandal resistance. German banking networks specify analog-digital hybrid architectures to maintain BDSG-compliant on-premise storage while phasing infrastructure gradually.
- Government:Municipal surveillance networks face Federal Data Protection Commissioner oversight that limits cloud-connected deployments. City operators across North Rhine-Westphalia and Bavaria favor edge-recording analog configurations that eliminate external network dependencies.
- Transportation:Deutsche Bahn and municipal traffic departments operate under KBA guidelines mandating minimum image retention periods.
- Education:School district security managers balance budget constraints against vandalism exposure in public facilities.
Retail accounts handle the majority of commercial volume; transportation infrastructure is gaining share fastest under federal monitoring mandate expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering-intensive manufacturing clusters across southern and western Germany anchor domestic analog camera supply chains, while municipal procurement concentrates in industrialized states facing legacy infrastructure refresh cycles.
Bavaria
Precision manufacturing facilities in Munich and Nuremberg maintain extensive analog-digital hybrid surveillance networks. The state's data protection authority enforces strict BDSG compliance protocols for industrial security deployments. Bavarian banking networks in Frankfurt's extended economic zone specify vandal-resistant dome cameras for ATM vestibule monitoring.
North Rhine-Westphalia
Ruhr Valley industrial zones generate sustained demand for bullet camera retrofits at manufacturing perimeters and loading docks. KBA traffic monitoring mandates apply to municipal road infrastructure across Düsseldorf and Cologne metropolitan corridors. Dortmund logistics hubs deploy weather-resistant outdoor housings for supply chain security coverage.
Baden-Württemberg
Stuttgart-centered rail engineering capabilities position the region for Deutsche Bahn platform surveillance upgrades requiring IP67-rated enclosures. State procurement guidelines prioritize Mean Time Between Failures specifications for transportation infrastructure. Karlsruhe's municipal traffic department operates extensive coaxial-based camera networks under federal retention mandates.
Lower Saxony
Wolfsburg automotive manufacturing complexes maintain legacy analog plant for perimeter and production line monitoring. The state's industrial security managers balance BDSG compliance costs against phased IP migration timelines. Hanover's municipal surveillance network faces mounting pressure to upgrade aging coaxial infrastructure without triggering full fiber reconstructions.
Hesse
Frankfurt financial district security operations specify discreet dome form factors for branch surveillance with on-premise storage architectures. The regional data protection commissioner oversees strict protocols limiting cloud-connected analog deployments. Wiesbaden government facilities favor edge-recording configurations that eliminate external network dependencies.
Germany Surveillance Analog Camera Market Competitive Landscape
Concentration sits with diversified security conglomerates and specialized video surveillance manufacturers. The vendor base spans three tiers: Stuttgart-engineered domestic suppliers with rail specialization, Chinese manufacturers with deep distribution partnerships, and Nordic bridging-technology specialists. Dominant competitive moves include hybrid signal format diversification and systems integrator channel consolidation.
Among diversified security conglomerates, Bosch Security Systems Incorporated and Panasonic Corporation exemplify engineering-intensive domestic positioning. Dahua Technology Co Ltd represents the distribution-partnership archetype anchoring mid-tier commercial accounts through German systems integrator networks.
| Leading Market Players |
|---|
| Bosch Security Systems Incorporated |
| Dahua Technology Co Ltd |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Panasonic Corporation |
| Johnson Controls Inc |
| Axis Communications AB |
| Honeywell Security Group |
| Hanwha Vision Co Ltd |
| FLIR Systems |
| Others |
Pricing and Supply Chain Analysis
Long-term municipal procurement contracts with embedded price adjustment clauses lock in supply access for German systems integrators while buffering against copper and coaxial cable input swings. These multi-year agreements between North Rhine-Westphalia city operators and enclosure manufacturers stabilize unit economics for IP67-rated outdoor specifications despite raw material volatility.
Pricing Analysis
KBA guidelines dictate the pricing tier structure across traffic monitoring deployments, separating certified rail-grade configurations from standard municipal specifications. Three-tier pricing structure across premium, standard, and economy levels reflects enclosure durability ratings and BDSG compliance documentation bundling. Cost compression in economy indoor tiers is intensifying because HD-over-coax alternatives erode legacy composite video premiums. Municipal traffic departments show least price sensitivity due to federal mandate funding, while education sector buyers prioritize lowest acquisition cost over specification depth.
Supply Chain Analysis
Strait of Malacca transit routes for copper concentrate and rare earth magnet feedstock underpin shielded cable assembly availability for German enclosure manufacturers. Supply draws from Chilean copper smelters, Chinese rare earth processors, and domestic Stuttgart-area metal fabricators. Raw material dependencies span copper cathode, neodymium magnets for PTZ motor assemblies, and polycarbonate resin for vandal-resistant dome housings. Single-source vulnerability concentrates in Chinese rare earth magnet supply. Distribution runs through authorized systems integrator networks serving mid-tier commercial accounts across Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of technicians competent in both PAL signal troubleshooting and IP configuration protocols constrains installation capacity and elongates project timelines for hybrid migration deployments. This skills gap creates defensive moats for incumbents with established service networks while raising barriers for new entrants lacking training infrastructure.
For Market Incumbents: Compound technical service capabilities through apprenticeship partnerships with Baden-Württemberg vocational institutes, building captive PAL-IP dual-competency workforces that emerging players cannot replicate cost-effectively. Deepen backward integration into Stuttgart-area metal fabrication to secure IP67 enclosure supply against copper price volatility and Chinese component tariff exposure. For New Entrants and Emerging Players: Post-installation firmware migration support represents a service-layer gap where incumbents under-serve mid-tier manufacturing accounts in North Rhine-Westphalia. Target this segment with HD-CVI bridging expertise bundled with extended warranty terms, using direct sales teams rather than integrator channel dependence to capture margin otherwise surrendered to distribution intermediaries. For Investors and Strategic Acquirers: Engineering-intensive domestic specialists with KBA certification pathways and Deutsche Bahn reference contracts offer the strongest acquisition target archetype for long-term infrastructure exposure. Monitor BDSG amendment timing as the inflection indicator for edge-recording analog configuration demand acceleration versus cloud-connected IP substitution.| Strategic Initiative | Industry Significance |
|---|---|
| HD-over-Coax Format Diversification | TVI and CVI encoding capabilities capture North Rhine-Westphalia manufacturing retrofit demand without fiber reconstruction. |
| Systems Integrator Channel Consolidation | Exclusive distribution partnerships with Bavarian commercial integrators lock out competing suppliers from mid-tier municipal procurement. |
| IP67 Enclosure Engineering Investment | Stuttgart-centered rail-grade housing development positions for Deutsche Bahn platform surveillance upgrade cycles. |
| BDSG Compliance Documentation Services | Pre-packaged data protection impact assessments reduce sales cycle elongation for government and transportation accounts. |
| Dual-Competency Technician Training Programs | Apprenticeship pipelines in Baden-Württemberg create service differentiation that hardware-focused competitors cannot replicate. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal surveillance procurement officers, industrial security managers, systems integrator technical directors, and BDSG compliance consultants. Secondary validation drew from KBA technical guideline publications, BSI information security advisories, Federal Data Protection Commissioner enforcement notices, and Deutsche Bahn infrastructure tender databases. Bottom-up unit shipment estimates by form factor and technology tier were triangulated against top-down addressable market calculations derived from municipal budget disclosures and industrial facility security expenditure patterns.
Across the analysis window, forecasts were constructed through multi-dimensional segmentation modeling spanning product type, installation environment, signal technology, and end-user vertical. CAGRs were derived from trend extrapolation of replacement cycle velocities and hybrid migration adoption curves, calibrated against copper price elasticity assumptions and BDSG compliance cost trajectories. Industry-specific inputs included KBA retention mandate enforcement intensity and HD-over-coax interoperability standardization timelines.
Underlying assumptions cover steady BDSG regulatory enforcement without disruptive amendment, with deviation risk concentrated in accelerated IP substitution from declining networked camera costs and potential rare earth magnet supply disruptions. Practitioners should keep alternative scenarios live as federal data protection interpretation evolves and hybrid technology standardization matures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
AI CCTV Market