
 Aluminum Beryllium Market | 2026-2036
Aluminum Beryllium Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Beryllium Market Insights
Capital-intensity divergence between integrated smelters and downstream fabricators is reorganizing competitive tiers in aluminum beryllium supply. Materion Corporation leverages captive beryllium extraction and vacuum induction melting to sustain premium alloy margins across aerospace contracts. IBC Advanced Alloys Corp anchors its position through specialized powder metallurgy capabilities serving nuclear and defense segments. Ulba Metallurgical Plant competes on geographic proximity to Central Asian beryllium ore sources, controlling raw material logistics for European and Asian customers.
Aluminum beryllium designates a family of lightweight, high-stiffness alloys typically containing 38-65% beryllium by weight, produced through vacuum hot pressing or ingot metallurgy to achieve specific stiffness-to-density ratios exceeding titanium alloys. These materials serve critical functions in satellite structures, missile guidance systems, and semiconductor manufacturing equipment where thermal stability and dimensional precision are mandatory. The alloys and forms segment leads current value generation, as aerospace structures and heat sinks command premium pricing for certified vacuum-grade material. Powders represent the fastest-growing category, driven by additive manufacturing qualification programs at prime defense contractors seeking near-net-shape beryllium-aluminum components.
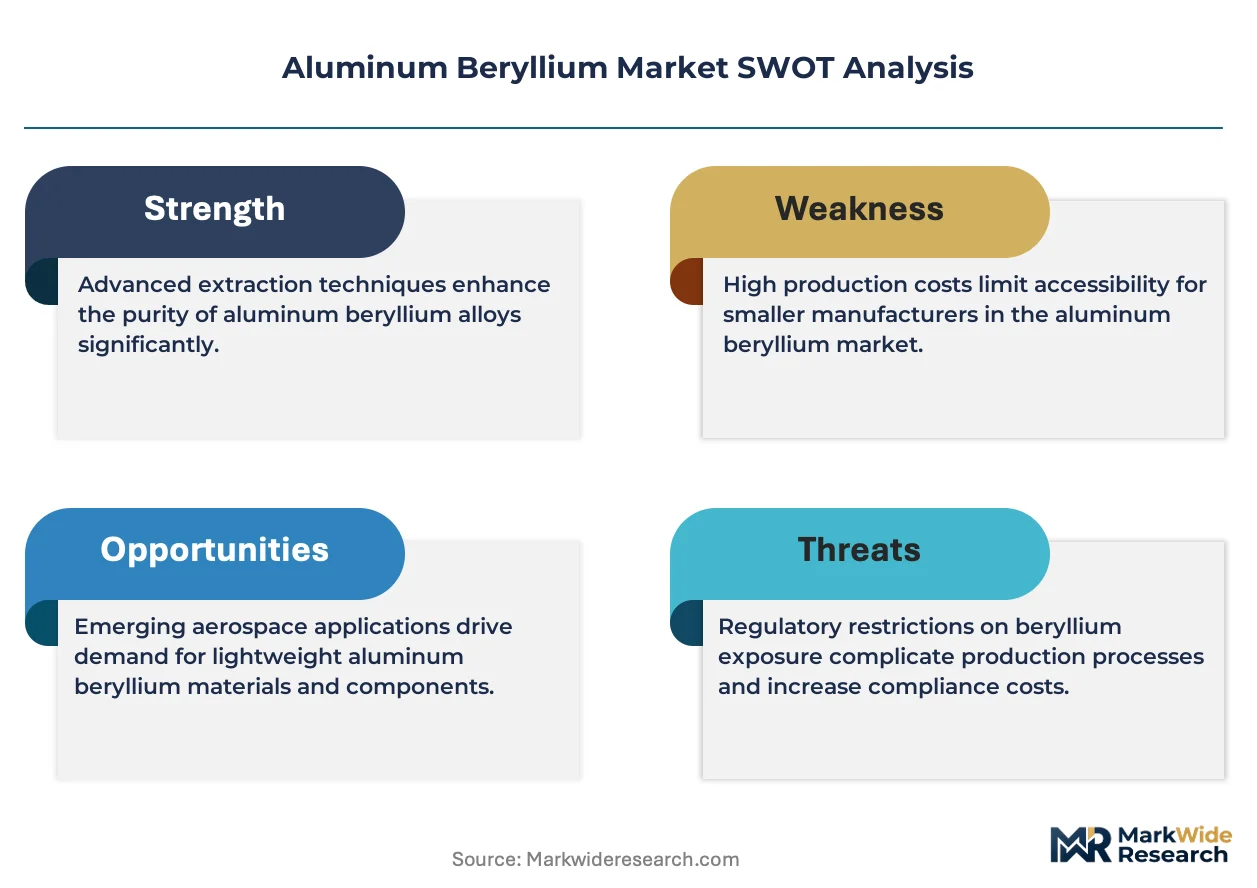
OSHA's enforceable beryllium exposure standards and REACH authorization requirements under ECHA are tightening particulate handling protocols across the value chain, elevating compliance costs for machine shops and foundries. The EPA and state-level environmental regulators in Ohio and Arizona are scrutinizing beryllium waste streams from machining operations, forcing capital upgrades to filtration and closed-loop coolant systems. Stakeholders must monitor evolving toxicity classifications and defense procurement certification timelines to align capacity investments with qualified demand windows.
Market Dynamics
OSHA's enforceable beryllium exposure limits and REACH authorization timelines are compressing foundry capacity while defense procurement accelerates, creating a structural squeeze between qualified supply and certified demand.
Growth Catalysts
- Defense procurement acceleration:Prime contractors in the United States are expanding satellite bus and missile airframe programs, pulling vacuum-grade aluminum beryllium through qualified supply chains in Ohio and Arizona.
- REACH authorization pressure:ECHA's tightening beryllium compound classifications are consolidating European demand onto pre-authorized suppliers with closed-loop machining capabilities.
- Additive manufacturing qualification:Powder metallurgy specifications for near-net-shape beryllium-aluminum components are unlocking design freedoms previously constrained by ingot metallurgy limits.
Market Restraints
- Raw material concentration:Spodumene and bertrandite ore processing concentrates in Central Asian and Southwestern US deposits, exposing fabricators to single-source geopolitical risk.
- Substitution by carbon fiber composites:Satellite manufacturers in Japan and Europe are qualifying CFRP structures for non-thermal-critical applications, capping aluminum beryllium volume in secondary structures.
- OSHA compliance cost escalation:The 2017 general industry standard mandates medical surveillance and engineering controls that add fixed cost per machining station.
Strategic Opportunities
- Underpenetrated semiconductor capital equipment:EUV lithography stage manufacturers in the Netherlands and Japan represent unqualified demand for thermally stable mirror substrates.
- Closed-loop powder recovery systems:Regulatory tailwinds from EPA hazardous waste minimization programs create first-mover advantage for integrated smelter-fabricators.
- Convergence of HIP and AM:Hot isostatic pressing of additively manufactured preforms is opening aerospace component geometries previously machined from solid billet.
Industry Challenges
- Certification timeline compression:NADCAP and AS9100D audit cycles for new entrant foundries stretch 18-24 months, misaligning capacity investment with defense contract award windows.
- Specialized machining workforce scarcity:Beryllium particulate handling certification requires OSHA-compliant training pipelines that community colleges in Ohio and Arizona have not scaled to match demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Beryllium Market |
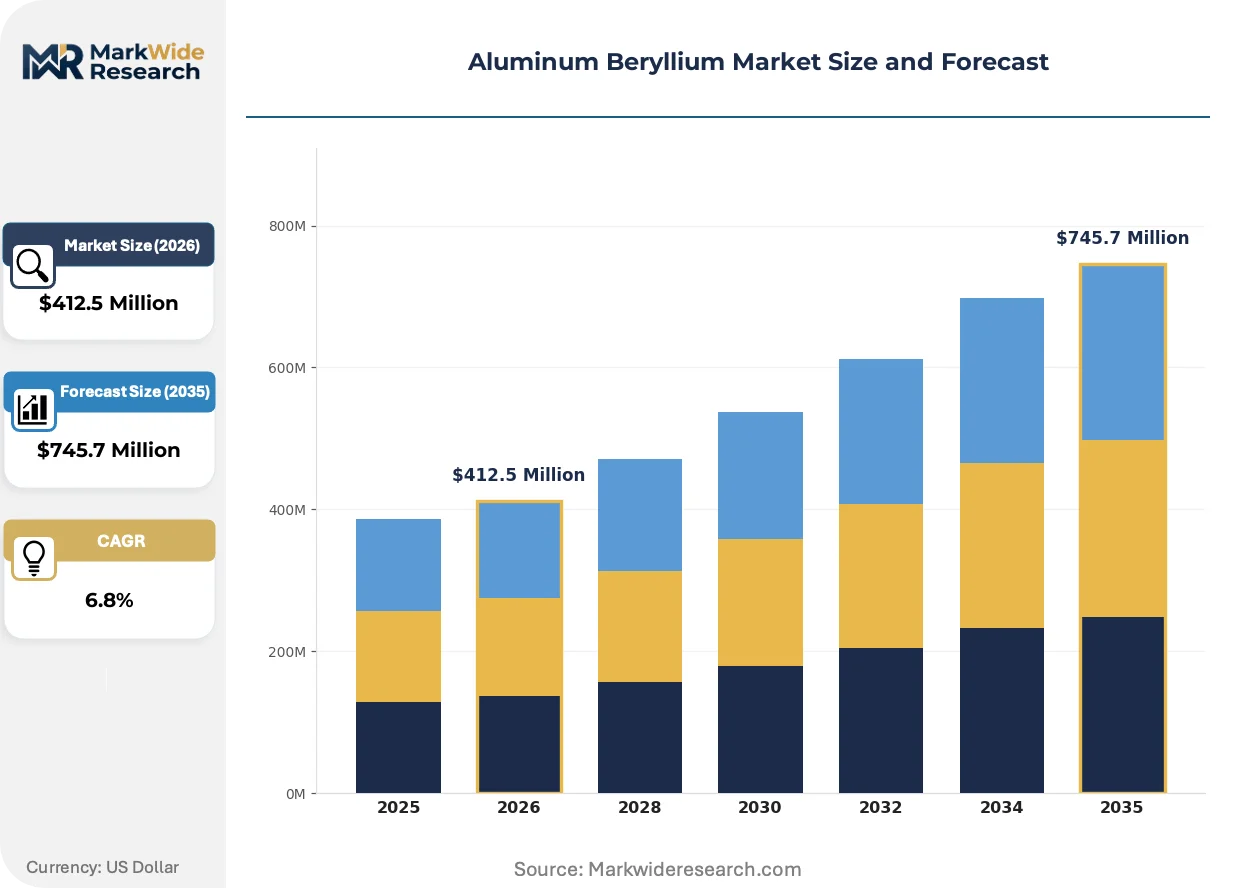
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloys, Powders, Forms, Sheets End User: Aerospace, Military, Electronics, Medical Devices Application: Structural Components, Heat Sinks, Electrical Contacts, Aerospace Structures Form: Cast, Machined, Extruded, Forged |
| Companies Covered | Materion Corporation, IBC Advanced Alloys Corp, Ulba Metallurgical Plant, NGK Metals Corporation, American Elements, American Beryllia Inc, Belmont Metals Inc, Fuyun Hengsheng Beryllium Industry, Hunan Shuikoushan Nonferrous Metals Group Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Beryllium Market Trends and Innovations
Vacuum hot pressing parameters, regulatory authorization pathways, and procurement qualification models are simultaneously evolving, compressing the traditional alloy development cycle from years to months for certified applications.
Additive manufacturing of beryllium-aluminum preforms is miniaturizing satellite structural nodes while preserving stiffness-to-density ratios. Lockheed Martin and Northrop Grumman are qualifying laser powder bed fusion builds for bracket and isolator applications. The technology is miniaturizing component footprints, enabling denser payload packaging without thermal expansion penalties.
REACH authorization requirements under ECHA are forcing European fabricators toward closed-loop coolant and powder containment architectures. The regulation eliminates open machining operations for non-authorized suppliers. Aerospace subcontractors in Germany and France are consolidating onto Materion's pre-authorized supply chain, accelerating tier-two foundry exits.
Defense procurement offices are unbundling material certification from component fabrication, creating direct alloy purchase contracts that bypass traditional prime-tier structures. Tier-one integrators now specify vacuum-grade billet rather than finished brackets, shifting margin capture upstream. This pattern concentrates in US Air Force satellite programs, where material traceability requirements exceed component-level audit depth.
Aluminum Beryllium Market Segmentation
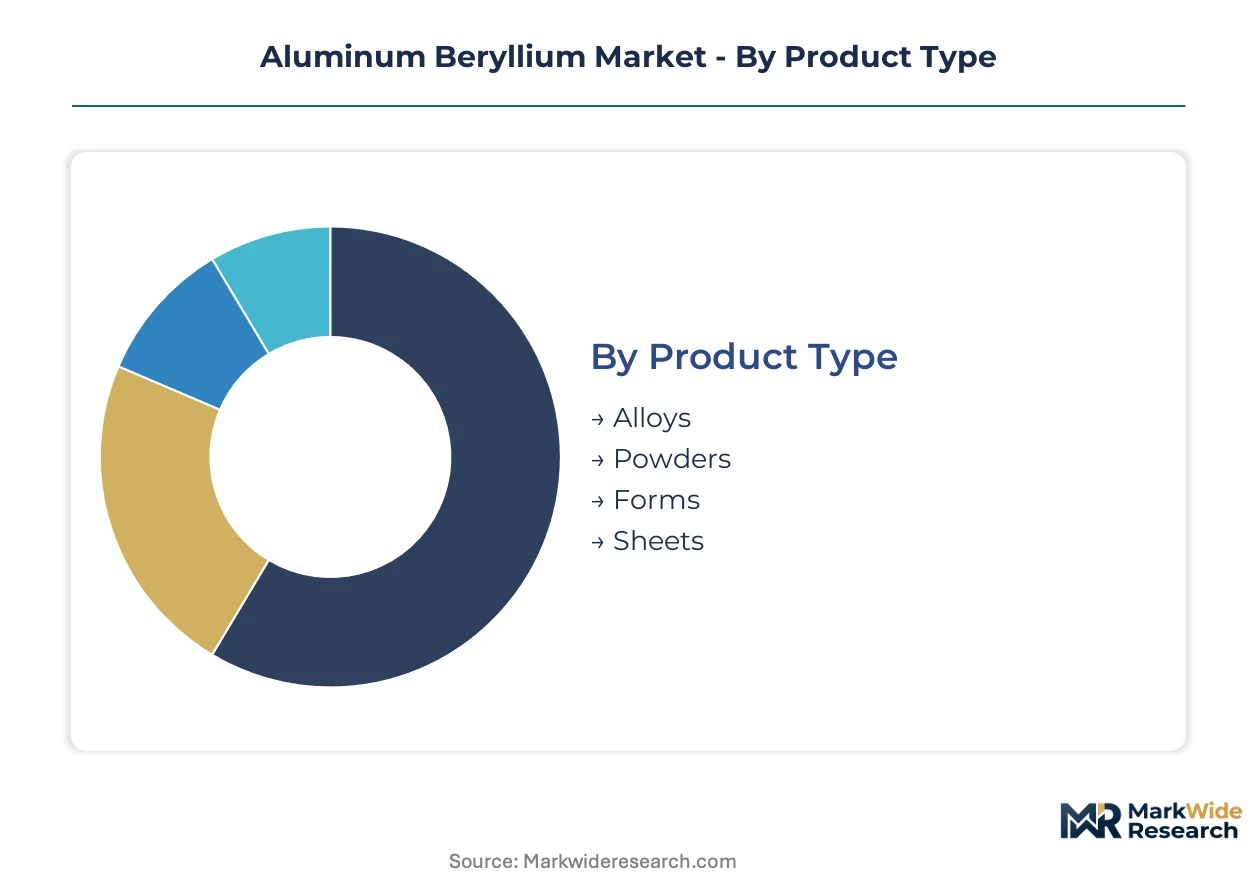
Aluminum beryllium procurement patterns diverge sharply across product specifications and end-use certifications. Regulatory authorization status and aerospace qualification timelines determine which segments capture premium pricing versus commodity volume.
Product Type:
REACH authorization requirements and OSHA exposure standards create tiered compliance costs that reshape competitive positioning across material formats.
- Alloys:Vacuum-grade ingots and billets containing 38-65% beryllium by weight serve as feedstock for satellite structural nodes and missile guidance housings. Aerospace manufacturers in the United States concentrate procurement through Ohio and Arizona supply clusters where NADCAP certification is already established. These ingots command premium pricing due to traceability requirements exceeding component-level audit depth.
- Powders:Atomized and mechanically alloyed powders enable laser powder bed fusion builds for near-net-shape bracket and isolator applications. Lockheed Martin and Northrop Grumman qualification programs are accelerating additive manufacturing adoption for denser payload packaging without thermal expansion penalties.
- Forms:Near-net blanks and preforms reduce machining waste for high-volume aerospace contracts.
- Sheets:Rolled plate products serve heat sink and thermal management applications in semiconductor capital equipment.
Alloys handle the majority of throughput; powders are expanding most quickly on share.
End User:
Defense procurement acceleration and commercial qualification timelines separate volume concentration from margin capture across customer categories.
- Aerospace:Satellite bus manufacturers and prime contractors drive vacuum-grade material specifications. US Air Force programs unbundle material certification from component fabrication, creating direct alloy purchase contracts that shift margin upstream.
- Military:Missile airframe and guidance system programs pull certified beryllium-aluminum through qualified supply chains with 18-24 month NADCAP audit cycles.
- Electronics:EUV lithography stage manufacturers in the Netherlands and Japan represent emerging demand for thermally stable mirror substrates.
- Medical Devices:Specialized imaging equipment utilizes beryllium-aluminum for X-ray window applications requiring dimensional precision.
Aerospace dominates current volume; electronics is climbing the fastest on emerging qualification timelines.
Application:
Functional performance requirements and thermal criticality determine whether aluminum beryllium retains position against carbon fiber composite substitution.
- Structural Components:Satellite frames and optical bench structures require stiffness-to-density ratios exceeding titanium alloys. Japanese and European satellite manufacturers are qualifying CFRP for non-thermal-critical secondary structures, capping volume growth in this segment.
- Heat Sinks:Thermal management solutions for high-power electronics leverage aluminum beryllium's thermal conductivity and low expansion coefficient.
- Electrical Contacts:High-reliability connectors utilize the alloy's spring properties and corrosion resistance.
- Aerospace Structures:Primary load-bearing applications maintain aluminum beryllium position where thermal stability is mandatory.
Structural components retain the largest installed base; heat sinks are gaining share fastest on semiconductor equipment demand.
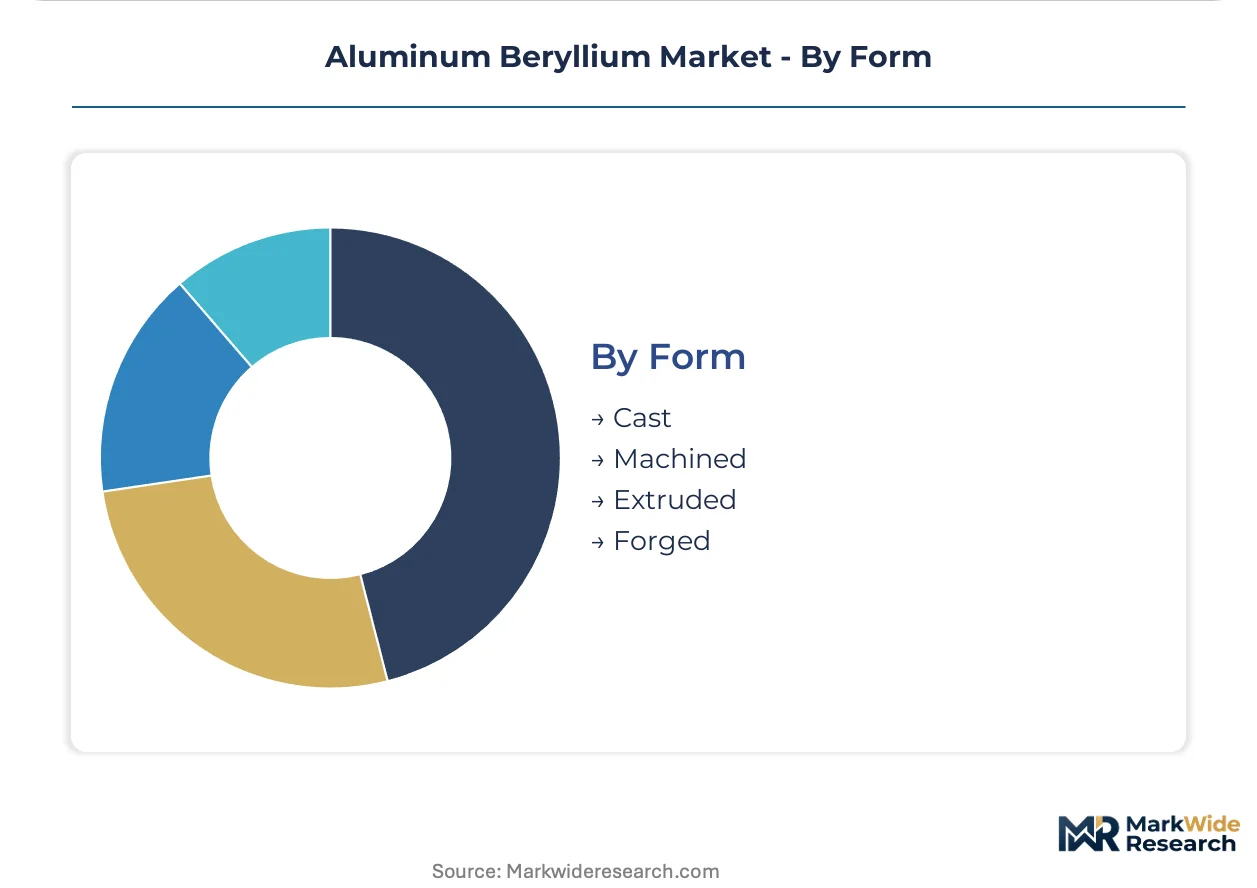
Form:
Capital intensity and machining waste rates differentiate margin structures across processing methods.
- Cast:Investment casting produces complex geometries for satellite bracket applications with reduced machining requirements.
- Machined:CNC finishing from solid billet dominates high-precision guidance system housings despite OSHA-mandated closed-loop coolant system costs.
- Extruded:Profile shapes serve structural framing with favorable stiffness-to-weight ratios for aerospace platforms.
- Forged:Hot isostatic pressing of preforms opens component geometries previously machined from solid billet, converging with additive manufacturing workflows.
Machined forms command the highest unit economics; forged products are accelerating fastest on HIP-AM convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States supply clusters where defense procurement unbundles material certification, while European fabricators absorb REACH authorization premiums that compress margins against closed-loop machining investments.
United States
Defense contractors in Ohio and Arizona drive vacuum-grade alloy procurement through qualified supply chains with established NADCAP certification. OSHA's 2017 general industry standard mandates medical surveillance and engineering controls that add fixed cost per machining station. Materion Corporation anchors captive extraction and vacuum induction melting capacity in the Southwest, sustaining premium margins across aerospace contracts.
Germany
Aerospace subcontractors in Bavaria and Baden-Württemberg consolidate onto pre-authorized supply chains as ECHA eliminates open machining operations for non-authorized suppliers. REACH authorization requirements force capital upgrades to closed-loop coolant and powder containment architectures. Industrial clusters around Munich and Stuttgart specialize in semiconductor capital equipment components requiring thermal stability.
Japan
Satellite manufacturers in Tokyo and Nagoya qualify carbon fiber composites for non-thermal-critical secondary structures, capping aluminum beryllium volume growth. METI oversees industrial standards for high-reliability materials in aerospace and electronics applications. Precision machining clusters in the Chubu region serve EUV lithography stage manufacturers with thermally stable mirror substrates.
China
State-owned nonferrous metals groups in Hunan Province control bertrandite ore processing capacity serving domestic aerospace programs. MIIT regulates strategic materials production under national industrial policy frameworks. Fuyun Hengsheng Beryllium Industry and Hunan Shuikoushan Nonferrous Metals Group concentrate smelting operations in Central Asian ore proximity zones.
United Kingdom
Defense procurement through BAE Systems and satellite prime contractors pulls certified material through established supply relationships. The Health and Safety Executive enforces particulate exposure limits aligned with evolving EU regulatory frameworks. Aerospace engineering clusters in the Midlands and Southwest England maintain machining capabilities for missile guidance system housings.
Aluminum Beryllium Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the aluminum beryllium value chain. Integrated smelters with captive ore access command premium pricing through vacuum-grade certification, while downstream fabricators compete on specialized powder metallurgy and closed-loop machining compliance. Three archetypes dominate: vertically integrated material suppliers, specialized alloy fabricators, and geographic-proximity processors. Competitive moves concentrate on NADCAP/AS9100D certification acquisition and hot isostatic pressing capacity expansion.
Among integrated material suppliers, Materion Corporation and Ulba Metallurgical Plant occupy positions that exemplify the captive-extraction archetype, with geographic naming conventions indicating Southwestern US and Central Asian operational bases respectively. IBC Advanced Alloys Corp represents the specialized fabricator tier, with corporate structure suggesting Canadian or North American incorporation focused on downstream alloy processing. These three entities anchor the competitive structure without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Materion Corporation |
| IBC Advanced Alloys Corp |
| Ulba Metallurgical Plant |
| NGK Metals Corporation |
| American Elements |
| American Beryllia Inc |
| Belmont Metals Inc |
| Fuyun Hengsheng Beryllium Industry |
| Hunan Shuikoushan Nonferrous Metals Group Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber composite substitution in satellite secondary structures simultaneously redraws procurement geography toward Japan and European CFRP clusters while compressing aluminum beryllium pricing premiums to thermal-critical applications alone. This displacement dynamic concentrates pricing power with vacuum-grade certified suppliers in Ohio and Arizona defense corridors where NADCAP traceability commands configured-to-order premiums.
Pricing Analysis
Configured-to-order vacuum-grade billet commands substantial premiums over standard ingot formats due to AS9100D certification depth and material traceability requirements exceeding component-level audit standards. Price differentiation separates NADCAP-certified aerospace feedstock from commercial-grade alternatives, with defense procurement offices unbundling material certification from fabrication to shift margin capture upstream. Pricing pressure stems from REACH authorization compliance costs forcing European fabricators toward closed-loop machining investments that erode downstream margins. Military satellite prime contractors exhibit lowest price sensitivity given mission-critical thermal stability requirements, while commercial electronics buyers negotiate aggressively on heat sink volumes.
Supply Chain Analysis
Central Asian bertrandite ore transit through Kazakhstan and Uzbekistan underwrites raw material security for Ulba Metallurgical Plant and Chinese state-owned smelters in Hunan Province. The supply chain draws from geographically concentrated spodumene deposits in Southwestern US and Central Asian ore belts, with fabricated components flowing through Ohio and Arizona machining clusters. Single-source vulnerability concentrates in ore processing capacity controlled by state-affiliated entities in China and Kazakhstan. Distribution runs through qualified prime contractor supply chains with established NADCAP certification rather than open market spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against carbon fiber composite encroachment in non-thermal-critical satellite structures, demanding that incumbents harden their position in thermal-mandatory applications where stiffness-to-density ratios exceed substitute performance.
For Market Incumbents: Fortify captive beryllium extraction and vacuum induction melting capacity to sustain premium alloy margins against powder metallurgy specialists encroaching from additive manufacturing qualification programs. Prioritize NADCAP certification depth in Ohio and Arizona supply clusters where defense procurement unbundling shifts margin upstream toward material suppliers. Accelerate hot isostatic pressing capacity expansion to capture convergence opportunities between HIP and additive manufacturing workflows for near-net-shape aerospace components.
For New Entrants and Emerging Players: Differentiate on closed-loop powder containment architectures that preempt REACH authorization barriers blocking European market access for non-compliant fabricators. Target EUV lithography stage manufacturers in the Netherlands and Japan as underpenetrated demand for thermally stable mirror substrates with shorter qualification timelines than defense aerospace. Pursue direct alloy purchase contracts with semiconductor capital equipment OEMs seeking vacuum-grade billet bypassing traditional prime-tier structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized fabricators possessing pre-authorized European supply chains and established OSHA-compliant machining infrastructure. Long-term viability hinges on defense procurement continuity and additive manufacturing qualification acceleration across prime contractor programs. Watch for inflection signals in semiconductor capital equipment qualification timelines for EUV lithography mirror substrates as alternative demand anchors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Processing | Captive bertrandite extraction secures raw material margin and insulates against Central Asian supply disruptions. |
| Closed-Loop Machining Certification | Pre-authorized REACH compliance creates competitive moats eliminating non-compliant European fabricators from qualified supply chains. |
| Additive Manufacturing Qualification | Laser powder bed fusion certification at Lockheed Martin and Northrop Grumman unlocks near-net-shape component geometries. |
| Hot Isostatic Pressing Capacity Expansion | HIP convergence with AM preforms opens aerospace geometries previously machined from solid billet. |
| Semiconductor Equipment Market Entry | EUV lithography stage demand in the Netherlands and Japan diversifies revenue beyond defense procurement cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from publicly traded alloy suppliers, ECHA authorization registries, and defense procurement disclosure databases. Primary interviews engaged plant managers at vacuum induction melting facilities, procurement leads at satellite prime contractors, regulatory affairs directors navigating REACH authorization pathways, and technical R&D heads specializing in powder metallurgy specifications. Bottom-up alloy volume estimates triangulated against top-down defense procurement budget allocations and semiconductor capital equipment shipment data.
Segmentation dimensions modeled span product type across alloys, powders, forms and sheets; end user categories separating aerospace, military, electronics and medical devices; application functions including structural components, heat sinks, electrical contacts and aerospace structures; and processing forms distinguishing cast, machined, extruded and forged outputs. CAGRs derived from regression analysis of historical procurement patterns against defense contract award timelines and additive manufacturing qualification milestones. Industry-specific forecast inputs incorporated NADCAP certification pipeline durations and REACH authorization sunset dates.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement acceleration or semiconductor capital equipment demand qualification would require recalibration. Forecasts reflect assumptions regarding OSHA compliance cost trajectories and ECHA authorization timelines that could shift with regulatory reinterpretation. Practitioners should keep alternative scenarios live as carbon fiber composite performance improvements and REACH authorization enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market