
 Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market | 2026-2036
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market Insights
Aftermarket refurbishment revenue is reconfiguring margin pools away from initial OEM sales toward lifetime service contracts. GKN Aerospace leverages its transatlantic manufacturing footprint to capture recurring window replacement cycles on aging narrow-body fleets. PPG Aerospace sustains technology leadership through proprietary coating systems that extend optical clarity lifespans. Saint-Gobain Aerospace dominates European supply chains with vertically integrated glass-ceramic production from raw material to finished pane.
Lightweight high-strength passenger window systems for next-gen aircraft integrate laminated transparent structures, typically 20-40mm thick, engineered to withstand differential pressures exceeding 8 psi while transmitting visible light at rates above 85 percent. These assemblies serve the essential commercial purpose of maintaining cabin pressurization integrity and passenger visibility across altitudes up to 43,000 feet. Composite laminates and lithium aluminosilicate materials command premium positioning as OEMs specify thermally stable, bird-strike-compliant solutions for single-aisle programs. Acoustic windows represent the fastest-growing product category as airlines prioritize cabin noise reduction for passenger comfort differentiation on long-haul routes.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks mandate specific impact resistance and fatigue cycling thresholds that directly determine material selection and testing protocols for window system suppliers. The EU Green Deal's emissions reduction trajectory and ICAO carbon offset requirements pressure airframers to shave every kilogram of weight, amplifying specification intensity for low-density transparent structures. Stakeholders must monitor evolving bird-strike kinetic energy standards and dual-carbon regulatory timelines to anticipate which material platforms will secure design lock on next-generation programs.
Market Dynamics
Airframers' fuel efficiency mandates are compressing specification cycles for transparent structures, forcing material transitions from thermally heavy soda-lime glass to lithium aluminosilicate and hybrid laminates within single product generations.
Growth Catalysts
- Boeing 737 MAX and 777X production ramps:These programs specify bird-strike-rated transparent assemblies, pulling advanced material capacity toward narrow-body and wide-body platforms simultaneously.
- FAA Part 25 certification thresholds:Updated impact resistance and fatigue cycling requirements compel OEMs to source upgraded window systems rather than grandfather legacy designs.
- Composite laminate bonding advances:Improved interlayer adhesion technologies enable thinner, lighter assemblies that maintain optical clarity across pressurization cycles.
Market Restraints
- Lithium aluminosilicate raw material concentration:Specialty glass-ceramic feedstock production clusters in limited geographies, exposing supply chains to geopolitical friction and input cost volatility.
- EASA CS-25 certification timeline rigidity:Extended validation protocols for new transparent material platforms delay revenue recognition by 18-36 months after technical readiness.
- Acoustic window cost premium:Noise-dampening transparent structures command 40-60% price elevation over standard configurations, constraining adoption to long-haul fleet segments.
Strategic Opportunities
- India narrow-body fleet expansion:IndiGo and Air India's A320neo and 737 MAX orders create demand for lightweight window systems as domestic aviation infrastructure scales.
- EU Green Deal aviation emissions targets:Weight reduction mandates for carbon intensity compliance position low-density transparent structures as qualifying components for green financing instruments.
- Aftermarket refurbishment channel development:Aging single-aisle fleets in the United States enter replacement cycles, shifting margin capture from OEM first-fit to lifetime service contracts.
Industry Challenges
- Bird-strike kinetic energy testing capacity:Limited certified test facilities create bottlenecks for new material qualification, compressing development schedules.
- Optical coating process expertise scarcity:Specialized vapor deposition and sputtering skills required for anti-icing and anti-fog surface treatments concentrate among veteran technicians.
- Legacy fleet retrofit integration:New lightweight assemblies must interface with existing cabin pressure frames designed for heavier legacy glass, complicating installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market |
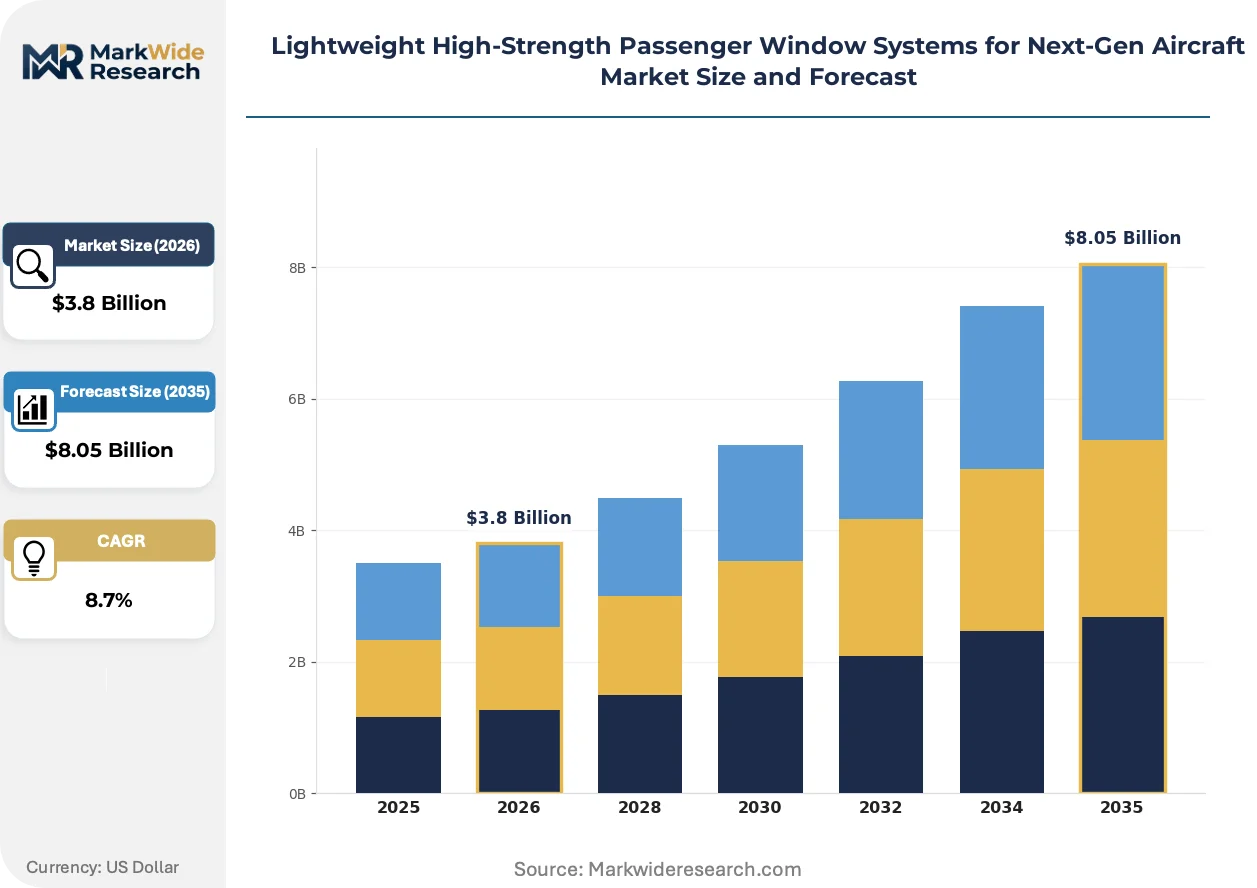
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV-Resistant Windows, Impact-Resistant Panes, Thermal Insulated Panels, Acoustic Windows, Anti-Glare Screens Material: Lithium Aluminosilicate, Acrylic Polymer, Polycarbonate, Tempered Glass, Composite Laminates Application: Commercial Jets, Business Aviation, Regional Aircraft, Cargo Planes, Personal Commuters End User: OEMs, Tier-1 Suppliers, Aircraft Maintenance Providers, Airlines, Aviation Retrofitters |
| Companies Covered | GKN Aerospace, PPG Aerospace, Saint-Gobain Aerospace, Gentex Corporation, The NORDAM Group, Lee Aerospace, LP Aero Plastics, FACC AG, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market Trends and Innovations
Transparent structure engineering is converging with digital manufacturing and predictive maintenance architectures, redefining how window systems are specified, produced, and serviced across aircraft lifecycles.
Smart window technologies incorporating electrochromic dimming layers are digitizing passenger experience control and cabin management system integration. Airbus and Boeing now specify these assemblies for premium cabin zones on long-haul platforms. The shift is compressing traditional static window procurement into connected cabin ecosystem contracts.
ICAO carbon offset and reduction schemes for international aviation are tightening emissions accounting methodologies, directly weighting airframe component selection toward verified low-mass solutions. EASA has aligned CS-25 guidance with these frameworks, accelerating material substitution timelines. European OEM supply chains are responding by pre-qualifying lithium aluminosilicate platforms earlier in development cycles.
Airline technical procurement teams are consolidating vendor relationships around integrated transparent structure suppliers capable of delivering coating, framing, and installation as unified packages. This consolidation displaces fragmented sourcing of discrete glass, interlayer, and hardware components. The restructuring is most visible among United States-based network carriers refreshing narrow-body interiors.
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market Segmentation
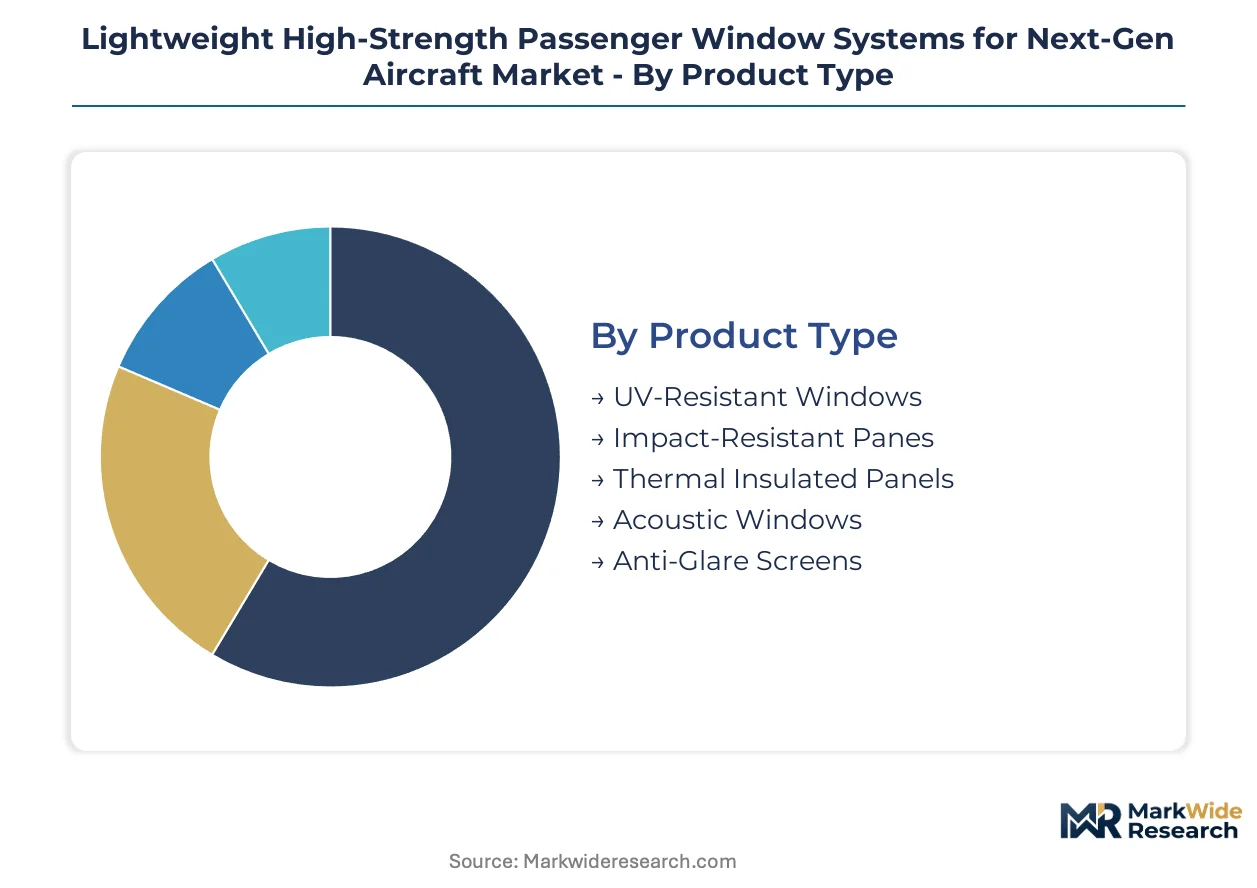
Segmentation in aircraft window systems determines aftermarket revenue capture and material qualification pathways. Each dimension—product type, material, application, and end user—shapes distinct margin structures and certification requirements that suppliers must navigate.
Product Type:
After-sales service intensity varies dramatically across window categories, with acoustic and thermal solutions commanding premium refurbishment contracts while standard impact-resistant panes generate volume-driven replacement cycles.
- Acoustic Windows:Multi-layer transparent assemblies integrate viscoelastic interlayers to dampen cabin noise by 6-10 decibels. Long-haul carriers operating Boeing 777X and Airbus A350 fleets specify these for premium cabin zones, driven by passenger comfort differentiation mandates.
- Impact-Resistant Panes:Laminated structures engineered to FAA Part 25 bird-strike kinetic energy thresholds of 4 pounds at 350 knots. Narrow-body OEM production lines in Renton and Toulouse pull the majority of global capacity for this category.
- Thermal Insulated Panels:Double-pane configurations with low-emissivity coatings reduce heat transfer coefficients.
- UV-Resistant Windows:Spectrally selective transparent structures block ultraviolet transmission above 380 nanometers.
- Anti-Glare Screens:Polarized or tinted assemblies for cockpit and passenger viewing angles.
By volume, Impact-Resistant Panes leads. By growth pace, Acoustic Windows is ahead.
Material:
Cost tier stratification separates aerospace-grade specialty ceramics from commodity transparent polymers, with lithium aluminosilicate occupying the premium position and polycarbonate serving cost-sensitive retrofit applications.
- Lithium Aluminosilicate:Glass-ceramic matrix with near-zero thermal expansion coefficient and specific gravity below 2.5. Airbus A320neo and Boeing 737 MAX programs specify this material for forward cockpit windows, compelled by EASA CS-25 fatigue cycling requirements.
- Composite Laminates:Hybrid transparent structures bonding glass-ceramic outer plies to polymer interlayers. These assemblies dominate wide-body side window specifications where weight targets below 3 kilograms per pane intersect with optical clarity mandates.
- Polycarbonate:High-impact thermoplastic with 50% weight reduction versus glass.
- Acrylic Polymer:Lower-cost transparent alternative for non-pressurized applications.
- Tempered Glass:Legacy material retained for certain cargo and commuter aircraft.
By installed base, Lithium Aluminosilicate dominates. By expansion trajectory, Composite Laminates is climbing fastest.
Application:
Volume concentration in single-aisle commercial platforms creates procurement scale advantages, while business aviation and regional segments fragment demand across customized specifications.
- Commercial Jets:Pressurized cabin window systems for aircraft above 100 seats. Boeing and Airbus production rates for 737 MAX and A320neo families absorb approximately two-thirds of qualified lithium aluminosilicate capacity globally.
- Business Aviation:Custom transparent assemblies for Gulfstream, Dassault, and Bombardier platforms. These programs prioritize electrochromic dimming integration and acoustic performance over unit cost minimization.
- Regional Aircraft:Smaller-format windows for 50-100 seat turboprops and jets.
- Cargo Planes:Simplified transparent structures where passenger viewing is secondary.
- Personal Commuters:Emerging electric vertical takeoff and landing aircraft segment.
By fleet size, Commercial Jets leads. By specification intensity per window, Business Aviation is ahead.
End User:
Customer type determines contract structure, with OEM first-fit programs demanding multi-year qualification investments and aftermarket channels rewarding responsive logistics capabilities.
- OEMs:Boeing, Airbus, and Embraer source window systems through formalized supplier partnerships requiring dedicated production lines and joint development agreements. These relationships lock in design authority for entire aircraft programs.
- Aircraft Maintenance Providers:MRO operators including Lufthansa Technik and ST Engineering manage window replacement cycles for aging fleets. Their procurement emphasizes interchangeability with legacy frames and compressed turnaround times.
- Tier-1 Suppliers:Aerostructures integrators purchasing transparent assemblies for subsystem consolidation.
- Airlines:Direct procurement for interior refresh programs and damage replacement.
- Aviation Retrofitters:Specialized shops addressing cabin reconfiguration projects.
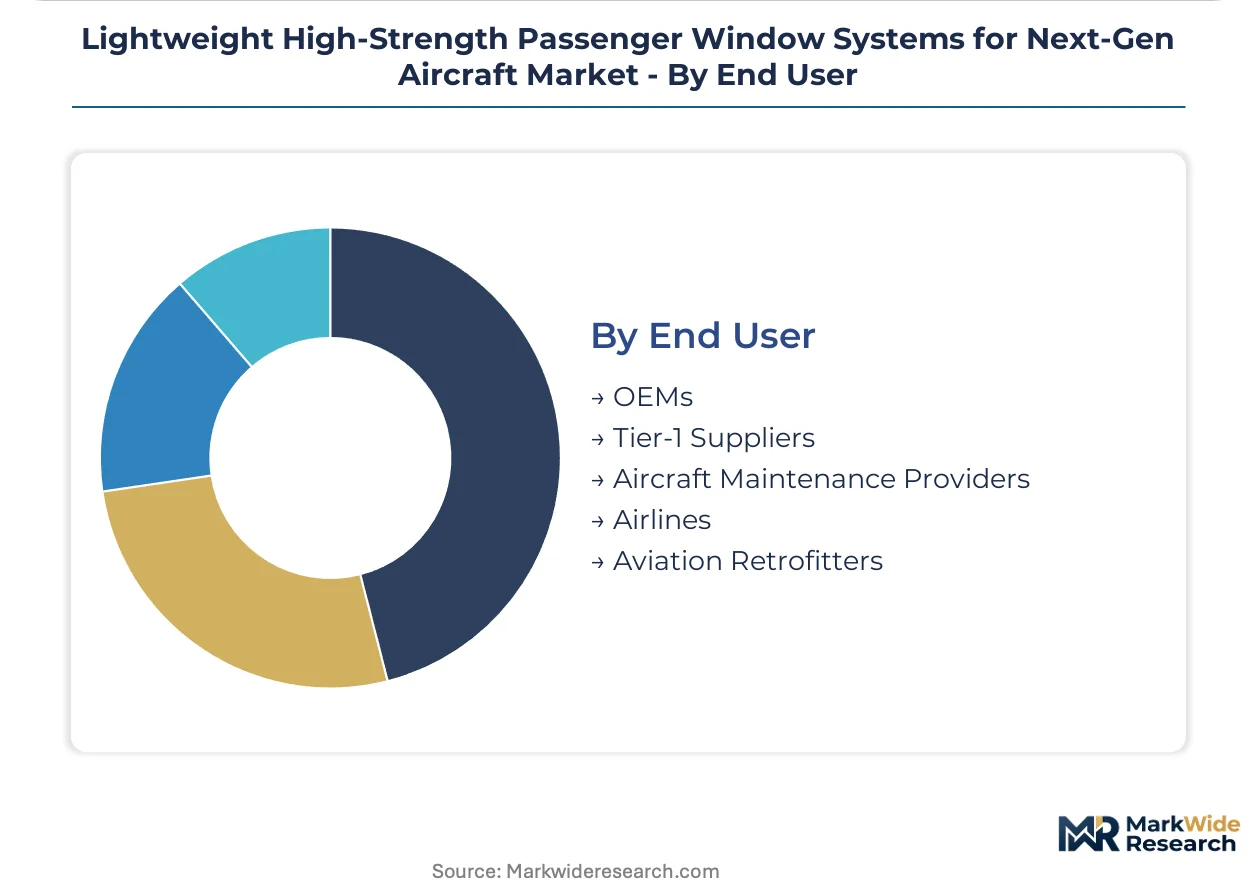
By contract value per engagement, OEMs leads. By transaction frequency, Aircraft Maintenance Providers is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airlines in India and Southeast Asia exhibit the highest price elasticity for window system procurement, while Middle Eastern and European carriers prioritize acoustic performance and electrochromic features regardless of cost premium.
United States
Boeing's 737 MAX and 777X production lines in Renton and Charleston pull substantial advanced material capacity for bird-strike-rated transparent assemblies. FAA Part 25 certification updates compel material upgrades from legacy soda-lime glass to lithium aluminosilicate platforms. Wichita, Kansas hosts specialized MRO clusters managing replacement cycles for aging narrow-body fleets.
Germany
Airbus final-assembly operations in Hamburg anchor European demand for composite laminate window systems on A320neo and A350 programs. EASA CS-25 fatigue cycling requirements align with EU Green Deal weight reduction mandates, accelerating specification intensity for low-density transparent structures. Bavaria's aerospace supplier corridor concentrates coating and interlayer adhesion expertise.
France
Toulouse-based Airbus manufacturing absorbs significant lithium aluminosilicate capacity for forward cockpit windows on single-aisle platforms. French national aerospace research programs support qualification timelines for new transparent material platforms. The Saint-Gobain industrial cluster near Paris maintains vertically integrated glass-ceramic production from raw material to finished pane.
India
IndiGo and Air India's combined A320neo and 737 MAX orders exceed 1,500 aircraft, creating substantial demand for lightweight window systems as domestic aviation infrastructure scales. The country's Directorate General of Civil Aviation enforces ICAO-aligned certification standards for pressurized cabin components. Bangalore and Hyderabad emerging as MRO hubs for Southeast Asian fleet refurbishment.
United Kingdom
GKN Aerospace's transatlantic manufacturing footprint includes UK-based production serving both Boeing and Airbus supply chains. British airworthiness standards under the Civil Aviation Authority maintain equivalence with EASA CS-25 frameworks post-Brexit. The West Midlands aerospace cluster specializes in bonded composite assemblies for wide-body side window applications.
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market Competitive Landscape
Capability concentration sits with specialty glass-ceramic and coating specialists; scale advantage sits with diversified aerostructures integrators serving multiple aircraft programs simultaneously. The market structures around three tiers: vertically integrated material producers controlling raw-to-finished supply chains, subsystem specialists delivering framed window assemblies, and MRO-focused distributors managing aftermarket logistics. Dominant competitive moves include backward integration into lithium aluminosilicate feedstock production and strategic partnerships for electrochromic technology licensing.
Within the integrated material tier, Saint-Gobain Aerospace exemplifies European supply chain dominance through captive glass-ceramic production. Among transatlantic aerostructures suppliers, GKN Aerospace occupies a position spanning OEM first-fit and aftermarket refurbishment channels. PPG Aerospace represents the coating technology archetype, with proprietary surface treatment systems extending optical clarity lifespans across pressurization cycles.
| Leading Market Players |
|---|
| GKN Aerospace |
| PPG Aerospace |
| Saint-Gobain Aerospace |
| Gentex Corporation |
| The NORDAM Group |
| Lee Aerospace |
| LP Aero Plastics |
| FACC AG |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Lithium aluminosilicate feedstock production clusters in Germany and France anchor margin capture at the raw material tier, while downstream value pools concentrate with MRO operators managing replacement cycles for aging narrow-body fleets.
Pricing Analysis
Lifetime service contracts and refurbishment agreements now drive value accretion beyond initial OEM sales. Pricing stratifies across acoustic performance tiers, certification grade, and after-sales bundling intensity. Cost compression in standard impact-resistant configurations is intensifying because airlines consolidate vendor relationships around integrated suppliers. Low-cost carriers in India exhibit highest price sensitivity, while Middle Eastern long-haul operators prioritize noise-dampening features regardless of premium.
Supply Chain Analysis
Specialty glass-ceramic feedstock draws from concentrated production in Germany, France, and the United States. Lithium aluminosilicate raw material, vapor deposition coating systems, and polymer interlayer adhesives constitute critical input dependencies. Single-source vulnerability around certified bird-strike testing facilities creates qualification bottlenecks for new material platforms. Distribution runs through formalized OEM supplier partnerships and responsive MRO logistics networks serving fleet refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket refurbishment revenue layers are expanding faster than first-fit hardware sales as aging single-aisle fleets enter replacement cycles, repositioning this market as a service-attach opportunity.
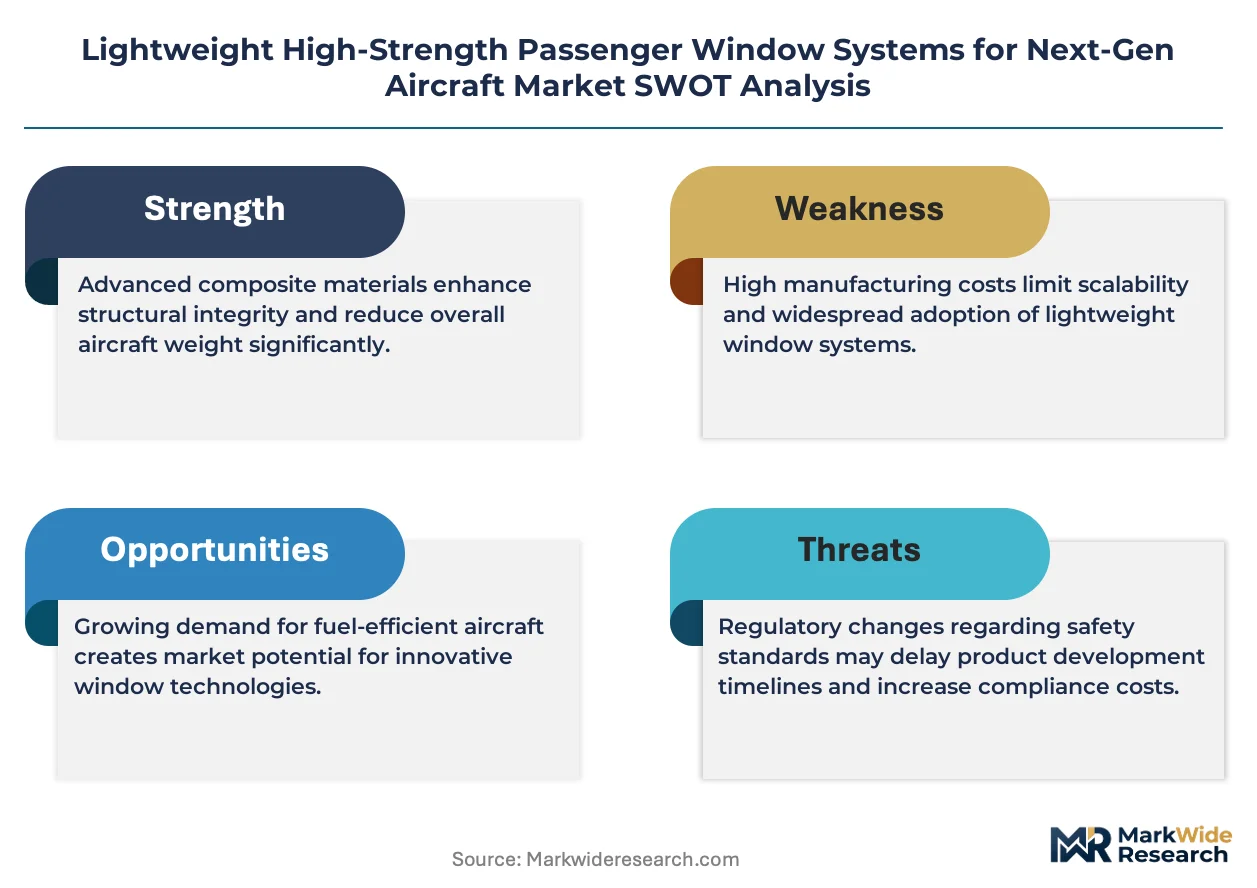
For Market Incumbents: Build captive lithium aluminosilicate production capacity to secure raw material access against supply concentration risk. Deepen coating process expertise through targeted technician development programs. Defensive consolidation around electrochromic technology licensing agreements counters emerging smart window specialists.
For New Entrants and Emerging Players: India's narrow-body fleet expansion represents the most penetrable entry point for qualified transparent assemblies. Regional MRO hubs in Bangalore and Hyderabad offer channel access for aftermarket penetration. Partner with established coating specialists to bypass vapor deposition capability gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart window technology development. Long-term viability favors suppliers with backward integration into glass-ceramic feedstock and dual certification pathways for FAA Part 25 and EASA CS-25. Monitor bird-strike kinetic energy standard revisions as inflection indicator for material platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Aluminosilicate Feedstock | Saint-Gobain's captive raw-to-finished production secures supply continuity against geopolitical friction. |
| Electrochromic Technology Licensing Partnership | Gentex Corporation's smart window patents enable Airbus and Boeing premium cabin specifications. |
| Regional MRO Hub Establishment | GKN Aerospace's transatlantic footprint captures recurring replacement cycles on aging 737 MAX fleets. |
| Dual Certification Pathway Investment | Simultaneous FAA Part 25 and EASA CS-25 qualification reduces revenue recognition delays. |
| Acoustic Window Product Line Expansion | PPG Aerospace's noise-dampening assemblies address long-haul carrier comfort differentiation mandates. |
Research Methodology
Initial hypotheses were tested against primary input from airframe procurement directors, MRO operations managers, coating process engineers, and regulatory certification specialists and refined through secondary validation against FAA airworthiness directives, EASA certification databases, customs trade records, and OEM supplier disclosure filings. Bottom-up demand modeling triangulated against top-down production capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, material platform, application tier, and end-user channel. CAGRs were derived from installed base projections and replacement cycle frequencies. Bird-strike testing capacity constraints and lithium aluminosilicate production expansion timelines served as industry-specific forecast inputs.
Practitioners should monitor evolving kinetic energy certification thresholds and dual-carbon regulatory timelines for early signals requiring forecast revision. Cross-checking against Boeing and Airbus published production rate schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market