
 Air Transport MRO Market | 2026-2036
Air Transport MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Air Transport MRO Market Intelligence
The airline industry's increasing reliance on asset-light operational models, which prioritize aircraft leasing over direct ownership, is reshaping the competitive landscape for maintenance services. This trend creates a larger addressable market for independent MRO providers. Lufthansa Technik leverages its vast engineering expertise to offer comprehensive support packages. ST Engineering Aerospace differentiates through its nose-to-tail service capabilities across multiple aircraft platforms. GE Aerospace sustains its market leadership in the engine overhaul segment through proprietary technologies and deep OEM integration.
Air transport MRO encompasses all maintenance, repair, and overhaul activities required to ensure an aircraft remains in an airworthy condition according to civil aviation authority standards. These activities range from routine line maintenance checks to complex structural repairs and complete engine overhauls. The primary purpose is to guarantee the safety, reliability, and operational efficiency of commercial and private aircraft fleets. Engine Overhaul services command the highest value due to their technical complexity and the cost of replacement parts. Demand for component repair services for new-generation commercial jets is expanding rapidly.
Strict regulatory oversight from bodies like the US Federal Aviation Administration (FAA) governs every aspect of MRO, from technician certification to parts traceability. European Union policies, such as the EU Green Deal, are also influencing engine service requirements by promoting modifications for greater fuel efficiency and lower emissions. These regulations create high barriers to entry and mandate continuous investment in compliance. MRO providers must now decide on the appropriate level of investment into digital capabilities, such as predictive maintenance, to secure future contracts.
Market Dynamics
The convergence of data analytics and asset management is the central force shaping air transport MRO. This shift compels providers to move from reactive repairs to predictive, data-driven maintenance models to service the growing fleets of aircraft leasing companies.
Growth Catalysts
- Predictive Maintenance Adoption:The integration of IoT sensors and analytics platforms allows MROs to forecast component failures, reducing unscheduled aircraft downtime and optimizing maintenance schedules.
- Fleet Management Outsourcing:Aircraft leasing companies are increasingly outsourcing maintenance management for their transitioning fleets, creating a larger market for independent MRO providers.
- Southeast Asian Hubs:The concentration of MRO capacity in Singapore and Malaysia creates specialized ecosystems that efficiently serve high-traffic aviation routes in the region.
Market Restraints
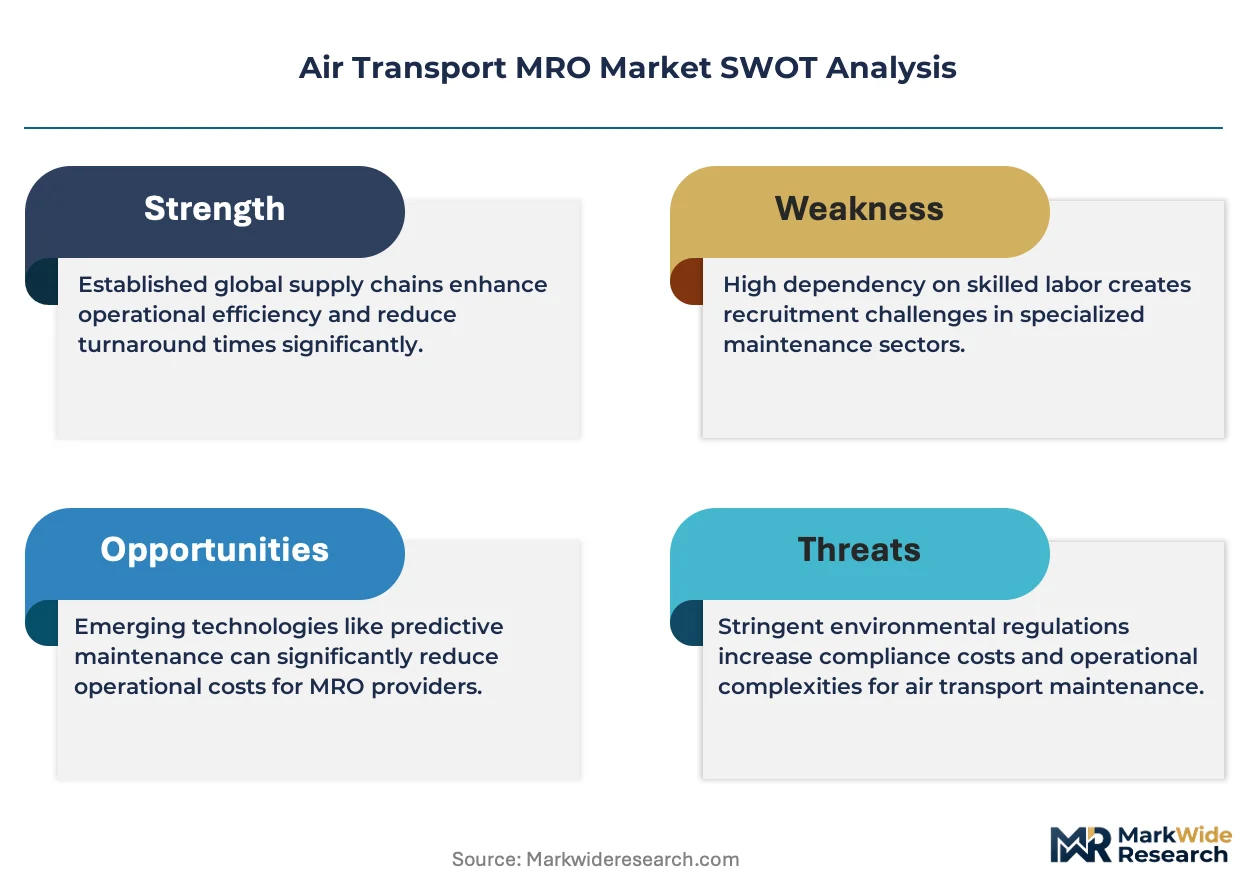
- Regulatory Compliance Costs:Strict FAA and EASA standards require continuous, costly investment in training, certification, and parts traceability, creating high barriers for new entrants.
- Proprietary OEM Parts:Control over intellectual property and parts distribution by engine manufacturers inflates repair costs and limits the scope for third-party MROs.
- Technical Complexity:The intricate design of new-generation engines and airframes demands specialized tooling and expertise, restricting the number of qualified service providers for complex overhauls.
Strategic Opportunities
- Digital Twin Services:Developing component-level digital twins offers a new service for simulating wear and predicting failures with higher accuracy than current statistical models.
- Sustainable Aviation Retrofits:The EU Green Deal creates demand for engine modifications and airframe services that improve fuel efficiency and lower aircraft emissions.
- Support for Aircraft Lessors:Offering integrated, multi-platform MRO programs tailored to the needs of lessors managing diverse and rotating aircraft portfolios is a key opportunity.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians certified in composite repairs and next-generation avionics constrains MRO capacity and increases labor costs across the industry.
- High Capital Expenditure:Servicing new aircraft platforms requires substantial upfront investment in specialized tooling and diagnostic equipment, impacting MRO provider profitability.
- Legacy System Integration:MROs face difficulties integrating modern predictive analytics software with airlines' older, disparate IT and maintenance planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Transport MRO Market |
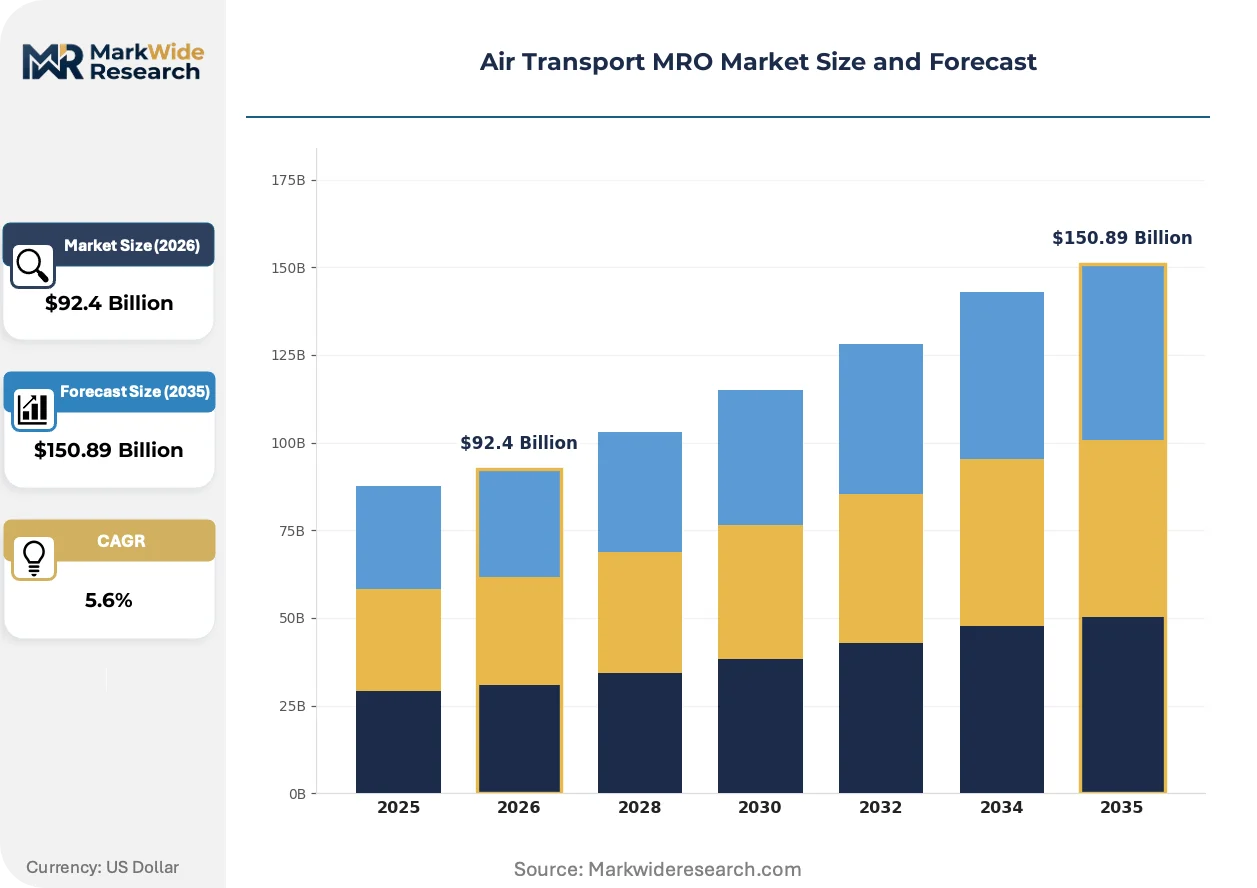
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $150.89 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Base Maintenance, Engine Overhaul, Component Repair, Modification Services, Aircraft Painting Aircraft Type: Commercial Jets, Regional Aircraft, Cargo Planes, Business Jets, Helicopters, Unmanned Aerial Vehicles Customer Type: Airlines, Charter Operators, Leasing Companies, Military Operators, Private Owners, Government Agencies Distribution Channel: Direct Contracts, Third-Party Providers, OEM Partnerships, Online Platforms, Maintenance Hubs, Authorized Dealers |
| Companies Covered | Lufthansa Technik, AAR Corp, Delta TechOps, GE Aerospace, ST Engineering Aerospace, Airbus, MTU Aero Engines, AFI KLM E&M, HAECO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Transport MRO Market Strategic Shifts & Innovations
The digitalization of maintenance and the influence of sustainability mandates are altering MRO service delivery. These forces compel providers to invest in new data analytics and engineering capabilities to meet evolving airline operational and regulatory requirements.
Digital twin modeling creates a virtual replica of an aircraft component or system. Major airlines and MROs are adopting this for high-value assets like engines and landing gear. The technology is virtualizing aspects of physical inspection and failure analysis, enabling more precise, condition-based maintenance interventions.
European Union policies under the Green Deal framework impose stricter emissions targets on aviation. This drives demand for engine modifications, lightweight component retrofits, and maintenance procedures that improve fuel efficiency. The engine overhaul segment is most affected, with providers marketing services to lower an engine's carbon footprint.
Airlines are unbundling MRO contracts to engage specialized providers for tasks like component repair. This shift from single-source agreements disrupts the model for large, integrated MROs. The trend is most visible among low-cost carriers in Europe and Southeast Asia seeking maximum cost flexibility in maintenance.
Air Transport MRO Market Segmentation
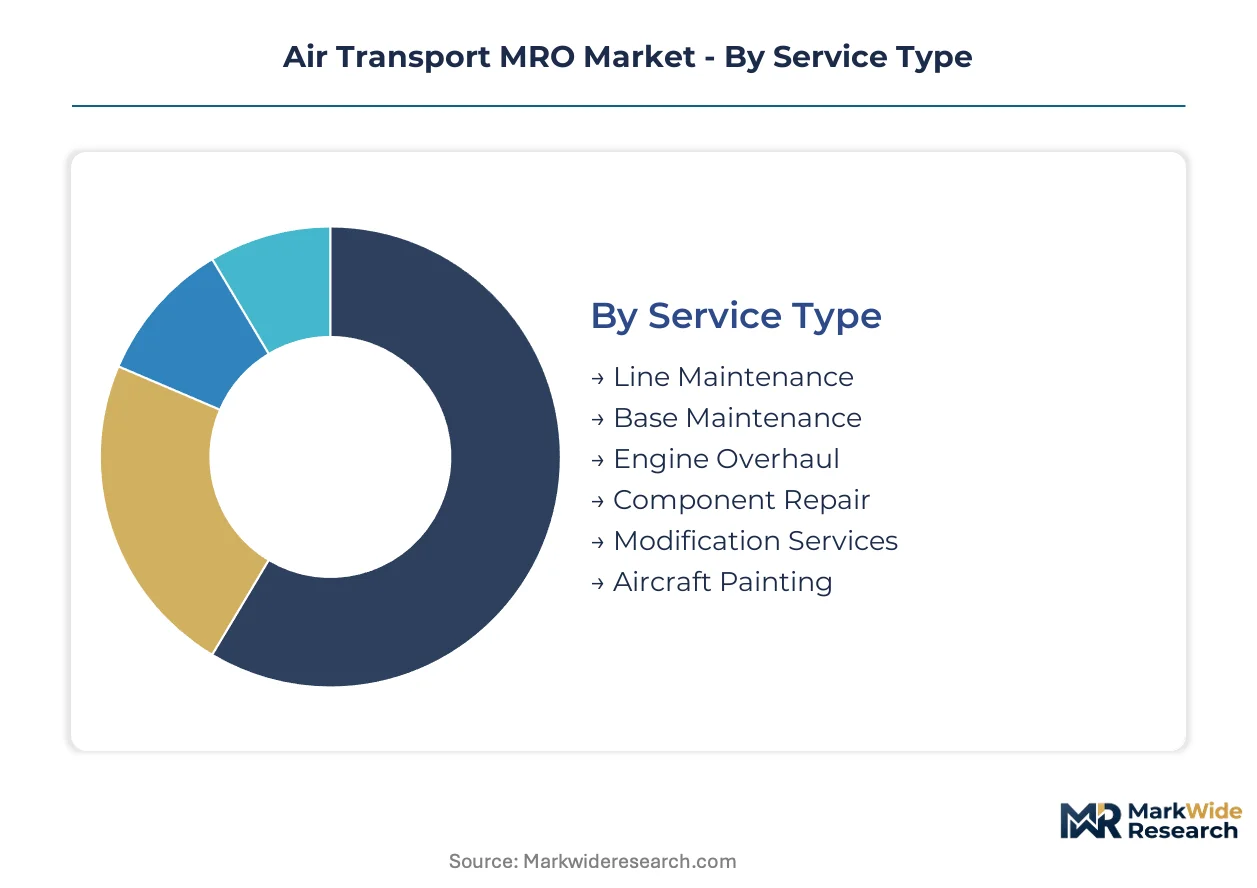
The Air Transport MRO market requires careful segmentation to understand its diverse operational requirements and service delivery models. This analysis breaks down the market by the specific services offered, the types of aircraft maintained, the end-user customer base, and the channels through which these critical services are delivered.
Service Type:
The spectrum of MRO services ranges from routine checks to highly specialized structural and engine work.
- Engine Overhaul:This service involves complete disassembly, inspection, repair, and reassembly of aircraft engines, critical for safety and operational longevity. Demand concentrates in regions with aging fleets and for new-generation engines requiring proprietary technologies.
- Component Repair:This segment focuses on restoring individual aircraft components to airworthy condition, encompassing avionics, landing gear, and auxiliary power units. Demand for these services expands rapidly for new-generation commercial jets due to advanced system integration.
- Line Maintenance:Routine checks and minor repairs at airports ensure immediate airworthiness before flights.
- Base Maintenance:Extensive scheduled inspections and repairs at dedicated facilities cause significant aircraft downtime.
- Modification Services:Upgrades and alterations to aircraft systems or structures enhance performance or ensure compliance.
- Aircraft Painting:Application of specialized coatings for corrosion protection, aesthetic branding, and weight reduction.
Established volume favors Line Maintenance; emerging adoption favors Component Repair.
Aircraft Type:
MRO activities are highly specialized, varying significantly across different aircraft platforms due to design and operational profiles.
- Commercial Jets:These large passenger aircraft, including narrow-body and wide-body models, constitute the largest segment of MRO demand due to extensive flight hours and fleet size. Regulatory oversight from bodies like the FAA drives continuous maintenance compliance for these fleets.
- Cargo Planes:Dedicated freight aircraft require robust maintenance schedules due to high utilization rates and heavy load cycles. The expansion of e-commerce logistics globally increases demand for their specialized MRO services.
- Regional Aircraft:Smaller jets and turboprops serving shorter routes need MRO tailored to their operational cycles.
- Business Jets:Executive and private aircraft demand high-reliability MRO with flexible scheduling.
- Helicopters:Rotary-wing aircraft MRO involves unique challenges related to rotor systems, gearboxes, and specialized controls.
- Unmanned Aerial Vehicles:Emerging MRO needs for drones and UAVs focus on sensor calibration, propulsion checks, and software updates.
Traditional MRO volume relies on Commercial Jets; the fastest-growing trajectory is in Unmanned Aerial Vehicles.
Customer Type:
The diverse client base for MRO services influences contract structures and specialized support requirements.
- Airlines:Commercial carriers represent the largest customer group, seeking comprehensive MRO solutions to ensure fleet airworthiness and operational efficiency. Their increasing reliance on asset-light models creates a larger market for independent MRO providers.
- Leasing Companies:These entities own and manage aircraft fleets, often outsourcing maintenance management, especially during fleet transitions. They require flexible, multi-platform MRO programs to manage diverse portfolios.
- Charter Operators:Companies providing on-demand air travel services often require expedited MRO to minimize downtime.
- Military Operators:Government defense forces need specialized MRO for combat and transport aircraft, adhering to strict national standards.
- Private Owners:Individuals or corporations owning private aircraft demand bespoke maintenance services with high attention to detail.
- Government Agencies:Public sector bodies operate aircraft for various missions, including surveillance, research, and emergency services.
Large-scale MRO consumption originates from Airlines; specialized support is expanding among Leasing Companies.
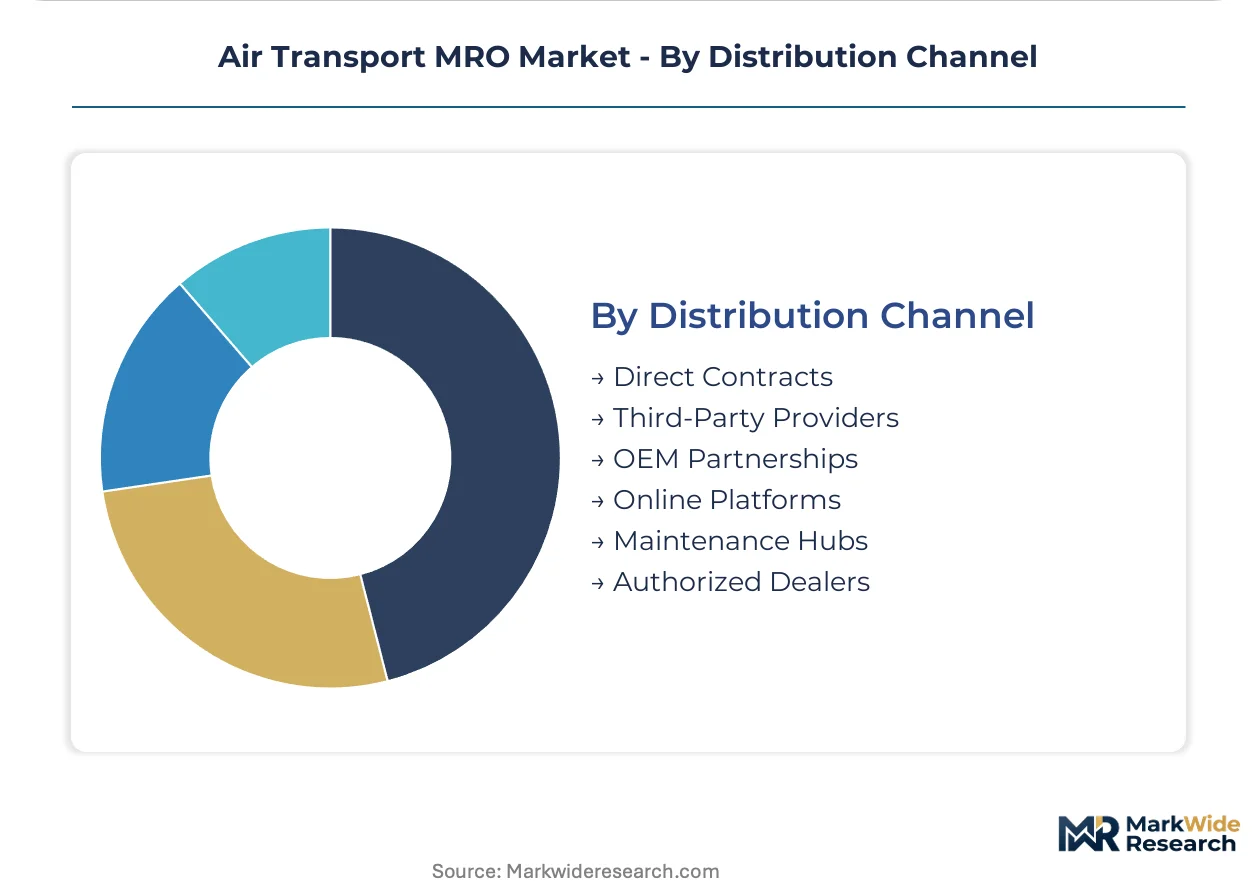
Distribution Channel:
The pathways for MRO service delivery are evolving, impacting accessibility and competitive dynamics.
- Third-Party Providers:Independent MRO organizations offer specialized services across various aircraft types and components, competing with OEMs. Their market share expands as airlines unbundle MRO contracts for cost flexibility.
- Maintenance Hubs:Geographically concentrated facilities, such as those in Singapore and Malaysia, offer integrated MRO services for high-traffic aviation routes. These hubs leverage economies of scale and specialized infrastructure.
- Direct Contracts:Airlines and operators directly engage MRO providers for customized service agreements.
- OEM Partnerships:Original Equipment Manufacturers provide MRO services, leveraging proprietary technology and parts distribution.
- Online Platforms:Digital marketplaces facilitate MRO parts procurement and service scheduling, enhancing transparency.
- Authorized Dealers:Certified entities offer MRO services and parts for specific aircraft manufacturers or systems.
Core service delivery flows through Direct Contracts; strategic growth is visible in Maintenance Hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Union policies, particularly the EU Green Deal, influence engine service requirements by promoting modifications for greater fuel efficiency. This regulatory push encourages MRO providers to invest in sustainable aviation retrofits and advanced digital capabilities. The global air transport MRO market experiences varied regional growth based on fleet age, regulatory frameworks, and strategic investment.
United States
Demand in the United States stems from a large, aging commercial jet fleet and a significant number of business aircraft. The US Federal Aviation Administration (FAA) mandates rigorous maintenance and certification standards for all aircraft. Major MRO facilities in Oklahoma City focus on heavy maintenance and engine overhauls for domestic carriers.
Germany
Germany's MRO market benefits from its strong aerospace manufacturing base and focus on engineering excellence, especially for engine and component repair. European Union Aviation Safety Agency (EASA) regulations drive continuous investment in advanced diagnostic tools. Lufthansa Technik's extensive facilities near Hamburg specialize in complex airframe and engine services for international clientele.
Singapore
Singapore serves as a critical MRO hub for Southeast Asia, driven by high air traffic volumes and aircraft leasing companies. The Civil Aviation Authority of Singapore (CAAS) ensures strict compliance with international airworthiness standards. Changi Aviation Park hosts numerous MRO providers, including ST Engineering Aerospace, offering nose-to-tail services.
India
India's MRO sector is expanding due to a rapidly growing domestic aviation market and increasing demand for localized maintenance solutions. The Directorate General of Civil Aviation (DGCA) oversees all aspects of aircraft maintenance and safety protocols. New MRO facilities emerging in Nagpur address the rising fleet maintenance requirements.
United Arab Emirates
The United Arab Emirates benefits from its strategic geographical location and investment in aviation infrastructure, attracting MRO demand from regional and international carriers. The General Civil Aviation Authority (GCAA) implements robust regulatory frameworks for operational safety. Dubai South's aerospace district is developing as a major MRO cluster, supporting wide-body aircraft maintenance.
Air Transport MRO Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large integrated providers alongside numerous specialized independent MROs. Strategic archetypes include original equipment manufacturers (OEMs) extending their service reach, dedicated third-party MRO specialists, and airline-affiliated MRO divisions. Dominant competitive moves involve strategic partnerships to expand geographic coverage and continuous investment in new technologies for predictive maintenance.
Dedicated third-party MRO specialists like Lufthansa Technik exemplify comprehensive support packages across diverse aircraft platforms, often extending their vast engineering expertise to a broad customer base. Companies such as ST Engineering Aerospace represent providers focused on nose-to-tail service capabilities, catering to multiple aircraft types and leveraging their integrated approach. Meanwhile, GE Aerospace occupies a strong position in the engine overhaul segment, leveraging proprietary technologies and deep OEM integration to sustain market leadership, particularly for its own engine products. These players collectively anchor different segments of the MRO value chain.
| Leading Market Players |
|---|
| Lufthansa Technik |
| AAR Corp |
| Delta TechOps |
| GE Aerospace |
| ST Engineering Aerospace |
| Airbus |
| MTU Aero Engines |
| AFI KLM E&M |
| HAECO |
Cost & Logistics Intelligence
Underutilized MRO capacity across smaller regional facilities drives competitive pricing, influencing supplier investment decisions and service bundling strategies. This dynamic shapes how providers approach new technology adoption and market entry.
Pricing Analysis
FAA and EASA certification levels create the primary pricing spread across air transport MRO services, reflecting the stringent regulatory compliance required. Pricing models predominantly involve contract-based long-term agreements for base maintenance and project-based structures for complex engine overhauls. Price differentiation stems from specialized tooling investments, OEM integration, and guaranteed turnaround times. Pricing pressure intensifies as airlines unbundle MRO contracts, particularly for component repair services. Leasing companies and low-cost carriers exhibit the highest price sensitivity, often seeking maximum cost flexibility.
Supply Chain Analysis
Extended payment terms for specialized parts characterize the air transport MRO supply chain, impacting smaller independent providers. Geographic supply concentration for critical components centers on the United States and Europe, home to major OEM manufacturers. The market relies heavily on proprietary OEM parts, particularly for new-generation engines and advanced avionics. Single-source vulnerability for these specialized components represents a significant supply chain risk. Distribution runs primarily through direct contracts between airlines and MROs, alongside OEM-managed parts networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as digital twin services and predictive analytics threaten to displace traditional physical inspection methods. Incumbents must navigate this technological shift to maintain relevance and service value.
For Market Incumbents:Harden core MRO service offerings by investing heavily in predictive maintenance analytics and digital twin modeling to counter the shift from reactive repairs. Expand capacity in strategic Southeast Asian MRO hubs like Singapore to serve high-traffic routes and mitigate technician skill gaps. Deepen OEM integration through strategic partnerships, securing access to proprietary technologies and parts distribution. Continuous certification investment ensures compliance with evolving FAA and EASA standards.
For New Entrants and Emerging Players:Pursue specialized niches within component repair for new-generation commercial jets, leveraging advanced system integration knowledge. Target aircraft leasing companies with flexible, multi-platform MRO programs tailored to diverse and rotating portfolios. Focus go-to-market strategies on offering cost flexibility and rapid turnaround times for specific, high-demand services. Opportunities exist in sustainable aviation retrofits driven by EU Green Deal mandates.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among integrated MRO providers with long-term service agreements for commercial jet fleets. Long-term viability for this market remains strong due to continuous regulatory oversight and the extended lifespan of aircraft assets. Consider acquiring specialized third-party MROs demonstrating strong digital capabilities in predictive maintenance. The signal to watch is the accelerating adoption of digital twin modeling for high-value components.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Service Development | Simulates wear and predicts failures more accurately, reducing unscheduled downtime for airlines. |
| MRO Hub Expansion (Southeast Asia) | Concentrates specialized capacity to efficiently serve high-traffic aviation routes and leasing company fleets. |
| Proprietary Engine Technology Licensing | Secures access to OEM intellectual property, mitigating proprietary parts control and inflates repair costs. |
| Technician Training Programs | Addresses critical skill gaps in composite repairs and next-generation avionics, increasing MRO capacity. |
| Sustainable Aviation Retrofit Services | Meets EU Green Deal requirements for fuel efficiency and lower emissions, creating new demand segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA and EASA regulatory reports, ICAO publications, and aviation industry trade journals. Primary interviews engaged MRO executives, airline fleet managers, and aircraft leasing company portfolio managers to gather granular market insights. This approach ensured a robust bottom-up and top-down triangulation of market data. Expert perspectives validated quantitative models and qualitative assessments.
Forecast inputs considered aircraft fleet growth, evolving regulatory compliance, and technological advancements across the analysis window. The analytical framework modeled key segments including service type, aircraft type, customer type, and regional MRO capacity. Compound Annual Growth Rates were derived from historical trends and projected operational efficiency gains. Demand for component repair services for new-generation commercial jets informed specific segment projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major OEMs or large independent MROs would shift outcomes. Projections reflect current market dynamics and anticipated technological adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market