
 Aircraft Galley Inserts Market | 2026-2036
Aircraft Galley Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Galley Inserts Market Analysis
The EU Green Deal's aviation decarbonization framework is hardening material specifications for cabin equipment across European carrier procurement mandates. Diehl Aviation leverages its in-house thermoplastic composites capability to meet these lighter-weight requirements. Collins Aerospace anchors its position through integrated galley-lavatory system architectures that reduce installation complexity. Safran SA differentiates via fire-resistant polymer formulations that exceed current smoke-toxicity thresholds.
Aircraft galley inserts are modular cabin components—typically fabricated from aluminum alloys, high-performance thermoplastics, or glass-fiber-reinforced composites—engineered to withstand cyclic pressurization, vibration, and temperature extremes while optimizing stowage density per linear foot of fuselage. Serving Equipment commands the broadest addressable base as airlines retrofit existing fleets with ergonomic tray and cart designs, while Composites represents the fastest-expanding material category as manufacturers pursue gram-level weight reductions per seat. Stainless Steel retains dominance in high-wear zones such as beverage container housings where impact resistance governs replacement cycles.
FAA airworthiness directives and EASA CS-25 certification requirements govern flammability, smoke emission, and structural integrity standards for all galley insert installations on certificated aircraft. The EU AI Act's emerging supply-chain traceability provisions will extend documentation burdens to sub-tier composite resin suppliers. ISO 26800 usability standards are reshaping meal preparation tool geometries to reduce crew repetitive-strain injuries during short-haul turnarounds. Stakeholders must monitor how emerging sustainable aviation fuel mandates redirect airline capital toward airframe efficiency investments that indirectly constrain cabin refresh budgets.
Market Dynamics
EASA's compressed CS-25 certification timelines and the EU Green Deal's material mandates are forcing suppliers to accelerate qualification cycles while simultaneously reformulating composites for lighter-weight, lower-emission cabin architectures.
Growth Catalysts
- Narrow-body fleet renewal:Southwest Airlines and Ryanair are replacing aging galley inserts at scale as they refresh their Boeing 737 and Airbus A320 fleets, creating sustained replacement demand across North America and Europe.
- Southeast Asia MRO expansion:Vietnam, Indonesia, and Thailand are building aviation maintenance ecosystems that localize galley insert refurbishment and reduce turnaround times for regional carriers.
- Thermoplastic composite adoption:High-performance thermoplastics are displacing aluminum in non-structural galley components, driven by gram-level weight reduction targets per passenger seat.
Market Restraints
- Resin supply concentration:Fire-resistant polymer formulations rely on specialized epoxy and PEEK resin suppliers concentrated in Germany and Japan, creating input bottlenecks during demand spikes.
- Certification cost barriers:FAA airworthiness directives require extensive flammability and smoke-toxicity testing that adds eighteen to twenty-four months to new product introductions, freezing out smaller composite fabricators.
- Stainless steel substitution limits:High-wear beverage container housings remain locked into stainless steel due to impact resistance requirements that thermoplastics cannot yet match at comparable lifecycle cost.
Strategic Opportunities
- EU AI Act traceability:The regulation's supply-chain documentation requirements create a service revenue stream for suppliers who can automate resin batch tracking and certification record management for tier-two composite manufacturers.
- ISO 26800 ergonomic redesign:Crew repetitive-strain injury standards are opening demand for redesigned meal preparation tools with anthropometric geometries optimized for short-haul turnaround environments.
- Integrated galley-lavatory architectures:System-level integration contracts are consolidating vendor relationships, rewarding suppliers with cross-functional engineering capabilities spanning refrigeration, waste management, and water systems.
Industry Challenges
- Composite technician scarcity:Thermoplastic layup and autoclave processing skills are concentrated among aerospace airframe specialists, forcing galley insert manufacturers to compete for talent against larger tier-one suppliers.
- Legacy fleet retrofit compatibility:New lightweight inserts must interface with forty-year-old rail mounting systems and power distribution architectures, complicating modular upgrade paths without full galley replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Galley Inserts Market |
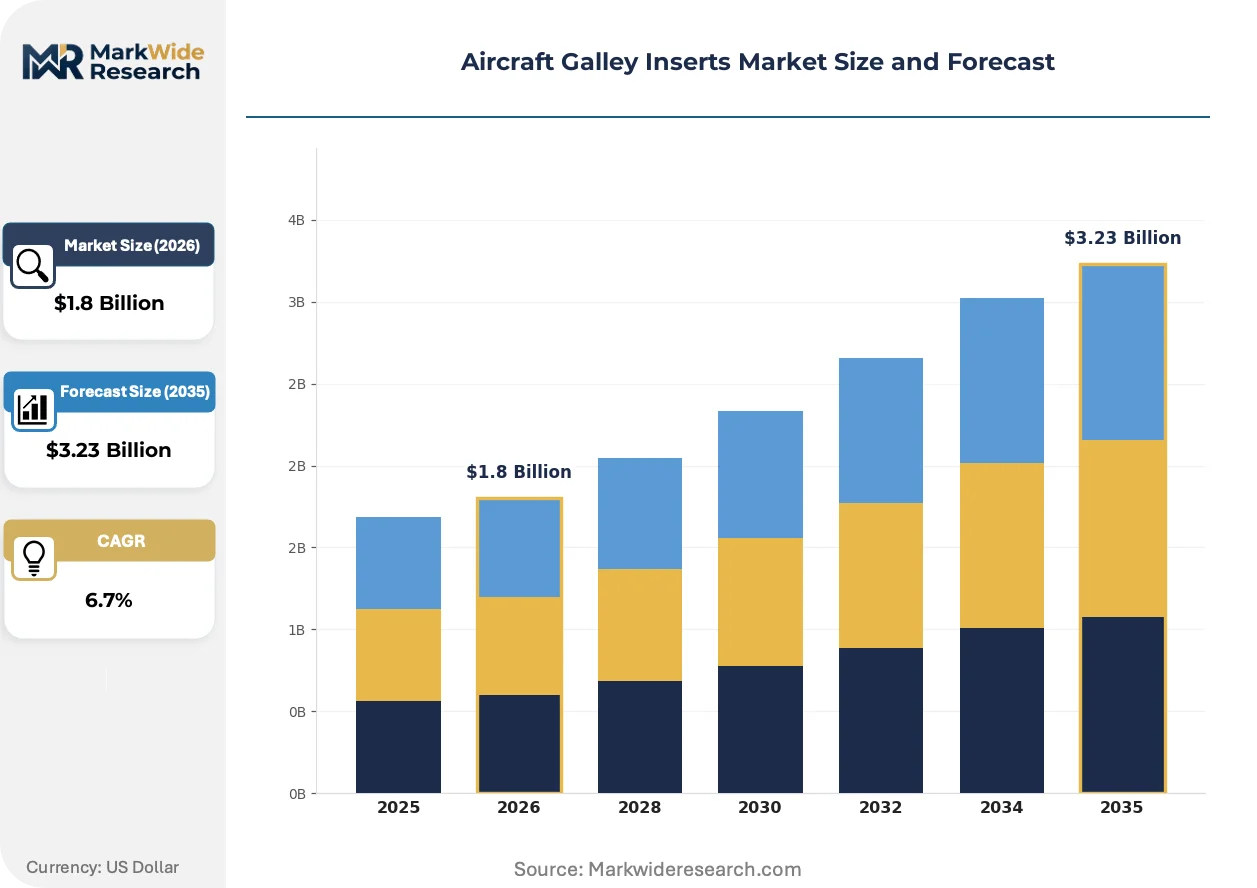
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Storage, Beverage Containers, Serving Equipment, Meal Preparation Tools Material: Aluminum, Plastic, Stainless Steel, Composites Application: Commercial Aviation, Private Jets, Cargo Aircraft, Military Transport End User: Airlines, Aircraft Manufacturers, Catering Services, Maintenance Providers |
| Companies Covered | Diehl Aviation, Panasonic Avionics Corporation, Collins Aerospace, AIM Altitude, Honeywell International Inc., Safran SA, Bucher Leichtbau AG, Reheat Aero Limited, JAMCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Galley Inserts Market Emerging Trajectories
Digital thread technologies and sustainable material formulations are converging to compress development cycles while embedding compliance documentation directly into manufacturing workflows.
Thermoplastic composite welding is rewriting how galley superstructures achieve weight targets without sacrificing fire-resistance ratings. Low-cost carriers retrofitting narrow-body fleets are adopting these bonded assemblies faster than legacy flag carriers. The technology is rewriting supplier qualification criteria, as traditional riveted aluminum expertise becomes less decisive than polymer processing capabilities.
REACH regulation amendments on persistent organic pollutants are tightening restrictions on halogenated flame retardants used in legacy galley composites. European carriers now mandate material declarations covering full substance inventories through the supply chain. Galley insert manufacturers serving Air France-KLM and Lufthansa Group are accelerating non-halogenated polymer formulation programs to maintain contract eligibility.
Airline technical procurement teams are consolidating vendor panels around system integrators capable of delivering galley-lavatory combinations as single contract lines. Maintenance, repair, and overhaul providers in Singapore and Dubai are building in-house insert refurbishment capabilities to capture revenue previously flowing to OEM service networks. This consolidation is most visible in the Gulf Cooperation Council, where Emirates and Qatar Airways have shifted toward ten-year total-cost-of-ownership contracts with penalty clauses for weight overruns.
Aircraft Galley Inserts Market Segmentation
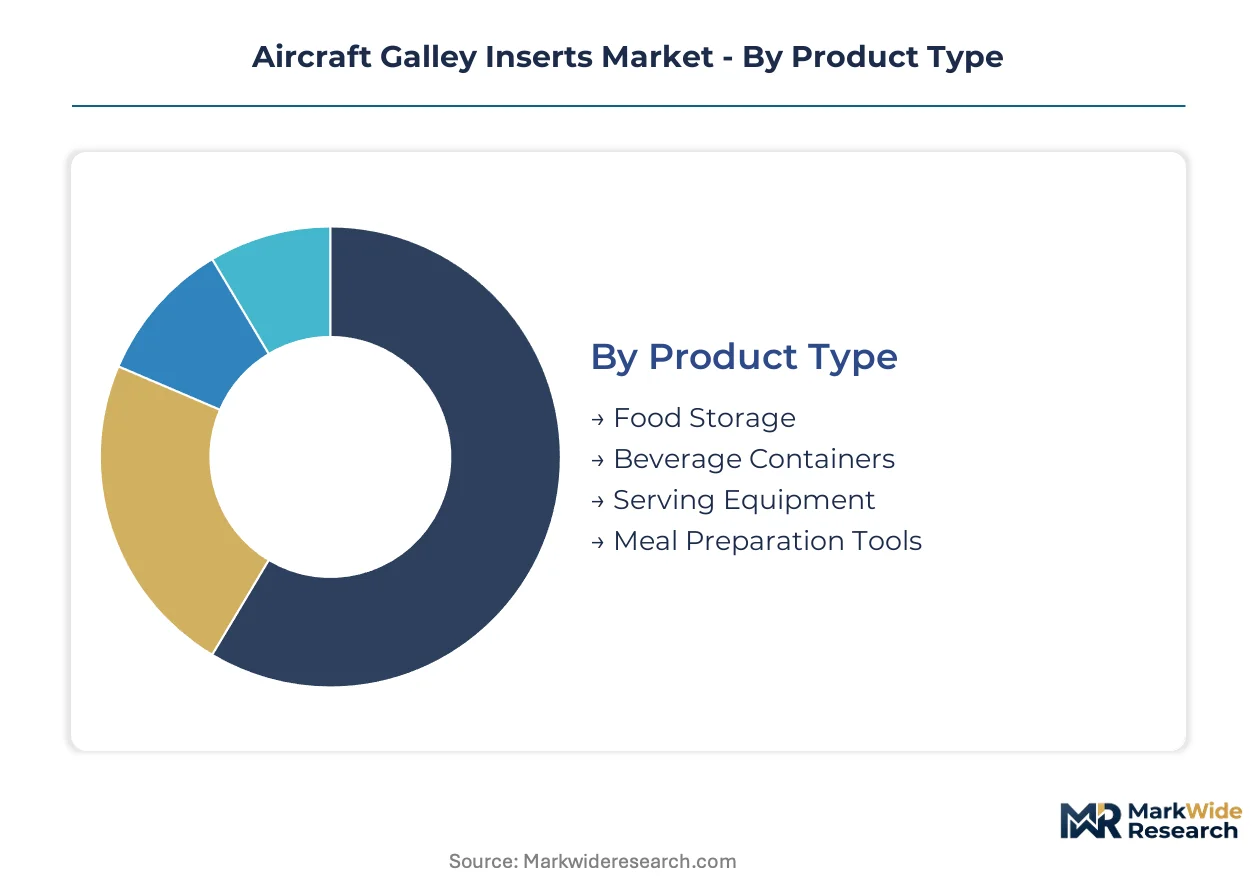
Galley insert procurement decisions split across four distinct axes: product function, material specification, aircraft application, and buyer type. Each axis carries different technical certification burdens and margin profiles that reshape supplier positioning.
Product Type:
Airlines prioritize segments based on replacement frequency and crew ergonomic impact during high-turnaround operations.
- Serving Equipment:Modular tray sets, carts, and dispensing units fabricated from hybrid aluminum-thermoplastic assemblies dominate retrofit volumes across narrow-body fleets. Southwest Airlines and Ryanair renewal programs concentrate demand here as carriers seek ergonomic designs that compress galley service times during 25-minute turnarounds.
- Meal Preparation Tools:Cutting boards, utensil organizers, and thermal containers engineered to ISO 26800 anthropometric standards are gaining specification momentum. Vietnam and Indonesia-based MRO providers are localizing refurbishment capabilities for these high-wear items to reduce OEM dependency.
- Food Storage:Refrigerated compartments and dry stowage modules with integrated temperature monitoring.
- Beverage Containers:Hot and cold liquid reservoirs with specialized sealing mechanisms for pressurized cabin environments.
Volume sits with Serving Equipment; growth tilts toward Meal Preparation Tools.
Material:
Weight-per-seat targets and EASA flammability mandates are rebalancing material procurement priorities across European carrier fleets.
- Composites:Glass-fiber-reinforced and thermoplastic composite formulations achieving gram-level reductions per passenger position. Diehl Aviation's in-house thermoplastic capability anchors demand concentration in Germany, while REACH amendments on halogenated flame retardants are accelerating non-halogenated polymer qualification programs.
- Stainless Steel:Austenitic and ferritic grades retaining dominance in beverage container housings and high-impact zones where thermoplastics cannot yet match lifecycle durability. Japanese and German epoxy and PEEK resin supply concentration creates substitution limits for this material in structural load-bearing applications.
- Aluminum:Legacy 6061-T6 and 7075 alloys in riveted assemblies for cost-sensitive retrofit programs.
- Plastic:Injection-molded commodity and engineering polymers for non-structural cosmetic components.
Stainless Steel captures current volume leadership; Composites trace the steepest expansion trajectory as EU Green Deal procurement mandates harden.
Application:
Certification pathway complexity and fleet renewal timing differentiate addressable demand across aircraft categories.
- Commercial Aviation:Narrow-body and wide-body passenger aircraft galley systems subject to FAA airworthiness directives and EASA CS-25 certification. Fleet renewal at Southwest Airlines, Ryanair, Air France-KLM, and Lufthansa Group drives replacement cycles, with Southeast Asian carriers in Vietnam, Indonesia, and Thailand expanding maintenance ecosystems to capture regional refurbishment demand.
- Private Jets:Business aircraft configurations emphasizing customization density and premium material finishes over unit cost.
- Cargo Aircraft:Converted freighter and dedicated cargo platforms with simplified galley requirements for reduced crew complements.
- Military Transport:Tactical airlift platforms with ruggedized specifications and multi-mission flexibility requirements.
Commercial Aviation concentrates absolute volume; Private Jets offer margin expansion through specification customization.
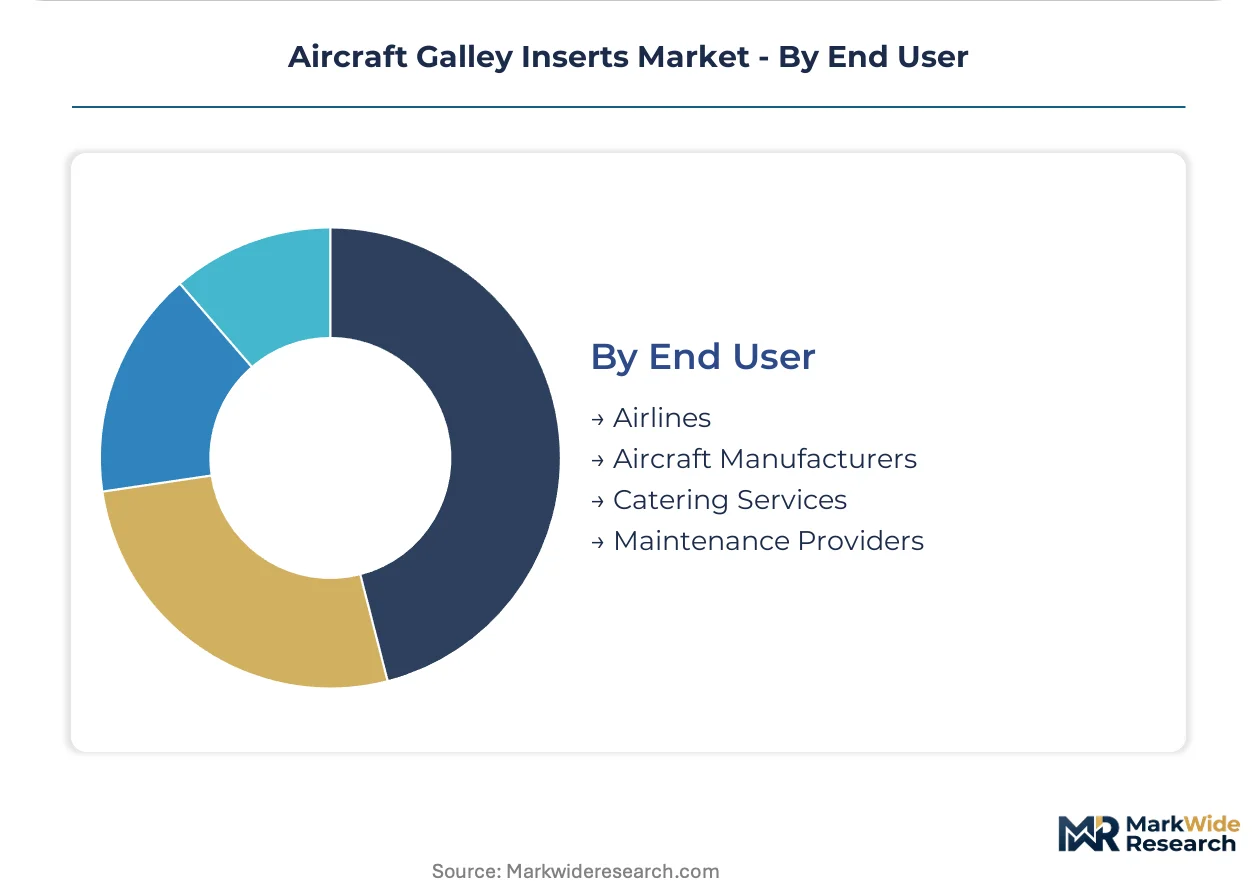
End User:
Procurement authority fragmentation between OEM line-fit, airline direct purchase, and MRO channel insertion shapes supplier go-to-market design.
- Airlines:Direct procurement by carrier technical teams consolidating vendor panels around system integrators capable of galley-lavatory combined contracts. Emirates and Qatar Airways have shifted toward ten-year total-cost-of-ownership agreements with weight overrun penalty clauses, compressing supplier margins while extending contract duration.
- Maintenance Providers:Singapore and Dubai-based MRO operators building in-house insert refurbishment capabilities to capture revenue previously flowing to OEM service networks. This channel is expanding most quickly as regional carriers seek turnaround time reductions and localized supply security.
- Aircraft Manufacturers:Boeing and Airbus line-fit procurement for new production aircraft with integrated galley system architectures.
- Catering Services:Third-party meal providers with limited direct insert procurement authority, primarily specifying consumables and temporary equipment.
Airlines retain volume dominance; Maintenance Providers are climbing fastest as MRO regionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European galley insert engineering concentration through Diehl Aviation's thermoplastic composites campus and EASA certification laboratories serving Air France-KLM and Lufthansa Group procurement mandates.
United States
Southwest Airlines and Boeing 737 fleet renewal programs concentrate replacement demand in Dallas and Seattle aerospace corridors. FAA airworthiness directives govern flammability testing protocols that extend qualification timelines for new composite formulations. Wichita's aviation manufacturing cluster hosts Collins Aerospace integration facilities for galley-lavatory system architectures.
Germany
EU Green Deal material specifications and REACH amendments on halogenated flame retardants drive reformulation programs at Diehl Aviation and Bucher Leichtbau AG. EASA CS-25 certification compression accelerates supplier qualification cycles. Hamburg and Laupheim industrial zones concentrate thermoplastic welding and fire-resistant polymer development capabilities.
France
Safran SA anchors smoke-toxicity threshold innovation through fire-resistant polymer formulations exceeding current regulatory baselines. EU AI Act supply-chain traceability provisions extend documentation requirements to resin batch suppliers. Toulouse aerospace cluster integrates galley insert specifications into Airbus A320 and A350 line-fit procurement workflows.
Singapore
Emirates and Qatar Airways ten-year total-cost-of-ownership contracts with weight overrun penalty clauses compress supplier margins while extending contract duration. Seletar Aerospace Park MRO providers build in-house insert refurbishment capabilities to capture revenue from regional carrier turnaround reduction demands. Civil Aviation Authority of Singapore coordinates with EASA on CS-25 certification reciprocity.
Japan
JAMCO Corporation exemplifies specialized galley insert fabrication for narrow-body and wide-body platforms. Japanese epoxy and PEEK resin supply concentration creates input bottlenecks during demand spikes for fire-resistant polymer formulations. Nagoya aerospace manufacturing corridor hosts composite processing facilities serving Boeing and Airbus tier-one supply chains.
Aircraft Galley Inserts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermoplastic composite capability and integrated system architecture dimensions. The vendor base stratifies into three tiers: aerospace conglomerates with cross-functional engineering capabilities, specialized cabin equipment fabricators with EASA certification depth, and regional MRO providers building refurbishment competencies. Three strategic archetypes dominate: system integrators pursuing galley-lavatory combined contracts, materials specialists advancing non-halogenated polymer formulations, and maintenance providers capturing localized insert overhaul revenue. Competitive dynamics center on M&A activity consolidating vendor panels and strategic partnerships securing resin supply security.
Among aerospace conglomerates, Collins Aerospace and Safran SA exemplify system integration archetypes spanning refrigeration, waste management, and water systems. Diehl Aviation occupies a position within the materials specialization tier through in-house thermoplastic composites capability. Bucher Leichtbau AG represents the specialized fabricator segment with Swiss precision manufacturing heritage. These three anchors illustrate how competitive positioning depends on composite processing depth versus aluminum legacy expertise.
| Leading Market Players |
|---|
| Diehl Aviation |
| Panasonic Avionics Corporation |
| Collins Aerospace |
| AIM Altitude |
| Honeywell International Inc. |
| Safran SA |
| Bucher Leichtbau AG |
| Reheat Aero Limited |
| JAMCO Corporation |
| Others |
Supply Flow & Price Mechanics
Emirates and Qatar Airways ten-year total-cost-of-ownership contracts with weight overrun penalty clauses are forcing suppliers to absorb certification and material costs while compressing quoted rates, reshaping how composite fabricators calibrate margin reserves against resin price volatility.
Pricing Analysis
Gram-level weight reduction guarantees per passenger seat anchor contract valuation, with pricing stratifying across premium, standard, and economy tiers based on EASA CS-25 certification tier and thermoplastic welding capability depth. Cost compression in standard-grade aluminum retrofits is intensifying because Southeast Asian MRO providers are localizing refurbishment and undercutting OEM service rates. Low-cost carriers exhibit acute price sensitivity, while Gulf carriers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Fire-resistant polymer formulations rest on specialized epoxy and PEEK resin producers concentrated in Germany and Japan, creating input bottlenecks during narrow-body fleet renewal spikes. Raw material dependencies span halogen-free flame retardant additives, aerospace-grade thermoplastic prepregs, and austenitic stainless steel for beverage container housings. Single-source vulnerability runs through Japanese resin suppliers serving Boeing and Airbus tier-one networks. Distribution runs through OEM line-fit procurement, airline direct technical purchasing, and Singapore and Dubai-based MRO channel insertion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite technician scarcity across aerospace manufacturing clusters is propping supplier pricing power, as galley insert fabricators compete against larger airframe programs for autoclave and layup specialists.
For Market Incumbents: Lock in resin supply security through long-term offtake agreements with German and Japanese specialty chemical producers before REACH amendments tighten halogenated flame retardant restrictions. Anchor position in integrated galley-lavatory system architectures, as Emirates and Qatar Airways vendor consolidation threatens standalone insert suppliers with contract exclusion. For New Entrants and Emerging Players: Begin with ISO 26800 ergonomic redesign services for meal preparation tools, where Vietnam and Indonesia-based MRO providers seek localized refurbishment partnerships to reduce OEM dependency. Target maintenance provider channel insertion with automated resin batch tracking systems that satisfy EU AI Act traceability mandates for tier-two composite manufacturers. For Investors and Strategic Acquirers: The window for entry favors specialized fabricators with captive thermoplastic composites capability and EASA certification depth, as aerospace conglomerates pursue M&A to fill materials specialization gaps. Watch for REACH amendment enforcement timing as the inflection indicator triggering accelerated non-halogenated polymer qualification spending.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Supply Security Agreement | Long-term offtake with German and Japanese specialty chemical producers mitigates REACH-driven input bottlenecks. |
| Thermoplastic Welding Capability Buildout | In-house polymer processing displaces riveted aluminum expertise as Collins Aerospace and Diehl Aviation consolidate supplier panels. |
| EU AI Act Traceability Automation | Automated resin batch tracking creates service revenue stream for tier-two composite manufacturers facing documentation burdens. |
| Southeast Asia MRO Partnership | Singapore and Dubai-based refurbishment capabilities capture revenue from regional carrier turnaround reduction demands. |
| Integrated Galley-Lavatory System Development | Cross-functional engineering spanning refrigeration, waste management, and water systems rewards vendors with consolidated contract eligibility. |
Methodological Framework
Document review covered EASA CS-25 certification databases, FAA airworthiness directive filings, and REACH amendment substance inventories, complemented by interviews with airline technical procurement directors, MRO operations managers, composite manufacturing engineers, and cabin systems integration specialists. Secondary validation drew from SEC 10-K disclosures of aerospace conglomerates, customs trade data on epoxy and PEEK resin flows, and ISO 26800 ergonomic standard documentation. Bottom-up and top-down triangulation cross-checked segment-level demand against fleet renewal schedules and narrow-body production rates.
Market sizing and growth projections across the analysis window applied a structured analytical framework segmenting by product function, material specification, aircraft application, and buyer type. CAGRs were derived from regression analysis against airline fleet renewal capex cycles and MRO regionalization trends. Industry-specific forecast inputs incorporated Southwest Airlines and Ryanair galley refresh timelines, plus Vietnam and Indonesia aviation maintenance ecosystem buildout trajectories.
Underlying measurement precision varies by segment; serving equipment and stainless steel categories carry tighter precision than emerging thermoplastic composite formulations where supplier qualification timelines remain uncertain. Forecasts reflect assumptions on EASA certification compression rates and EU Green Deal procurement mandate adoption curves. A small set of triggers warrants ongoing watch: REACH amendment enforcement timing, resin supply disruption events, and Gulf carrier contract renegotiation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market