
 Commercial Aircraft Cabin Lighting Market | 2026-2036
Commercial Aircraft Cabin Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Cabin Lighting Market Outlook
Certification-grade LED retrofit specifications is unwinding legacy fluorescent and halogen installed bases across commercial aviation. Collins Aerospace leverages vertical integration into avionics and lighting control architectures to sustain program wins on next-generation platforms. Diehl Stiftung & Co. anchors European supply through manufacturing scale in cabin electronics and lighting systems. Safran competes on technology leadership in smart ambient systems that integrate with in-flight entertainment networks.
Commercial aircraft cabin lighting encompasses the engineered illumination systems installed within passenger and crew compartments, including LED and OLED sources operating at specific color temperatures and dimming curves to support circadian rhythm management and safety protocols. These systems serve the primary industrial purpose of ensuring regulatory compliance for emergency egress visibility while enabling airlines to differentiate passenger experience through programmable ambient environments. LED product types now dominate new installations given their weight reduction and power efficiency advantages, while smart lighting technology captures expanding margin pools as carriers prioritize mood-programmable cabins. Retrofit installation solutions represent the fastest-growing structural segment as aging fleets face mandatory emergency lighting upgrades and carriers seek to avoid full cabin reconfiguration costs.
FAA airworthiness directives and EASA CS-25 certification standards govern photometric output, failure modes, and fire resistance for cabin lighting equipment, creating compliance barriers that favor established suppliers with dedicated aerospace testing facilities. The EU Green Deal and associated CSRD disclosure requirements are pushing European carriers and lessors to prioritize energy-efficient LED conversions that reduce aircraft electrical load and reported carbon intensity. Stakeholders must monitor how emerging ISO standards for human-centric lighting in transport applications reshape specification requirements for circadian-adjustable systems.
Market Dynamics
The commercial aircraft cabin lighting sector is experiencing a structural compression driven by mandatory LED retrofit cycles intersecting with EASA certification deadlines for emergency egress systems. This regulatory-technology collision is forcing accelerated replacement of legacy fluorescent and halogen installations while reshaping supplier qualification requirements.
Growth Catalysts
- EASA CS-25 Emergency Lighting Mandates:Certification requirements for photometric output and failure-mode redundancy are compelling fleet-wide LED upgrades across European-registered aircraft, shortening replacement cycles from fifteen to seven years.
- Retrofit Installation Economics:Narrow-body operators in the United States are prioritizing LED conversions that avoid full cabin reconfiguration costs while delivering immediate electrical load reductions.
- Circadian-Adjustable Systems:Smart ambient lighting technology is capturing premium specification slots as long-haul carriers deploy programmable color temperature systems to reduce passenger jet lag.
Market Restraints
- Aerospace-Grade LED Input Costs:Specialized high-reliability diodes and thermal management substrates face price volatility due to concentrated supply from Japanese and South Korean semiconductor foundries.
- Testing Facility Bottlenecks:EASA and FAA fire-resistance certification protocols require dedicated aerospace testing infrastructure, creating multi-year qualification backlogs for new market entrants.
- Legacy System Interoperability:Existing fluorescent ballast architectures and proprietary control buses resist seamless LED retrofit without substantial wiring harness modifications.
Strategic Opportunities
- China Domestic Fleet Expansion:COMAC C919 production ramp and indigenous narrow-body programs create demand for certified lighting systems with local content preferences.
- ISO Human-Centric Lighting Standards:Emerging transport-sector guidelines for circadian rhythm management are opening specification windows for tunable-white LED systems with melanopic output controls.
- Integrated IFE Convergence:Lighting control networks merging with in-flight entertainment architectures enable new revenue streams through synchronized ambient programming and sponsored cabin environments.
Industry Challenges
- Multidisciplinary Engineering Talent Scarcity:The intersection of photometric design, avionics integration, and regulatory compliance requires specialists rarely available outside established aerospace clusters.
- Extended Certification Timelines:EASA design approval and FAA supplemental type certificate processes for novel LED form factors routinely exceed thirty-six months, compressing product lifecycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Cabin Lighting Market |
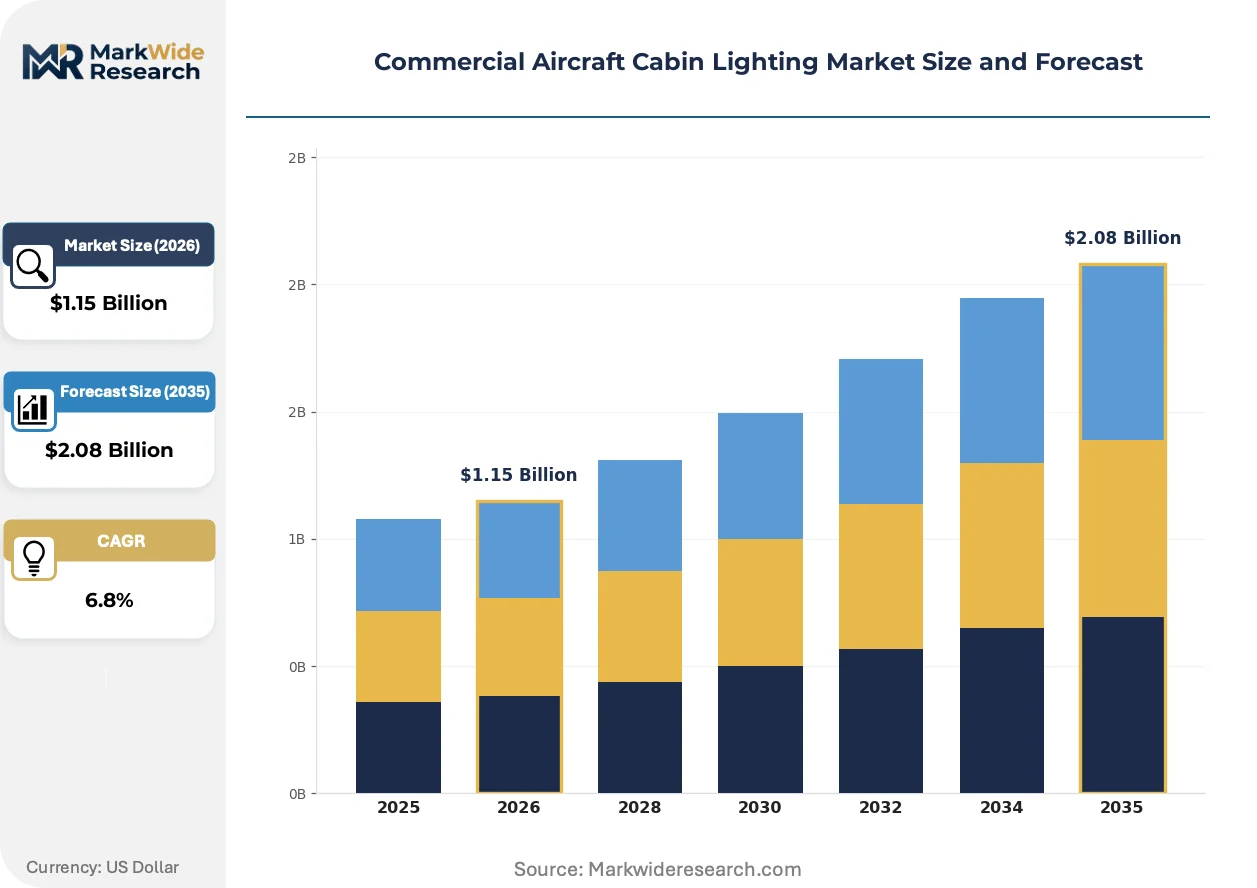
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Halogen, Fluorescent Technology: Smart Lighting, Mood Lighting, Emergency Lighting, Control Systems End User: Airlines, Private Operators, Charter Services, Maintenance Providers Installation: Overhead Systems, Wall-Mounted Units, Cabin Integration, Retrofit Solutions |
| Companies Covered | Collins Aerospace, Honeywell International Inc., Diehl Stiftung & Co., Astronics Corporation, Safran, STG Aerospace Limited, Luminator Technology Group, Cobham Limited, Soderberg Manufacturing Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Cabin Lighting Market Strategic Shifts
Active developments in commercial aviation lighting center on three vectors: solid-state source evolution, regulatory disclosure requirements, and procurement model restructuring. These forces are compressing traditional supplier margins while opening adjacent value pools.
OLED panel technology is fragmenting the upper cabin segment as VIP and business jet operators adopt ultra-thin, surface-conformable illumination for curved architectural elements. Fractional ownership fleets and charter operators are specifying these systems at triple the rate of narrow-body retrofits. The technology is fragmenting established LED supplier positions by introducing new failure-mode profiles and thermal management requirements that favor electronics specialists over legacy lighting houses.
The EU Green Deal and associated CSRD disclosure mandates are reshaping European carrier procurement criteria, requiring documented carbon intensity reductions across electrical subsystems. Lessors and flag carriers must now report aircraft-level energy consumption, creating procurement preference for LED systems with verified wattage reduction metrics. German and French operators are consolidating supplier lists to those offering lifecycle carbon accounting.
Airline technical procurement departments are unbundling lighting system acquisition from full cabin retrofit contracts, creating direct specification authority previously held by integrators. Low-cost carriers in the United States and Southeast Asia are issuing standalone RFPs for LED emergency and ambient systems, bypassing traditional seat and monument suppliers. This disintermediation is most pronounced among carriers with in-house engineering capabilities in Dallas and Singapore.
Commercial Aircraft Cabin Lighting Market Segmentation
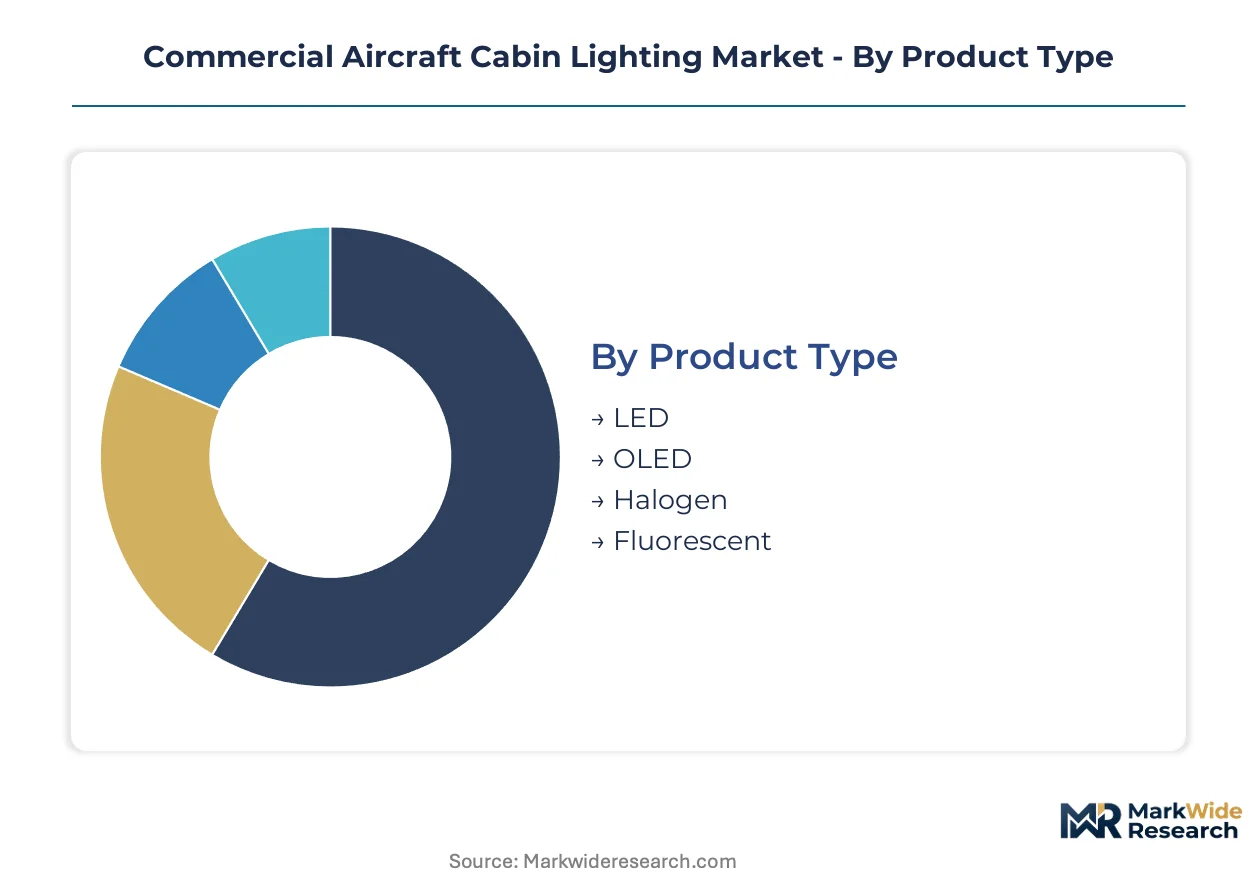
Segmentation in commercial aircraft cabin lighting reveals how procurement authority, certification requirements, and fleet economics fragment demand across distinct technical and commercial boundaries. Airlines prioritize retrofit compatibility and regulatory compliance, while private operators and charter services emphasize customization and passenger experience differentiation.
Product Type:
LED systems dominate domestic fleet retrofits across the United States, China, and Germany, while OLED adoption concentrates in export-oriented VIP and business jet configurations serving Middle Eastern and Asian private aviation markets.
- LED:Solid-state semiconductor sources operating at 2700K-6500K with programmable dimming curves and failure-mode redundancy. Narrow-body operators in the United States are specifying these for mandatory EASA CS-25 emergency lighting upgrades to reduce electrical load and extend generator life.
- OLED:Organic electroluminescent panels offering surface-conformable illumination with sub-2mm thickness and uniform luminance. Demand clusters in fractional ownership fleets and ultra-long-range business jets where curved architectural integration and weight reduction justify premium procurement.
- Halogen:Tungsten-halogen incandescent sources with established airworthiness certification in legacy wide-body platforms.
- Fluorescent:Cold-cathode and compact fluorescent installations facing accelerated replacement cycles under EU Green Deal carbon intensity disclosure requirements.
LED commands the established base. The steepest expansion runs through OLED.
Technology:
Cost tier stratification separates premium smart lighting systems with IFE network integration from standardized emergency lighting meeting baseline regulatory photometric output requirements.
- Smart Lighting:Networked control architectures enabling circadian rhythm programming through tunable-white LED arrays with melanopic output management. Long-haul carriers in Germany and Singapore are deploying these to reduce passenger jet lag on transcontinental routes.
- Mood Lighting:Programmable ambient systems with scene-based color temperature transitions synchronized to flight phases. Low-cost carriers in Southeast Asia specify simplified variants without full circadian calibration to differentiate passenger experience at controlled cost.
- Emergency Lighting:Battery-backed egress illumination meeting FAA and EASA failure-mode redundancy standards.
- Control Systems:DALI and proprietary avionics bus interfaces governing dimming curves and fault monitoring.
Emergency lighting commands the established base. The steepest expansion runs through smart lighting.
End User:
Customer type determines specification authority, with in-house engineering teams at major airlines issuing direct RFPs while private operators rely on completion centers and integrators for system selection.
- Airlines:Scheduled carriers operating narrow-body and wide-body fleets under flag, low-cost, and hybrid business models. Technical procurement departments at carriers with Dallas and Singapore engineering hubs are unbundling lighting acquisition from full cabin retrofit contracts.
- Private Operators:Individual and corporate aircraft owners specifying VIP cabin configurations. Demand concentrates in Saudi Arabia, the UAE, and China where fractional ownership growth drives customization requirements.
- Charter Services:On-demand operators balancing asset utilization with passenger experience consistency.
- Maintenance Providers:MRO facilities executing mandatory LED conversions under EASA and FAA airworthiness directives.
Airlines command the established base. The steepest expansion runs through private operators.
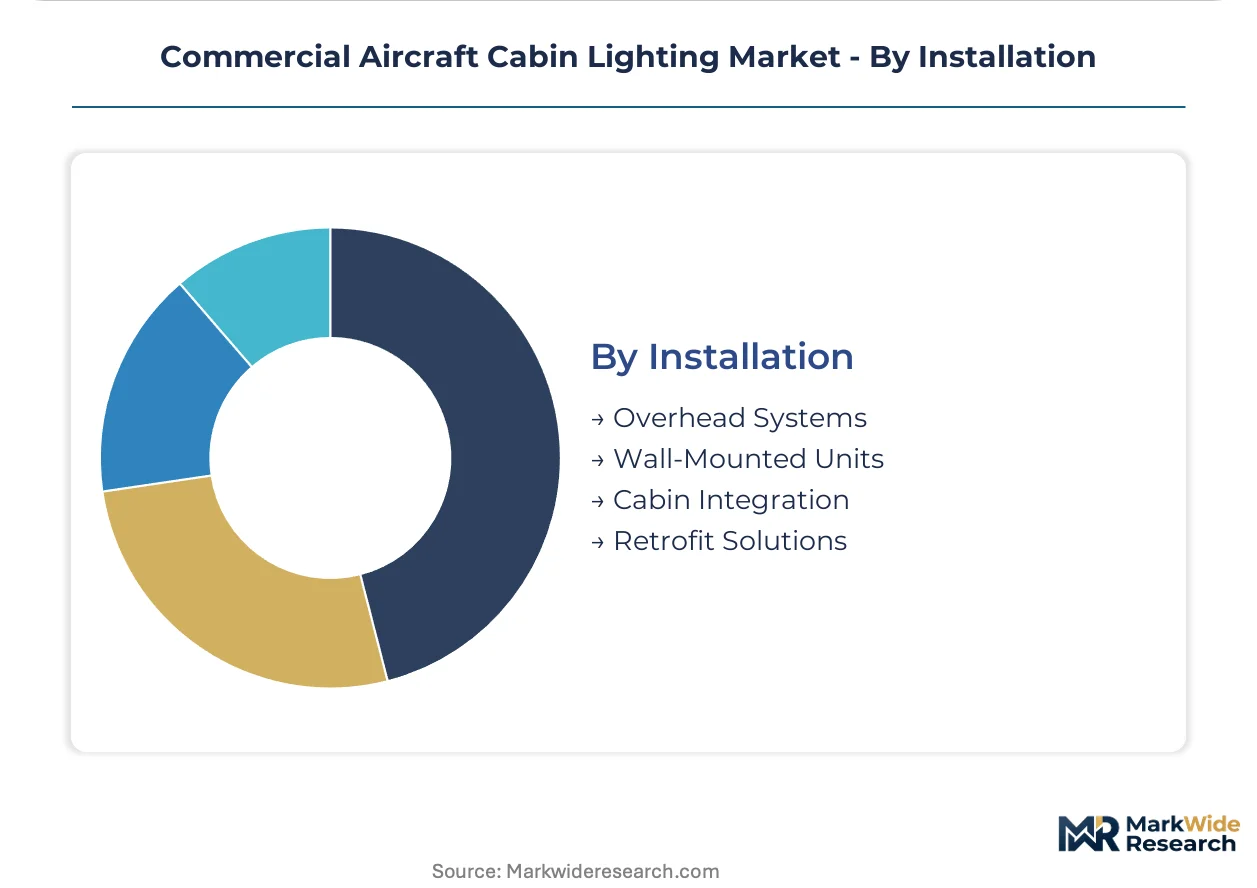
Installation:
Application context separates line-fit installations at original equipment manufacturers from aftermarket retrofit solutions avoiding full cabin reconfiguration costs.
- Retrofit Solutions:LED conversion kits engineered for existing fluorescent ballast locations with minimal wiring harness modification. Narrow-body operators in the United States prioritize these for immediate electrical load reduction without passenger service interruption.
- Overhead Systems:Ceiling-mounted passenger service units integrating reading lights, signage, and emergency illumination. COMAC C919 production ramp in China is generating line-fit demand for certified overhead configurations with local content preferences.
- Wall-Mounted Units:Sidewall wash and accent lighting for architectural feature emphasis.
- Cabin Integration:Monument, lavatory, and galley illumination specified through seat and interior integrators.
Overhead systems command the established base. The steepest expansion runs through retrofit solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with low-cost carriers in Southeast Asia demanding bare-bones LED emergency retrofits while Gulf-based private operators absorb triple-digit premiums for OLED architectural integration. This elasticity divergence fragments supplier pricing power and complicates global product standardization.
United States
Narrow-body operators dominate retrofit volume as American Airlines, Southwest, and United accelerate LED conversions to cut electrical load and extend APU generator life. FAA airworthiness directives on emergency egress visibility are compressing replacement cycles from fifteen to seven years. Dallas-Fort Worth hosts the densest MRO cluster, where in-house engineering teams at major carriers now unbundle lighting procurement from full cabin retrofit contracts.
Germany
Lufthansa Group and Condor are mandating circadian-adjustable smart lighting on long-haul fleets to reduce passenger jet lag on transcontinental routes. EU Green Deal CSRD disclosure requirements are forcing documented carbon intensity reductions across electrical subsystems, favoring LED suppliers with verified lifecycle accounting. Hamburg anchors European supply chain coordination, with Diehl Stiftung & Co. maintaining manufacturing scale in cabin electronics.
China
COMAC C919 production ramp and indigenous narrow-body programs are generating line-fit demand for certified overhead configurations with local content preferences. The country's dual carbon goals are pressuring Air China and China Eastern to prioritize energy-efficient LED conversions in aging fleets. Shanghai and Tianjin concentrate MRO infrastructure executing mandatory upgrades under CAAC airworthiness directives.
United Arab Emirates
Emirates and Etihad are specifying premium smart ambient systems with IFE network integration to differentiate passenger experience on ultra-long-haul routes. Fractional ownership growth in Dubai and Abu Dhabi is driving demand for customizable OLED architectural lighting in VIP configurations. Local aviation authorities are aligning certification protocols with EASA standards to accelerate European-registered aircraft operations.
Singapore
Singapore Airlines deploys tunable-white LED arrays with melanopic output controls on flagship routes to reduce circadian disruption. The city-state's MRO hub at Changi is executing LED retrofits for Southeast Asian low-cost carriers seeking immediate electrical load reduction without passenger service interruption. In-house engineering capabilities enable direct RFP issuance for standalone lighting systems, bypassing traditional seat and monument integrators.
Commercial Aircraft Cabin Lighting Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium specification slots and commodity retrofit volume follow distinct qualification pathways. The market concentrates around three strategic archetypes: diversified aerospace conglomerates with avionics integration capabilities, specialized cabin electronics manufacturers with EASA-certified testing infrastructure, and niche lighting houses focused on VIP architectural applications. Dominant competitive moves include backward integration into semiconductor sourcing to secure aerospace-grade LED supply, and strategic partnerships with IFE network providers to capture converged control system specifications.
Among diversified aerospace conglomerates, Collins Aerospace and Honeywell International Inc. occupy positions spanning avionics and lighting control architectures. Safran exemplifies the technology leadership archetype through its positioning in smart ambient systems. Diehl Stiftung & Co. anchors European supply consolidation with manufacturing scale in cabin electronics. These three represent distinct strategic postures: avionics integration, smart system innovation, and regional manufacturing dominance.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| Diehl Stiftung & Co. |
| Astronics Corporation |
| Safran |
| STG Aerospace Limited |
| Luminator Technology Group |
| Cobham Limited |
| Soderberg Manufacturing Company Inc. |
| Others |
Value Chain & Pricing Dynamics
LED module substitution for legacy fluorescent and halogen sources is simultaneously relocating supply geography toward East Asian semiconductor foundries and compressing pricing power among European legacy lighting houses. This input transition rewards suppliers with captive diode sourcing while penalizing those dependent on spot-market procurement for aerospace-grade components.
Pricing Analysis
Aftermarket service contracts and spares provisioning drive lifetime value capture for certified lighting suppliers. Three-tier pricing structure across premium smart-ambient, standard LED retrofit, and economy emergency-only configurations reflects certification grade and IFE integration depth. Pricing pressure stems from low-cost carriers in Southeast Asia issuing unbundled RFPs for bare-bones LED conversions. Charter operators exhibit lowest price sensitivity, absorbing premiums for programmable circadian systems.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for thermal management substrates and specialized optical polymers. Manufacturing concentrates in Japan, South Korea, and Germany for high-reliability diodes, precision optics, and EASA-certified assembly. Supply chains rest on concentrated gallium nitride wafer supply and aerospace-grade aluminum substrate availability. Single-source vulnerability runs through Japanese foundry capacity for aviation-qualified emitters. Distribution runs through OEM line-fit contracts and MRO channel partnerships for retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as airline procurement departments unbundle lighting specification from full cabin retrofit contracts, creating direct-access niches for specialized suppliers outside traditional integrator networks.
For Market Incumbents: Compound certification infrastructure advantages by deepening EASA and FAA testing facility capacity to capture accelerated retrofit cycles. Secure aerospace-grade LED supply through backward integration or long-term offtake agreements with Japanese foundries. Defend against emerging electronics specialists by merging lighting control architectures with IFE network standards. For New Entrants and Emerging Players: Lead with OLED architectural solutions for fractional ownership fleets in Dubai and Abu Dhabi, where customization premiums offset qualification costs. Target standalone emergency lighting retrofits for narrow-body operators in the United States seeking immediate EASA CS-25 compliance without full cabin reconfiguration. Pursue direct RFP relationships with carriers possessing in-house engineering capabilities in Dallas and Singapore. For Investors and Strategic Acquirers: The market sits at a regulatory-mandate phase that favors suppliers with pre-qualified testing infrastructure and established airline technical relationships. Long-term viability favors acquisition targets combining EASA-certified manufacturing with software-defined lighting control capabilities. Monitor CAAC certification alignment with EASA standards as inflection indicator for Chinese domestic fleet access.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Certification Investment | Accelerates access to European-registered fleet retrofit cycles under CS-25 mandates. |
| IFE Network Integration Partnership | Captures converged lighting-entertainment specifications from Emirates and Singapore Airlines. |
| Aerospace-Grade LED Backward Integration | Secures supply continuity against Japanese foundry capacity constraints and price volatility. |
| COMAC C919 Line-Fit Qualification | Positions for indigenous Chinese narrow-body production ramp with local content preferences. |
| Smart Lighting Software Platform Development | Enables recurring revenue through circadian programming subscriptions for long-haul carriers. |
Study Parameters
The analysis maps LED retrofit specifications, OLED VIP configurations, emergency lighting mandates, and smart ambient systems, each validated through airline technical procurement officers, MRO engineering directors, cabin integrator program managers, and EASA certification specialists. Primary interview intelligence triangulates against FAA airworthiness directive databases, EASA CS-25 certification registries, COMAC production schedules, and airline fleet planning disclosures. Bottom-up segment sizing cross-references with top-down aerospace electronics market estimates.
Consistency checks validated volume and value outputs against aircraft delivery forecasts, fleet age distributions, and mandatory replacement cycle assumptions. Segmentation dimensions include product type, technology tier, end-user category, and installation context across the projection horizon. CAGRs derive from fitted curves to historical retrofit penetration rates and regulatory deadline clustering. Industry-specific inputs incorporate EASA CS-25 photometric requirements and EU Green Deal carbon intensity disclosure trajectories.
Forecasts assume regulatory continuity in EASA, FAA, and CAAC regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market