

UAM Cabin Lighting and User Experience Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UAM Cabin Lighting and User Experience Systems Market Insights
Urban air mobility operators is broadening the addressable base for cabin lighting and user experience systems beyond traditional commercial aviation. Collins Aerospace leverages its avionics heritage to anchor integrated lighting-control architectures for eVTOL platforms. Honeywell International competes through sensor fusion capabilities that merge ambient illumination with flight-state awareness. Safran differentiates via lightweight OLED panel designs optimized for constrained UAM cabin geometries.
UAM cabin lighting and user experience systems encompass electroluminescent and solid-state illumination technologies, human-machine interface controllers, and environmental control software engineered to passenger comfort and situational awareness parameters in electrically powered vertical-takeoff aircraft. LED Lighting occupies the dominant product position due to proven thermal management and lumen-per-watt efficiency in aerospace applications. AI Personalization within the technology dimension is attracting disproportionate engineering investment as operators seek differentiation through adaptive cabin environments. Energy Efficiency as an application priority is reshaping procurement criteria, with sensor-integrated designs that modulate output based on occupancy and flight phase gaining traction among aircraft manufacturers.
FAA Part 23 and Part 27 certification standards govern airworthiness requirements for UAM lighting systems in the United States, while EASA SC-VTOL special conditions establish parallel compliance frameworks in Europe. Both regulators are tightening electromagnetic compatibility and fail-safe illumination mandates that directly shape supplier R&D roadmaps. ISO 26262 functional safety protocols and RTCA DO-160G environmental test standards further constrain design choices for entrants. Stakeholders must monitor evolving type certification timelines and harmonization gaps between FAA and EASA as these will determine which technology platforms achieve scalable deployment.
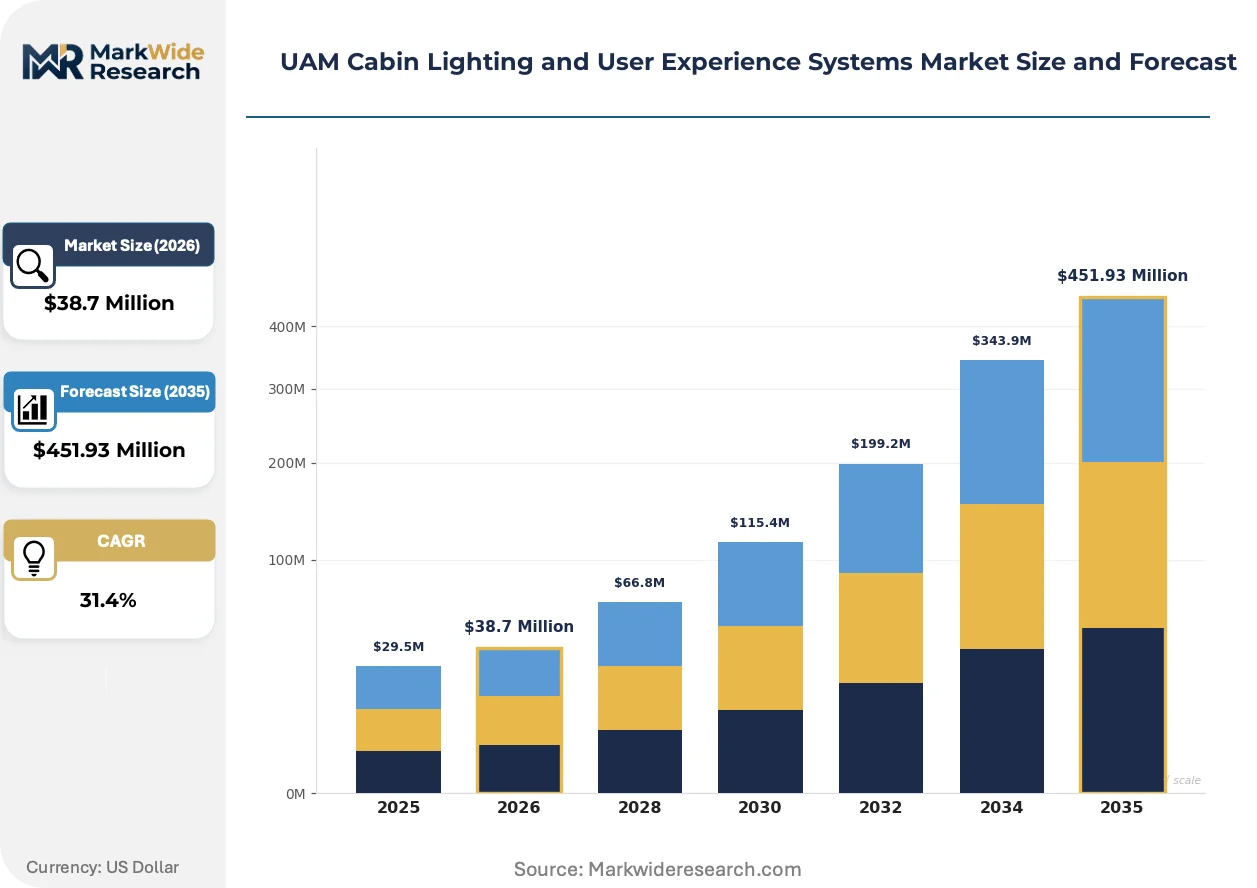
Market Dynamics
FAA Part 23 and Part 27 certification pathways are compressing development timelines for UAM lighting systems, forcing suppliers to front-load electromagnetic compatibility testing and fail-safe illumination validation before airworthiness approvals.
Growth Catalysts
- eVTOL Fleet Expansion:Urban air mobility operators in California and Texas are scaling certified aircraft deployments, creating immediate demand for integrated cabin lighting architectures that meet FAA illumination standards.
- SC-VTOL Harmonization:EASA special conditions for vertical-takeoff aircraft are converging with FAA requirements, reducing dual-certification burdens and accelerating European market entry for qualified suppliers.
- Solid-State Efficiency Gains:LED thermal management improvements are enabling higher lumen output per watt in constrained cabin geometries, satisfying energy budgets of battery-electric propulsion systems.
Market Restraints
- Aerospace-Grade Component Costs:RTCA DO-160G-qualified drivers and controllers command 3-4x commercial pricing, inflating bill-of-materials for low-volume UAM programs.
- Supplier Concentration:Electroluminescent phosphor deposition capabilities cluster with specialty chemical processors in Germany and Japan, creating single-source vulnerability for OLED-adjacent technologies.
- Certification Timeline Uncertainty:Divergent FAA-EASA harmonization gaps on electromagnetic interference thresholds delay type certification completion, freezing procurement commitments.
Strategic Opportunities
- AI Personalization Integration:Machine learning algorithms that modulate ambient illumination based on passenger biometrics and flight phase represent uncaptured value in current cabin specifications.
- Sensor Fusion Convergence:Integration of lighting controllers with flight-state awareness systems creates bundled offering potential beyond standalone illumination hardware.
- Urban Vertiport Networks:Emerging air taxi corridors in Dubai and Singapore are specifying standardized cabin environments, opening design-once-deploy-multiple opportunities.
Industry Challenges
- Functional Safety Engineering Shortage:ISO 26262 expertise for automotive applications does not translate directly to aerospace fail-safe requirements, constraining talent pipelines.
- Integration Complexity:Legacy avionics bus architectures in modified helicopters clash with modern Ethernet-based lighting networks, requiring costly protocol bridging.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAM Cabin Lighting and User Experience Systems Market Trends and Innovations
Distributed intelligence architectures are displacing centralized lighting control in UAM cabins, enabling real-time adaptation without single points of failure. This shift is compressing hardware consolidation timelines while expanding software-defined feature sets.
Edge-computing lighting controllers with embedded ambient sensors are decentralizing illumination decision-making away from master avionics computers. eVTOL manufacturers in the United States are specifying these architectures for 2026-2027 certification programs. The technology is decentralizing supplier power from traditional avionics integrators toward specialized human-machine interface developers.
EASA SC-VTOL special conditions on electromagnetic compatibility are tightening test severity levels for cabin systems above traditional Part 23 baselines. Manufacturers must now demonstrate immunity to high-intensity radiated fields across expanded frequency spectra. European eVTOL programs are responding by front-loading shielding design and filtering component selection.
Buyer specifications are unbundling lighting hardware from installation and certification support, treating these as separately procured service lines. Tier-one airframers are internalizing integration engineering while outsourcing component supply. This pattern is most visible in California-based eVTOL development programs where capital efficiency pressures dominate procurement design.
UAM Cabin Lighting and User Experience Systems Market Segmentation
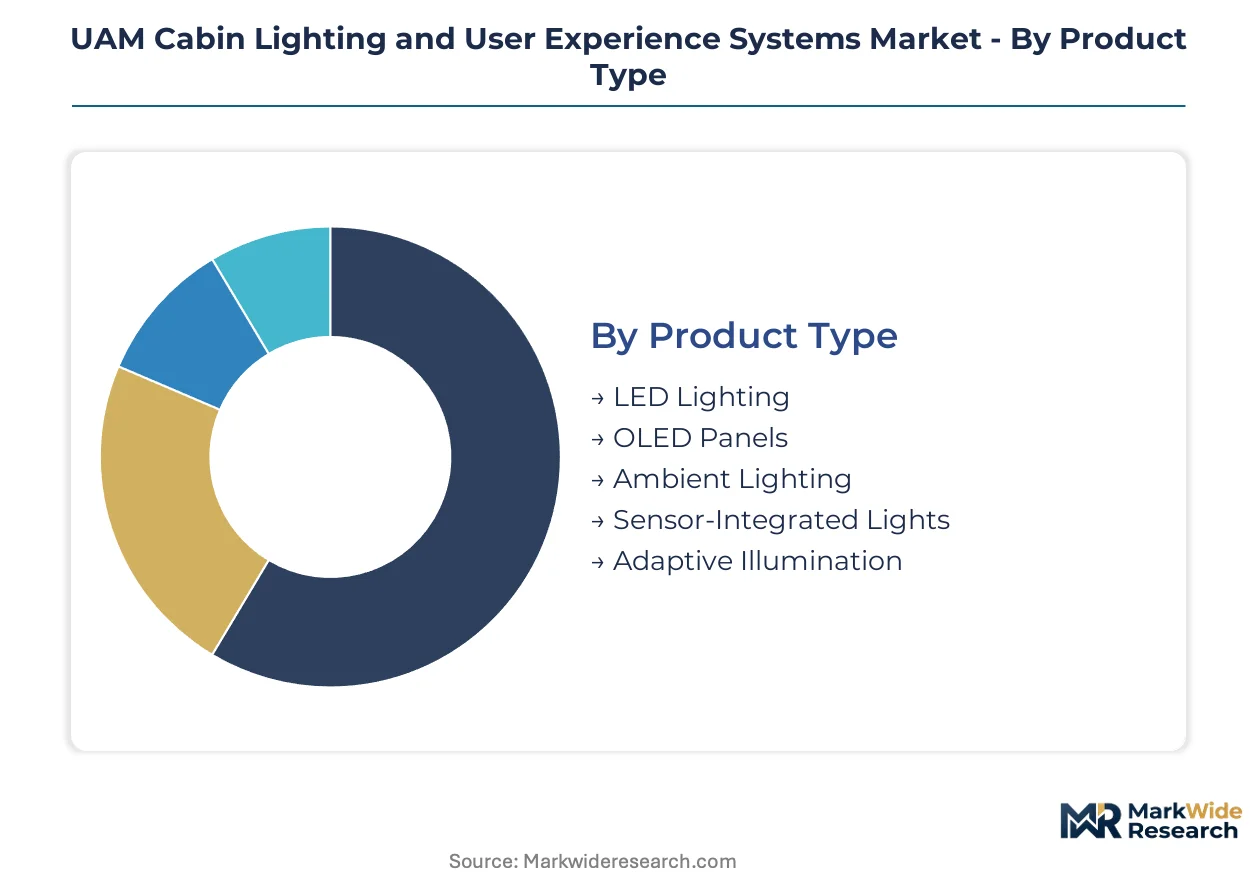
UAM cabin lighting systems fragment across multiple technical and commercial dimensions. Suppliers must navigate divergent certification requirements and integration protocols across each segment boundary. Procurement patterns in California and Texas eVTOL programs reveal which configurations command premium positioning.
Product Type:
Standardization dominates LED and OLED hardware, while adaptive and sensor-integrated variants demand bespoke engineering for each airframe program.
- LED Lighting:Solid-state semiconductor arrays deliver lumen-per-watt efficiency exceeding 150 lm/W in aerospace-qualified packages. Thermal management architectures from Texas-based eVTOL manufacturers specify these for battery-constrained power budgets. FAA Part 23 certification pathways favor proven LED form factors over experimental alternatives.
- OLED Panels:Organic electroluminescent layers enable conformal surface illumination in curved cabin geometries. Safran and specialized chemical processors in Germany and Japan control phosphor deposition capabilities. Weight savings versus LED edge-lit panels attract California airframers pursuing maximum payload efficiency.
- Ambient Lighting:Indirect cove and wash configurations establish baseline cabin atmosphere.
- Sensor-Integrated Lights:Embedded photodiodes and proximity detectors enable occupancy-responsive output modulation.
- Adaptive Illumination:Flight-phase-aware intensity and color temperature adjustment for passenger circadian management.
Most installed capacity flows through LED Lighting. Expansion is steepest in Sensor-Integrated Lights.
Technology:
Touch and voice interfaces anchor near-term deployments, while AI Personalization and gesture recognition require heavier software validation cycles.
- AI Personalization:Machine learning inference at the lighting controller edge modulates ambient parameters against passenger biometrics and flight state. Honeywell International and Collins Aerospace are anchoring integrated architectures around this capability. California eVTOL operators specify adaptive environments as competitive differentiators for premium air taxi services.
- Touch Interface:Capacitive and resistive panels mounted in seatbacks and cabin sidewalls provide deterministic passenger control. RTCA DO-160G environmental qualification for these interfaces is well-established, compressing procurement timelines for Texas-based manufacturers. FAA human factors guidelines govern placement and feedback latency.
- Voice-Control:Natural language processing for hands-free illumination adjustment during critical flight phases.
- Gesture Recognition:Computer vision-based passenger intent detection without physical contact.
- Wireless Connectivity:Bluetooth Low Energy and proprietary mesh protocols for distributed controller synchronization.
Touch Interface carries the largest active install base. AI Personalization is climbing the fastest as operators seek service differentiation.
Application:
Energy Efficiency and Safety Enhancement drive procurement specifications, while Mood Setting and Information Display remain discretionary upgrades.
- Energy Efficiency:Sensor-integrated dimming and daylight harvesting algorithms reduce electrical load on battery-electric propulsion systems. FAA certification for Part 23 aircraft now includes illumination power budget documentation. Texas eVTOL programs prioritize this application to preserve range reserves.
- Safety Enhancement:Emergency egress path marking, cabin evacuation signaling, and flight-attendant alert illumination meet fail-safe regulatory mandates. EASA SC-VTOL special conditions tighten electromagnetic compatibility requirements for these safety-critical functions. European programs front-load shielding validation accordingly.
- Passenger Comfort:General cabin illumination quality and uniformity for reduced fatigue.
- Mood Setting:Chromotherapy and scene-based atmosphere configuration for premium service tiers.
- Information Display:Integrating wayfinding and flight status into illuminated cabin surfaces.
Energy Efficiency absorbs the majority of current engineering hours. Safety Enhancement shows the steepest regulatory-driven expansion trajectory.
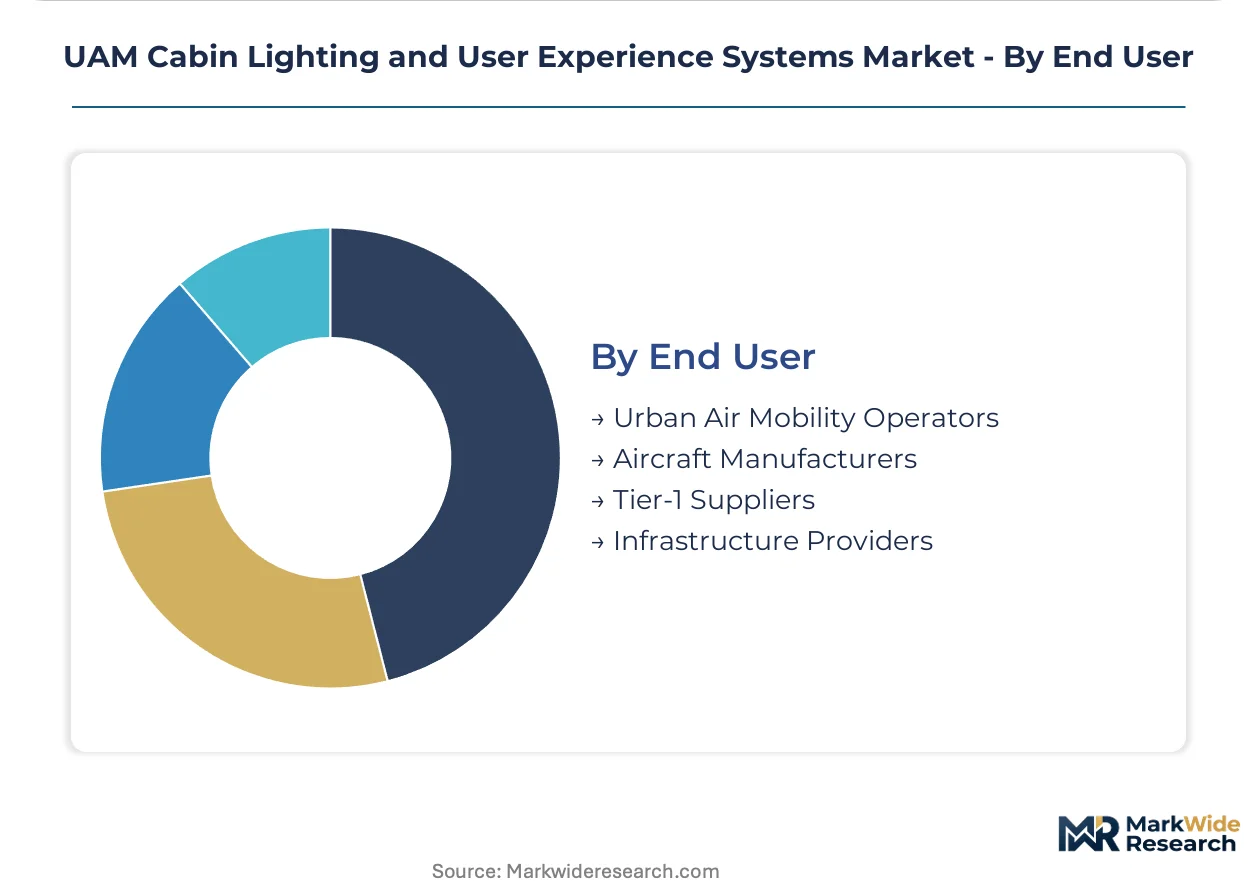
End User:
Aircraft Manufacturers and Urban Air Mobility Operators split procurement authority, with Tier-1 Suppliers and Infrastructure Providers occupying narrower niches.
- Aircraft Manufacturers:Original equipment specifications for type-certified eVTOL and modified helicopter programs. California-based developers internalize integration engineering while outsourcing component supply. FAA airworthiness directives flow through these entities as certification holders.
- Urban Air Mobility Operators:Fleet-wide retrofit and refurbishment procurement for in-service aircraft. Texas air taxi corridors specify standardized cabin environments to simplify maintenance logistics. These operators are unbundling hardware from installation and certification support.
- Tier-1 Suppliers:Avionics and interior systems integrators serving as procurement intermediaries.
- Infrastructure Providers:Vertiport operators specifying ground-based lighting and passenger lounge systems.
Aircraft Manufacturers command the deepest supplier relationships. Urban Air Mobility Operators are gaining procurement share fastest as fleet scales materialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's eVTOL corridor anchors demand concentration for UAM cabin lighting systems, with Texas and European manufacturing clusters following as secondary poles. FAA Part 23 certification timelines in the United States compress supplier development cycles, while EASA SC-VTOL frameworks in Europe impose parallel electromagnetic compatibility standards. Regulatory divergence between these jurisdictions shapes where technology platforms achieve scalable deployment.
United States
California-based eVTOL developers in Silicon Valley and Los Angeles specify adaptive cabin environments as competitive differentiators for premium air taxi services. FAA Part 23 and Part 27 certification pathways mandate electromagnetic compatibility testing and fail-safe illumination validation before airworthiness approvals. Texas manufacturers in Dallas-Fort Worth prioritize energy-efficient LED architectures to preserve battery-electric range reserves.
Germany
Specialty chemical processors in Bavaria and Baden-Württemberg control electroluminescent phosphor deposition capabilities for OLED-adjacent technologies. EASA SC-VTOL special conditions establish compliance frameworks parallel to FAA requirements, reducing dual-certification burdens for qualified suppliers. Stuttgart and Munich host tier-one avionics integrators serving as procurement intermediaries for European eVTOL programs.
Japan
Advanced materials suppliers concentrate electroluminescent phosphor deposition expertise, creating single-source vulnerability for OLED panel technologies. METI industrial standards and JIS certification protocols govern component quality for aerospace applications. Tokyo and Nagoya industrial zones supply precision drivers and controllers meeting RTCA DO-160G environmental test specifications.
Singapore
Urban vertiport network specifications for emerging air taxi corridors demand standardized cabin environments, opening design-once-deploy-multiple opportunities. The Civil Aviation Authority of Singapore aligns regulatory frameworks with EASA SC-VTOL conditions to accelerate type certification acceptance. Changi and Seletar aerospace clusters attract lighting system suppliers targeting Asia-Pacific operator procurement.
United Arab Emirates
Dubai's autonomous aerial vehicle initiatives specify integrated cabin lighting architectures for desert climate operations. GCAA regulations incorporate electromagnetic compatibility thresholds adapted from FAA and EASA baselines. Dubai South and Abu Dhabi industrial zones concentrate infrastructure providers specifying ground-based lighting and passenger lounge systems for vertiport networks.
UAM Cabin Lighting and User Experience Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers bundle lighting controllers with flight-state awareness systems beyond standalone illumination hardware. The vendor base clusters around three strategic archetypes: diversified aerospace conglomerates leveraging avionics heritage, specialized human-machine interface developers exploiting distributed intelligence shifts, and tier-one systems integrators internalizing integration engineering. Competitive positioning hinges on M&A activity targeting sensor fusion capabilities and technology licensing agreements for AI personalization algorithms.
Within the diversified aerospace tier, Collins Aerospace, Honeywell International, and Safran exemplify contrasting technical anchors. Collins Aerospace occupies a position leveraging avionics heritage for integrated lighting-control architectures. Honeywell International sits within the sensor fusion convergence space, merging ambient illumination with flight-state awareness. Safran represents the lightweight materials specialization vector, with organic electroluminescent capabilities concentrated through controlled phosphor deposition supply relationships.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International |
| Safran |
| Thales |
| Panasonic Avionics |
| Diehl Aviation |
| Astronics |
| Luminator Technology Group |
| Heads Up Technologies |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap lighting specialists in Germany and Japan anchor phosphor deposition capabilities, creating disciplined supply allocation that resists price erosion despite California eVTOL manufacturers' volume procurement pressure. Their captive control over electroluminescent chemistry feeds directly into tiered pricing structures where aerospace-grade OLED panels command substantial premiums over LED alternatives.
Pricing Analysis
Distributor margins for RTCA DO-160G-qualified drivers compress at 15-20 percent, while direct-to-OEM contracts for integrated lighting-control architectures secure deeper discounts tied to certification bundling. Three-tier pricing structure across premium adaptive systems, standard LED configurations, and economy retrofit kits differentiates primarily by FAA Part 23 certification completeness and AI personalization capability depth. Pricing pressure stems from Texas-based operators unbundling hardware from installation services, forcing component suppliers to absorb integration engineering costs. Fleet-scale Urban Air Mobility Operators exhibit highest price sensitivity, whereas Aircraft Manufacturers prioritize certification timeline certainty over unit cost.
Supply Chain Analysis
FAA and EASA electromagnetic compatibility qualification gates concentrate electroluminescent phosphor deposition in Germany, Japan, and South Korea, where METI and KOSHA standards align with aerospace material traceability requirements. Supply chains draw from specialty chemical processors for organic emitter substrates, precision semiconductor foundries for LED drivers, and avionics-grade cable harness suppliers. Single-source vulnerability in phosphor chemistry creates exposure to export licensing disruptions. Distribution runs through tier-one avionics integrators in Stuttgart, Dallas-Fort Worth, and Nagoya before reaching California and Texas eVTOL final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAM cabin lighting systems represent a late-cycle quality story as California airframers shift procurement specifications toward AI-personalized adaptive environments that command specification premiums over commodity illumination.
For Market Incumbents: Anchor sensor fusion capabilities through flight-state awareness integration to defend against specialized human-machine interface developers exploiting distributed intelligence shifts. Prioritize backward integration into electroluminescent phosphor deposition to neutralize German and Japanese single-source vulnerability. Accelerate FAA-EASA harmonization lobbying to freeze certification timeline uncertainty that delays procurement commitments. For New Entrants and Emerging Players: Urban Air Mobility Operators in Texas air taxi corridors present the most penetrable buyer archetype, as these fleet operators unbundle hardware from installation support and seek standardized cabin environments for maintenance simplification. Target sensor-integrated retrofit programs for in-service modified helicopters, where legacy avionics bus architectures create integration complexity incumbents avoid. Lead with Ethernet-native lighting networks that eliminate costly protocol bridging. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized human-machine interface developers with ISO 26262 functional safety expertise but limited aerospace certification track records. Long-term viability hinges on SC-VTOL harmonization completion and type certification scalability across multiple eVTOL platforms. The signal to watch is EASA electromagnetic compatibility test severity expansion, which will determine which technology platforms achieve European market entry.| Strategic Initiative | Industry Significance |
|---|---|
| AI Personalization Algorithm Licensing | Machine learning inference at lighting controller edge enables adaptive cabin differentiation for California premium air taxi services. |
| Sensor Fusion Platform Integration | Bundling illumination controllers with flight-state awareness systems expands addressable scope beyond standalone hardware. |
| Phosphor Deposition Supply Agreement | Long-term contracts with Bavarian and Baden-Württemberg chemical processors secure OLED panel weight advantage. |
| Vertiport Network Standardization Partnership | Dubai and Singapore corridor specifications create design-once-deploy-multiple opportunities for cabin environment suppliers. |
| Distributed Intelligence Architecture Launch | Edge-computing controllers displace centralized avionics dependence and shift supplier power toward HMI specialists. |
Research Methodology
Coverage spans the United States, Germany, Japan, Singapore, and United Arab Emirates, with primary inputs from each region's eVTOL development clusters. Primary interviews with FAA certification engineers, EASA SC-VTOL compliance officers, Urban Air Mobility fleet procurement directors, aircraft manufacturer platform engineers, and electroluminescent materials specialists combined with secondary validation from FAA type certification databases, EASA special condition publications, METI industrial standards filings, and RTCA DO-160G test reports. Bottom-up triangulation across component supplier bill-of-materials and top-down demand aggregation from eVTOL production forecasts anchored market sizing.
Rate-of-change decomposition separated volume expansion from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include product type, technology interface, application priority, and end-user procurement authority, with additional granularity on certification pathway alignment. CAGRs derived from logistic diffusion curves fitted to eVTOL fleet deployment schedules and lighting system replacement cycles. Forecast inputs incorporated battery-electric propulsion energy budget constraints and electromagnetic compatibility test severity trajectories.
Underlying measurement precision varies by segment; LED Lighting and Touch Interface categories carry tighter precision than AI Personalization and Gesture Recognition given certification maturity differentials. Forecasts reflect assumptions on FAA-EASA harmonization progress and eVTOL type certification completion rates. A model refresh is warranted upon material change in SC-VTOL electromagnetic interference threshold alignment or urban vertiport network deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.