
 North America Commercial Aircraft Cabin Lighting Market | 2026-2036
North America Commercial Aircraft Cabin Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Aircraft Cabin Lighting Market Analytics
Modular lighting kits that separate power modules from luminaire housings is broadening procurement flexibility for MRO providers and fleet operators. Collins Aerospace leverages its integrated avionics heritage to bundle cabin management systems with lighting controls. Diehl Aerospace sustains engineering partnerships with European and North American OEMs through dedicated production lines in the United States. Safran competes on adaptive mood-lighting algorithms that synchronize with flight phases.
North America commercial aircraft cabin lighting encompasses electroluminescent and solid-state illumination systems engineered to FAA TSO-C30 standards for flammability, electromagnetic interference, and optical performance across altitudes from sea level to 45,000 feet. These systems serve to enhance passenger circadian rhythm management, crew workspace visibility, and emergency egress pathway marking. LED lighting now dominates new installations given its weight reduction and mean-time-between-failure advantages over fluorescent alternatives, while retrofit demand for smart lighting accelerates as carriers seek connectivity-enabled cabin upgrades. Mood lighting commands premium positioning among private aviation and charter operators who differentiate through passenger experience investments.
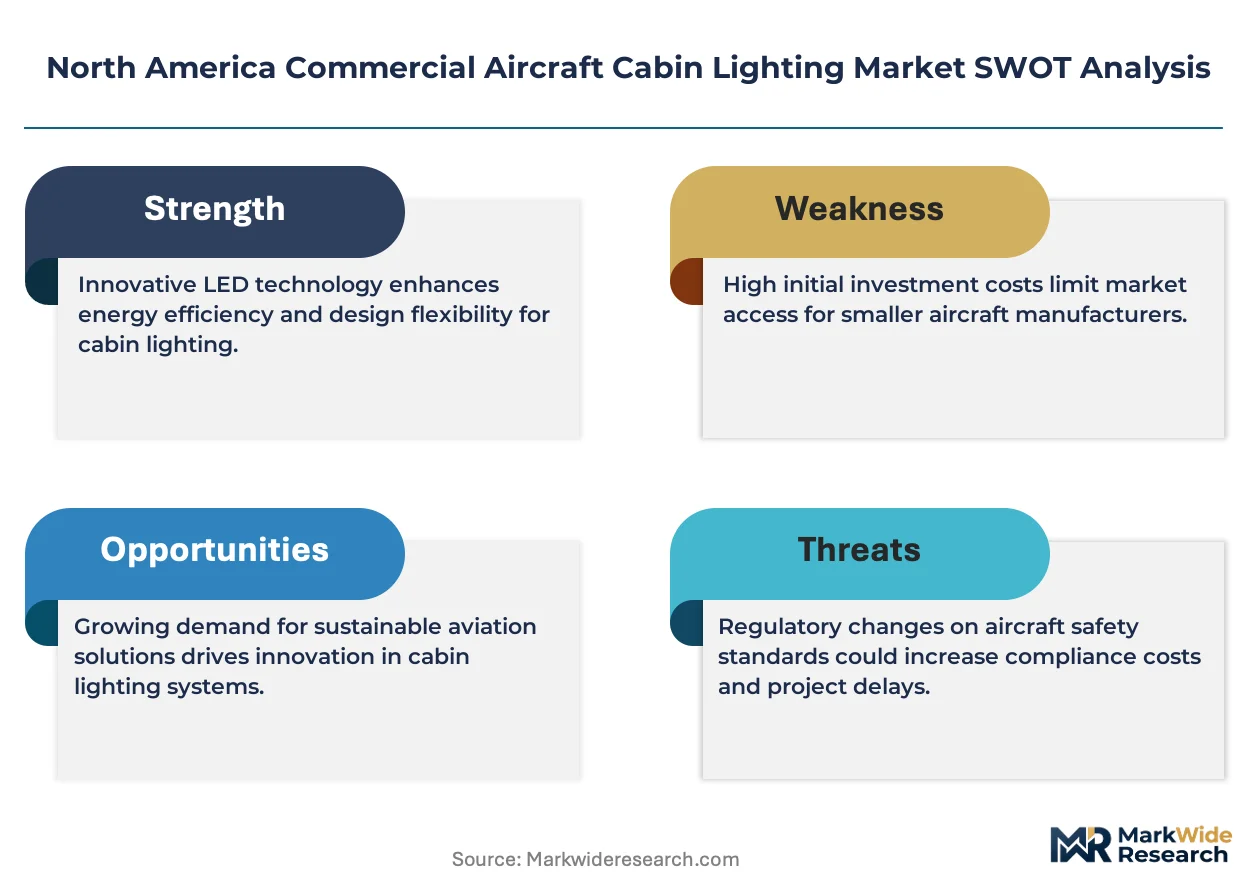
FAA certification under 14 CFR Part 25, EPA restrictions on mercury-containing fluorescent lamps, and OSHA workplace illumination standards collectively shape product design cycles and material selection for cabin lighting suppliers. The FAA's ongoing harmonization with EASA CS-25 standards is creating dual-certification burdens that favor suppliers with transatlantic testing capabilities. Stakeholders must monitor emerging cybersecurity mandates for connected cabin systems as lighting networks integrate with passenger-facing digital platforms.
Market Dynamics
Fleet retrofit cycles and FAA certification timelines are compressing supplier lead times across the North American commercial aircraft cabin lighting value chain. LED system standardization is forcing incumbents to reconfigure production footprints while MRO providers demand modular architectures that reduce aircraft downtime.
Growth Catalysts
- 14 CFR Part 25 harmonization with EASA CS-25:Dual-certification requirements favor suppliers with transatlantic testing capabilities, consolidating procurement toward qualified vendors.
- Narrow-body fleet renewal:United States and Canadian full-service carriers are retrofitting aging single-aisle aircraft with weight-reducing LED systems to extend operational lifespans.
- EPA mercury lamp restrictions:Phasedown of fluorescent technologies accelerates solid-state lighting adoption across commercial aviation maintenance programs.
Market Restraints
- Aluminum and rare-earth magnet price volatility:LED driver components and thermal management materials face input cost pressure from commodity market swings.
- Supplier concentration in US Southeast:Final assembly synchronization at Airbus Mobile and Boeing Charleston creates geographic dependency risk for lighting procurement.
- Electromagnetic interference hardening:FAA TSO-C30 certification for avionics compatibility adds engineering overhead that extends product development cycles.
Strategic Opportunities
- Canadian regional carrier segment:Underpenetrated turboprop and regional jet fleets present retrofit volume as operators modernize cabin interiors.
- Cybersecurity-integrated lighting networks:Connected cabin systems that interface with passenger-facing digital platforms create new service revenue streams.
- OSHA workplace illumination standards:Enhanced crew workspace visibility mandates drive demand for task-optimized lighting configurations in flight decks and galleys.
Industry Challenges
- Systems integration engineering talent:Shortage of avionics-software specialists capable of certifying lighting-to-cabin management system interfaces.
- Legacy fluorescent infrastructure:Existing MRO tooling and technician training for obsolete lamp technologies creates transition friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Aircraft Cabin Lighting Market |
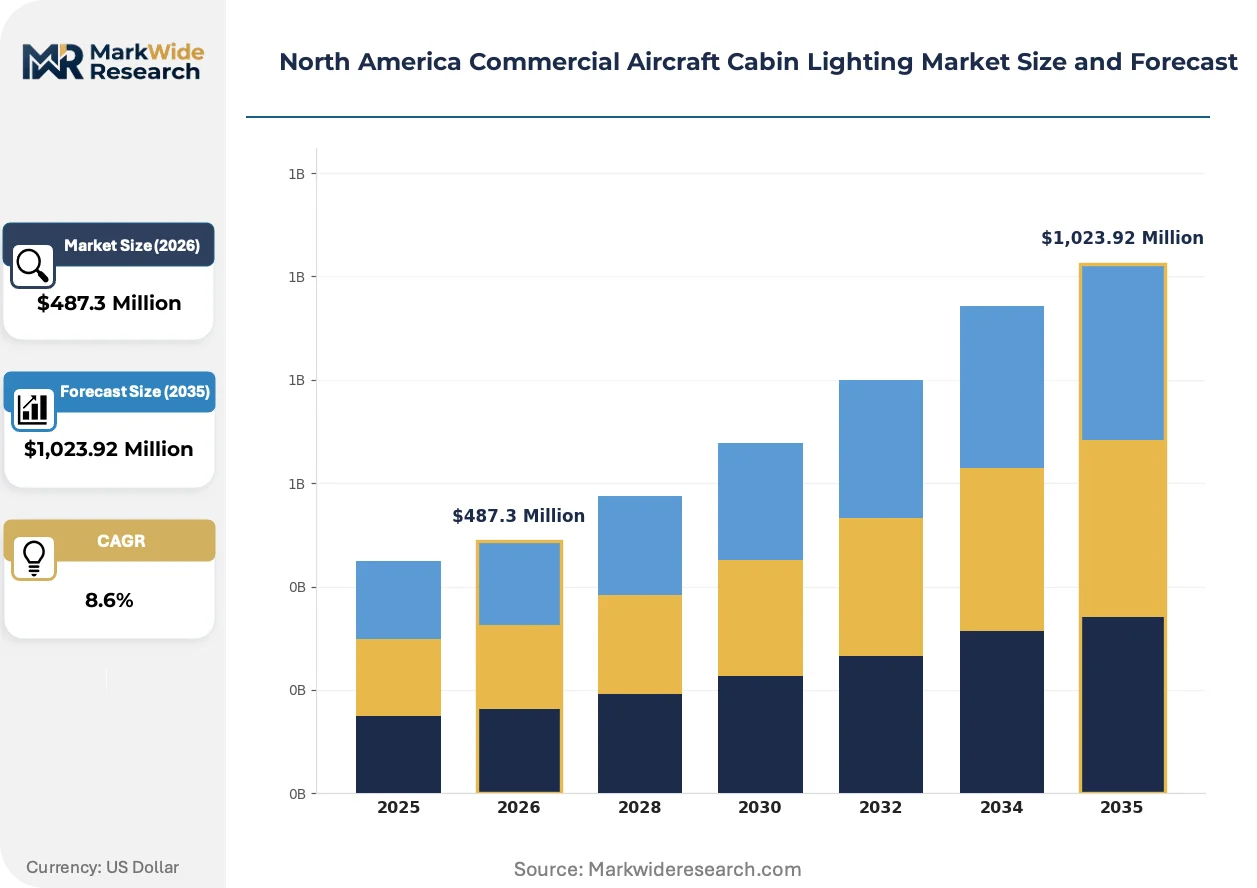
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lighting, Fluorescent Lighting, Halogen Lighting, Ambient Lighting End User: Commercial Airlines, Private Aviation, Charter Operators, OEMs Technology: Smart Lighting, Adaptive Lighting, Conventional Lighting, Mood Lighting Installation Type: New Installation, Retrofit, Upgrade, Maintenance |
| Companies Covered | Astronics Corporation, Collins Aerospace, Honeywell International, Diehl Aerospace, Luminator Technology Group, Safran, STG Aerospace, SCHOTT Technical Glass Solutions, Soderberg Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Aircraft Cabin Lighting Market Evolving Landscape
Modular power architectures and adaptive control algorithms are redefining how lighting systems are specified, installed, and maintained across North American commercial aviation. Three developments are restructuring competitive positioning.
Power-over-Ethernet lighting distribution is decentralizing aircraft electrical architectures by eliminating centralized power conversion units. Regional carriers and charter operators in the United States are adopting these systems fastest to simplify line maintenance. This topology is decentralizing supplier relationships as MRO shops gain direct procurement access to luminaire modules without airframe OEM intermediation.
FAA airworthiness directives on electrical fire suppression are tightening flammability testing protocols for cabin components. Manufacturers must now demonstrate arc-fault containment across integrated power-and-control assemblies. Narrow-body retrofit programs face the steepest compliance burden as they mix legacy harnessing with new-generation LED drivers.
Carrier technical procurement teams are unbundling lighting hardware from installation services, reversing decades of turnkey contracting. Low-cost and ultra-low-cost operators in the US domestic market are driving this disintermediation to capture labor arbitrage through independent MRO relationships. The shift is most visible in Southwest and Southeast hub operations where fleet commonality supports standardized kit deployment.
North America Commercial Aircraft Cabin Lighting Market Segmentation
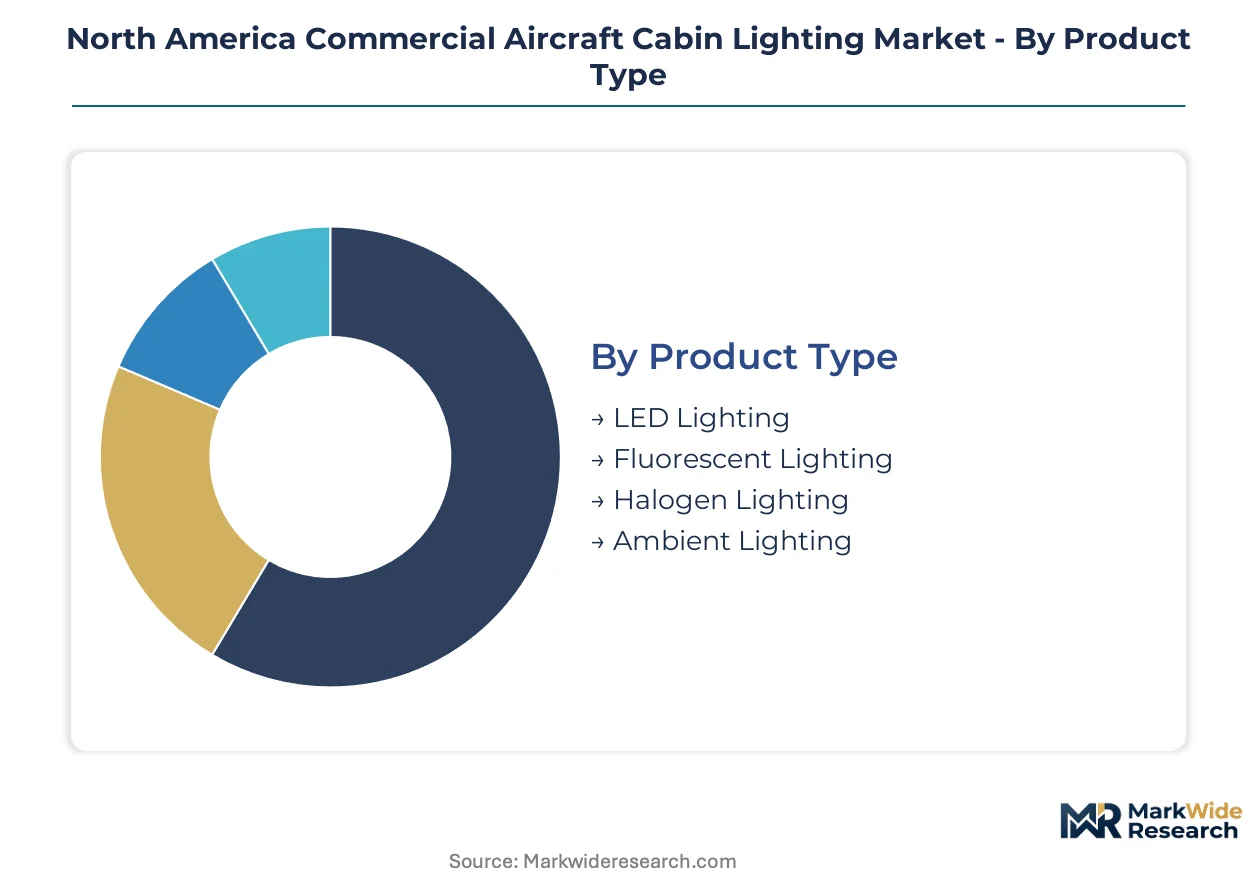
Cabin lighting procurement in North America fragments across four critical dimensions that shape supplier engagement models and certification pathways. Each segmentation axis carries distinct margin profiles, regulatory burdens, and fleet lifecycle dependencies that determine competitive positioning.
Product Type:
Supply concentration among LED module producers in the US Southeast has compressed lead times for solid-state systems while stranding legacy lamp inventories.
- LED Lighting:Solid-state semiconductor arrays deliver 50,000-hour mean-time-between-failure performance with 40% weight reduction versus fluorescent alternatives. Demand concentrates at Airbus Mobile and Boeing Charleston final assembly lines where synchronized procurement mandates FAA TSO-C30 dual-certification with EASA CS-25.
- Fluorescent Lighting:Mercury-vapor discharge lamps face EPA phasedown deadlines that accelerate fleet retrofit cycles across US and Canadian carriers. Legacy MRO tooling and technician certification requirements create transition friction for maintenance providers.
- Halogen Lighting:Tungsten-halogen incandescent systems retain niche applications in cargo compartments and emergency egress marking where extreme temperature tolerance outweighs efficiency concerns.
- Ambient Lighting:Indirect cove and sidewash illumination systems prioritize passenger circadian rhythm management through spectral tuning.
Today's leader: LED Lighting. Tomorrow's challenger: Ambient Lighting.
End User:
Cost tier stratification separates turnkey OEM contracts from unbundled MRO procurement that US low-cost carriers now favor.
- Commercial Airlines:Full-service and low-cost carriers across the United States and Canada drive volume through narrow-body fleet renewal programs. United Airlines and Air Canada retrofit schedules prioritize weight-reducing LED conversions to extend airframe economic life.
- Private Aviation:Business jet operators in Texas, Florida, and California demand premium mood-lighting configurations that differentiate cabin experience.
- Charter Operators:Fractional ownership fleets in the US Southeast require rapid-install modular kits that minimize aircraft downtime.
- OEMs:Boeing Charleston and Airbus Mobile integrate lighting at final assembly with synchronized supply chain coordination.
Commercial Airlines dominate procurement volume. Private Aviation commands the steepest expansion trajectory as experience differentiation intensifies.
Technology:
Application intensity varies sharply between flight-phase automation and static illumination, with connectivity requirements reshaping supplier capability portfolios.
- Smart Lighting:Networked luminaires with Power-over-Ethernet distribution enable remote diagnostics and predictive maintenance. Regional carriers in the United States adopt these systems fastest to simplify line maintenance operations.
- Adaptive Lighting:Algorithmic spectral tuning synchronizes with flight phases to manage passenger circadian disruption on transcontinental routes.
- Conventional Lighting:Fixed-output systems without control network integration serve price-sensitive retrofit segments.
- Mood Lighting:Programmable scene control targets private aviation and premium commercial cabins where passenger experience investment justifies premium positioning.
Smart Lighting leads installed base growth. Adaptive Lighting gains share fastest as FAA cybersecurity mandates for connected cabin systems mature.
Installation Type:
Customer type divergence separates OEM line-fit programs from aftermarket unbundling trends that independent MRO shops exploit.
- New Installation:Line-fit integration at Airbus Mobile and Boeing Charleston requires supplier co-location and synchronized production schedules.
- Retrofit:Fleet-wide LED conversions on aging narrow-body aircraft drive demand across US and Canadian full-service carriers facing EPA mercury lamp restrictions.
- Upgrade:Mid-life cabin refresh programs install mood-lighting and smart control systems without full electrical architecture replacement.
- Maintenance:Unscheduled component replacement concentrates in high-utilization Southwest and Southeast hub operations where fleet commonality supports standardized spare parts deployment.
Retrofit programs dominate near-term revenue. New Installation provides the most stable long-term contracting visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American commercial aircraft cabin lighting industry traces its modern scale to post-war aerospace manufacturing clusters established in Southern California and the Pacific Northwest during the 1950s and 1960s, when defense contractors pivoted toward commercial aviation supplier networks.
United States
FAA airworthiness directives on electrical fire suppression are tightening certification requirements for cabin components across the domestic fleet. EPA restrictions on mercury-containing fluorescent lamps are accelerating LED retrofit programs at major carrier maintenance bases. Final assembly lines at Boeing Charleston and Airbus Mobile in the Southeast drive synchronized lighting procurement from regional supplier networks.
Canada
Air Canada and regional operators are modernizing narrow-body fleets with weight-reducing LED systems to extend operational lifespans. Transport Canada harmonization with FAA 14 CFR Part 25 standards creates dual-certification pathways for lighting suppliers. Montreal and Toronto aerospace clusters concentrate engineering talent for cabin system integration with avionics platforms.
Mexico
Aerospace manufacturing growth in Querétaro and Baja California is expanding supplier presence for cabin component fabrication. Mexican regulatory alignment with FAA standards supports tier-two supplier qualification for US-based OEMs. Guadalajara and Chihuahua industrial corridors are attracting lighting subsystem assembly operations seeking proximity to US Southwest maintenance hubs.
North America Commercial Aircraft Cabin Lighting Market Competitive Landscape
The competitive structure tilts toward integrated system providers with transatlantic certification capabilities. Supplier concentration remains moderate, with tier-one aerospace conglomerates controlling line-fit programs at major final assembly sites while specialized lighting houses compete for retrofit volume. Two strategic archetypes dominate: avionics-integrated platform providers and modular component specialists. Consolidation through strategic partnerships and geographic co-location with OEM assembly lines represent the primary competitive vectors reshaping vendor positioning.
Within the integrated systems tier, Collins Aerospace and Honeywell International exemplify platform providers leveraging avionics heritage to bundle cabin management with lighting controls. Diehl Aerospace anchors the transatlantic specialist archetype through dedicated US production lines sustaining engineering partnerships with North American OEMs. Safran occupies a position in adaptive lighting algorithms, competing on flight-phase synchronization capabilities for circadian rhythm management.
| Leading Market Players |
|---|
| Astronics Corporation |
| Collins Aerospace |
| Honeywell International |
| Diehl Aerospace |
| Luminator Technology Group |
| Safran |
| STG Aerospace |
| SCHOTT Technical Glass Solutions |
| Soderberg Manufacturing Company |
| Others |
Value Network & Pricing Analysis
FAA airworthiness directives on electrical fire suppression are forcing LED module suppliers to absorb arc-fault containment engineering costs, compressing margins on narrow-body retrofit contracts while concentrating procurement leverage among carriers with fleet-scale volume.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FAA TSO-C30 dual-certification tier and volume scale as the primary differentiation drivers. Cost compression in the standard tier is intensifying because MRO providers are unbundling installation services from hardware. Low-cost carriers exhibit the highest price sensitivity, while private aviation operators accept premium positioning for mood-lighting configurations.
Supply Chain Analysis
Avionics-software engineering talent shortages in the US Southeast and Montreal aerospace clusters are constraining supplier expansion timelines. Manufacturing concentrates in the United States, Canada, and Mexico, with production drawing from aluminum heat sinks, rare-earth magnet LED drivers, and flame-retardant polymer housings. Single-source vulnerability around semiconductor components for power conversion units creates exposure. Distribution runs through OEM line-fit programs at Boeing Charleston and Airbus Mobile, with independent MRO channels gaining share in retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA mercury lamp phasedown deadlines and FAA cybersecurity mandates for connected cabin systems generate sustained retrofit demand across North American carrier fleets.
For Market Incumbents: Deepen backward integration into LED driver semiconductor sourcing to offset rare-earth magnet price volatility. Secure dedicated engineering partnerships with Airbus Mobile and Boeing Charleston to defend line-fit positioning against modular specialists. Certification investment in Power-over-Ethernet architectures represents the critical capability lever as MRO channels disintermediate turnkey contracts. For New Entrants and Emerging Players: Canadian regional turboprop operators present the most penetrable buyer archetype, with underpenetrated fleets and Transport Canada harmonization creating dual-certification efficiency. Target rapid-install modular kits for charter operators in the US Southeast seeking minimal aircraft downtime. A go-to-market angle through independent MRO relationships bypasses OEM procurement gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with transatlantic testing capability providers who can amortize dual-certification costs across EASA CS-25 and FAA 14 CFR Part 25 requirements. Long-term viability centers on cybersecurity-integrated lighting networks as passenger-facing digital platform interfaces mature. Watch for FAA cybersecurity mandate implementation timing as the inflection signal for connected cabin system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | TSO-C30 and CS-25 alignment opens procurement access at Airbus Mobile and Boeing Charleston. |
| Power-over-Ethernet Development | Decentralized architectures enable direct MRO channel relationships without OEM intermediation. |
| Cybersecurity Protocol Integration | FAA mandates for connected cabin systems create service revenue attachment to hardware sales. |
| Regional MRO Partnership Network | Southwest and Southeast hub proximity captures high-utilization fleet maintenance volume. |
| Adaptive Algorithm Licensing | Flight-phase synchronization capabilities differentiate premium positioning in private aviation. |
Research Methodology
Bottom-up fleet modeling reconciled against top-down supplier production tracking forms the analytical core of this study. Primary interviews with avionics procurement directors, MRO operations managers, FAA certification engineers, and cabin systems integrators were validated against secondary sources including FAA airworthiness directive filings, EPA mercury lamp restriction timelines, and OEM production schedules at Charleston and Mobile. Triangulation across these data streams ensures segmentation accuracy across product type, end user, technology, and installation type dimensions.
Historical trendline analysis of LED retrofit penetration rates and narrow-body fleet age distributions informed the projection framework. Segmentation modeling spans lighting technology, aircraft platform category, carrier operating model, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new installation line-fit schedules. Forecast inputs include FAA harmonization timelines with EASA standards and EPA fluorescent lamp phasedown compliance deadlines.
Inputs from carrier fleet planning departments and tier-one supplier production disclosures were available through the study window; gaps in regional carrier retrofit intention surveys introduce uncertainty bands around Canadian market sizing. Forecasts reflect documented assumptions regarding certification timeline adherence and commodity price stability. Practitioners should monitor FAA cybersecurity rulemaking progress and rare-earth magnet export policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market