
 Middle East Commercial Aircraft Cabin Interior Market | 2026-2036
Middle East Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Aircraft Cabin Interior Market Foresight
Market Context
Capital-intensity divergence between integrated systems houses and component specialists is redrawing competitive boundaries in the Middle East commercial aircraft cabin interior supply base. Collins Aerospace leverages its full-spectrum avionics-to-interior portfolio to dominate turnkey retrofit programs for Gulf carriers. Safran sustains engineering depth in seating and galley systems through captive R&D centers in the region. Diehl Aerospace GmbH anchors its position with German-certified manufacturing processes adapted to EASA-GCAA dual compliance requirements.
Technical Definition and Segment Structure
The Middle East commercial aircraft cabin interior encompasses the integrated assembly of seating, lighting, storage, lavatory, and partition systems engineered to aircraft-specific flammability, smoke, and toxicity standards under FAR 25.853 and CS 25.853, with primary purpose to maximize passenger density, crew efficiency, and per-flight revenue yield while meeting emergency evacuation timelines. Seating commands the largest value pool as Gulf carriers specify lie-flat business and first-class platforms with composite shells and thermoplastic trim to reduce weight against fuel burn targets. Smart cabin technology represents the fastest-expanding segment, with LED ambient lighting and noise reduction materials migrating from flagship routes to narrow-body fleets as retrofit economics improve.
Regulatory Environment and Outlook
The UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce cabin interior certification aligned with EASA CS-25 and FAA Part 25 standards, while the EU AI Act's emerging safety protocols for connected cabin systems will shape next-generation product development cycles. GCAA mandates on fire-resistant composites and emergency lighting autonomy directly determine supplier qualification timelines and retrofit scheduling for Middle East operators. Stakeholders must monitor how Saudi Arabia's localization requirements under Vision 2030 reshape procurement rules for cabin interior content on aircraft delivered to Riyadh Air and Saudia's expanding fleet.
Market Dynamics
Retrofit scheduling compression for wide-body fleets is forcing Gulf carriers to synchronize interior refresh cycles with heavy maintenance checks, collapsing traditional procurement timelines and privileging suppliers with regional stocking infrastructure.
Growth Catalysts
- Riyadh Air Fleet Expansion:Saudi Arabia's new flag carrier is specifying entirely new cabin configurations for aircraft deliveries, creating immediate demand for premium seating and integrated lighting systems.
- GCAA Fire-Retardant Mandates:The UAE's tightened material standards are accelerating replacement cycles for legacy cabin components that fail updated toxicity and smoke-density thresholds.
- LED Ambient Migration:Narrow-body operators are retrofitting mood lighting systems previously reserved for flagship routes, extending addressable fleet coverage across regional subsidiaries.
Market Restraints
- Composite Input Volatility:Thermoplastic resin prices fluctuate with petrochemical feedstock costs, compressing margin visibility for seating shell manufacturers on fixed-price retrofit contracts.
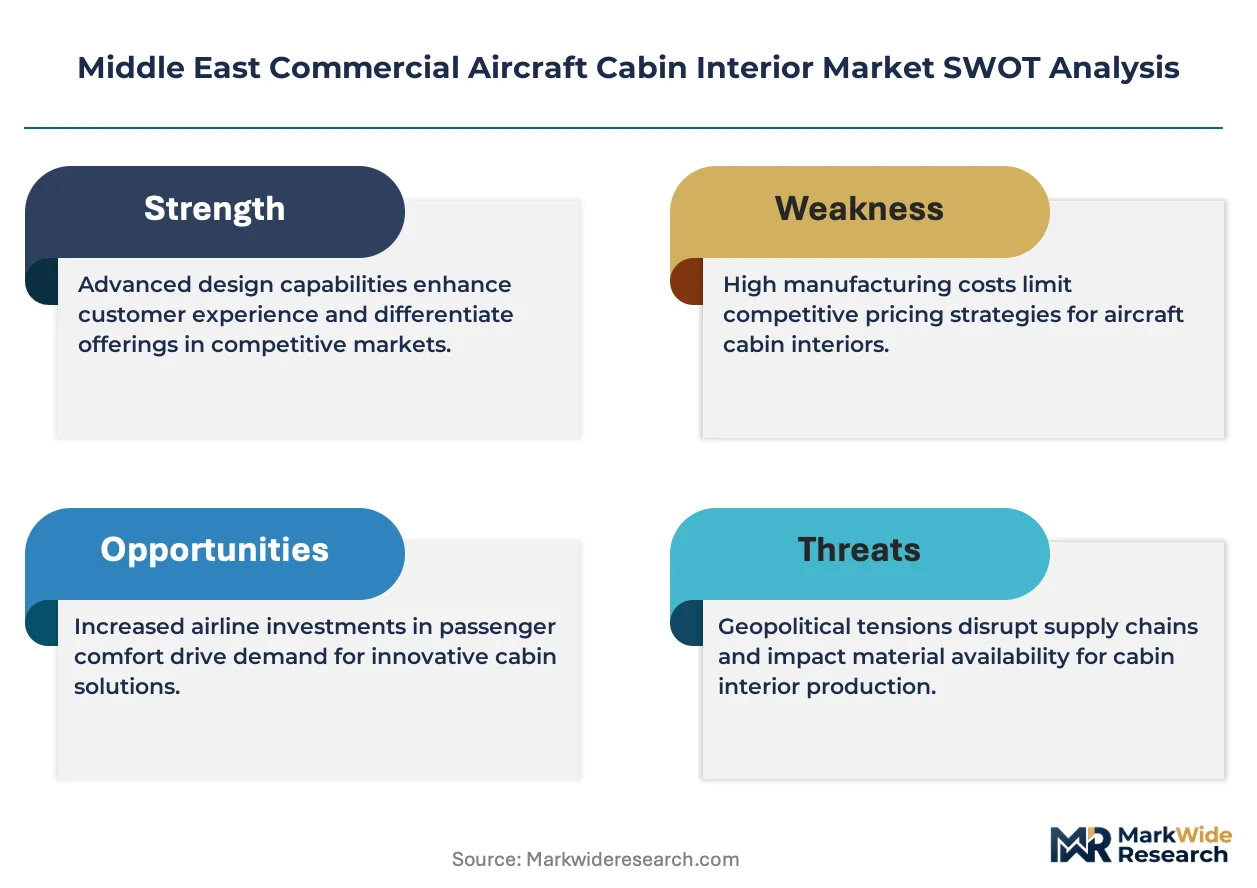
- Dual-Certification Burden:Suppliers must maintain parallel EASA CS-25 and GCAA approval tracks, extending qualification timelines and freezing engineering resources on redundant documentation.
- Integrated Systems Concentration:Turnkey retrofit capability concentrates among full-spectrum avionics-to-interior houses, marginalizing component specialists without captive MRO partnerships.
Strategic Opportunities
- Vision 2030 Localization:Saudi Arabia's domestic content requirements will reshape procurement rules for Riyadh Air and Saudia fleet expansion, creating joint-venture openings for manufacturing transfer.
- Connected Cabin Convergence:Integration of IoT sensors with predictive maintenance platforms enables subscription-based interior health monitoring, shifting revenue from hardware to service annuities.
- Secondary Market Refurbishment:Retired Gulf carrier premium seats enter aftermarket refurbishment channels for lease operators in North Africa and Central Asia, extending asset utility.
Industry Challenges
- Flammability Engineering Talent Scarcity:Specialized expertise in FAR 25.853 and CS 25.853 compliance testing remains concentrated in European and North American laboratories, creating recruitment bottlenecks for regional R&D centers.
- Legacy Fleet Integration Complexity:New-generation lightweight seating platforms require structural floor modifications on aging Airbus A330 and Boeing 777 airframes, complicating retrofit economics.
- Supply Chain Reconfiguration Friction:Relocation of composite manufacturing to GCC free zones demands recertification of entire production lines under GCAA oversight, freezing output during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Aircraft Cabin Interior Market |
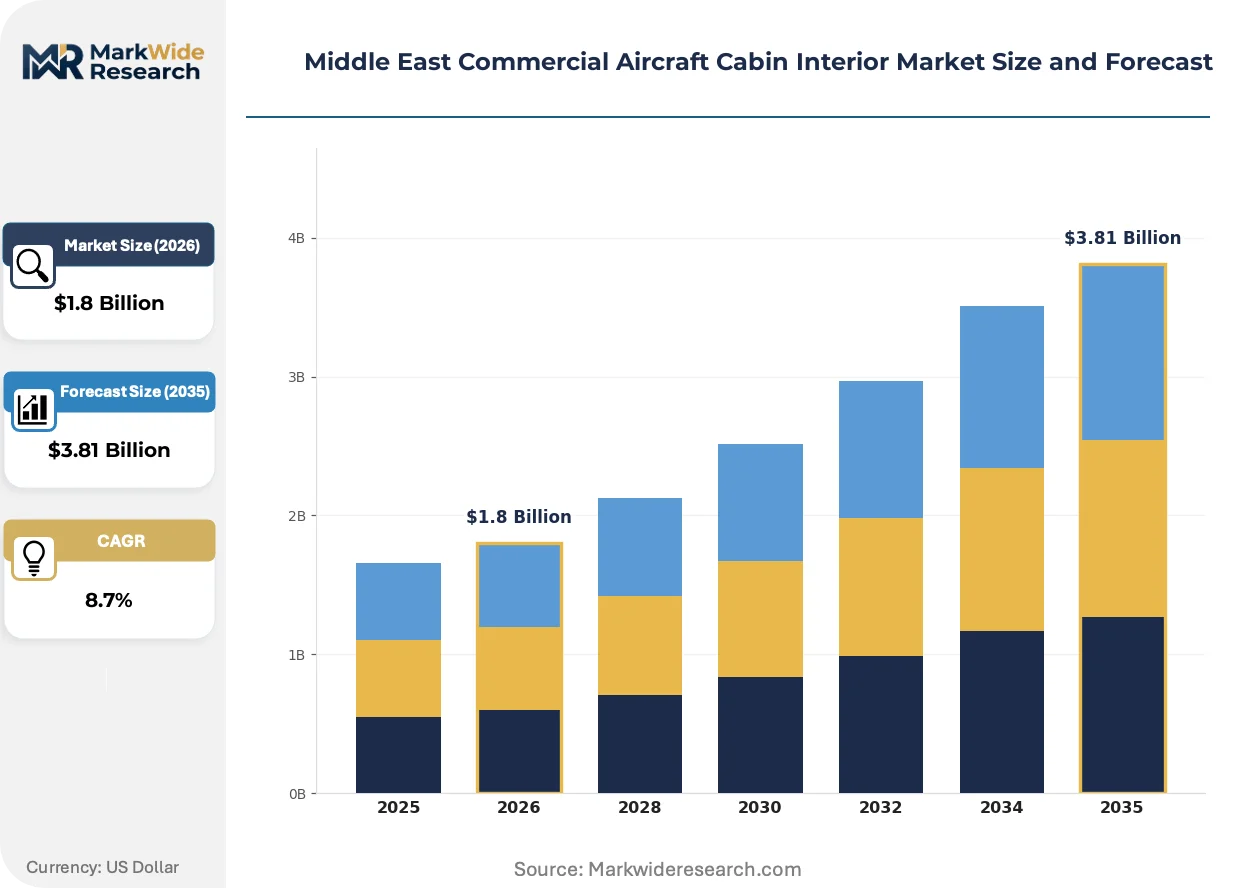
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Lighting, Overhead Storage, Lavatories Material: Aluminum, Composites, Plastic, Fabric End User: Airlines, OEMs, Maintenance Providers, Retrofit Companies Technology: Smart Cabin, Modular Design, LED Lighting, Noise Reduction |
| Companies Covered | Collins Aerospace, Safran, Adient Aerospace, Astronics Corporation, Diehl Aerospace GmbH, Recaro Group, Jamco Corporation, Panasonic Avionics Corporation, Expliseat, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Aircraft Cabin Interior Market Shifts & Advancements
Digital thread integration across design-to-installation workflows is collapsing traditional handoffs between OEM engineering, airline specification teams, and MRO execution, compressing program timelines.
Thermoplastic composite seating shells are decomposing the traditional metal-frame-plus-foam construction paradigm in premium cabin segments. Emirates and Qatar Airways have specified all-composite lie-flat platforms for upcoming A350 deliveries. This material transition is decomposing established supply relationships with aluminum forging houses and redirecting procurement toward specialized polymer processors.
The EU AI Act's emerging safety protocols for connected cabin systems are reshaping product development cycles across Middle East supplier engineering centers. Systems houses must now embed algorithmic transparency documentation and fail-safe autonomy into LED control and environmental management units. First-class and business-class seating with integrated sensor networks faces the steepest compliance redesign burden.
Airline technical procurement teams are consolidating vendor relationships around single-source accountability for full-cabin retrofits rather than assembling component specialists. This concentration is displacing fragmented seating, lighting, and galley procurement committees. The shift is most visible at Etihad Airways, where integrated program management now sits with turnkey systems providers.
Middle East Commercial Aircraft Cabin Interior Market Segmentation
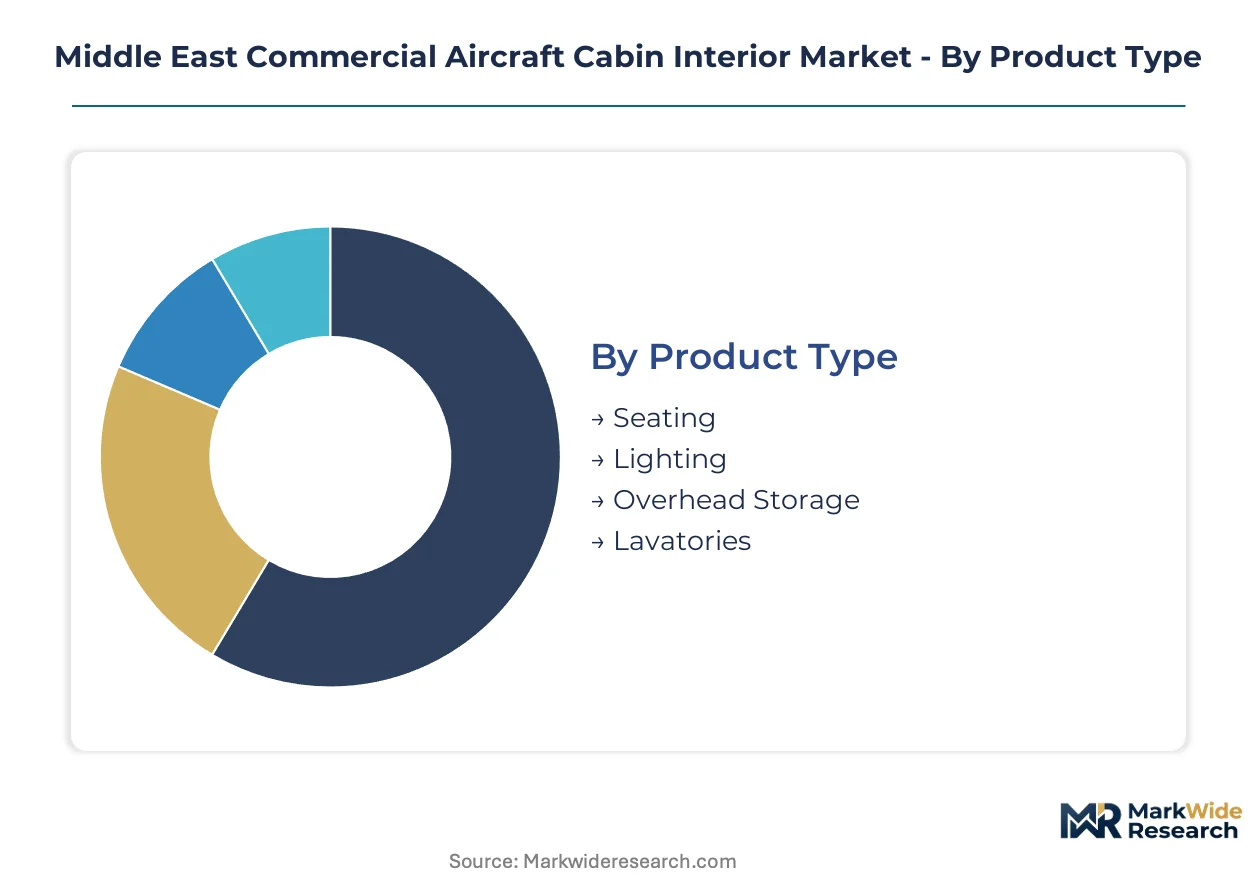
Segmentation reveals how procurement authority and technical specification power distribute across the Middle East commercial aircraft cabin interior value chain. Product type and end-user dynamics determine margin capture, while material and technology choices shape compliance burden and retrofit economics for Gulf carriers.
Product Type:
Substitute pressure intensifies where lightweight alternatives and integrated system architectures displace standalone component sales, particularly in premium cabin retrofits where Gulf carriers consolidate vendor relationships.
- Seating:Composite-shell lie-flat platforms with thermoplastic trim dominate premium cabin specifications at Emirates and Qatar Airways. Demand concentrates in Saudi Arabia as Riyadh Air's fleet launch drives procurement of business and first-class platforms engineered to GCAA fire-retardant standards.
- Lighting:LED ambient systems with programmable mood controls are migrating from wide-body flagship routes to narrow-body regional fleets. Retrofit economics improve as Etihad and Saudia synchronize lighting refresh cycles with heavy maintenance checks.
- Overhead Storage:Stowage bin retrofits on aging Airbus A330 and Boeing 777 fleets require structural floor modifications that complicate installation timelines.
- Lavatories:Vacuum waste systems with antimicrobial surfaces face replacement cycles accelerated by UAE toxicity and smoke-density threshold updates.
Seating retains volume leadership; lighting holds the steepest expansion curve as LED migration accelerates across narrow-body fleets.
Material:
Cost tier stratification separates certified aerospace-grade inputs from commercial alternatives, with thermoplastic composites commanding premium positioning against metal legacy standards.
- Aluminum:Traditional forging-based seat frames face displacement as Gulf carriers specify weight reduction targets against fuel burn metrics.
- Composites:Carbon-fiber and glass-reinforced thermoplastic shells enable lie-flat platforms that reduce mass while meeting FAR 25.853 and CS 25.853 flammability requirements. Procurement concentrates at specialized polymer processors serving Collins Aerospace and Safran regional programs.
- Plastic:Injection-molded cabin interior components face margin compression from petrochemical feedstock volatility.
- Fabric:Fire-resistant upholstery materials must comply with tightened GCAA smoke and toxicity mandates, accelerating replacement of legacy inventory.
Composites gain share fastest in premium seating applications; aluminum retains residual volume in galley and structural subassemblies.
End User:
Customer type concentration shifts procurement influence toward integrated program managers as Gulf carriers abandon fragmented component committees.
- Airlines:Full-service carriers across the UAE, Saudi Arabia, and Qatar now consolidate vendor accountability with single-source turnkey providers rather than assembling seating, lighting, and galley specialists separately.
- OEMs:Airbus and Boeing line-fit programs for Riyadh Air deliveries specify entirely new cabin configurations, bypassing traditional aftermarket channels.
- Maintenance Providers:MRO execution houses in Dubai and Jeddah require regional stocking infrastructure to meet compressed retrofit timelines synchronized with heavy maintenance checks.
- Retrofit Companies:Specialized interior refurbishment firms face marginalization without captive partnerships to full-spectrum systems houses.
Airlines retain specification authority; maintenance providers are climbing the fastest as retrofit scheduling compression privileges regional execution capability.
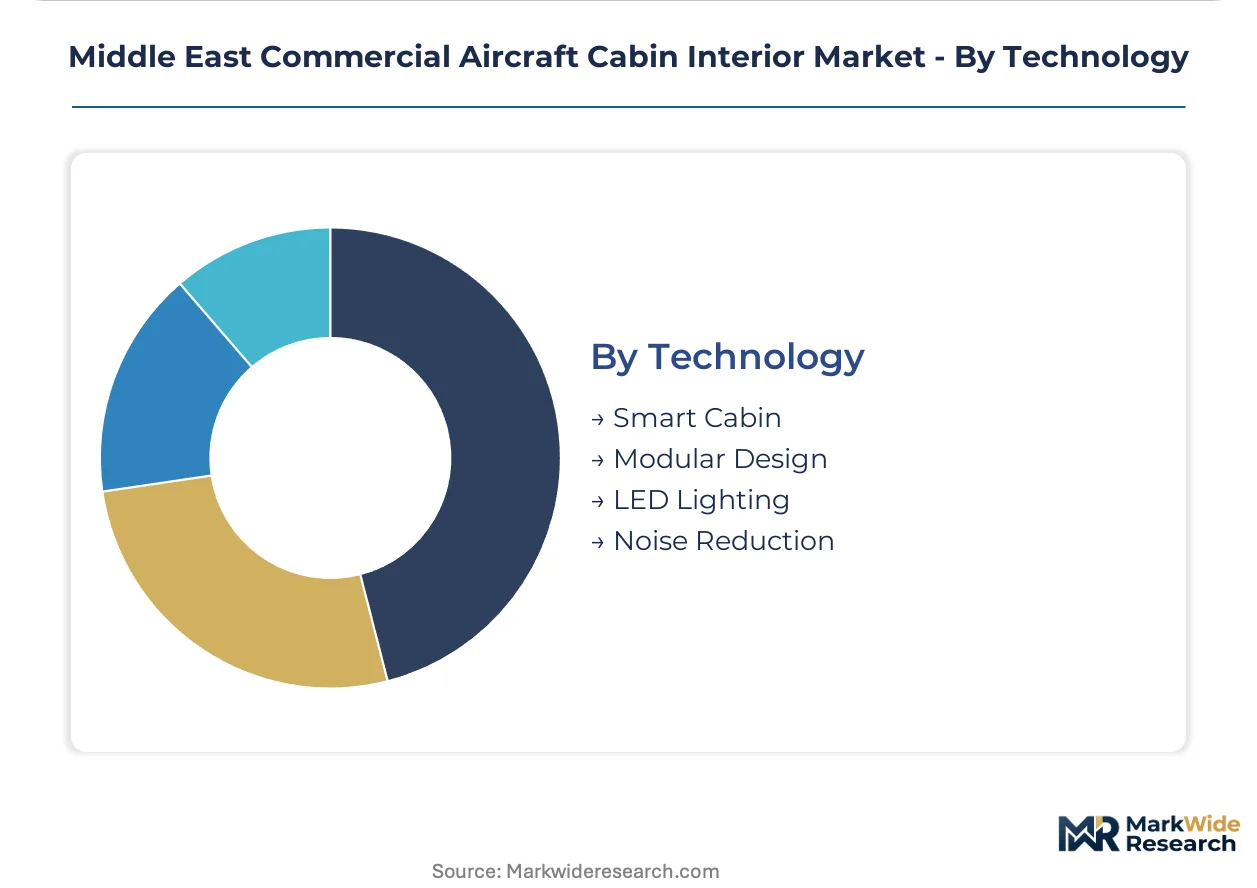
Technology:
Maturity gradients separate proven LED and modular architectures from emerging smart cabin platforms facing EU AI Act compliance redesign.
- Smart Cabin:IoT sensor networks integrated with predictive maintenance platforms enable subscription-based interior health monitoring. Algorithmic transparency documentation and fail-safe autonomy requirements under emerging EU protocols reshape engineering cycles at regional R&D centers.
- Modular Design:Standardized galley and lavatory units reduce installation downtime during compressed retrofit windows at Emirates and Etihad facilities.
- LED Lighting:Programmable ambient systems with circadian rhythm programming have achieved cost parity sufficient for narrow-body deployment.
- Noise Reduction:Acoustic dampening materials and active cancellation systems face qualification bottlenecks as specialized flammability engineering talent remains concentrated in European laboratories.
LED lighting retains installed base leadership; smart cabin systems hold the steepest expansion trajectory as connectivity convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing leverage over UAE suppliers for premium seating contracts, while Qatar's procurement teams extract volume discounts that compress margins for component specialists serving Doha-based retrofit programs.
Saudi Arabia
Riyadh Air's fleet launch and Saudia's expansion drive concentrated demand for lie-flat business-class platforms and integrated lighting systems. The General Authority of Civil Aviation enforces cabin interior certification aligned with EASA CS-25 standards while advancing Vision 2030 localization mandates. Riyadh anchors manufacturing transfer negotiations as joint-venture requirements reshape procurement rules for domestic content.
United Arab Emirates
Emirates and Etihad synchronize wide-body retrofit cycles with heavy maintenance checks, collapsing traditional procurement timelines. The General Civil Aviation Authority tightened fire-retardant material standards for cabin components, accelerating replacement of legacy inventory failing updated toxicity thresholds. Dubai's MRO execution houses require regional stocking infrastructure to meet compressed installation windows.
Qatar
Qatar Airways specifies all-composite lie-flat platforms for upcoming A350 deliveries, redirecting procurement toward specialized polymer processors. National regulations mirror EASA CS-25 and FAA Part 25 frameworks without additional GCAA-style material mandates. Doha's technical procurement teams consolidate vendor accountability with single-source turnkey providers rather than fragmented component committees.
Kuwait
Kuwait Airways' narrow-body fleet renewal creates demand for LED ambient lighting systems migrating from flagship routes to regional aircraft. The country's civil aviation regulator maintains certification alignment with ICAO standards and EASA guidance. Kuwait City serves as a secondary distribution node for composite seating components entering Gulf retrofit channels.
Israel
El Al's premium cabin refresh programs generate specialized demand for lightweight seating with integrated sensor networks. The Israel Civil Aviation Authority enforces flammability standards referencing FAA Part 25 and EASA CS-25 protocols. Tel Aviv's engineering centers face recruitment bottlenecks as specialized FAR 25.853 compliance expertise remains concentrated in European laboratories.
Middle East Commercial Aircraft Cabin Interior Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East commercial aircraft cabin interior supply base. Full-spectrum systems houses dominate turnkey retrofit programs through integrated avionics-to-interior portfolios, while component specialists compete on engineering depth in narrow seating or galley subsystems. Three archetypes define competitive positioning: integrated systems houses with captive MRO partnerships, European-certified manufacturers with dual EASA-GCAA compliance capabilities, and lightweight material specialists serving premium carrier specifications. Consolidation pressure and regional manufacturing transfer represent the dominant competitive moves as Saudi localization requirements reshape procurement rules.
Among integrated systems houses, Collins Aerospace and Safran occupy positions defined by full-spectrum capability spanning avionics through interior systems. Diehl Aerospace GmbH exemplifies the European-certified manufacturing archetype with German-engineered processes adapted to dual compliance requirements. These three companies represent the competitive anchors around which Gulf carriers consolidate vendor accountability for compressed retrofit timelines.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| Adient Aerospace |
| Astronics Corporation |
| Diehl Aerospace GmbH |
| Recaro Group |
| Jamco Corporation |
| Panasonic Avionics Corporation |
| Expliseat |
| Others |
Supply & Pricing Matrix
EASA CS-25 and GCAA dual certification requirements gate both supplier qualification and price differentiation simultaneously, as compliance burden separates certified aerospace-grade inputs from commercial alternatives while compressing margin visibility for fixed-price retrofit contracts.
Pricing Analysis
Configured-to-order pricing for lie-flat composite seating platforms commands substantial premiums over standard narrow-body configurations, with customization depth and flammability certification tier as primary differentiation drivers. Cost compression in economy-class seating intensifies as petrochemical feedstock volatility squeezes thermoplastic resin margins. Gulf carriers demonstrate lowest price sensitivity in first-class and business-class platforms, while regional subsidiaries and MRO execution houses exhibit acute cost discipline for narrow-body fleet retrofits.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for carbon-fiber prepregs and specialized polymer resins entering Dubai and Jeddah free zones. Manufacturing gravity centers on Germany, France, and the United States for certified seating shells and integrated lighting systems, with raw material dependencies on Japanese carbon-fiber feedstock and Belgian epoxy resin formulations. Single-source vulnerability concentrates in specialized flammability testing laboratories, while distribution runs through regional MRO stocking hubs to meet compressed installation windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Gulf carriers abandon fragmented procurement committees in favor of single-source turnkey accountability, consolidating vendor relationships around integrated systems houses.
For Market Incumbents: Fortify regional MRO partnerships and captive certification infrastructure to defend against component specialist marginalization. Backward integration into composite shell manufacturing in GCC free zones locks in margin capture under Vision 2030 localization mandates, while deepening flammability engineering talent pools mitigates recruitment bottlenecks threatening R&D timelines. For New Entrants and Emerging Players: Anchor in aftermarket refurbishment channels for retired premium seats entering North African and Central Asian lease operator fleets, a white-space segment bypassing OEM line-fit concentration. Saudi Arabia's domestic content requirements present the most penetrable geography, with joint-venture manufacturing transfer as the essential go-to-market mechanism. For Investors and Strategic Acquirers: EU AI Act safety protocols for connected cabin systems reshape the acquisition landscape toward engineering centers with embedded algorithmic transparency capabilities. Long-term viability favors targets with dual EASA-GCAA compliance infrastructure and smart cabin IoT platforms. Watch for GCAA material mandate updates as the signal indicating retrofit cycle acceleration and inventory replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Joint Venture | Vision 2030 localization requirements force partnership structures for Riyadh Air and Saudia fleet content. |
| Flammability Certification Investment | GCAA and EASA dual approval tracks extend engineering timelines and freeze resources on redundant documentation. |
| Regional MRO Stocking Infrastructure | Compressed retrofit scheduling privileges suppliers with Dubai and Jeddah execution capability. |
| Smart Cabin Platform Development | EU AI Act fail-safe autonomy requirements reshape LED control and environmental management unit engineering cycles. |
| Composite Material Supply Agreement | Thermoplastic resin price volatility demands long-term offtake structures to stabilize seating shell margins. |
Research Methodology
Initial hypotheses were tested against primary input from airline technical procurement directors, MRO operations managers, flammability engineering leads, and composite manufacturing specialists and refined through secondary validation against EASA certification databases, GCAA regulatory filings, customs trade records for aerospace components, and fleet delivery schedules from Airbus and Boeing. Bottom-up triangulation across product type, material grade, and end-user segments converged with top-down market sizing from carrier fleet plans and retrofit cycle analysis.
Variance decomposition across product type, material tier, end-user category, and technology maturity level structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate synthesis calibrated to fleet expansion schedules, regulatory mandate timelines, and material substitution curves. Industry-specific inputs included Riyadh Air delivery schedules, GCAA material standard update protocols, and thermoplastic composite adoption rates in premium seating specifications.
Material uncertainties — petrochemical feedstock volatility, EU AI Act implementation timing, and Saudi localization requirement enforcement — sit outside the modeled envelope. Forecasts reflect assumptions on carrier retrofit synchronization patterns and certification timeline stability. Practitioners should keep alternative scenarios live as regulatory mandate acceleration and manufacturing transfer negotiation outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market