
 Commercial Aircraft in-Flight Entertainment System Market | 2026-2036
Commercial Aircraft in-Flight Entertainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft in-Flight Entertainment System Market Outlook
DO-160G environmental qualification is rotating vendor eligibility, as only suppliers with proven thermal, vibration, and electromagnetic interference testing can secure platform approvals. Panasonic Avionics Corporation leverages its vertically integrated content and hardware pipeline to sustain long-term airline contracts. Thales Group anchors European programs through manufacturing scale in France and certification proximity to EASA. Collins Aerospace differentiates via embedded connectivity and avionics integration expertise.
A commercial aircraft in-flight entertainment system comprises seatback displays, audio distribution networks, wireless access points, and content servers operating across ARINC 429 and Ethernet avionics buses, typically delivering 1080p video streams at sub-100 millisecond latency to passenger devices and embedded screens. The system's primary purpose is to enhance passenger experience, generate ancillary revenue through premium content, and reduce perceived flight duration on long-haul sectors. Display Systems and Connectivity Solutions command the largest share of procurement budgets, as airlines prioritize high-definition screens and satellite-based broadband over legacy audio-only architectures. Wireless Streaming is displacing traditional in-seat wired platforms on narrow-body retrofits, where weight reduction and faster installation cycles improve return-on-investment.
FAA airworthiness directives and EASA CS-25 certification standards govern hardware installation, electrical load management, and cybersecurity protocols for connected cabin systems. The EU AI Act and GDPR frameworks increasingly shape content personalization algorithms and passenger data handling across European-registered fleets. Stakeholders must monitor evolving spectrum allocation debates between aviation connectivity providers and terrestrial 5G operators, as interference rulings will determine next-generation antenna deployment economics.
Market Dynamics
Wireless streaming architectures are compressing installation timelines for narrow-body retrofits while seatback display procurement concentrates among vertically integrated suppliers with DO-160G certification capabilities.
Growth Catalysts
- FAA airworthiness directives:Mandates for cybersecurity-hardened cabin systems are forcing carriers to replace legacy analog distribution networks with encrypted Ethernet backbones.
- Narrow-body fleet renewal:Low-cost carriers across Southeast Asia and Latin America are stripping out heavy seatback hardware in favor of lightweight wireless streaming pods.
- Content personalization engines:Machine learning algorithms operating under GDPR and EU AI Act frameworks are enabling dynamic pricing for premium entertainment bundles.
Market Restraints
- DO-160G test chamber scarcity:Only three independent laboratories in North America and Europe can execute full environmental qualification cycles, creating 18-month certification backlogs.
- Indium gallium arsenide supply concentration:High-performance display driver chips depend on Taiwanese foundry capacity exposed to geopolitical shipping lane risks.
- Ka-band spectrum auction conflicts:Terrestrial 5G operators in the United States and Germany are contesting aviation frequency allocations, delaying antenna deployment schedules.
Strategic Opportunities
- India domestic trunk routes:IndiGo and Air India Express are retrofitting 400+ A320 family aircraft with bring-your-own-device streaming platforms lacking legacy seatback infrastructure.
- Extended reality content pipelines:Spatial audio and 360-degree video formats are converging with low-earth-orbit satellite latency profiles to enable immersive entertainment on ultra-long-haul sectors.
- EASA CS-25 cybersecurity amendments:Pending rulemaking will mandate continuous monitoring of cabin network traffic, creating aftermarket service contracts for threat detection software.
Industry Challenges
- DO-178C software engineer scarcity:Safety-critical avionics coding expertise concentrates among aging specialists in Toulouse, Hamburg, and Seattle, constraining development velocity.
- Legacy ARINC 429 integration:New Ethernet-based streaming servers must bridge obsolete 32-kilobit databuses on 15-year-old airframes, multiplying wiring harness complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft in-Flight Entertainment System Market |
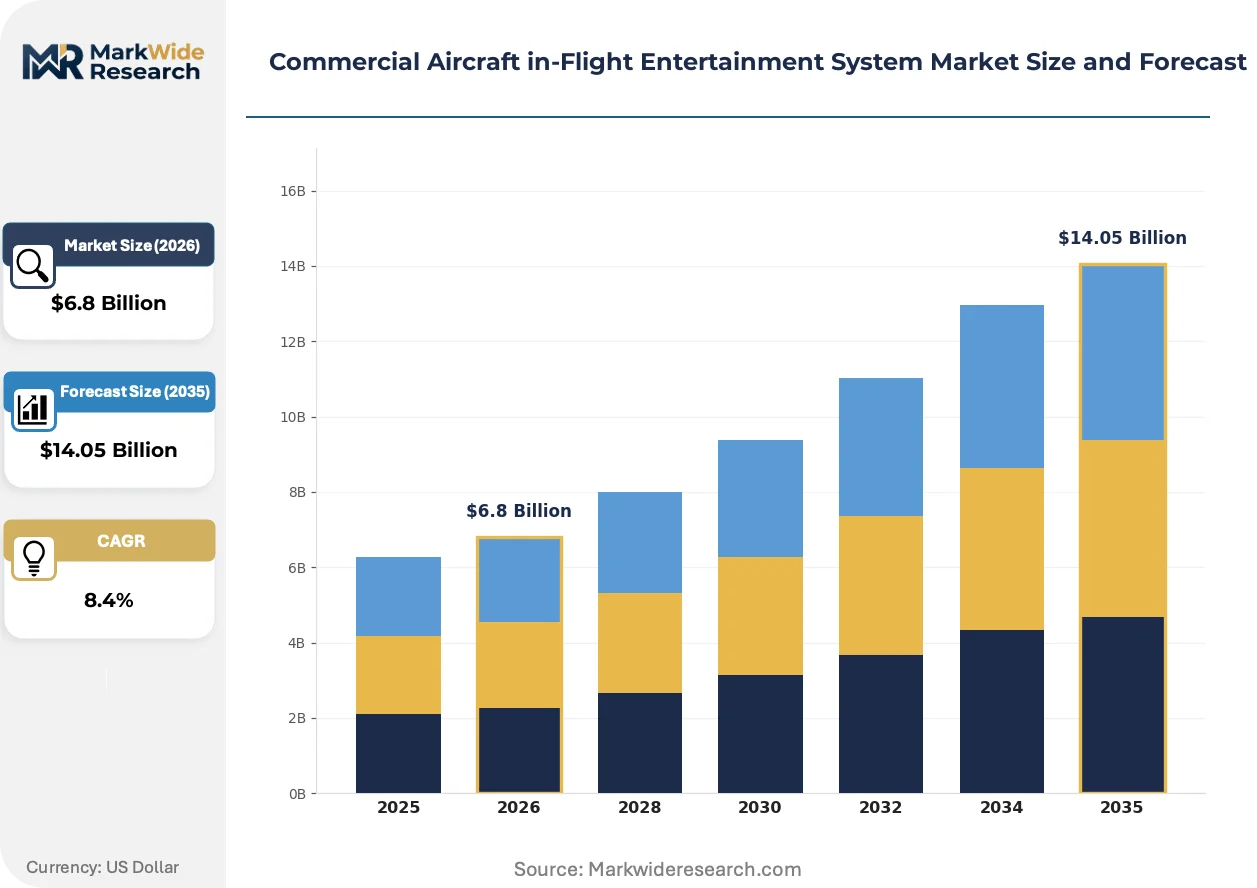
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Systems, Audio Systems, Connectivity Solutions, Content Management Technology: Wireless Streaming, In-Seat Entertainment, Satellite-Based Systems, IPTV Application: Commercial Aviation, Cargo Aircraft, Business Jets, Regional Jets End User: Airlines, Aircraft Manufacturers, In-Flight Service Providers, Third-Party Content Providers |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Anuvu, Burrana Pty Ltd, Astronics Corporation, RTX Corporation, Gogo LLC, Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft in-Flight Entertainment System Market Strategic Shifts
Content delivery architectures are splitting between bandwidth-heavy seatback screens and minimalist wireless streaming, with regulatory pressure on electromagnetic compatibility accelerating hardware refresh cycles.
Wireless streaming technology is bifurcating the retrofit market. Low-cost carriers operating Boeing 737 MAX and A321neo fleets are adopting server-only configurations that beam content to passenger smartphones, eliminating display hardware entirely. This shift is compressing supplier margins on embedded screens while expanding recurring revenue from content licensing portals.
EASA CS-25 Amendment 25-157 is mandating isolation between passenger entertainment networks and flight-critical avionics buses. Manufacturers must now implement hardware-enforced air gaps or certified data diodes, adding firmware development costs and extending platform qualification timelines. European-registered wide-body operators face 2027 compliance deadlines for connected cabin architectures.
Airline technical procurement teams are unbundling hardware acquisition from content service agreements. Gulf carriers and Southeast Asian flag operators now source seatback displays through direct OEM contracts while negotiating streaming rights through separate media aggregators. This disintermediation fragments vendor relationships and shifts negotiation leverage toward content studios in Los Angeles and London.
Commercial Aircraft in-Flight Entertainment System Market Segmentation
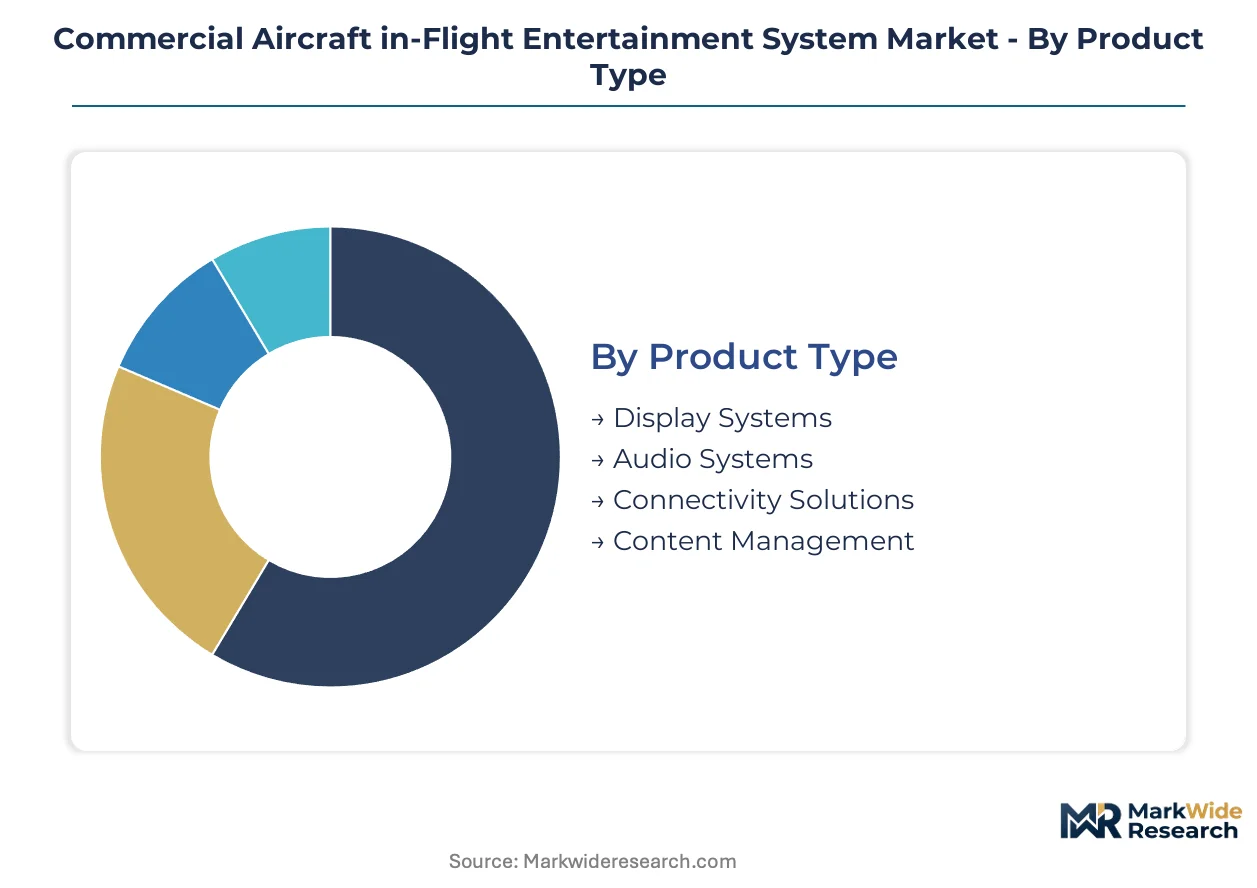
Segmentation in commercial aircraft in-flight entertainment reveals how procurement channels split between factory-installed OEM programs and aftermarket retrofit contracts. Airlines, system integrators, and content aggregators each favor distinct technology bundles based on fleet age and route economics.
Product Type:
Display Systems and Connectivity Solutions flow primarily through OEM airframe contracts, while Audio Systems and Content Management move via airline direct procurement and third-party service agreements.
- Display Systems:High-definition seatback screens ranging from 9-inch economy units to 32-inch premium cabin monitors with 4K resolution and capacitive touch interfaces. Demand clusters among Gulf carriers retrofitting wide-body fleets for premium differentiation, constrained by DO-160G thermal qualification backlogs at North American test facilities.
- Connectivity Solutions:Satellite modems, Ka-band antennas, and cabin wireless access points enabling broadband internet and streaming services. Lufthansa and Singapore Airlines are prioritizing these systems for long-haul passenger retention, though spectrum allocation disputes between aviation providers and terrestrial 5G operators in Germany and the United States delay antenna certifications.
- Audio Systems:Noise-canceling headphone distribution networks and seat-embedded audio jacks operating across analog and digital buses.
- Content Management:Server racks, storage arrays, and software platforms for media ingest, encryption, and passenger-facing distribution.
Display Systems dominates installed base. Connectivity Solutions is where expansion concentrates.
Technology:
Cost tiering separates legacy hardware from emerging platforms, with wireless architectures commanding premium pricing for weight reduction and installation speed.
- Wireless Streaming:Server-only configurations beaming content to passenger smartphones and tablets via cabin Wi-Fi, eliminating seatback hardware entirely. IndiGo and Air India Express are deploying these platforms across 400-plus A320 family aircraft for domestic trunk routes, driven by narrow-body retrofit economics and faster turnaround times.
- In-Seat Entertainment:Traditional wired architectures with embedded displays, audio jacks, and control units at each passenger position. Legacy fleets in the United States and China retain these systems for passenger experience consistency, though procurement is shifting toward hybrid wireless-seatback configurations.
- Satellite-Based Systems:Geostationary and low-earth-orbit links providing global broadband coverage.
- IPTV:Internet protocol television distribution for live broadcast and video-on-demand services.
In-Seat Entertainment retains the largest installed footprint. Wireless Streaming is climbing the fastest as low-cost carriers strip out heavy hardware.
Application:
Volume concentration tracks fleet renewal cycles, with commercial narrow-body and wide-body programs consuming disproportionate procurement share.
- Commercial Aviation:Scheduled passenger operations across narrow-body, wide-body, and regional aircraft types. Major carriers in China, Germany, and the United States are driving seatback display and wireless platform adoption through OEM factory-install contracts and mid-life retrofit programs.
- Business Jets:Private and corporate aircraft requiring customized cabin entertainment and connectivity solutions.
- Cargo Aircraft:Freighter conversions and factory-built cargo platforms with minimal passenger-facing systems.
- Regional Jets:Sub-100-seat aircraft operated by feeder carriers with constrained weight and electrical budgets.
Commercial Aviation dominates installed base. Business Jets is where expansion concentrates for ultra-high-net-worth customization.
End User:
Customer type determines contract structure, with OEMs bundling hardware into airframe pricing and airlines unbundling content rights for separate negotiation.
- Airlines:Operating carriers specifying, procuring, and maintaining entertainment systems across owned and leased fleets. Delta Air Lines and Emirates are disaggregating hardware acquisition from content service agreements, fragmenting vendor relationships and shifting leverage toward media aggregators in Los Angeles and London.
- Aircraft Manufacturers:Boeing and Airbus embedding factory-installed entertainment architectures into new-build programs.
- In-Flight Service Providers:Third-party contractors managing content loading, hardware maintenance, and passenger support.
- Third-Party Content Providers:Studios and aggregators licensing film, television, and interactive media for airline distribution.
Airlines dominate installed base. Aircraft Manufacturers is where expansion concentrates for embedded connectivity integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA cybersecurity mandates and EASA CS-25 amendments are accelerating fleet retrofits across major aviation markets, with carriers in the United States, China, and Germany leading procurement of next-generation entertainment architectures.
United States
Delta Air Lines and American Airlines are disaggregating hardware acquisition from content service agreements, fragmenting vendor relationships. FAA airworthiness directives mandate encrypted Ethernet backbones for cabin systems. Seattle hosts Boeing's factory-install programs embedding connectivity-integrated entertainment platforms into new-build 787 and 777X aircraft.
China
Air China and China Eastern are retrofitting aging wide-body fleets with seatback display systems ahead of international route expansion. The country's national aviation regulator enforces electromagnetic compatibility standards aligned with DO-160G environmental qualification. Shanghai's Pudong district concentrates system integration facilities serving COMAC C919 factory-install contracts.
Germany
Lufthansa prioritizes Ka-band connectivity solutions for long-haul passenger retention despite spectrum allocation disputes with terrestrial 5G operators. EASA CS-25 Amendment 25-157 mandates hardware-enforced air gaps between passenger networks and flight-critical avionics. Hamburg anchors Airbus final assembly lines where Thales Group supplies factory-installed entertainment architectures.
India
IndiGo and Air India Express are deploying wireless streaming platforms across 400-plus A320 family aircraft for domestic trunk routes, eliminating seatback hardware entirely. The country's Directorate General of Civil Aviation monitors cabin network cybersecurity compliance. Bangalore's electronics manufacturing cluster produces lightweight server-only configurations for narrow-body retrofit programs.
United Arab Emirates
Emirates and Etihad Airways drive premium cabin differentiation through 32-inch 4K seatback monitors and immersive content pipelines. The General Civil Aviation Authority aligns certification requirements with EASA standards for European-registered fleet compatibility. Dubai's aviation free zone hosts maintenance facilities performing mid-life connectivity upgrades on A380 and 777 aircraft.
Commercial Aircraft in-Flight Entertainment System Market Competitive Environment
Player mix skews toward vertically integrated system integrators with captive content pipelines and certification-hardened hardware divisions. Market structure concentrates procurement leverage among three global suppliers possessing DO-160G test capabilities and EASA proximity. Two strategic archetypes dominate: full-stack platform providers bundling hardware, software, and media rights; and connectivity specialists monetizing recurring satellite bandwidth contracts. Competitive moves center on unbundling hardware from content service agreements and securing aftermarket cybersecurity monitoring contracts.
Among vertically integrated platform providers, Panasonic Avionics Corporation and Thales Group exemplify the full-stack archetype, while Collins Aerospace occupies a position bridging avionics integration expertise with embedded connectivity architectures. These three anchors represent the certification-heavy tier where long-term airline contracts hinge on regulatory proximity and environmental qualification depth.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Collins Aerospace |
| Anuvu |
| Burrana Pty Ltd |
| Astronics Corporation |
| RTX Corporation |
| Gogo LLC |
| Safran SA |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwanese foundries lock in indium gallium arsenide wafer supply while capping display driver chip costs for tier-one system integrators. These arrangements grant Panasonic Avionics and Thales Group price visibility across multi-year airline retrofit cycles, insulating procurement budgets from spot-market volatility in semiconductor substrates.
Pricing Analysis
Certification level (DO-160G environmental qualification) creates the primary spread between premium and standard hardware tiers. Three-tier pricing structure across DO-160G-certified, DO-160G-pending, and uncertified equipment levels segments the market by thermal, vibration, and electromagnetic interference test completion. Cost compression in wireless streaming server configurations is intensifying because low-cost carriers are stripping out seatback displays entirely. Low-cost carriers operating narrow-body fleets exhibit the highest price sensitivity, while Gulf carriers retrofitting wide-body premium cabins demonstrate minimal elasticity for 4K display procurement.
Supply Chain Analysis
Container availability constraints across the Trans-Pacific trade lane are extending lead times for server rack assemblies sourced from Shenzhen manufacturing clusters. Display panel production concentrates in South Korea, Taiwan, and China, while content server final assembly localizes in France and the United States to maintain EASA and FAA certification proximity. High-performance semiconductor substrates draw from Taiwanese foundry capacity exposed to geopolitical shipping lane risks. Distribution runs through OEM airframe contracts for factory-install programs and direct airline procurement channels for aftermarket retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA CS-25 cybersecurity amendments are mandating hardware-enforced air gaps between passenger entertainment networks and flight-critical avionics, creating a regulatory inflection that will reshape competitive positioning across the analysis window.
For Market Incumbents: Secure DO-178C software engineering talent pools in Toulouse, Hamburg, and Seattle before aging specialist retirements constrain development velocity. Deepen backward integration into indium gallium arsenide wafer supply through long-term foundry partnerships, neutralizing Taiwanese capacity concentration risks. These moves defend against emerging connectivity specialists monetizing recurring satellite bandwidth contracts. For New Entrants and Emerging Players: Anchor in India's domestic trunk route retrofit market where IndiGo and Air India Express are deploying server-only wireless streaming platforms across 400-plus A320 family aircraft. Target aftermarket cybersecurity monitoring contracts triggered by pending EASA CS-25 rulemaking, as European-registered wide-body operators face compliance deadlines for connected cabin architectures. A software-first go-to-market approach bypasses hardware certification backlogs. For Investors and Strategic Acquirers: Certification-hardened mid-tier system integrators with captive DO-160G test capabilities represent the most defensible acquisition targets in a market where environmental qualification backlogs extend 18 months. Long-term viability hinges on regulatory proximity to FAA and EASA certification pathways rather than content aggregation scale. The signal to monitor is spectrum allocation rulings between aviation connectivity providers and terrestrial 5G operators in Germany and the United States, as interference determinations will reset antenna deployment economics and vendor contract valuations.| Strategic Initiative | Industry Significance |
|---|---|
| DO-160G Certification Investment | Environmental qualification unlocks platform approvals from FAA and EASA for seatback hardware. |
| Wireless Streaming Platform Launch | Server-only configurations capture narrow-body retrofit demand from low-cost carriers in India and Southeast Asia. |
| Cybersecurity Monitoring Service | Continuous cabin network traffic analysis addresses EASA CS-25 Amendment 25-157 compliance mandates. |
| Content Rights Disaggregation | Unbundling hardware acquisition from streaming agreements shifts negotiation leverage toward media aggregators. |
| Ka-Band Antenna Partnership | Satellite modem integration secures long-haul connectivity contracts with Lufthansa and Singapore Airlines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline technical procurement directors, IFE system integration engineers, avionics certification specialists, and content licensing executives at media aggregators. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment documentation, ARINC specification releases, and customs records for avionics component trade flows. Bottom-up fleet retrofit pipeline analysis triangulated against top-down OEM factory-install program disclosures.
Across the analysis window, the forecasting framework modeled segmentation by product type (display systems, connectivity solutions, audio systems, content management), technology architecture (wireless streaming, in-seat entertainment, satellite-based systems), and application (commercial aviation, business jets, regional aircraft). CAGRs were derived from installation timeline compression rates, fleet renewal schedules, and regulatory compliance deadline clustering. Industry-specific inputs included DO-160G test chamber capacity utilization and Ka-band spectrum auction timelines.
Material uncertainties — cybersecurity rulemaking delays, semiconductor supply disruptions, and spectrum allocation conflicts — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification backlog resolution and foundry capacity expansion. Recalibration cycles align with material shifts in FAA airworthiness directive issuance and EASA CS-25 amendment finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market