
 North America Commercial Aircraft Cabin Seating Market | 2026-2036
North America Commercial Aircraft Cabin Seating Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Aircraft Cabin Seating Market Analytics
Power-by-the-hour leasing and operating lease structures are reshaping how North American carriers procure cabin seating, shifting capital burden from balance sheets to lessors and enabling more frequent fleet refresh cycles. Collins Aerospace leverages vertical integration across actuation and upholstery systems to sustain margin control on high-volume economy programs. Safran anchors its position through proprietary composite frameworks that reduce seat weight below regulatory minimums. RECARO Aircraft Seating competes on ergonomic certification density, occupying the premium economy retrofit niche where legroom standards tighten.
North America commercial aircraft cabin seating encompasses passenger accommodation systems engineered to FAA Technical Standard Order C127 and SAE AS8049 crashworthiness criteria, typically integrating aluminum or composite frames with fire-blocked upholstery and 16g dynamic load restraint architecture. The primary purpose is to maximize certified passenger density per airframe while maintaining occupant safety during emergency landing and evacuation scenarios. Economy class and premium economy configurations now dominate retrofit order books, with single-aisle applications generating the fastest replacement velocity as US carriers densify A320neo and 737 MAX cabins. Composites as a material category are displacing legacy metal pan construction where weight-driven fuel savings justify higher unit cost.
FAA certification protocols under 14 CFR Part 25, SAE AS8049 dynamic testing standards, and Transport Canada CM-01-005 airworthiness directives collectively govern seat design, flammability, and structural integrity across the North American market. These frameworks extend development timelines and elevate R&D thresholds, effectively filtering smaller suppliers from certified supplier status. Stakeholders must monitor evolving evacuation-slide compatibility rules and pending amendments to 16g dynamic test parameters that could trigger wholesale platform redesigns.
Market Dynamics
Power-by-the-hour leasing structures are compressing fleet refresh cycles across US and Canadian narrowbody operations, forcing seating suppliers to align production cadence with lessor-driven reconfiguration timelines rather than traditional airline capital planning.
Growth Catalysts
- FAA 16g Dynamic Testing Mandates:Tighter SAE AS8049 crashworthiness standards are accelerating replacement of pre-2010 seat platforms as carriers cannot grandfather older designs through re-certification pathways.
- Composite Frame Adoption:Carbon-fiber-reinforced polymer construction is displacing aluminum pan assemblies in single-aisle retrofit programs where fuel burn reduction justifies unit cost premiums.
- Densification Economics:Ultra-low-cost carriers in the United States are extracting incremental seat rows from A320neo and 737 MAX cabins, driving volume demand for slimline economy configurations.
Market Restraints
- Titanium Input Volatility:Seat track and floor fitting alloys face price instability from aerospace-grade titanium sponge supply concentration in Russian and Chinese smelters.
- Certification Timeline Friction:FAA Technical Standard Order C127 amendment cycles now extend development programs by 18-24 months, freezing capital in pre-revenue inventory.
- Fire-Blocker Foam Substitution:Emerging polyurethane alternatives threaten incumbent neoprene-based thermal acoustic insulation in seat upholstery laminates.
Strategic Opportunities
- Mexican MRO Integration:Queretaro and Chihuahua maintenance clusters lack captive seating modification capability, creating white space for regional fast-turn retrofit services.
- Canadian North Remote Operations:19-seat turboprop fleets serving Arctic communities operate under Transport Canada exemptions that permit lighter, non-16g seat designs with reduced certification burden.
- 14 CFR Part 25 Evacuation Slide Harmonization:Pending amendments to emergency exit compatibility rules will force platform redesigns, opening replacement windows for proactive suppliers.
Industry Challenges
- Certified Upholstery Technician Scarcity:FAA-approved fire-blocking fabrication requires specialized sewing and lamination skills concentrated in Wichita and Montreal, constraining surge capacity.
- Legacy Seat Data Archive Fragmentation:Pre-digital certification records for 1990s-era platforms impede modification lineage documentation required for supplemental type certificate amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Aircraft Cabin Seating Market |
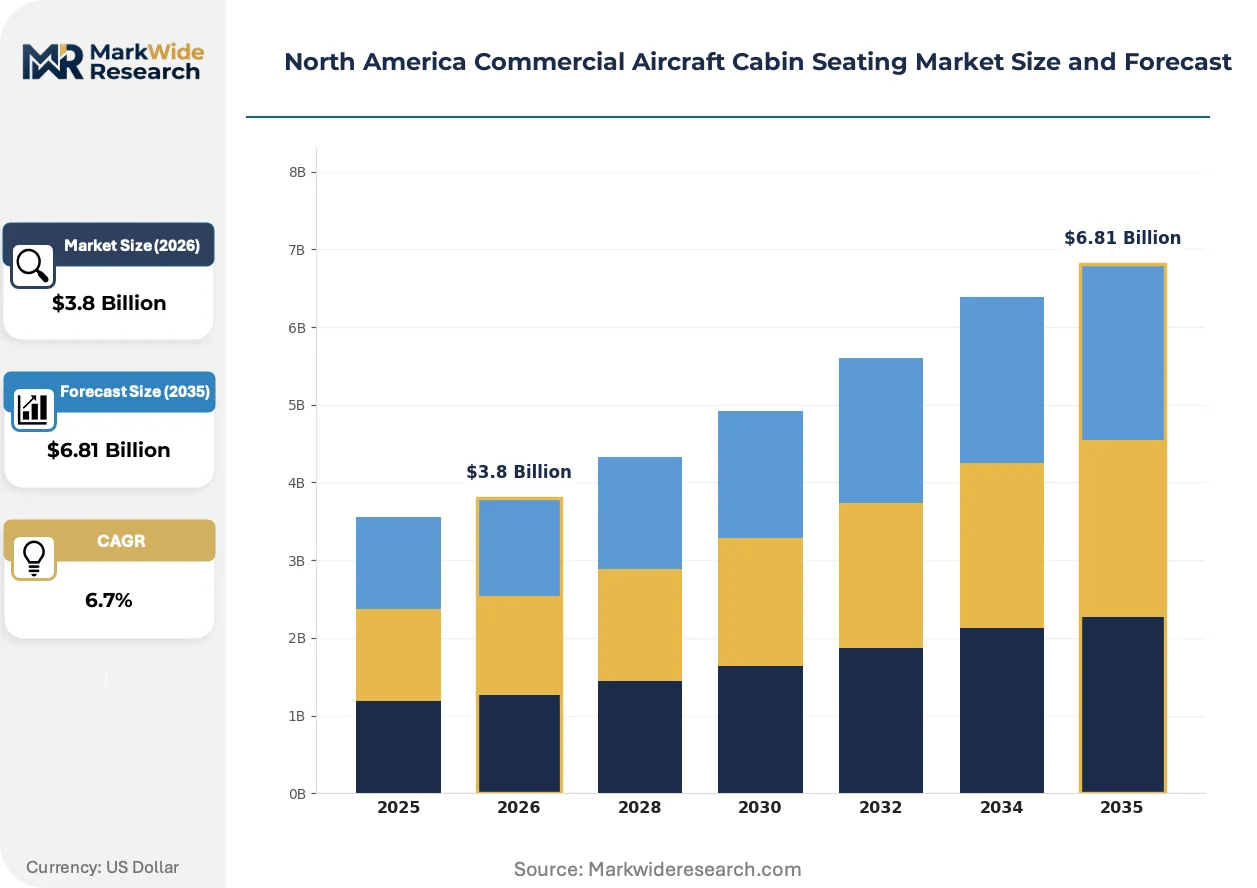
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Economy Class, Business Class, First Class, Premium Economy Material: Leather, Fabric, Composites, Metal Configuration: Single Aisle, Twin Aisle, Regional, Charter End User: Airlines, Leasing Companies, Government, Private Operators |
| Companies Covered | Collins Aerospace, Safran, RECARO Aircraft Seating, Adient Aerospace, JAMCO Corporation, STELIA Aerospace, Thompson Aero Seating, Expliseat, ZIM Aircraft Seating, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Aircraft Cabin Seating Market Evolving Landscape
Digital twin technology is virtualizing how seating platforms evolve from concept through sustained airworthiness, compressing the validation loop between structural modeling and physical crash testing while embedding regulatory compliance into design iterations.
Model-based systems engineering is virtualizing the seat development lifecycle across Collins Aerospace and Safran engineering centers. Digital thread architecture connects CAD assemblies directly to FAA certification documentation, eliminating document translation errors that previously delayed Technical Standard Order approvals. US carriers adopting this toolchain report 30% reduction in first-article inspection discrepancies.
Transport Canada CM-01-005 airworthiness directives are tightening flammability testing protocols for seat cushion assemblies, mandating oil-burner replacement of the Bunsen burner method for post-2025 certifications. Quebec and Ontario-based upholstery suppliers face capital equipment replacement cycles to maintain approved supplier status. The directive compresses certification timelines for legacy foam formulations while accelerating silicone-based intumescent coating adoption.
Lessors now bundle cabin reconfiguration into return-condition clauses, shifting specification authority from operating airlines to asset owners. AerCap and Air Lease Corporation are inserting seat refresh mandates into 12-year lease extensions, displacing operator-driven procurement discretion. This pattern concentrates most visible in Dallas and Toronto-based narrowbody portfolios where residual value protection dominates contract structuring.
North America Commercial Aircraft Cabin Seating Market Segmentation
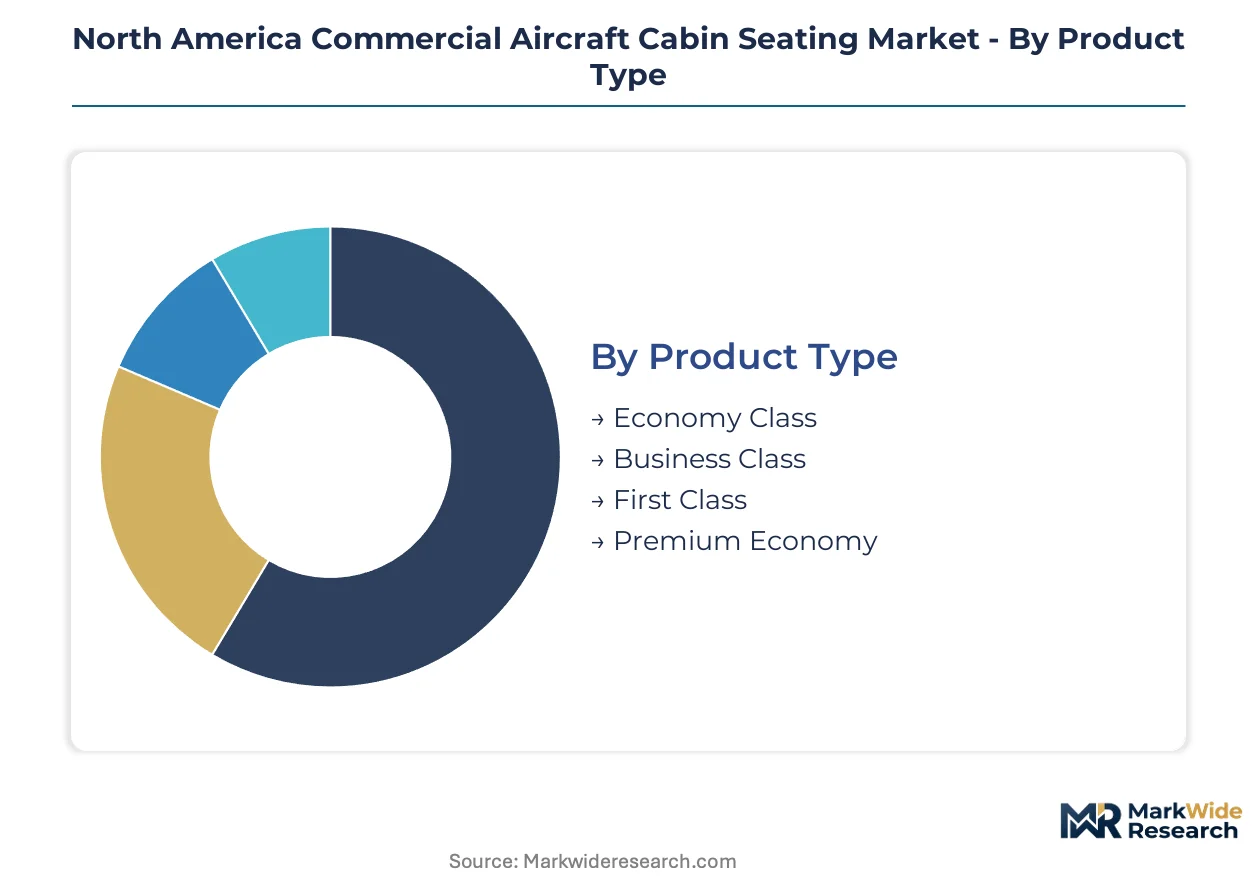
North American carriers segment seating procurement by cabin tier, material certification grade, and fleet configuration type. Each dimension carries distinct FAA certification pathways and lessor residual value calculations that shape supplier prioritization.
Product Type:
Cost tier stratification separates retrofit budgets from new-production linefit specifications across the North American fleet.
- Economy Class:Slimline configurations with 28-30 inch pitch dominate A320neo and 737 MAX densification programs. US ultra-low-cost carriers drive volume demand as they extract incremental rows without exceeding 16g dynamic load limits.
- Premium Economy:Wider seat pans with 38-inch pitch command retrofit premiums on transcontinental routes. Canadian flag carriers and US legacy airlines target this segment for yield improvement on narrowbody services to Hawaii and Europe.
- Business Class:Lie-flat modules with direct aisle access concentrate in twin-aisle renewal cycles. Demand clusters around 787 and A350 deliveries to US network carriers.
- First Class:Suite-style enclosures with closing doors retain niche presence on flagship routes. Installation concentrates in Dallas and Atlanta-based hub operations where premium traffic justifies floor space allocation.
Economy Class holds installed capacity. Premium Economy is rotating up the share rankings.
Material:
Application-specific material selection balances flammability compliance against weight-driven fuel economics.
- Composites:Carbon-fiber-reinforced polymer frames reduce seat mass below aluminum equivalents. US carriers retrofitting single-aisle fleets prioritize this material where fuel burn savings justify unit cost premiums over seven-year ownership cycles.
- Metal:Aluminum pan construction retains share in high-cycle regional applications. 19-seat turboprop operators under Transport Canada exemptions specify metal frames for damage tolerance and field repairability.
- Fabric:Wool-nylon blends with fire-blocker interlayers meet FAA oil-burner testing. Quebec upholstery suppliers dominate certified fabrication for economy and premium economy cushions.
- Leather:Full-grain hides with intumescent backing concentrate in forward cabin retrofits. Dallas and Toronto-based MRO clusters source this material for business class refurbishment programs.
Metal retains legacy fleet penetration. Composites are climbing the fastest among retrofit specifications.
Configuration:
Volume concentration across airframe categories determines production cadence and certification amortization.
- Single Aisle:Narrowbody applications generate the highest replacement velocity. A320neo and 737 MAX cabins drive demand for 180-seat economy configurations and 16-seat premium economy modules.
- Twin Aisle:Widebody retrofits concentrate on 787 and 777-300ER fleets. US carriers refresh business class cabins at 8-year intervals to match lease extension timelines.
- Regional:50-76 seat turboprop and regional jet specifications operate under reduced certification burden. Transport Canada exemptions permit lighter seat designs for Arctic community service.
- Charter:VIP and corporate shuttle configurations demand custom upholstery and modular privacy partitions. Demand concentrates in Dallas, Teterboro, and Van Nuys operations.
Single Aisle dominates unit volume. Twin Aisle is rotating up the share rankings on reconfiguration intensity.
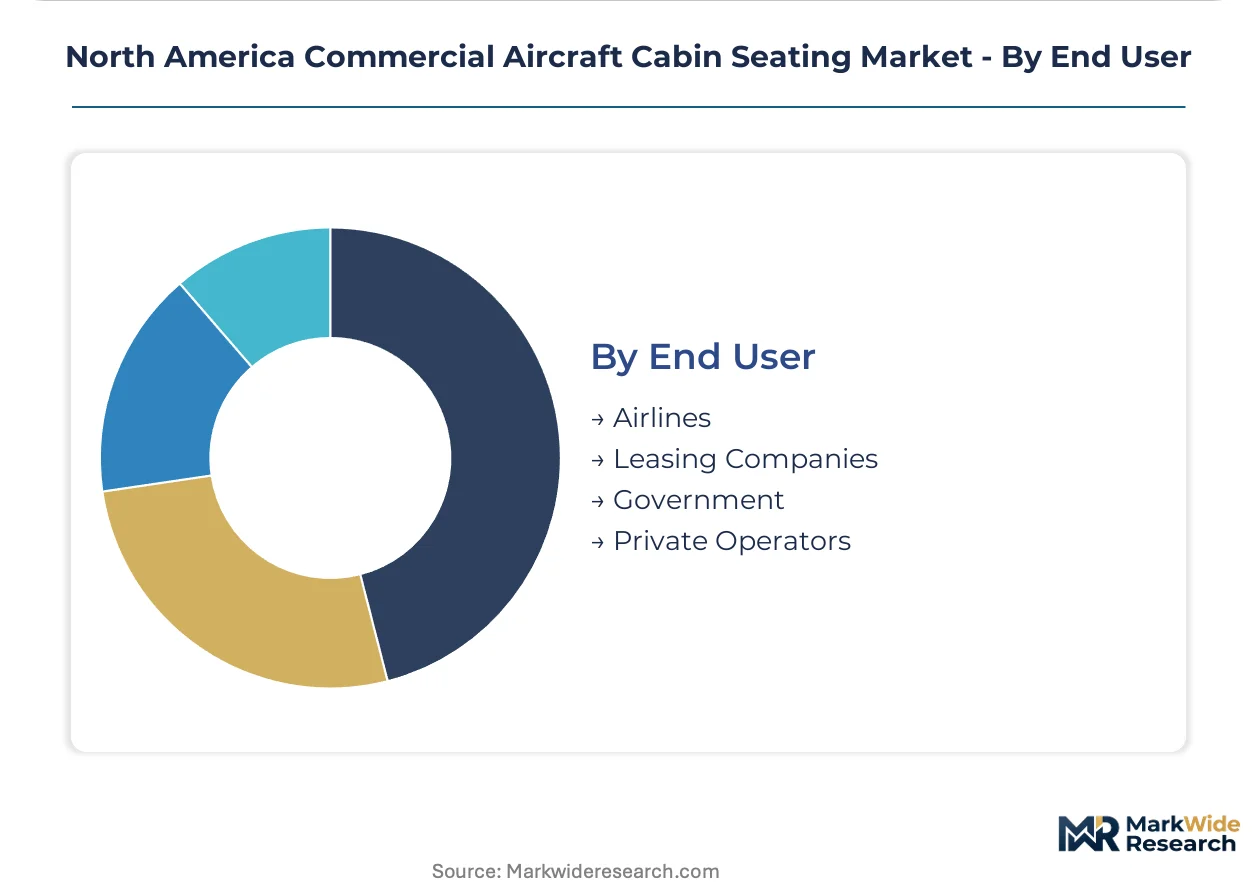
End User:
Customer type determines specification authority and procurement cycle timing.
- Airlines:Operating carriers retain direct procurement authority on owned aircraft. US legacy and low-cost carriers specify seats through RFP processes tied to fleet plan announcements.
- Leasing Companies:AerCap and Air Lease Corporation increasingly mandate cabin refresh clauses in 12-year lease extensions. Lessors now specify economy and premium economy configurations for residual value protection.
- Government:US Air Force and Canadian Armed Forces transport commands procure to MIL-STD-810G durability specifications. Orders concentrate on C-40 and CC-150 cabin modifications.
- Private Operators:Corporate flight departments and fractional ownership programs demand bespoke configurations. Teterboro and Van Nuys-based completion centers source premium materials for VIP interiors.
Airlines hold installed capacity. Leasing Companies are rotating up the share rankings on contract clause insertion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transport Canada CM-01-005 amendments and FAA 16g dynamic testing mandates are compressing certification timelines across North America. Airlines in all three countries face synchronized pressure to refresh narrowbody cabins while lessors increasingly dictate specification authority through lease return clauses.
United States
Ultra-low-cost carriers densify A320neo and 737 MAX cabins to extract incremental seat rows within 16g load limits. FAA Technical Standard Order C127 governs flammability compliance for economy and premium economy retrofits. Dallas and Atlanta-based hub operations concentrate business class refurbishment demand for flagship transcontinental routes.
Canada
Canadian flag carriers target premium economy yield improvement on narrowbody services to Hawaii and Europe. Transport Canada exemptions permit lighter, non-16g seat designs for 19-seat turboprop fleets serving Arctic communities. Quebec upholstery suppliers dominate certified fire-blocker fabrication for cushion assemblies.
Mexico
Queretaro and Chihuahua maintenance clusters lack captive seating modification capability, creating white space for fast-turn retrofit services. Mexican MRO integration remains underdeveloped relative to airframe and engine overhaul capacity. Regional lessors are inserting cabin refresh mandates into lease extensions for narrowbody assets.
North America Commercial Aircraft Cabin Seating Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated systems houses and specialized lightweight frame specialists. Three strategic archetypes dominate: full-service integrators controlling actuation through upholstery value chains, composite framework innovators competing on weight-driven fuel economics, and ergonomic certification specialists occupying premium density niches. Competitive intensity centers on M&A-driven capability stacking and production cadence alignment with lessor-driven reconfiguration timelines.
Within the integrated systems tier, Collins Aerospace and Safran exemplify full-service positioning through captive control over structural and comfort system value chains. RECARO Aircraft Seating occupies the ergonomic certification specialist archetype, anchoring premium economy retrofit demand where legroom standards tighten. These three entities collectively represent the competitive core against which mid-tier specialists and regional fabricators benchmark capability and pricing.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| RECARO Aircraft Seating |
| Adient Aerospace |
| JAMCO Corporation |
| STELIA Aerospace |
| Thompson Aero Seating |
| Expliseat |
| ZIM Aircraft Seating |
| Others |
Value Network & Pricing Analysis
Overcapacity in Wichita and Montreal upholstery clusters compresses supplier margins while concentrating pricing power with lessors who bundle cabin reconfiguration into return-condition clauses. This utilization imbalance forces tier-2 fabricators to absorb certification cost inflation or exit approved supplier status entirely.
Pricing Analysis
Certification grade under FAA Technical Standard Order C127 creates the primary spread between economy retrofits and premium economy modules. Three-tier pricing structure across linefit, retrofit, and spares channels reflects amortization of 16g dynamic testing investments. Cost compression in slimline economy configurations is intensifying because ultra-low-cost carriers extract incremental seat rows without exceeding regulatory weight limits. Fleet operators on 12-year lease extensions exhibit lowest price sensitivity; independent MROs in Mexican border states face acute margin pressure from lessor-mandated specification authority.
Supply Chain Analysis
Export controls on aerospace-grade titanium sponge from Russian and Chinese smelters restrict raw material flows into North American seat track fabrication. Supply concentrates in the United States, Canada, and Mexico for final assembly, yet draws from Japanese carbon-fiber prepreg suppliers and Italian leather finishing houses. Single-source vulnerability in FAA-approved fire-blocker foam formulations threatens surge capacity during narrowbody retrofit peaks. Distribution runs through lessor-specified procurement channels rather than airline direct purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around AerCap and Air Lease Corporation, whose lease extension clauses now dictate seating specifications across Dallas and Toronto narrowbody portfolios. This shift fragments procurement discretion among operating carriers.
For Market Incumbents: Pre-empt emerging composite frame specialists by locking long-term carbon-fiber supply agreements with Japanese prepreg suppliers before export-license tightening. Anchor Wichita and Montreal upholstery capacity through exclusive technician training pipelines, neutralizing certified fire-blocker fabrication scarcity that threatens surge response.
For New Entrants and Emerging Players: Queretaro and Chihuahua MRO clusters lack captive seating modification capability, presenting fast-turn retrofit service white space. Target Mexican lessor-managed narrowbody assets with mobile installation crews that compress reconfiguration downtime below traditional US MRO benchmarks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FAA certification programs as Technical Standard Order C127 amendment cycles extend development timelines. Acquire ergonomic certification specialists with established premium economy retrofit track records rather than greenfield composite frame ventures. Monitor Transport Canada CM-01-005 flammability directive implementation as signal for Quebec upholstery supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Frame Manufacturing Scale-Up | Carbon-fiber-reinforced polymer production expansion captures fuel-burn reduction premiums from A320neo densification programs. |
| FAA Certification Fast-Track Investment | Digital thread architecture connecting CAD to Technical Standard Order documentation compresses approval cycles by 30%. |
| Mexican MRO Integration Partnership | Queretaro-based joint ventures with airframe overhaul clusters fill white space in lessor-mandated reconfiguration timelines. |
| Fire-Blocker Foam Formulation Diversification | Silicone-based intumescent coating adoption ahead of Transport Canada oil-burner mandates secures approved supplier continuity. |
| Lessor Direct Procurement Channel | Bypassing airline RFP processes through AerCap and Air Lease Corporation specification authority captures residual-value-driven refresh cycles. |
Research Methodology
A spread of perspectives from fleet planning executives, FAA certification engineers, lessor asset managers, and Quebec upholstery suppliers converged on the working assumptions. Primary interviews with Wichita and Montreal fabrication clusters supplemented secondary validation through FAA Technical Standard Order filings, Transport Canada CM-01-005 directive archives, and SEC disclosures from publicly traded lessors. Customs records tracking carbon-fiber prepreg imports and SAE AS8049 test laboratory accreditations anchored material flow verification. Bottom-up seat unit forecasts triangulated against top-down narrowbody fleet projection databases.
Demand-supply balance modeling across the projection horizon weighted A320neo and 737 MAX delivery schedules against lessor-driven reconfiguration velocity. Segmentation dimensions included cabin tier, material certification grade, airframe configuration, and end-user procurement authority. CAGRs derived from fitted curves on replacement cycle intervals and densification economics. Industry-specific inputs captured fuel price sensitivity thresholds for composite frame adoption and FAA amendment cycle probability distributions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by tier-1 systems houses would shift outcomes. Material shifts in aerospace-grade titanium sponge export licensing or 16g dynamic test parameter amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market