

Premium Air Taxi Cabin Interior Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Air Taxi Cabin Interior Systems Market Insights
FAA Part 23 rewrite for powered-lift aircraft is restructuring the cost-of-entry calculus for cabin interior suppliers. Collins Aerospace leverages its established Part 25 certification infrastructure to anchor early design partnerships with eVTOL OEMs. Safran competes through vertical integration into thermoplastic composite seating shells, trimming supplier touchpoints. Diehl Aviation specializes in modular lighting architectures that navigate the power-constraint trade-offs inherent in battery-electric airframes.
Premium air taxi cabin interior systems encompass seating, environmental control, lighting, acoustic treatment, and human-machine interface assemblies engineered to Part 23/27 equivalent safety standards with mass fractions below traditional commercial aviation benchmarks. These systems employ carbon-fiber-reinforced thermoplastics and 6000-series aluminum extrusions to maintain structural integrity under 9g crash loads while holding seat masses under twelve kilograms per passenger place. Seating Systems currently dominate procurement volumes as OEMs prioritize occupant safety demonstration for type certification, while Smart Glass and Autonomous Adjustment technologies are capturing disproportionate R&D allocation as operators differentiate on passenger experience. Climate Control remains the most margin-constrained segment due to thermal management trade-offs with battery range performance.
FAA powered-lift regulations, EASA SC-VTOL special conditions, and UAE GCAA vertiport operational standards collectively shape product specifications and market access timelines across the three primary certification jurisdictions. EASA's crashworthiness requirements for occupant protection in unintended vertical descent scenarios are forcing redesign of legacy seating attachment schemes. Stakeholders must monitor how regulator harmonization efforts between FAA and EASA evolve, as divergence in emergency egress or flammability standards would fragment supplier development roadmaps and duplicate qualification costs.
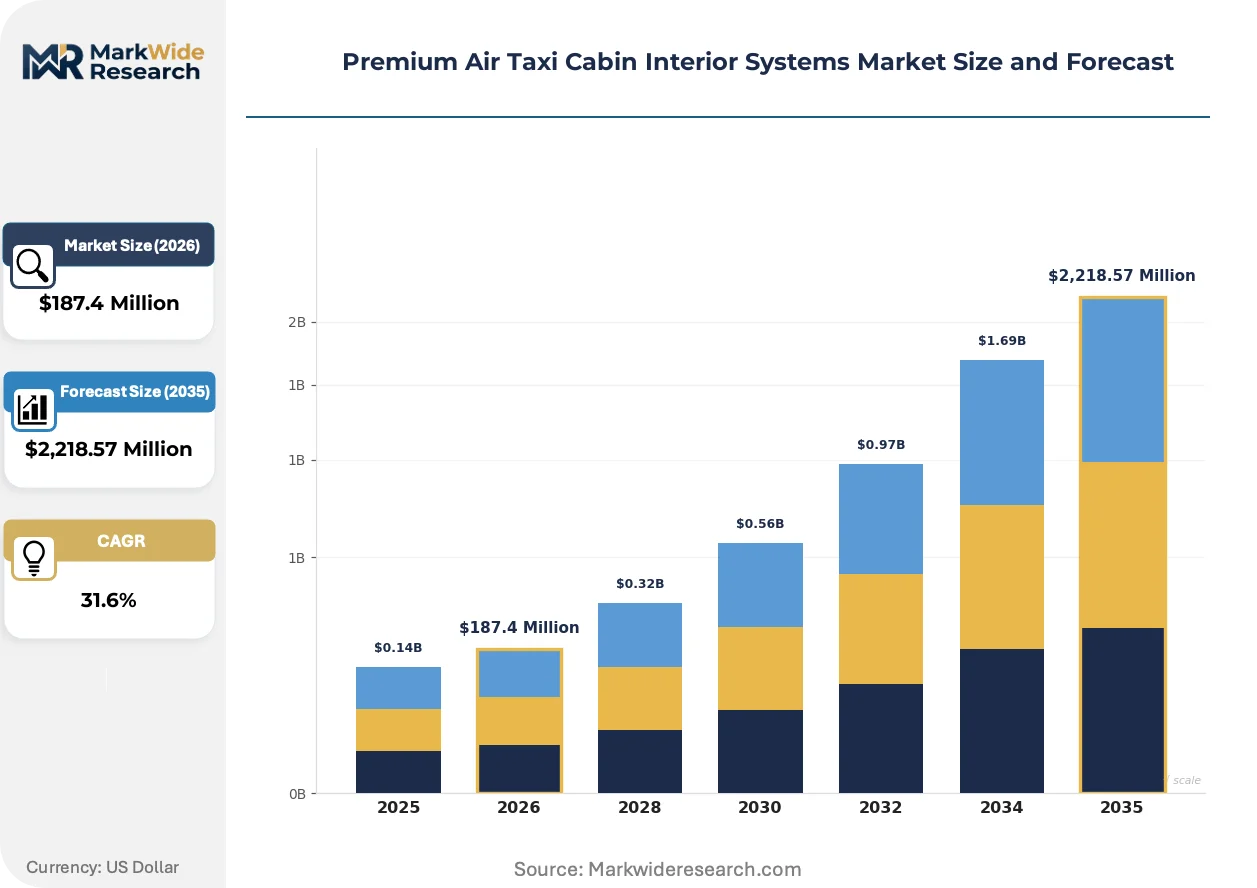
Market Dynamics
FAA Part 23 rewrite for powered-lift aircraft is compressing cabin interior development cycles, forcing suppliers to front-load crashworthiness validation before airframe integration. This regulatory acceleration privileges incumbents with existing Part 25 certification infrastructure.
Growth Catalysts
- Powered-lift certification pathway:FAA's streamlined Part 23 amendment reduces duplicate testing for eVTOL cabin systems, collapsing time-to-market for seating and environmental control assemblies.
- Thermoplastic welding advances:Automated fiber placement and induction welding are slashing composite seat shell cycle times while maintaining 9g load integrity.
- Urban vertiport densification:Dubai RTA's operationalized air taxi corridors are generating fleet-scale procurement commitments for premium cabin configurations.
Market Restraints
- Carbon fiber supply concentration:Toray, Hexcel, and Mitsubishi Chemical control 70% of aerospace-grade precursor supply, exposing interior manufacturers to allocation risk.
- Battery thermal trade-offs:Climate control systems face hard power budgets that compress HVAC performance margins and extend qualification timelines.
- EASA-FAA divergence on egress:Unharmonized emergency exit requirements force dual certification tracks, doubling engineering validation costs.
Strategic Opportunities
- Smart glass convergence:Electrochromic dimming fused with augmented reality overlays opens premium experience differentiation for urban mobility operators.
- Saudi GACA vertiport rollout:NEOM and Riyadh air taxi networks represent greenfield fleet deployment without legacy infrastructure constraints.
- Modular lighting architectures:Diehl Aviation's power-adaptive systems enable cabin reconfiguration across battery-electric and hybrid airframes.
Industry Challenges
- Multiphysics simulation talent scarcity:Crashworthiness modeling combining composite failure, occupant kinematics, and electromagnetic interference exceeds available workforce depth.
- Flammability testing backlog:FAA's limited burn-test facility capacity extends material qualification schedules for thermoplastic interior components.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Air Taxi Cabin Interior Systems Market Trends and Innovations
Carbon-fiber-reinforced thermoplastics are displacing thermoset prepregs across seating structures, compressing manufacturing cycle times while meeting stringent mass targets. This materials transition is reshaping supplier qualification requirements and tooling investment patterns.
Recycled carbon fiber nonwovens are absorbing acoustic treatment demand as eVTOL OEMs target circularity commitments without sacrificing NVH performance. Beta Technologies and Joby Aviation have specified these materials for cabin liner applications. The shift is absorbing legacy fiberglass supply relationships and forcing tier-two converters to retool pressing operations.
EASA SC-VTOL special conditions on unintended vertical descent are mandating energy-absorbing seat tracks and redesigned floor attachments. European OEMs must demonstrate 14g equivalent protection, exceeding FAA Part 23 baselines. This regulatory asymmetry is fragmenting platform development, with Airbus Urban Mobility maintaining dual-configuration supply chains.
Operator fleet commitments are consolidating procurement authority with Dubai RTA, Saudi GACA, and select US urban mobility networks. Traditional distributor channels face disintermediation as OEMs negotiate direct cabin system sourcing for volume deliveries. This concentration is most visible in UAE and Saudi Arabia, where sovereign wealth vehicle deployment schedules override conventional supplier selection cycles.
Premium Air Taxi Cabin Interior Systems Market Segmentation
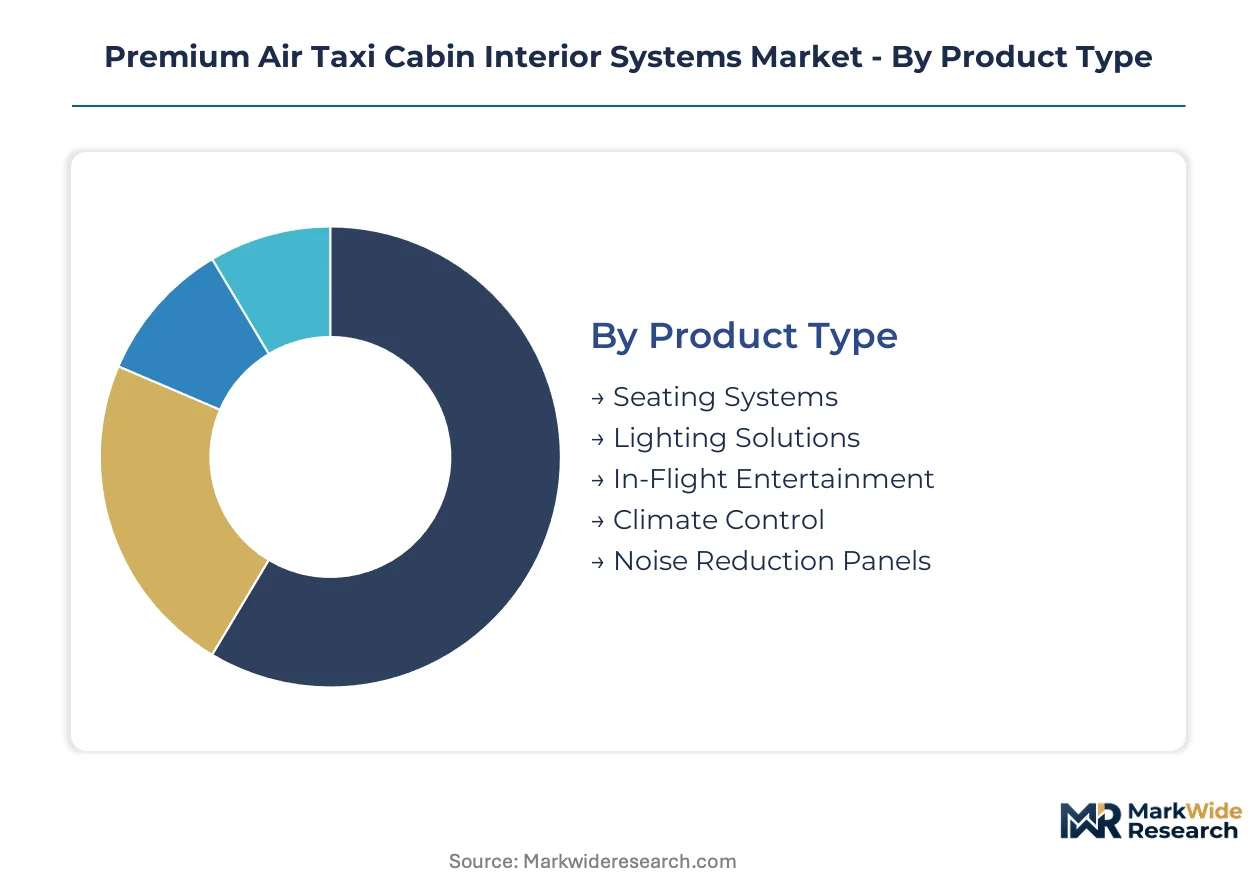
Premium air taxi cabin interiors fragment across four critical dimensions that determine procurement authority and margin capture. Product type governs safety-critical certification burdens, while technology selection separates experience-differentiated operators from cost-optimized fleet builders.
Product Type:
Customization intensity varies sharply across this category, with crashworthiness-mandated systems resisting commoditization while comfort features face standardization pressure.
- Seating Systems:Carbon-fiber-reinforced thermoplastic shells with 9g crash load certification anchor current procurement volumes. Dubai RTA's fleet commitments prioritize occupant safety demonstration for powered-lift type certification, making seating the dominant revenue pool.
- Climate Control:Battery thermal management trade-offs impose hard power budgets that compress HVAC performance margins. Range-sensitive operators in Saudi Arabia's NEOM network are specifying reduced-capacity climate systems to preserve flight endurance.
- Lighting Solutions:Diehl Aviation's modular LED architectures navigate power-constraint trade-offs across electric and hybrid airframes.
- In-Flight Entertainment:Minimal deployment in current generation platforms due to weight and power penalties on short-haul urban routes.
- Noise Reduction Panels:Recycled carbon fiber nonwovens specified by Beta Technologies and Joby Aviation for cabin liner applications.
Leading the category by volume: Seating Systems. Growing fastest: Lighting Solutions.
Technology:
Cost tier separation runs deepest here, with premium operators funding AR-integrated experiences while mass-market fleets defer discretionary technology.
- Smart Glass:Electrochromic dimming fused with augmented reality overlays creates premium experience differentiation for urban mobility operators in Dubai and Riyadh. Saudi GACA's greenfield vertiport networks enable specification without legacy retrofit constraints.
- Autonomous Adjustment:Voice-activated seat positioning and environmental personalization capture disproportionate R&D allocation as operators compete on passenger experience metrics.
- LED Lighting:Power-adaptive systems from Diehl Aviation enable rapid cabin reconfiguration across battery-electric and hybrid airframe variants.
- Touchscreen Interfaces:Human-machine interface assemblies engineered to Part 23 equivalent safety standards with electromagnetic interference shielding.
- Voice Recognition:Noise-canceling microphone arrays integrated into headliner assemblies for hands-free cabin control.
Commanding premium pricing: Smart Glass. Expanding most quickly: Autonomous Adjustment.
Application:
Volume concentration follows fleet deployment schedules, with sovereign wealth vehicle timelines overriding conventional demand patterns.
- Urban Mobility:Dubai RTA's operationalized air taxi corridors generate fleet-scale procurement commitments for premium cabin configurations. The UAE's GCAA vertiport standards shape product specifications across Gulf Cooperation Council markets.
- Corporate Travel:Time-sensitive executive transport in Saudi Arabia's Riyadh network demands premium seating and connectivity packages.
- Medical Evacuation:Specialized stretcher mounting and life-support power integration for emergency response operators.
- Emergency Response:Rapid deployment configurations with modular interior reconfiguration capabilities.
- Tourist Sightseeing:Panoramic viewing configurations with enhanced glazing and augmented reality narration systems.
Driving current procurement volumes: Urban Mobility. Steepest expansion trajectory: Corporate Travel.
End User:
Customer type determines contract structure, with direct OEM relationships displacing traditional distributor channels for volume fleet operators.
- Air Taxi Service Providers:Dubai RTA and select US urban mobility networks negotiate direct cabin system sourcing, consolidating procurement authority and disintermediating legacy supply chains. Sovereign wealth deployment schedules override conventional supplier selection cycles.
- Private Operators:Ultra-high-net-worth individuals in the UAE specify bespoke interior configurations with extended customization timelines.
- Government Agencies:Saudi GACA's regulatory and operational role creates dual customer influence over specification standards.
- Luxury Travel Firms:Experience-focused operators targeting premium-mid-economy pricing differentiation across service tiers.
- Event Organizers:Short-term lease configurations with rapid-install modular cabin systems for temporary demand spikes.
Capturing largest contract values: Air Taxi Service Providers. Gaining share fastest: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South's Mohammed bin Rashid Aerospace Hub anchors aerospace manufacturing concentration through tax-exempt zones and customs duty waivers for advanced materials imports.
United Arab Emirates
Dubai RTA's operationalized air taxi corridors generate fleet-scale procurement commitments for premium cabin configurations. GCAA vertiport operational standards shape product specifications across Gulf Cooperation Council markets. Dubai South's aerospace cluster hosts composite manufacturing facilities serving eVTOL interior programs.
Saudi Arabia
NEOM and Riyadh air taxi networks represent greenfield fleet deployment without legacy infrastructure constraints. GACA's regulatory and operational role creates dual customer influence over specification standards. NEOM's northwest development zone concentrates vertiport construction with sovereign wealth deployment schedules.
United States
FAA Part 23 rewrite for powered-lift aircraft compresses cabin interior development cycles for domestic eVTOL OEMs. Streamlined certification pathways reduce duplicate testing requirements for seating and environmental control assemblies. California's urban mobility operators in Los Angeles and San Francisco negotiate direct cabin system sourcing.
Germany
EASA SC-VTOL special conditions on unintended vertical descent mandate energy-absorbing seat tracks exceeding FAA baselines. Hamburg and Munich aerospace clusters maintain dual-configuration supply chains for European OEMs. Germany's national aviation regulator enforces 14g equivalent protection standards for occupant safety demonstration.
France
Toulouse and Paris aerospace corridors concentrate thermoplastic composite manufacturing for lightweight seating shells. EASA harmonization efforts with FAA influence supplier development roadmaps for export-oriented producers. French interior specialists navigate regulatory asymmetry through modular platform architectures.
Premium Air Taxi Cabin Interior Systems Market Competitive Landscape
North American producers anchor one tier; European specialists hold certification infrastructure advantages. The supplier base concentrates around three strategic archetypes: aerospace incumbents with Part 25 heritage, composite material specialists with thermoplastic welding capabilities, and modular systems integrators. Competitive positioning hardens through M&A activity targeting crashworthiness simulation talent and strategic partnerships with eVTOL OEMs for early design integration.
Among diversified aerospace conglomerates, Collins Aerospace and Safran exemplify the incumbent archetype leveraging established certification infrastructure. Diehl Aviation occupies a position representing modular lighting and power-adaptive systems specialization. These three anchors illustrate how competitive advantage flows from regulatory relationship depth and materials integration capabilities rather than scale alone.
| Leading Market Players |
|---|
| Collins Aerospace |
| Diehl Aviation |
| Safran |
| Recaro Aircraft Seating |
| FACC AG |
| Honeywell Aerospace |
| Thales Group |
| Panasonic Avionics Corporation |
| Joby Aviation |
| Others |
Pricing and Supply Chain Analysis
EASA SC-VTOL circularity mandates for recycled content certification gate both qualified carbon fiber supply and premium-tier pricing access for European-bound cabin interior contracts. Dubai RTA's fleet-scale procurement concentrates buyer power, compressing margins for non-certified suppliers while rewarding incumbents with Part 25 heritage.
Pricing Analysis
Lead-time-driven pricing stratifies across contract structures, with OEMs paying premiums for sub-twelve-week delivery of crash-validated seating shells while spot inventory trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified systems from single-jurisdiction alternatives. Pricing pressure stems from sovereign wealth fleet operators consolidating procurement authority. Air taxi service providers in the UAE demonstrate lowest price sensitivity; tier-two converters in Europe face acute margin compression.
Supply Chain Analysis
Carbon fiber precursor supply rests on Japanese, American, and German specialty chemical producers controlling aerospace-grade precursor allocation. Toray, Hexcel, and Mitsubishi Chemical feed thermoplastic composite welding operations for seating shell production. Single-source vulnerability concentrates in Toray's T800S fiber specification for 9g crash load certification. Distribution runs through direct OEM partnerships, bypassing legacy distributor channels for volume fleet commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cabin interior market sits in a materials-transition phase as thermoplastic composites displace thermoset prepregs across seating structures. Carbon-fiber-reinforced thermoplastics are compressing manufacturing cycle times while meeting stringent mass targets.
For Market Incumbents: To counter Safran's upstream control over thermoplastic composite seating shells, Collins Aerospace and Diehl Aviation should deepen captive supply of induction welding equipment and expand Hamburg certification infrastructure for EASA SC-VTOL compliance. Locking crashworthiness simulation talent through targeted acquisition protects margin position against emerging composite specialists.
For New Entrants and Emerging Players: Direct digital engagement with Dubai RTA and Saudi GACA procurement portals offers the fastest route to initial contract visibility. Modular lighting architectures for battery-electric airframes represent the most penetrable white space, with power-adaptive systems enabling rapid cabin reconfiguration. Position through demonstration of 14g equivalent protection for European OEM dual-configuration supply chains.
For Investors and Strategic Acquirers: FAA Part 23 powered-lift final rule publication is the leading indicator that certification-cycle compression will accelerate consolidation among tier-two interior suppliers. Long-term viability favors vertically integrated specialists with thermoplastic welding capabilities and existing Part 25 infrastructure. Watch EASA-FAA harmonization progress on emergency egress standards as the signal for qualification cost trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Expansion | Collins Aerospace leverages Part 25 heritage to anchor early eVTOL design partnerships. |
| Thermoplastic Welding Capability Acquisition | Safran's vertical control over composite seating shells trims supplier touchpoints for OEMs. |
| Modular Lighting Architecture Development | Diehl Aviation's power-adaptive systems navigate battery-electric constraint trade-offs. |
| Crashworthiness Simulation Talent Acquisition | Multiphysics modeling scarcity exceeds available workforce depth across European clusters. |
| Direct OEM Partnership Formation | Dubai RTA procurement consolidation disintermediates legacy distributor channels. |
Research Methodology
FAA certification dockets, EASA SC-VTOL special condition filings, and GCAA vertiport operational standards formed the secondary backbone for regulatory pathway mapping. Primary interviews with eVTOL platform engineers, cabin interior procurement leads at Dubai RTA, thermoplastic composite manufacturing directors, and FAA certification specialists validated demand assumptions. Bottom-up and top-down triangulation cross-checked OEM fleet commitment schedules against supplier capacity expansion announcements.
Bottom-up modeling segmented procurement volumes across seating systems, climate control, lighting solutions, and noise reduction panels by technology tier and application. Top-down validation referenced sovereign wealth deployment timelines and urban vertiport densification patterns across the analysis window. CAGRs derived from regression of fleet-scale commitments against certification milestone progress, with battery thermal trade-offs and flammability testing backlogs as industry-specific forecast inputs.
The model holds under sustained FAA-EASA regulatory harmonization progress; deviation in emergency egress standard divergence or carbon fiber allocation disruption would shift supplier development roadmaps. Forecasts reflect documented assumptions on certification cycle compression and materials substitution rates. A small set of named triggers—EASA 14g protection rule finalization, Toray precursor capacity expansion, and Dubai RTA fleet delivery acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.