
 Middle-East and Africa Commercial Aircraft Cabin Interior Market | 2026-2036
Middle-East and Africa Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Commercial Aircraft Cabin Interior Market Foresight
Aftermarket service revenue is narrowing the gap with original equipment sales as airlines across the Middle-East and Africa extend fleet lifecycles through cabin refresh programs. Collins Aerospace leverages its integrated seating and lighting portfolio to capture retrofit contracts at major Gulf hubs. Safran anchors its position through galley and lavatory systems optimized for high-density configurations favored by low-cost carriers in the region. RECARO Aircraft Seating GmbH & Co. KG specializes in lightweight economy and business-class seats that reduce fuel burn on long-haul routes connecting Africa to Europe and Asia.
The Middle-East and Africa commercial aircraft cabin interior encompasses the complete suite of installed components within the passenger and crew compartments, including seats certified to dynamic 16g crash requirements, LED mood lighting systems with programmable color temperatures, thermoplastic panels meeting smoke and toxicity standards, and stowage units engineered for rapid reconfiguration. These elements collectively determine passenger comfort ratings, crew operational efficiency, and aircraft turnaround times. Seats and IFEC technology command the deepest margin pools as carriers differentiate through lie-flat business products and immersive entertainment platforms. Lighting and cabin management systems represent the fastest-expanding categories, driven by retrofit demand for circadian-rhythm programming and energy-efficient architectures. Fabric and leather materials remain mature segments where procurement teams negotiate on volume and certification pedigree rather than technical novelty.
The European Union Aviation Safety Agency influences product access through EASA Part 21 design approvals that most Middle-East regulators reference for type certification acceptance. The General Authority of Civil Aviation in Saudi Arabia and the UAE's General Civil Aviation Authority enforce supplemental fire-blocking and flammability standards that exceed baseline FAA requirements, compelling suppliers to maintain dual-compliance testing capabilities. Stakeholders must monitor how bilateral airworthiness recognition agreements between African states and Gulf regulators reshape certification pathways and supplier qualification timelines.
Market Dynamics
The retrofit imperative among Gulf carriers is compressing product lifecycles as airlines compete on passenger experience without fleet replacement. This pressure cascades through seating, lighting, and galley suppliers who must now engineer for rapid reconfiguration cycles rather than twenty-year durability.
Growth Catalysts
- Saudi Fire-Safety Mandates:The General Authority of Civil Aviation's tightened flammability standards for thermoplastic composites are accelerating supplier R&D into advanced material formulations that command premium positioning.
- Emirates and Etihad Refurbishment Programs:The United Arab Emirates hosts two of the world's largest wide-body cabin refresh initiatives, creating concentrated demand for lie-flat seating and programmable LED architectures.
- Circadian-Rhythm Lighting:Long-haul carriers connecting Africa to Europe and Asia are retrofitting mood-lighting systems with programmable color temperatures to reduce passenger jet lag and improve comfort ratings.
Market Restraints
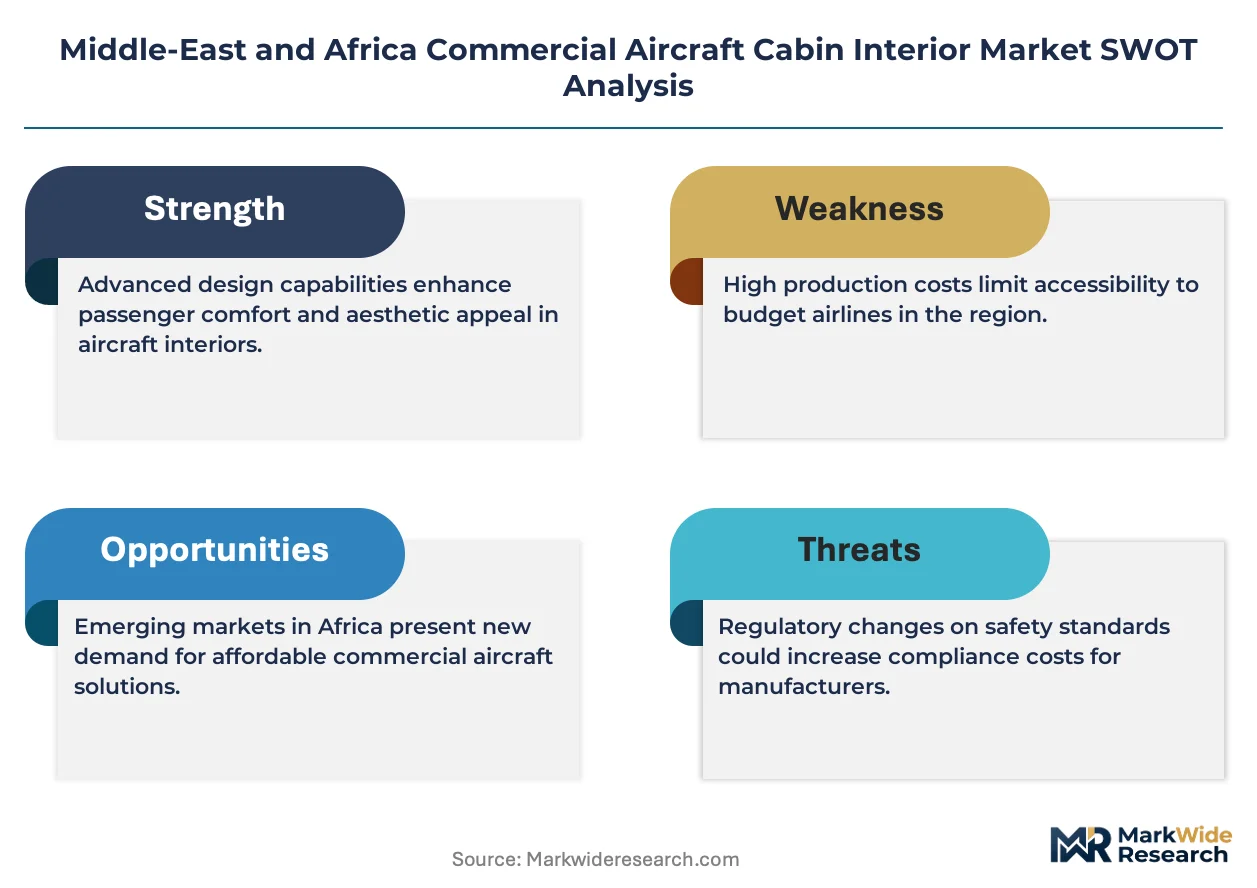
- Thermoplastic Raw Material Volatility:Specialized resin and fiber supplies for fire-compliant cabin panels face price instability due to concentrated petrochemical feedstock sourcing.
- Dual-Compliance Testing Burden:Suppliers must maintain parallel certification capabilities for EASA Part 21 design approvals and Saudi supplemental fire-blocking standards, elevating fixed compliance costs.
- Extended Aircraft Lifecycles:Airlines deferring new deliveries stretch refurbishment intervals, compressing the addressable retrofit window for interior component suppliers.
Strategic Opportunities
- Low-Cost Carrier Density Configurations:Saudi Arabia's emerging point-to-point operators favor high-density galley and lavatory systems optimized for rapid turnaround, opening volume segments beyond premium flagships.
- Energy-Efficient Architectures:LED cabin management systems with circadian programming represent the fastest-expanding retrofit category as carriers seek fuel burn reductions and differentiation.
- African Bilateral Airworthiness Agreements:Evolving recognition frameworks between Gulf regulators and African states are streamlining certification pathways for suppliers entering underpenetrated East African hubs.
Industry Challenges
- 16g Dynamic Crash Certification Talent:The specialized engineering workforce capable of certifying seats to dynamic crash requirements remains concentrated among a handful of suppliers, constraining capacity expansion.
- Legacy Fleet Integration Complexity:Retrofit programs must reconcile new lightweight seating and lighting systems with existing electrical architectures and structural mounting points on aging wide-body platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Commercial Aircraft Cabin Interior Market |
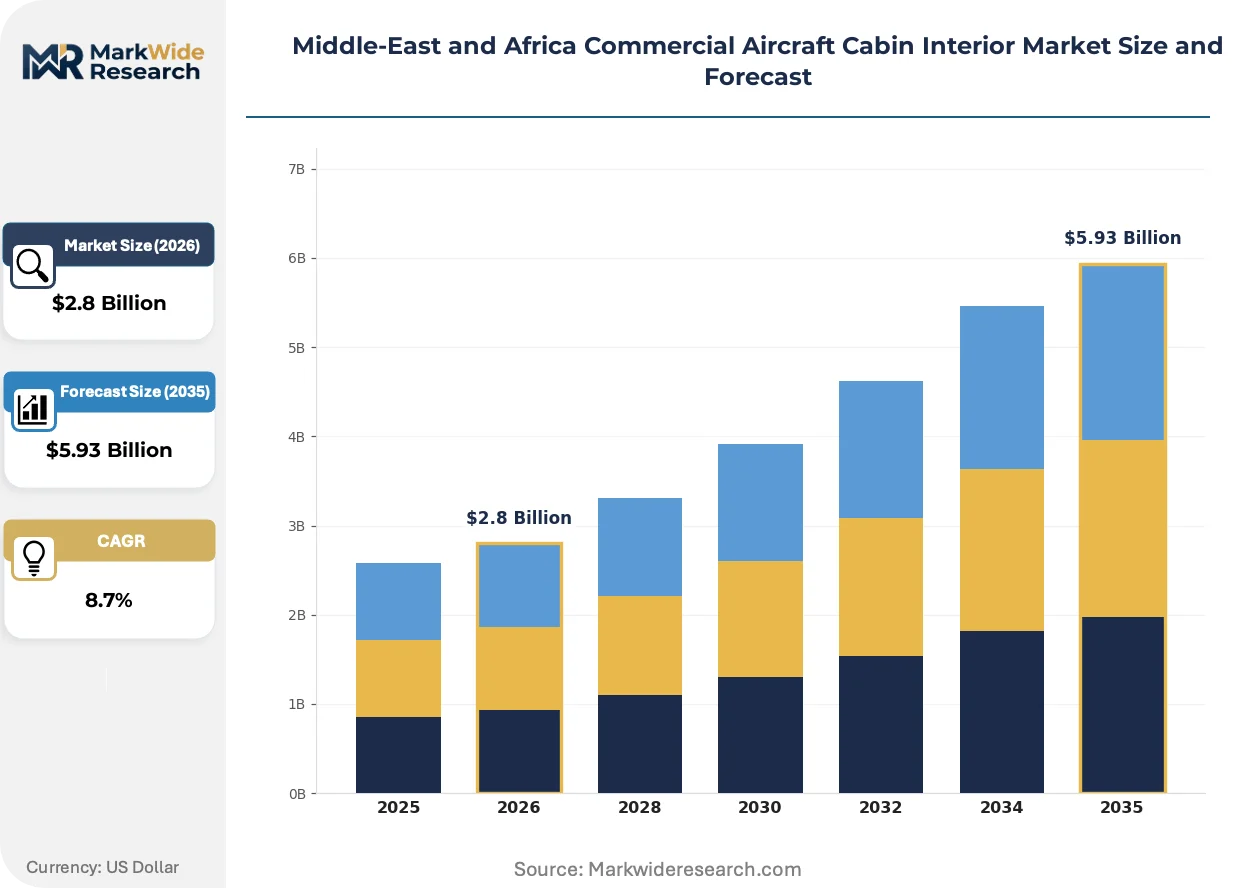
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seats, Lighting, Storage, Panels Material: Fabric, Leather, Plastic, Metal End User: Airlines, OEMs, MROs, Manufacturers Technology: IFEC, Cabin Management, Environmental Control, Safety Systems |
| Companies Covered | Collins Aerospace, Safran, RECARO Aircraft Seating GmbH & Co. KG, Panasonic Avionics Corporation, Diehl Aerospace GmbH, Adient Aerospace, Astronics Corporation, Jamco Corporation, Expliseat, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Commercial Aircraft Cabin Interior Market Shifts & Advancements
Material science and digital control systems are converging to redefine cabin architecture as airlines seek weight reduction alongside experiential differentiation. This transformation manifests across composite adoption, regulatory harmonization pressures, and evolving procurement models for aftermarket services.
Advanced thermoplastic composites are displacing traditional thermoset materials in panel and stowage applications due to superior smoke-toxicity performance and recyclability. Full-service carriers across the Gulf Cooperation Council specify these materials for new deliveries and retrofits alike. The technology is migrating from premium wide-body programs into narrow-body refresh cycles as unit economics improve and fire-safety standards tighten.
EASA Part 21 design approvals function as the de facto gateway for product access across Middle-East markets, with most national regulators referencing European certifications for type acceptance. Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority enforce supplemental flammability standards that exceed baseline FAA requirements, compelling suppliers to maintain redundant testing infrastructure. Seating and galley segments bear the heaviest compliance burden as these categories face the most stringent fire-blocking mandates.
Carrier procurement for cabin interiors is fragmenting from bundled OEM contracts toward component-level sourcing that unbundles seating, lighting, and IFEC systems. Airlines now negotiate directly with specialized suppliers for retrofit programs, bypassing traditional airframe integrators. This pattern is most pronounced in the United Arab Emirates, where Emirates and Etihad operate dedicated refurbishment facilities with in-house engineering teams capable of managing multi-vendor integration.
Middle-East and Africa Commercial Aircraft Cabin Interior Market Segmentation
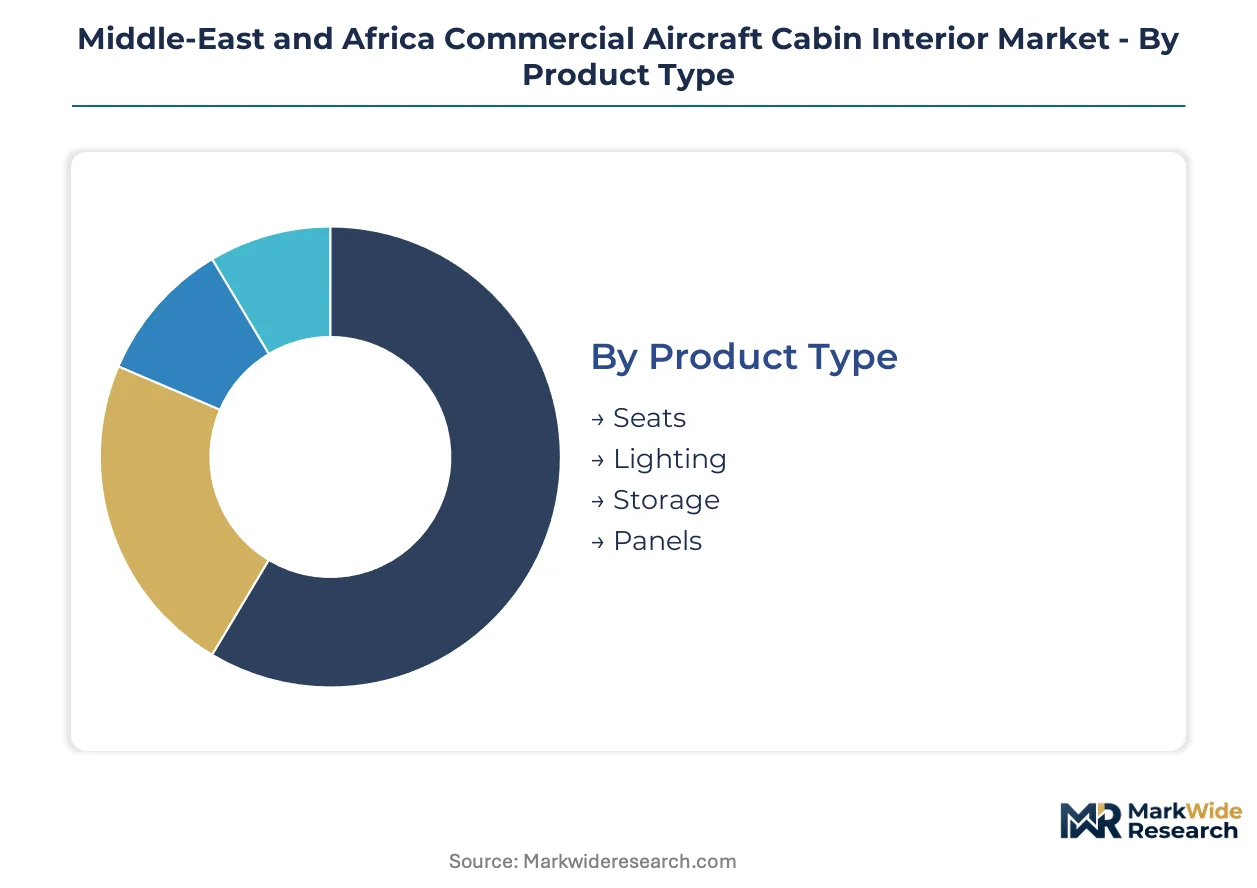
Cabin interior procurement patterns diverge sharply between retrofit refresh cycles and new aircraft deliveries. Understanding where replacement intervals compress versus stretch reveals where suppliers can capture recurring revenue versus one-time specification wins.
Product Type:
Seats turn over every 5-7 years on high-utilization Gulf fleets, while panels and storage often survive 15-year airframe lifecycles without replacement.
- Seats:Dynamic 16g crash-certified structures dominate retrofit spending as Emirates and Etihad refresh wide-body cabins with lie-flat business products. Saudi Arabia's emerging low-cost operators specify lightweight economy configurations to maximize density on point-to-point routes.
- Lighting:LED mood systems with programmable color temperatures command premium positioning as circadian-rhythm programming spreads across long-haul Africa-Europe-Asia routes. Retrofit demand concentrates in the United Arab Emirates where carriers compete on passenger experience ratings.
- Storage:Overhead bins and stowage units engineered for rapid reconfiguration support high-turnaround operations at Dubai and Jeddah hubs.
- Panels:Thermoplastic composite sidewalls meeting Saudi General Authority of Civil Aviation fire-safety mandates displace legacy thermoset materials in refurbishment programs.
Seats dominate installed base value. Lighting is where expansion concentrates fastest.
Material:
Cost tiers separate fire-compliant synthetics from commodity coverings, with certification pedigree determining access to premium retrofit contracts.
- Plastic:Advanced thermoplastic composites with superior smoke-toxicity performance anchor panel and stowage specifications across Gulf Cooperation Council retrofit programs. Saudi supplemental flammability standards exceed baseline FAA requirements, filtering supplier qualification.
- Fabric:Fire-blocking textiles meeting EASA Part 21 referenced standards cover seat cushions and sidewalls on narrow-body fleets serving African point-to-point routes. Procurement teams negotiate on volume and certification lineage rather than technical differentiation.
- Leather:Premium upholstery concentrates in first-class and business cabins on flagships operating from Dubai and Abu Dhabi.
- Metal:Aluminum and alloy structural components retain position in seat frames and mounting hardware where crash-load certification demands material traceability.
Plastic commands the steepest expansion trajectory as fire-safety mandates tighten. Fabric retains volume leadership across economy cabins.
End User:
Customer type shapes contract structure, with airlines driving component-level sourcing while OEMs and MROs mediate integration risk.
- Airlines:Direct procurement from specialized seating and lighting suppliers accelerates as Emirates and Etihad operate dedicated refurbishment facilities with in-house engineering teams. Fragmented sourcing unbundles traditional airframe integrator contracts.
- MROs:Maintenance-repair-overhaul providers capture installation and certification work on aging wide-body platforms requiring legacy electrical architecture reconciliation.
- OEMs:Original equipment manufacturers retain specification control on new deliveries, though Gulf carrier influence over sub-tier supplier selection is expanding.
- Manufacturers:Tier-2 fabricators supply fire-compliant subassemblies to integrators serving Saudi and UAE certification pathways.
Airlines dominate decision-making authority. MROs are where execution complexity concentrates.
Technology:
Application criticality separates passenger-facing differentiation systems from crew-operational infrastructure and mandatory safety equipment.
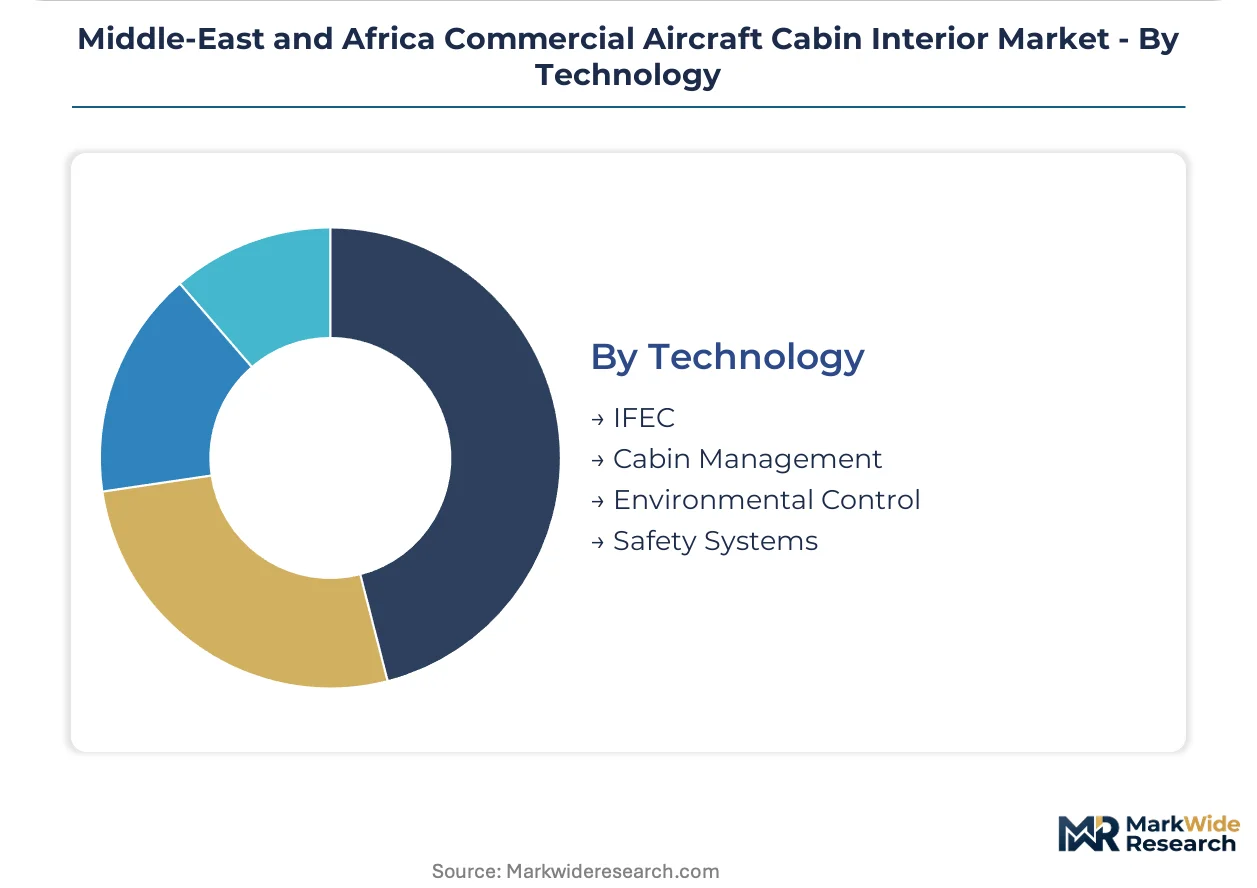
- IFEC:In-flight entertainment and connectivity platforms with immersive screens and streaming architecture differentiate premium cabins on long-haul routes connecting African hubs to European and Asian destinations.
- Cabin Management:Integrated LED control and environmental programming systems represent the fastest-expanding retrofit category as carriers seek fuel burn reduction through efficient architectures.
- Environmental Control:Air quality and thermal management systems maintain baseline comfort standards across high-density configurations favored by low-cost operators.
- Safety Systems:Oxygen deployment, emergency lighting, and evacuation equipment face mandatory replacement cycles tied to airworthiness directives from the UAE General Civil Aviation Authority and Saudi regulators.
Cabin Management is climbing the fastest as retrofit penetration deepens. IFEC retains margin concentration in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the region, with Gulf carriers least sensitive to price premiums for passenger experience differentiation, while African operators prioritize cost-efficient refurbishment cycles on aging fleets.
United Arab Emirates
Emirates and Etihad operate two of the world's largest wide-body cabin refresh programs, driving concentrated demand for lie-flat seating and programmable LED architectures. The UAE's General Civil Aviation Authority enforces supplemental flammability standards exceeding baseline FAA requirements. Dubai anchors the regional refurbishment hub with dedicated in-house engineering facilities managing multi-vendor integration.
Saudi Arabia
Saudi Arabia's General Authority of Civil Aviation tightened fire-safety material standards for thermoplastic composites, accelerating supplier R&D into advanced formulations. Emerging point-to-point low-cost operators favor high-density galley and lavatory systems optimized for rapid turnaround. Jeddah and Riyadh concentrate procurement authority as the kingdom expands point-to-point connectivity under its aviation sector transformation.
South Africa
South African carriers extend fleet lifecycles through phased cabin refresh programs, compressing replacement intervals for seating and lighting systems. The country's national aviation regulator references EASA Part 21 design approvals for type certification acceptance. Johannesburg concentrates MRO capabilities serving sub-Saharan operators with legacy wide-body platforms requiring electrical architecture reconciliation.
Egypt
Egyptian operators balance refurbishment investments against fleet modernization constraints, prioritizing IFEC upgrades and cabin management systems for competitive positioning on Europe-Middle East routes. Cairo's aviation cluster serves as a procurement coordination point for North African carriers. The national civil aviation authority maintains bilateral airworthiness recognition frameworks with Gulf regulators streamlining supplier qualification.
Middle-East and Africa Commercial Aircraft Cabin Interior Market Competitive Landscape
Capability concentration sits with integrated systems specialists; scale advantage sits with component-level fabricators serving high-volume retrofit cycles. The market structure tilts toward tiered specialization, with premium flagships demanding full-service integration while low-cost operators unbundle specifications. Two strategic archetypes dominate: integrated portfolio suppliers capturing bundled refurbishment contracts, and focused component specialists winning direct airline procurement. Competitive moves center on certification capacity expansion and regional M&A to secure Gulf hub proximity.
Within the integrated systems tier, Collins Aerospace and Safran exemplify full-cabin capability spanning seating, lighting, and galley architectures. RECARO Aircraft Seating GmbH & Co. KG occupies a focused position as a German GmbH specialist in lightweight certified structures. These three entities represent contrasting strategic postures: diversified integration versus targeted component excellence.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| RECARO Aircraft Seating GmbH & Co. KG |
| Panasonic Avionics Corporation |
| Diehl Aerospace GmbH |
| Adient Aerospace |
| Astronics Corporation |
| Jamco Corporation |
| Expliseat |
| Others |
Supply & Pricing Matrix
Specialized thermoplastic resin production concentrates in Germany and the United States, anchoring premium pricing power for fire-compliant cabin panels while aftermarket service contracts capture recurring margin pools from Gulf carrier retrofit programs. This upstream concentration forces procurement teams to negotiate long-term offtake agreements or absorb volatile feedstock pass-throughs.
Pricing Analysis
Aftermarket parts and refurbishment service contracts drive lifetime value as airlines extend fleet cycles through cabin refresh programs. Three-tier pricing structure across premium lie-flat seating, standard narrow-body configurations, and high-density economy products separates Collins Aerospace and Safran portfolios from regional fabricators. Cost compression in economy seating intensifies as Saudi low-cost carriers negotiate volume-scale discounts. Low-cost operators exhibit highest price sensitivity; Emirates and Etihad prioritize passenger experience ratings over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced composite manufacturing equipment limit supplier expansion outside established Western hubs. Component fabrication concentrates in Germany, France, and the United States, with specialized resin systems drawing from Belgian and Japanese chemical producers. Single-source vulnerability runs through concentrated thermoplastic fiber supply. Tier-1 integrators ship finished assemblies to Dubai and Jeddah refurbishment hubs through direct airline procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier procurement fragmentation is creating specialist niches as Emirates and Etihad unbundle traditional OEM contracts for direct supplier negotiation.
For Market Incumbents: Insulate certification capacity through expanded EASA Part 21 testing infrastructure in the UAE, defending against emerging Turkish and Chinese seating specialists. Backward integration into thermoplastic resin compounding secures margin control as Saudi fire-safety mandates tighten material specifications. For New Entrants and Emerging Players: Build out high-density galley and lavatory system capabilities targeting Saudi Arabia's point-to-point low-cost expansion. East African MRO hubs present the most penetrable geography given evolving bilateral airworthiness agreements with Gulf regulators. Partner with Dubai-based refurbishment facilities for qualification pathway acceleration. For Investors and Strategic Acquirers: Capital is best deployed toward component-level specialists with captive EASA certification and established airline direct relationships. The five-to-ten year viability window favors seating and lighting integrators over panel fabricators facing material commoditization. Monitor Saudi General Authority of Civil Aviation regulatory harmonization with EASA as inflection signal for supplier qualification barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Expansion | EASA Part 21 testing infrastructure in Dubai accelerates retrofit program approval timelines for Emirates. |
| Backward Integration into Resin Compounding | In-house thermoplastic formulation control insulates margin pools from petrochemical feedstock volatility. |
| Regional M&A in East Africa | Acquisition of Nairobi or Addis Ababa MRO capabilities streamlines certification for African bilateral agreements. |
| High-Density Product Line Launch | Galley and lavatory systems optimized for rapid turnaround capture Saudi low-cost carrier volume procurement. |
| Circadian Lighting Platform Integration | Programmable LED architectures with cabin management system integration differentiate long-haul Africa-Europe-Asia routes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with airline procurement directors, MRO operations managers, EASA certification engineers, and cabin interior product managers; and secondary validation through EASA type certificate databases, UAE General Civil Aviation Authority airworthiness directives, Saudi GACA regulatory filings, and customs trade data for thermoplastic composite imports. Bottom-up segmentation triangulation against top-down macro fleet projections anchored volume estimates.
Forecast inputs across the projection horizon incorporated seat replacement cycle compression, lighting retrofit penetration curves, and regulatory harmonization scenarios between Gulf and African states. Product type, material grade, end-user channel, and technology application dimensions structured the analytical framework. CAGRs derived from segment-level growth rate blending weighted by installed base turnover assumptions and new delivery schedules from Boeing and Airbus.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese seating manufacturers or accelerated EASA-Saudi regulatory convergence would shift outcomes. Material shifts in thermoplastic raw material sourcing geography or bilateral airworthiness agreement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Aircraft Galley Market